
 Sealant Web Films Market | 2026-2036
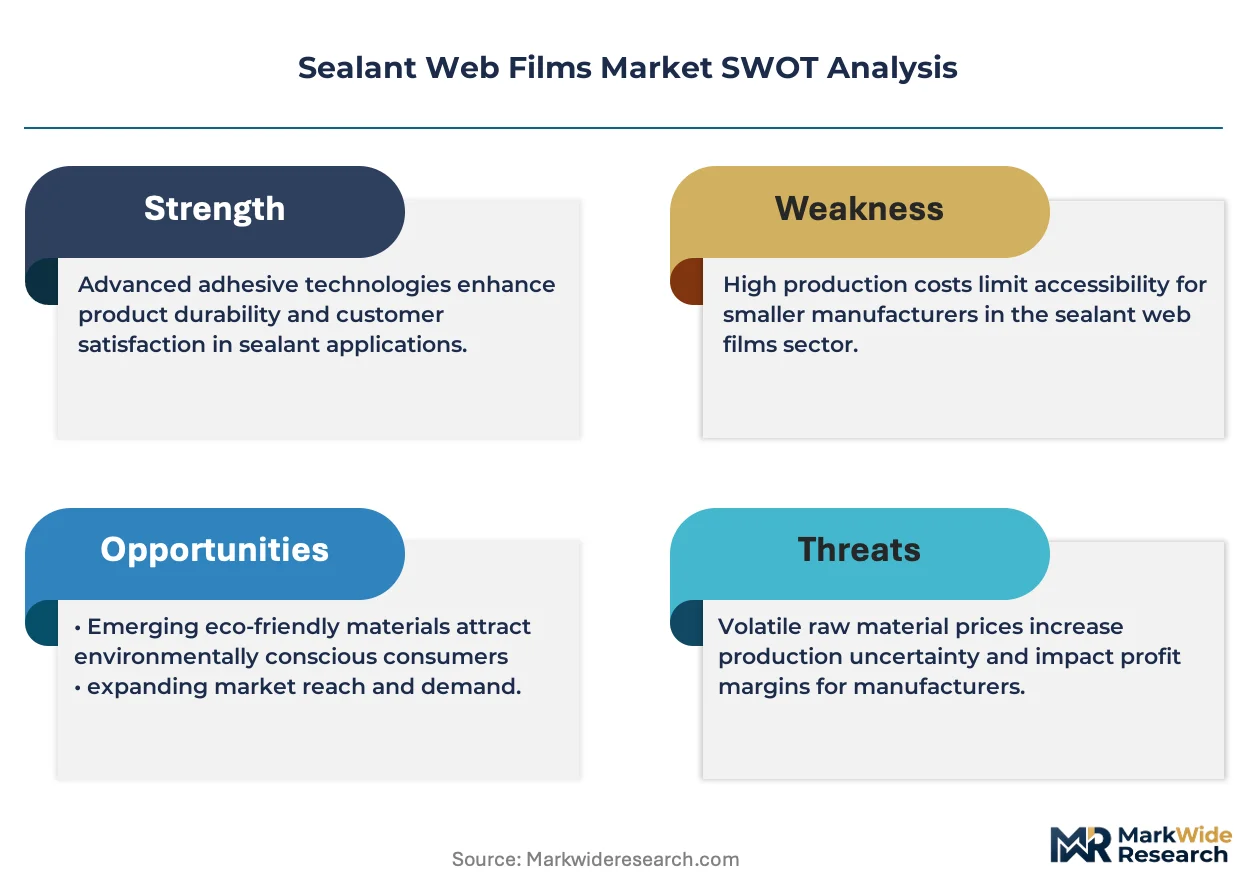
Sealant Web Films Market Size, Share, and Industry Trends Forecast 2026-2036
Sealant Web Films Market Outlook
Aftermarket technical service revenue for sealant film line integration and adhesive calibration is fragmenting across regional equipment distributors and resin compounders. Amcor plc leverages its blown film extrusion network across twelve countries to sustain global supply continuity for high-barrier sealant specifications. Toray Industries, Inc. anchors its position through biaxially oriented nylon and coextruded sealant technologies that dominate Asia-Pacific flexible packaging procurement. Berry Global Inc. competes via vertical control over polyethylene resin conversion into multi-layer sealant webs for hygiene and medical pouch applications.
Sealant web films are multi-layer polymeric laminates, typically 15 to 150 micrometers in thickness, engineered with heat-seal layers of metallocene polyethylene or ionomer resins that activate between 80°C and 160°C to form hermetic bonds. These structures serve primarily to enable reliable closure of flexible packages against moisture ingress, oxygen permeation, and microbial contamination across food, pharmaceutical, and industrial goods supply chains. Hot melt and moisture-curable product types capture expanding margin pools as converters abandon solvent-based systems to meet volatile organic compound restrictions. Packaging applications dominate volume absorption, while automotive interior lamination and electronics moisture barrier films represent faster-growing demand nodes with higher specification thresholds.
REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy metal stabilizers in sealant formulations, compelling reformulation toward bio-based tackifiers and maleic anhydride grafted polyolefins. The EPA in the United States enforces National Emission Standards for Hazardous Air Pollutants that limit solvent emissions from adhesive coating operations, pushing domestic manufacturers toward extrusion coating and thermal lamination platforms. China's GB standards and MEE enforcement on packaging recyclability are mandating mono-material polyethylene and polypropylene sealant constructions that displace complex multi-polymer laminates. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border packaging supply chains.
Market Dynamics
Europe's F-Gas Regulation and REACH compliance protocols are compressing the technology adoption window for solvent-free adhesive systems, forcing converters to abandon legacy coating platforms before amortization cycles complete.
Growth Catalysts
- REACH and RoHS frameworks:European restrictions on phthalate plasticizers and heavy metal stabilizers compel reformulation toward bio-based tackifiers and maleic anhydride grafted polyolefins, opening premium margin pools for compliant suppliers.
- Food sector shelf-life extension mandates:Flexible packaging converters in the food and pharmaceutical sectors are expanding sealant film procurement as hermetic closure requirements tighten against moisture ingress and oxygen permeation.
- Rhine-Ruhr industrial corridor concentration:Germany's clustering of major chemical film producers and packaging OEMs creates dense supplier networks that accelerate technical service response times and reduce qualification cycles for new sealant specifications.
Market Restraints
- Ethylene and propylene feedstock volatility:Polyolefin resin prices swing with naphtha-cracker economics, compressing converter margins and discouraging long-term contract commitments for sealant web volumes.
- Multi-polymer laminate complexity:China's GB standards and MEE enforcement on packaging recyclability are mandating mono-material polyethylene and polypropylene sealant constructions that strand existing multi-layer extrusion assets.
- Hot melt adhesive performance ceiling:Moisture-curable systems achieve superior bond strength on high-barrier substrates but require capital-intensive application equipment that mid-tier converters cannot justify.
Strategic Opportunities
- Automotive interior lamination:Electronics moisture barrier films and vehicle cabin acoustic laminates represent faster-growing demand nodes with higher specification thresholds and longer contract durations than commodity packaging.
- Solvent-free thermal lamination platforms:EPA National Emission Standards for Hazardous Air Pollutants in the United States are pushing domestic manufacturers toward extrusion coating equipment retrofits that create aftermarket service revenue streams.
- Mono-material pouch structures:Recyclable polyethylene sealant webs that displace complex laminates capture sustainability-linked procurement mandates from multinational food brands seeking circular packaging credentials.
Industry Challenges
- Adhesive calibration expertise scarcity:Aftermarket technical service for sealant film line integration fragments across regional equipment distributors and resin compounders, creating inconsistent commissioning quality and extended startup delays.
- Cross-border regulatory divergence:Stakeholders must monitor formulation compliance gaps between Europe's REACH protocols, China's GB standards, and United States EPA enforcement to avoid stranded inventory in international packaging supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sealant Web Films Market |
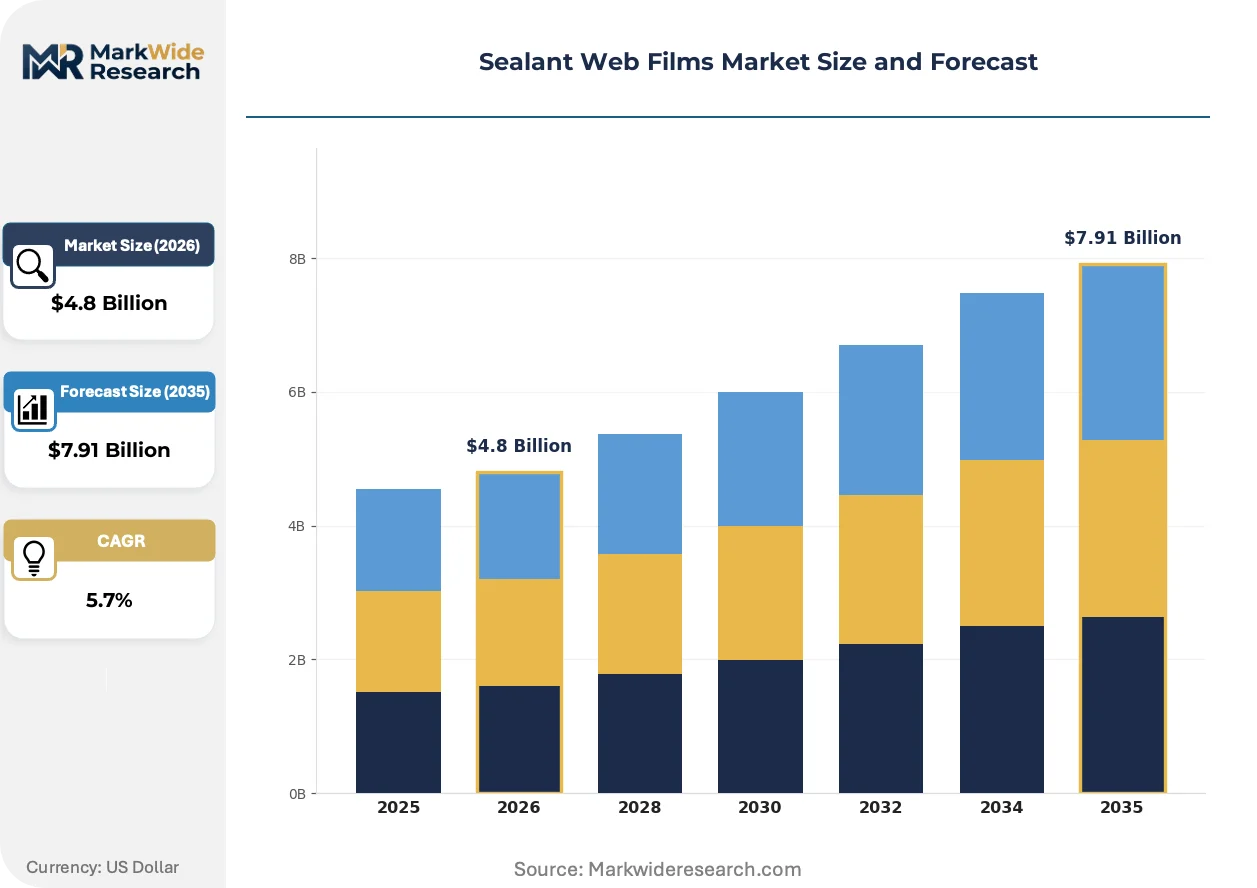
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Liquid, Hot Melt, Moisture-Curable Application: Construction, Automotive, Packaging, Electronics Material: Polyethylene, Polypropylene, Nylon, Rubber End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Toray Industries, Inc., Cosmo Films Ltd., Amcor plc, Jindal Poly Films Ltd., DIC Corporation, Berry Global Inc., Avery Dennison Corporation, UFlex Limited, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sealant Web Films Market Strategic Shifts
Active migration from solvent-based adhesive platforms toward thermal lamination and extrusion coating is restructuring converter capital allocation and equipment vendor order books across multiple geographies.
Metallocene polyethylene sealant layers are migrating from conventional Ziegler-Natta catalyzed resins in high-barrier food pouch specifications. Major European dairy and meat processors are specifying mPE sealants for their controlled atmosphere packaging lines to achieve hermetic seals at lower temperatures. This migration from legacy ionomer and EVA heat-seal layers is compressing the qualified supplier base to compounders with metallocene polymerization licensing.
Europe's F-Gas Regulation is accelerating the phase-down of hydrofluorocarbon blowing agents and solvent carriers in adhesive formulations. Industrial consequence includes stranded capital in solvent recovery systems and accelerated depreciation schedules for coating lines. German and French flexible packaging converters are responding fastest, with several Rhine-Ruhr facilities completing thermal lamination retrofits ahead of regulatory deadlines.
Buyer concentration among multinational food brands is consolidating sealant film procurement through direct mill relationships rather than distributor intermediaries. This disintermediation compresses converter margins but rewards compounders with technical service capabilities and global qualification documentation. The shift is most visible in North American and Western European markets where three to five brands control majority chilled and frozen food pouch volumes.
Sealant Web Films Market Segmentation
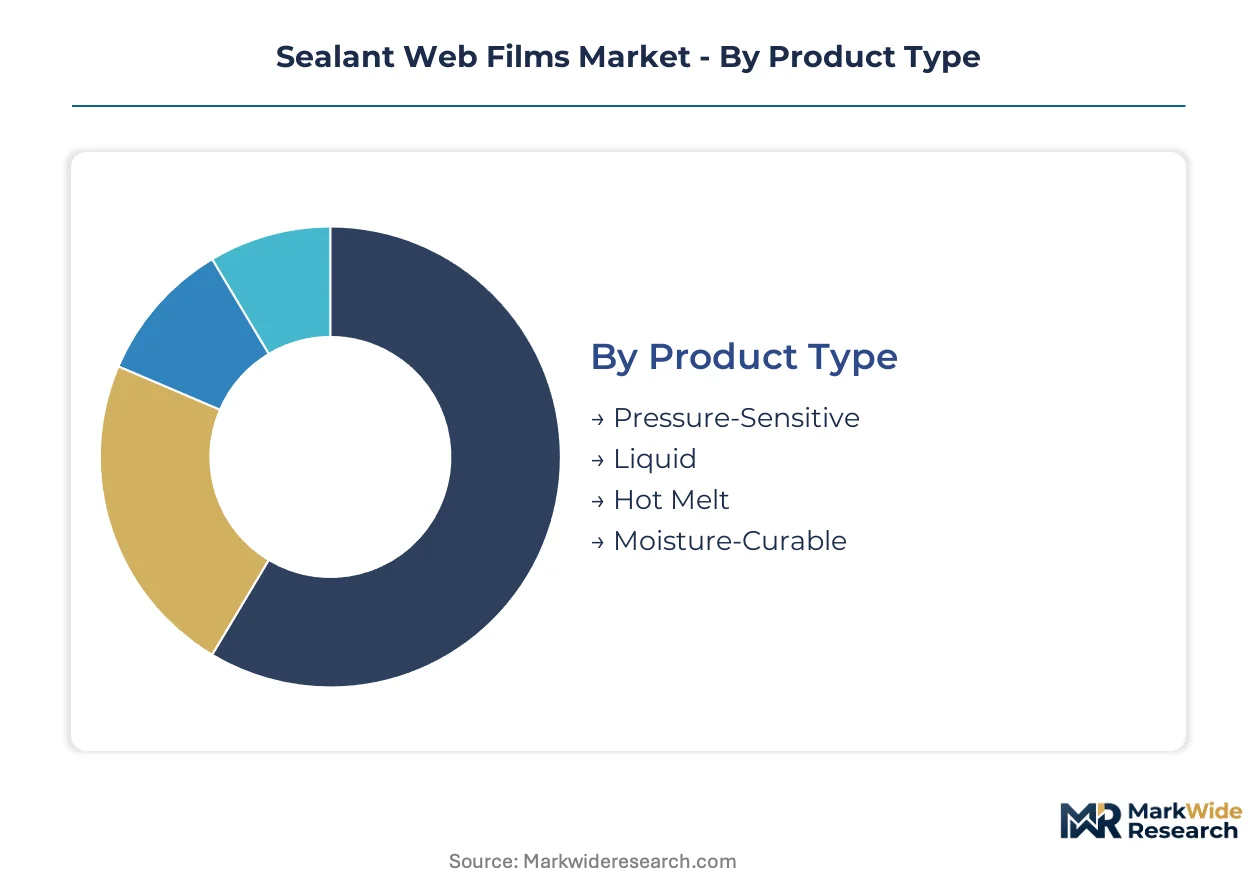
Sealant web films serve divergent performance requirements across adhesive chemistries, end-use environments, and material platforms. Procurement patterns fragment sharply between commodity packaging specifications and precision-engineered automotive or electronics barriers. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume absorbs price pressure.
Product Type:
Cost tier and regulatory compliance burden separate these adhesive platforms into distinct competitive arenas with diverging capital requirements and customer stickiness.
- Hot Melt:Thermoplastic formulations based on ethylene-vinyl acetate and metallocene polyethylene activate rapidly under heat without solvent carriers. European converters facing F-Gas Regulation deadlines are retrofitting coating lines toward these systems to eliminate volatile organic compound emissions. The technology captures expanding share in food packaging where hermetic seals must form at reduced temperatures.
- Moisture-Curable:Reactive polyurethane and silane-terminated polyether systems achieve superior bond strength on high-barrier substrates through ambient humidity crosslinking. Automotive interior lamination programs in Germany specify these grades for acoustic damping composites where peel strength requirements exceed 8 N/cm. Capital-intensive dispensing equipment limits adoption to tier-one suppliers with dedicated technical service teams.
- Pressure-Sensitive:Tackified acrylic and rubber-based films enable repositionable bonding without thermal activation.
- Liquid:Solvent-borne and water-based systems applied via roll coating or spray methods persist in construction membrane applications.
Hot melt commands the established base. The steepest expansion runs through moisture-curable systems.
Application:
Volume concentration and specification intensity create opposing poles in this dimension, with packaging absorbing tonnage while automotive and electronics extract premium pricing.
- Packaging:Flexible pouch and lidding applications dominate unit volume, with metallocene polyethylene sealant layers specified for controlled atmosphere meat and dairy formats. Germany's Rhine-Ruhr corridor hosts the densest converter concentration, where major chemical film producers co-locate with packaging OEMs to compress qualification cycles. Shelf-life extension mandates from multinational food brands are tightening hermetic closure specifications.
- Electronics:Moisture barrier films for display laminates and semiconductor packaging demand ultra-low water vapor transmission rates below 0.1 g/m²/day. Japan's METI efficiency standards and China's GB reliability protocols are converging on stricter barrier specifications that favor coextruded nylon-sealant constructions. Contract durations here exceed five years, insulating suppliers from resin price volatility.
- Construction:Roofing membrane and vapor barrier applications specify thicker gauge films with UV stabilization packages.
- Automotive:Interior acoustic laminates and exterior sealing tapes utilize high-tack formulations resistant to plasticizer migration.
Packaging absorbs the volume base. Electronics delivers the steepest margin expansion.
Material:
Recyclability mandates and catalysis licensing are restructuring competitive access across these polymer platforms.
- Polyethylene:Metallocene-catalyzed grades with narrow molecular weight distribution achieve hermetic seals at 80-100°C, reducing thermal stress on sensitive food contents. China's MEE enforcement on mono-material recyclability is displacing complex laminates in favor of all-polyethylene pouch structures. The shift strands multi-polymer extrusion assets while rewarding compounders with metallocene polymerization licensing.
- Nylon:Biaxially oriented polyamide 6 and coextruded sealant webs dominate Asia-Pacific high-barrier procurement for retort pouch and medical device packaging. Toray Industries anchors regional supply through integrated resin and film production. Oxygen transmission rates below 0.5 cc/m²/day qualify these specifications for pharmaceutical blister formats.
- Polypropylene:Oriented and cast grades serve twist-wrap and lidding applications requiring stiffness and clarity.
- Rubber:Styrene-butadiene and natural rubber tackifiers persist in pressure-sensitive construction tapes.
Polyethylene captures the sustainability-driven transition. Nylon retains the premium barrier position.
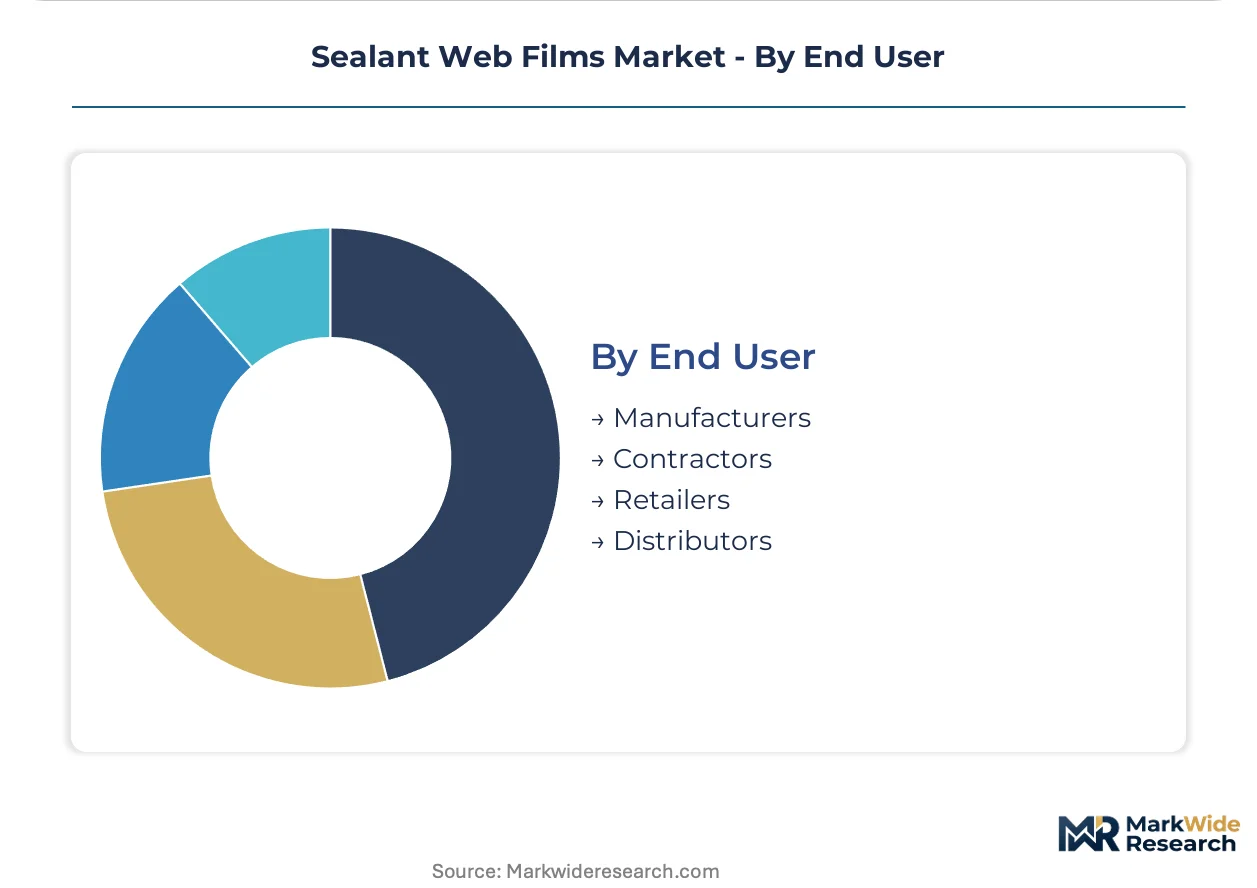
End User:
Channel structure and technical service requirements differentiate procurement behavior across these customer categories.
- Manufacturers:Brand-owning food, pharmaceutical, and electronics firms are consolidating sealant film procurement through direct mill relationships, eliminating distributor intermediaries. This disintermediation compresses converter margins but rewards compounders with global qualification documentation and technical calibration capabilities. Three to five multinational brands control majority chilled and frozen food pouch volumes in North America and Western Europe.
- Contractors:Construction and automotive installation specialists purchase through regional distributors with localized inventory and cut-to-width services.
- Retailers:Private-label packaging programs source through converter intermediaries rather than direct resin relationships.
- Distributors:Regional equipment and material distributors fragment aftermarket technical service for sealant film line integration.
Manufacturers anchor the value chain. Distributor technical service fragmentation creates the steepest capability gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing barrier performance and technical service over resin cost swings. Chinese and Indian converters face acute margin pressure from feedstock volatility, compressing procurement flexibility. United States demand sits mid-range, with EPA compliance costs partially offset by longer contract durations.
Germany
Rhine-Ruhr corridor converters specify metallocene polyethylene sealants for controlled atmosphere meat packaging, demanding hermetic closure at reduced thermal stress. ECHA's REACH enforcement restricts phthalate plasticizers, compelling reformulation toward maleic anhydride grafted polyolefins. Düsseldorf and Cologne host dense clusters of chemical film producers co-located with packaging OEMs, compressing qualification cycles for new specifications.
United States
Multinational food brands consolidate procurement through direct mill relationships, eliminating distributor intermediaries for chilled and frozen pouch volumes. EPA National Emission Standards for Hazardous Air Pollutants limit solvent emissions from adhesive coating operations, pushing manufacturers toward extrusion coating retrofits. Midwest flexible packaging converters around Chicago and Milwaukee are completing thermal lamination platform upgrades ahead of enforcement deadlines.
China
MEE enforcement on packaging recyclability mandates mono-material polyethylene and polypropylene sealant constructions, displacing complex multi-polymer laminates. GB standards on barrier reliability converge with METI-equivalent protocols for electronics moisture barrier films. Yangtze River Delta converters in Jiangsu and Zhejiang provinces are stranding multi-layer extrusion assets while scaling all-polyethylene pouch capacity.
Japan
Electronics moisture barrier films for display laminates and semiconductor packaging demand ultra-low water vapor transmission rates below 0.1 g/m²/day. METI efficiency standards tighten barrier specifications, favoring coextruded nylon-sealant constructions with contract durations exceeding five years. Kansai region compounders around Osaka anchor regional supply through integrated resin and film production.
India
Flexible packaging converters in food and pharmaceutical sectors expand sealant film procurement as shelf-life extension requirements tighten against moisture ingress. BIS standards on packaging safety and FSSAI mandates on food contact materials drive specification upgrades. Maharashtra and Gujarat host expanding blown film extrusion capacity serving domestic FMCG brands and export markets.
Sealant Web Films Market Competitive Environment
Capability concentration sits with integrated resin compounders possessing metallocene polymerization licensing; scale advantage sits with diversified packaging conglomerates operating across twelve-country extrusion networks. The vendor base separates into three archetypes: global film converters with captive technical service teams, regional specialists in high-barrier coextrusion, and resin compounders supplying qualified sealant formulations. Dominant competitive moves include thermal lamination equipment retrofits to meet F-Gas Regulation deadlines and backward integration into polyethylene resin production to hedge feedstock volatility.
Among Asia-Pacific integrated producers, Toray Industries, Inc. and Cosmo Films Ltd. occupy positions defined by biaxially oriented nylon and coextruded sealant technologies. Amcor plc exemplifies the global converter archetype through distributed blown film extrusion networks sustaining supply continuity for high-barrier specifications. These three entities represent distinct competitive vectors: resin-to-film integration, regional barrier specialization, and geographic scale dispersion.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Cosmo Films Ltd. |
| Amcor plc |
| Jindal Poly Films Ltd. |
| DIC Corporation |
| Berry Global Inc. |
| Avery Dennison Corporation |
| UFlex Limited |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr freight corridors linking Düsseldorf to Rotterdam port facilities transmit feedstock cost volatility directly into converter margin structures, while downstream price differentiation separates multinational food brands from regional distributors based on technical calibration capabilities and global qualification documentation.
Pricing Analysis
Aftermarket technical service revenue for sealant film line integration and adhesive calibration anchors lifetime value capture. Pricing stratifies across premium metallocene polyethylene formulations, standard ionomer heat-seal layers, and economy-grade EVA constructions. Cost compression in standard tiers intensifies because China's MEE enforcement strands multi-polymer extrusion assets. Regional distributors exhibit acute price sensitivity; multinational manufacturers with direct mill relationships prioritize barrier performance over resin cost swings.
Supply Chain Analysis
Export-control restrictions on advanced metallocene polymerization catalysts limit technology transfer to qualified compounders. Supply concentrates in Germany, Japan, and China, with raw material dependencies on naphtha-derived ethylene, propylene feedstocks, and maleic anhydride grafting agents. Single-source vulnerability runs through metallocene licensing concentration with select resin compounders. Distribution runs through converter direct procurement and regional equipment distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sealant web film incumbents face substitution pressure from mono-material all-polyethylene pouch structures displacing complex multi-polymer laminates under recyclability mandates.
For Market Incumbents: Harden technical service capabilities around solvent-free thermal lamination retrofits to defend against regional equipment distributors fragmenting aftermarket revenue. Secure captive metallocene polyethylene resin supply through backward integration into polymerization assets. ECHA's REACH enforcement on phthalate plasticizers threatens formulation portfolios lacking maleic anhydride grafted polyolefin alternatives. For New Entrants and Emerging Players: Mid-tier automotive interior lamination programs in Germany represent the most penetrable entry point, as tier-one suppliers with moisture-curable polyurethane systems cannot service smaller vehicle cabin acoustic contracts. Electronics moisture barrier films for display laminates offer second-mover opportunity where Japan's METI standards have consolidated supply with Toray and Cosmo. A technical service partnership with regional resin compounders bypasses capital-intensive dispensing equipment requirements. For Investors and Strategic Acquirers: Europe's F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward converters completing thermal lamination retrofits ahead of stranded asset risk. Long-term viability centers on compounders with integrated metallocene polymerization licensing and global qualification documentation spanning REACH, EPA, and GB standards. Monitor MEE enforcement intensity in China's Yangtze River Delta as the signal for mono-material polyethylene capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Lamination Retrofit | Rhine-Ruhr converters completing equipment upgrades ahead of F-Gas Regulation deadlines capture stranded competitor volumes. |
| Backward Integration into Resin | Captive metallocene polyethylene production hedges naphtha-cracker feedstock volatility compressing converter margins. |
| Mono-Material Pouch Qualification | All-polyethylene sealant webs aligned with China's MEE recyclability mandates secure multinational food brand procurement. |
| Moisture-Curable Adoption | Polyurethane systems for German automotive acoustic laminates achieve peel strength thresholds exceeding 8 N/cm. |
| Technical Service Network Expansion | Direct mill relationships with calibration capabilities disintermediate regional distributors fragmenting aftermarket revenue. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and chemical industry association reports. Primary interviews engaged flexible packaging converters, resin compounder technical directors, and automotive Tier 1 procurement leads across Germany, the United States, China, and Japan. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis and capacity announcements.
Forecast inputs include adhesive chemistry migration rates, metallocene polyethylene adoption curves, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions span product type, application, material platform, and end-user channel structure. CAGRs derive from regression analysis against historical resin price elasticity and converter capital expenditure cycles. Industry-specific inputs incorporate ECHA REACH enforcement timelines and EPA National Emission Standards compliance cost curves.
Practitioners should monitor regulatory divergence between Europe's F-Gas phase-down, China's MEE recyclability mandates, and United States EPA enforcement for early signals of cross-border inventory stranding. Forecasts reflect assumptions on metallocene catalyst licensing concentration and thermal lamination retrofit completion rates. Material shifts in naphtha-cracker economics or breakthrough mono-material barrier performance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Barrier Tube Packaging Market