
 Global Silicone Release Liner Market | 2026-2036
Global Silicone Release Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Release Liner Market Outlook
Market Context with Strategic Players
The gap between premium fluorosilicone liners and commodity-grade kraft-based alternatives is repositioning procurement criteria across automotive and electronics supply chains. 3M Company leverages its captive polymer science capabilities to dominate high-temperature adhesive transfer applications where liner consistency dictates yield rates. Sappi Limited anchors European demand through integrated pulp-to-release-paper manufacturing at its specialty mills. Mondi Group competes on coated substrate customization, extending its converting partnerships into medical and hygiene segments where lot traceability requirements favor integrated suppliers.
Technical Definition and Structural Segments
A silicone release liner is a carrier substrate—typically glassine, supercalendered kraft, or polyolefin film—coated with a cross-linked polydimethylsiloxane layer that delivers controlled release force measured in grams per inch against pressure-sensitive adhesives. Its primary industrial purpose is to protect adhesive surfaces during lamination, die-cutting, and transport while enabling clean, predictable separation at the point of application. Permanent liners for industrial tape and automotive bonding command the deepest margin pools due to silicone cure chemistry complexity and qualification timelines, while water-based coating technology is displacing solvent-based systems under emissions regulations. Medical applications in diagnostics and transdermal delivery represent the fastest-growing segment as healthcare end users demand lot-controlled, extractables-tested substrates.
Regulatory Frame and Forward-Looking Close
REACH in Europe restricts volatile organic compound migration from silicone coatings, while FDA biocompatibility guidance governs liner-to-skin contact applications in the United States; China's GB standards for food-contact materials further constrain substrate and silicone purity for packaging converters. Japan's PMDA and METI coordinate medical device material registrations that delay market entry for uncertified liner suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated release chemistries face substitution pressure that will redirect R&D spending toward plasma-treated silicone alternatives.
Market Dynamics
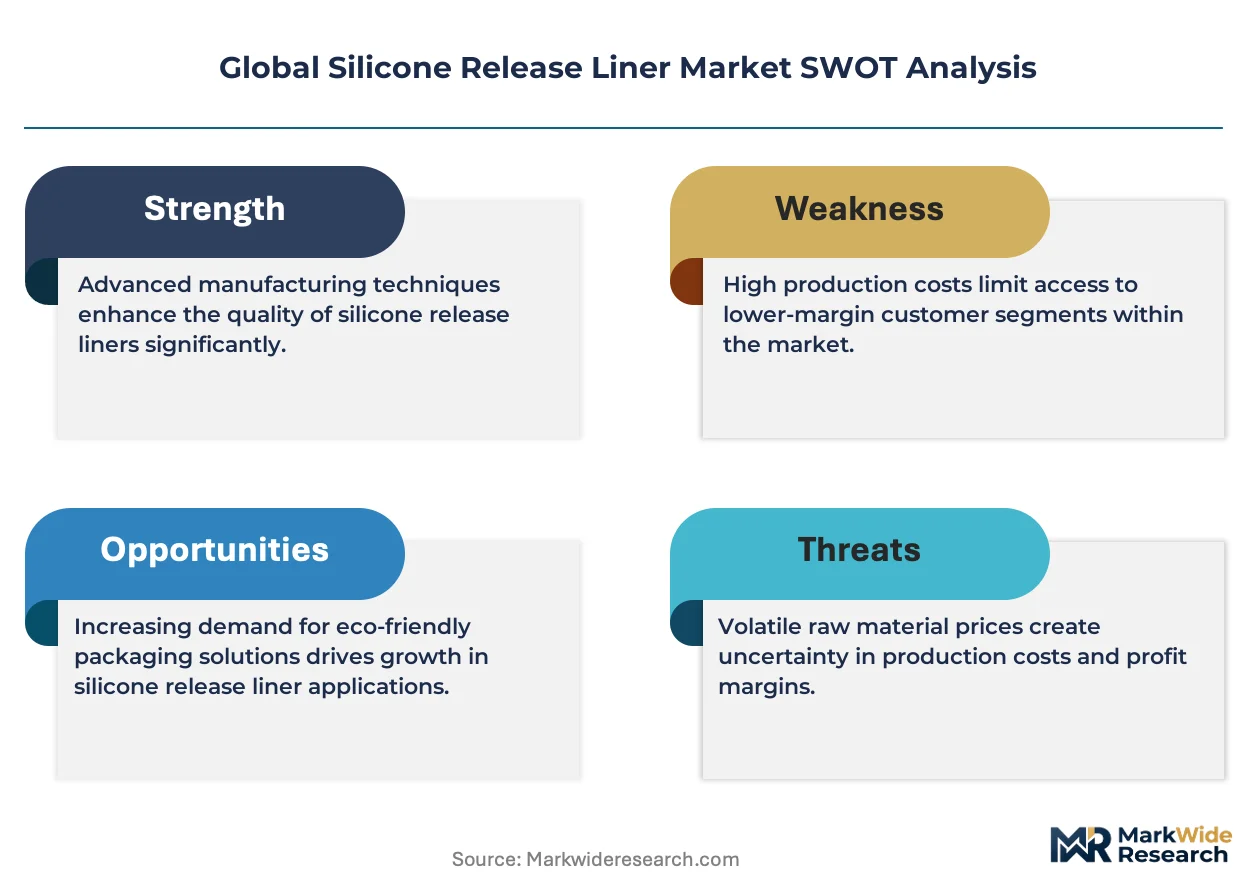
Water-based silicone coating chemistry is displacing solvent-cured systems across European and North American converting operations, driven by REACH VOC limits and EPA air quality enforcement. This shift compresses cure cycle throughput while elevating capital requirements for coating line retrofits.
Growth Catalysts
- EU MDR biocompatibility mandates:Medical device manufacturers in Germany and Switzerland now require extractables-tested liners for transdermal patches, pulling premium substrate volumes through qualified supply chains.
- Automotive lightweighting programs:Pressure-sensitive adhesive bonding for composite panels in electric vehicle assembly is expanding silicone release liner consumption at German and South Korean OEMs.
- Fluorosilicone thermal stability:High-temperature adhesive transfer tapes for aerospace and battery thermal management now specify fluorosilicone release chemistries with service thresholds above 200°C.
Market Restraints
- Specialty kraft pulp concentration:Supercalendered kraft supply for glassine substitutes concentrates in Nordic pulp mills, exposing converters to energy cost volatility and freight disruption.
- Silicone raw material oligopoly:Polydimethylsiloxane precursor production clusters in Germany, China, and the United States, creating geographic concentration risk for coating operations elsewhere.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit PFAS content threaten fluorosilicone release coatings, forcing reformulation investments before alternatives achieve equivalent release profiles.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO compliance requirements for drug-contact materials are accelerating demand for certified silicone release liners at domestic and multinational converters near Mumbai and Hyderabad.
- Plasma surface treatment:Atmospheric plasma activation of polyolefin films is expanding into release liner substrates, enabling silicone anchoring without solvent-based primers and opening PET recycling pathways.
- Japan medical device registration:PMDA lot traceability requirements favor integrated liner suppliers with captive coating and slitting capabilities, creating entry barriers for merchant substrate producers.
Industry Challenges
- Cross-linked silicone formulation expertise:Coating chemists capable of tuning release force across medical, industrial, and electronics specifications remain scarce in emerging converting clusters.
- Qualification timeline compression:Automotive OEMs now demand 12-month liner validation cycles for adhesive bonding applications, down from 24-36 months, straining R&D throughput.
- Legacy solvent coating asset stranding:Converters with substantial solvent-based infrastructure face accelerated depreciation as water-based and UV-cure systems achieve performance parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Release Liner Market |
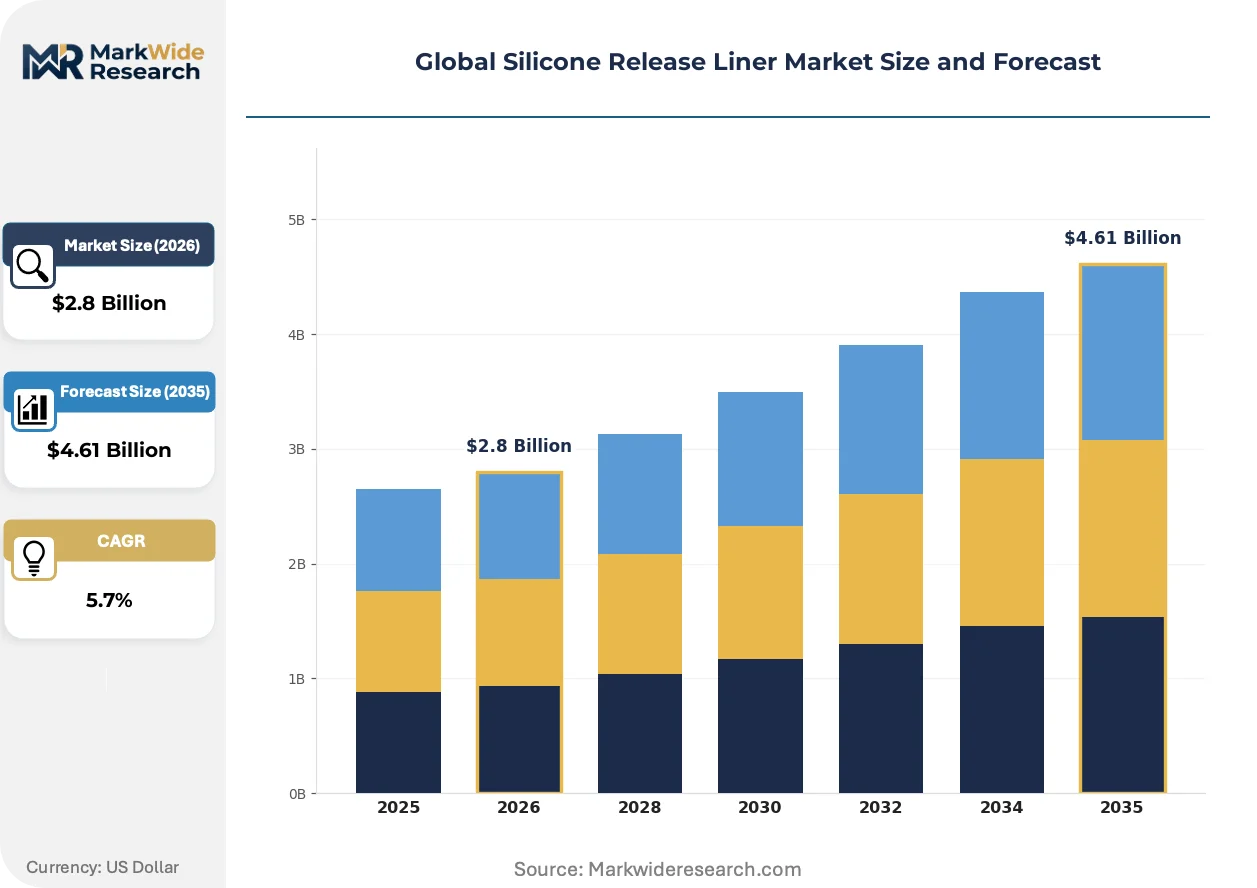
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Temporary, Coated, Uncoated Application: Tape, Labels, Medical, Graphics End User: Healthcare, Packaging, Automotive, Electronics Technology: Solvent-Based, Water-Based, Hot Melt, Others |
| Companies Covered | Lintec Corporation, Polyplex Corporation, 3M Company, Sappi Limited, UPM, Mondi Group, Loparex, Gascogne, Ahlstrom-Munksjö, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Release Liner Market Strategic Shifts
Silicone release liner technology is bifurcating between commodity kraft substrates and engineered films with functional coatings. This divergence is reshaping R&D allocation, capital deployment, and partnership structures across the value chain.
Electron-beam cured silicone coatings are expanding into high-speed converting operations where thermal cure ovens create bottlenecks. Medical tape manufacturers in Germany and the United States are adopting e-beam systems to achieve instant cure without residual volatiles. This technology is expanding into food-contact and diagnostic applications where extractables limits are tightening.
REACH Annex XVII restrictions on siloxane migration are compelling coating formulators to validate low-migration cure chemistries for skin-contact applications. ECHA enforcement actions against non-compliant medical device components have accelerated third-party testing adoption. European wound care and transdermal delivery segments are responding by consolidating supplier qualification lists around integrated mills with in-house analytical capabilities.
Direct mill-to-converter digital procurement platforms are compressing distributor margins in standard-grade liner categories. Large automotive and hygiene OEMs in the United States and Germany now contract directly with Sappi and Mondi for volume commitments, bypassing regional merchants. This channel shift is most visible in hygiene applications where specification standardization enables automated tendering and just-in-time inventory transfers.
Global Silicone Release Liner Market Segmentation
Silicone release liner procurement decisions pivot on release force precision, regulatory compliance tier, and substrate customization depth. Buyers segment suppliers by cure chemistry capability, lot traceability infrastructure, and qualification timeline flexibility.
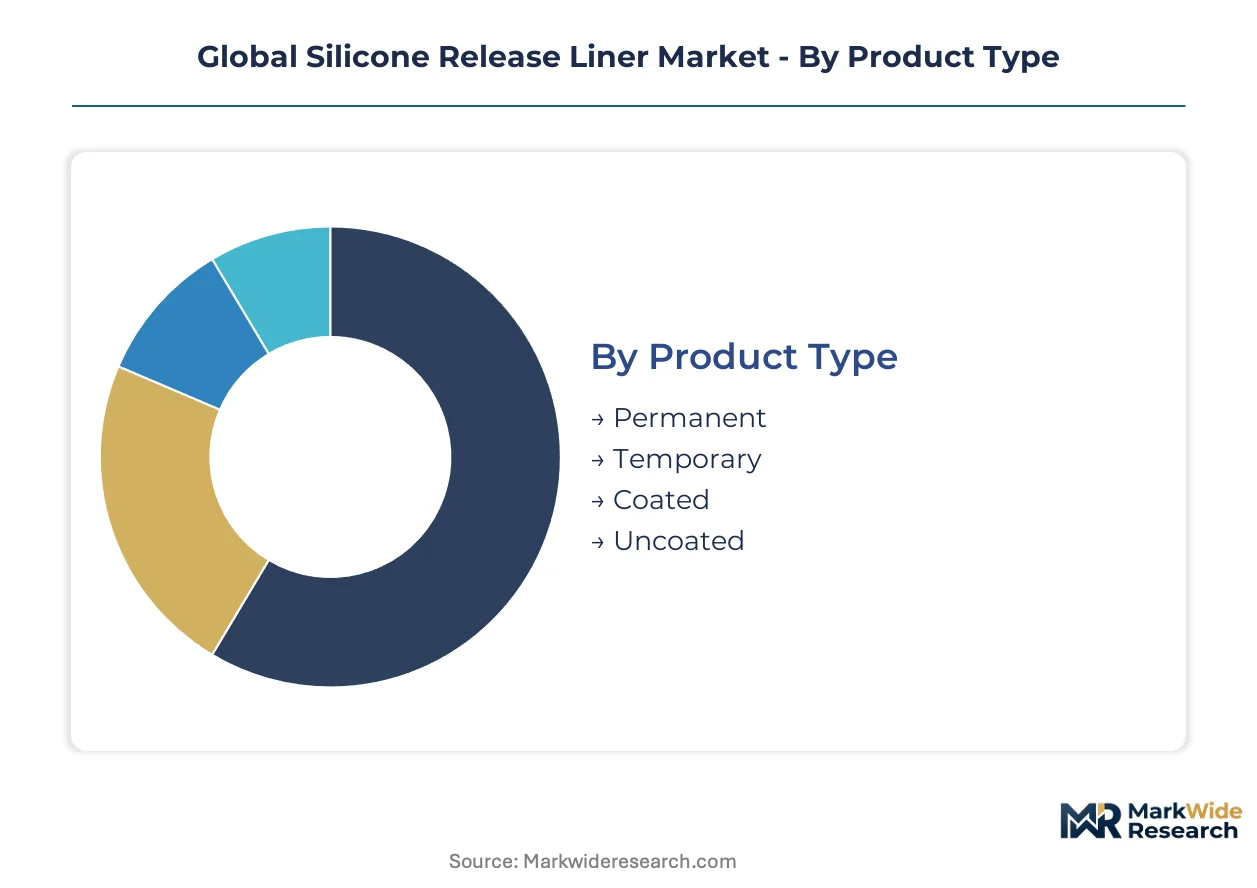
Product Type:
Buyers select product types based on adhesive permanence requirements and surface protection duration against total cost of ownership.
- Permanent:Cross-linked silicone coatings deliver controlled release force for industrial bonding and automotive assembly tapes. German OEMs specify permanent liners for electric vehicle composite panel bonding, where liner consistency directly impacts adhesive transfer yield rates.
- Temporary:Lower-release formulations protect pressure-sensitive adhesives during die-cutting and transport. Medical device manufacturers in Switzerland and the United States favor temporary liners for diagnostic strip production, where clean separation prevents adhesive contamination.
- Coated:Substrates with applied silicone layers dominate high-value applications requiring precise release profiles.
- Uncoated:Virgin glassine or kraft papers serve cost-sensitive industrial masking and short-cycle packaging.
Permanent liners lead on scale; temporary liners lead on momentum.
Application:
Application selection tracks end-use performance thresholds, from industrial durability to biocompatibility certification.
- Tape:Industrial and consumer adhesive tapes require liners with stable release force across temperature and humidity extremes. Automotive OEMs in South Korea specify tape-grade liners for battery thermal management systems.
- Labels:Pressure-sensitive label stocks demand thin, dimensionally stable substrates for high-speed dispensing. Food-contact label converters in Italy face EFSA migration limits that favor water-based silicone coatings.
- Medical:Wound care, transdermal patches, and diagnostic strips require extractables-tested substrates with lot-controlled silicone purity. FDA biocompatibility guidance and EU MDR compliance are compressing qualified supplier lists around integrated mills with captive coating capabilities.
- Graphics:Large-format adhesive films for signage and vehicle wraps use heavyweight liners with anti-curl properties.
Tape commands volume concentration; medical climbs the fastest.
End User:
End-user procurement patterns diverge by regulatory stringency, volume scale, and specification customization requirements.
- Healthcare:Medical device and pharmaceutical packaging buyers enforce CDSCO, FDA, and EMA material standards. Transdermal patch manufacturers in Germany and the United States now mandate third-party extractables documentation.
- Packaging:Food-contact and consumer goods converters prioritize cost efficiency and supply security. China's GB standards for food-contact materials constrain silicone purity specifications for export-oriented packaging producers.
- Automotive:Electric vehicle lightweighting programs are expanding pressure-sensitive adhesive bonding for composite structures. OEMs in Germany and South Korea specify fluorosilicone release chemistries with thermal thresholds above 200°C.
- Electronics:Flexible circuit and display assembly applications demand ultra-clean liners with low particulate generation.
Packaging leads on scale; healthcare leads on margin expansion.
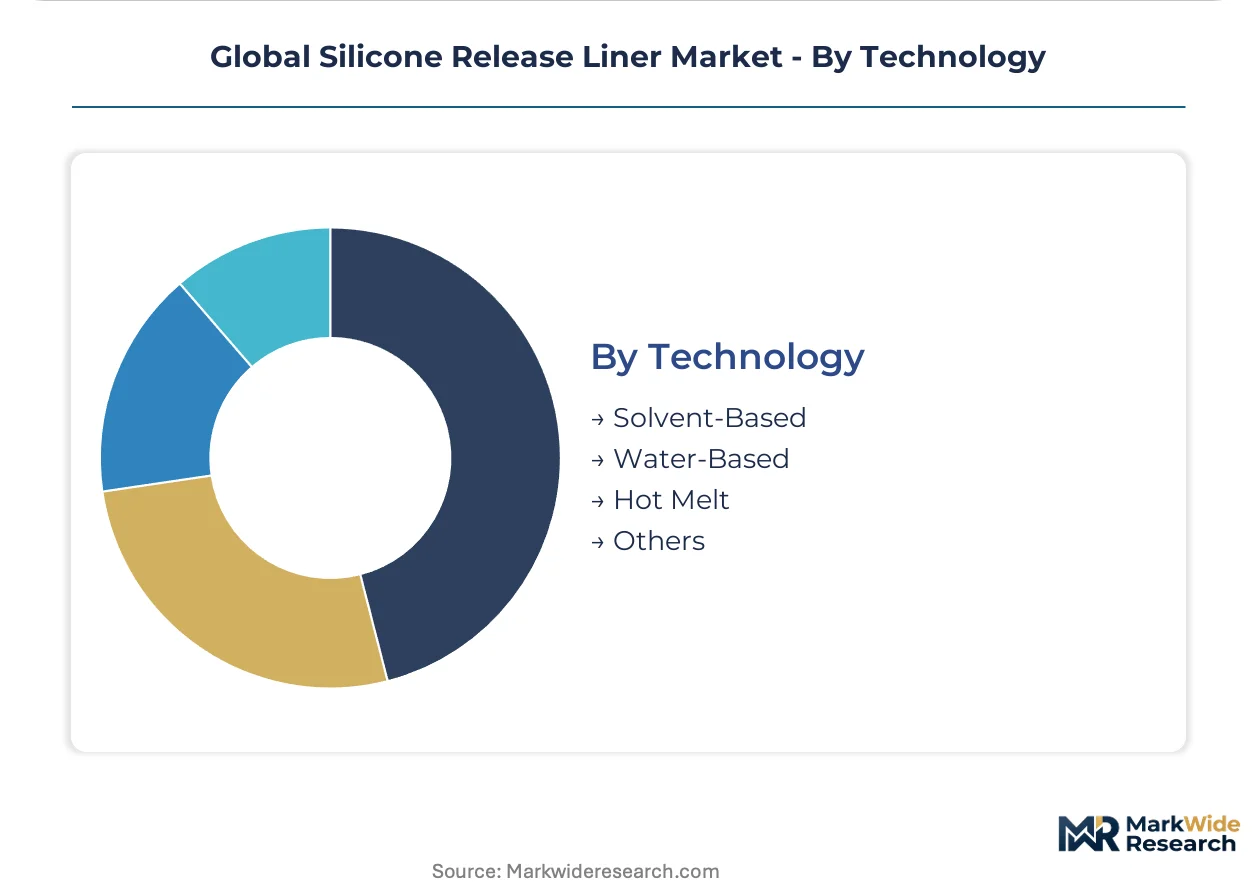
Technology:
Technology adoption reflects emissions compliance pressure, cure cycle throughput, and capital retrofit feasibility.
- Solvent-Based:Traditional thermal cure systems deliver optimal silicone anchoring and release profile consistency. REACH VOC limits and EPA air quality enforcement are stranding legacy coating assets across European and North American operations.
- Water-Based:Emulsion silicone coatings eliminate volatile organic compound emissions but compress cure cycle throughput. Converters in Germany and the United States are retrofitting lines to meet ECHA and state-level air quality mandates.
- Hot Melt:Solventless silicone application enables high-speed coating without thermal cure ovens.
- Others:Electron-beam and UV-cure systems serve niche medical and food-contact applications where residual volatiles are prohibited.
Solvent-based retains installed base dominance; water-based gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating chemists and precision converting engineers concentrate in German industrial clusters, anchoring European supply chains for medical-grade and automotive silicone release liner specifications.
Germany
Electric vehicle OEMs in Baden-Württemberg and Bavaria specify fluorosilicone release chemistries for composite panel bonding applications. EU MDR biocompatibility mandates from EMA tighten extractables documentation requirements for transdermal patch manufacturers. Stuttgart and Munich precision converting clusters now demand 12-month qualification cycles, compressing supplier R&D timelines.
United States
FDA biocompatibility guidance drives lot-controlled silicone purity requirements for wound care and diagnostic strip producers. EPA air quality enforcement accelerates water-based coating retrofits across Ohio and Wisconsin converting operations. The Midwest industrial corridor hosts integrated mills serving automotive OEMs with permanent liner specifications for adhesive transfer tapes.
China
GB standards for food-contact materials constrain silicone migration limits for export-oriented packaging converters. NMPA medical device registrations delay market entry for uncertified liner suppliers in transdermal delivery segments. Yangtze River Delta coating operations face dual carbon goals from MEE, elevating capital requirements for emissions-compliant curing systems.
Japan
PMDA lot traceability requirements favor integrated suppliers with captive coating and slitting capabilities in medical device applications. METI coordinates material registrations that create entry barriers for merchant substrate producers. Kanto and Kansai industrial zones concentrate electron-beam curing adoption for instant-cure medical tape manufacturing.
India
CDSCO compliance requirements for drug-contact materials accelerate demand for certified silicone release liners at pharmaceutical packaging converters. Domestic and multinational operations near Mumbai and Hyderabad expand water-based coating capacity to meet state-level air quality mandates. Maharashtra and Telangana precision converting clusters now serve both domestic healthcare demand and export markets.
Global Silicone Release Liner Market Competitive Environment
Capital-heavy producers compete with asset-light designers across coating chemistry and substrate customization tiers. The vendor base stratifies between integrated pulp-to-paper mills with captive silicone coating lines and specialized converters sourcing merchant substrates. Three archetypes dominate: integrated forestry-chemical conglomerates with backward polymer control; mid-scale coating specialists serving medical and automotive qualification channels; and regional substrate merchants competing on freight proximity and lot flexibility. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with coating line retrofits for water-based chemistry attracting joint venture structures.
Within the integrated forestry-chemical tier, Sappi Limited and Mondi Group exemplify backward integration into specialty pulp and controlled-release silicone chemistry. UPM anchors Nordic supply security for supercalendered kraft substrates. 3M Company occupies a distinct position bridging captive polymer science with high-temperature adhesive transfer applications. These players represent the concentration of qualification infrastructure and regulatory documentation capabilities that medical device and automotive OEMs now mandate.
| Leading Market Players |
|---|
| Lintec Corporation |
| Polyplex Corporation |
| 3M Company |
| Sappi Limited |
| UPM |
| Mondi Group |
| Loparex |
| Gascogne |
| Ahlstrom-Munksjö |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists across Germany and Japan anchor pricing discipline through long-term pulp supply contracts and captive silicone formulation expertise, insulating premium tiers from commodity volatility while compressing margins at unintegrated converters dependent on spot substrate markets.
Pricing Analysis
Bundled coating-and-certification packages command substantial premiums over unbundled substrate-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical grades from industrial tape specifications and cost-sensitive packaging substrates. Price differentiation hinges on extractables documentation depth and lot traceability infrastructure. Cost compression in standard-grade kraft liners is intensifying because direct mill-to-OEM procurement platforms are eliminating distributor markups. Hygiene and packaging converters exhibit highest price sensitivity; automotive and medical device manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Certification and qualification gating concentrates qualified supply among integrated mills with captive analytical laboratories and EMA/FDA submission experience. Geographic supply concentration centers on Germany, China, and the United States for polydimethylsiloxane precursor production, with Nordic pulp mills anchoring supercalendered kraft substrate supply. Raw material dependencies rest on silicone monomer feedstocks, specialty pulp grades, and fluorinated release chemistries facing ECHA substitution pressure. Single-source vulnerability runs through German silicone oligopolists and Nordic energy-intensive pulp operations. Distribution runs through direct mill contracts for volume automotive and hygiene OEMs, with regional merchants serving fragmented converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: water-based coating retrofits in Germany and the United States carry capital burdens three to four times higher than equivalent compliance investments in India, where CDSCO certification simultaneously unlocks pharmaceutical export pathways.
For Market Incumbents: Extend qualification infrastructure into electron-beam and UV-cure coating technologies before water-based performance parity eliminates solvent-based asset value entirely. Deepen backward integration into silicone monomer supply through offtake agreements with German and Chinese precursor producers, defending against raw material oligopoly pricing power. Prioritize captive analytical capabilities for extractables testing as EU MDR documentation requirements compress qualified supplier lists. For New Entrants and Emerging Players: The premium-to-economy price-point gap in medical-grade temporary liners offers entry space for plasma-treated polyolefilm substrates without fluorosilicone thermal thresholds. Target Indian pharmaceutical packaging converters near Mumbai and Hyderabad, where CDSCO compliance investments create switching costs favoring first-mover certifiers. Pursue joint venture structures with established coating specialists to bypass 12-month automotive qualification timelines. For Investors and Strategic Acquirers: Specialty chemical conglomerates with medical device material portfolios are the most active acquirer in this space, seeking coating capabilities to complement adhesive and polymer science assets. The five-to-ten year viability window favors integrated mills with captive pulp supply and water-based coating retrofit completion. Acquisition target archetype: mid-scale European coating specialists with EMA-validated extractables protocols and stranded solvent assets suitable for electron-beam conversion. Monitor ECHA PFAS restriction implementation timelines as inflection indicator for fluorosilicone substitution R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Retrofit | REACH VOC compliance protects European market access for German and US converters. |
| Electron-Beam Cure Adoption | Instant-cure technology eliminates residual volatiles for FDA medical tape submissions. |
| Backward Integration into Silicone Monomers | Captive precursor supply insulates margins from German-Chinese oligopoly pricing. |
| CDSCO Certification Investment | Indian pharmaceutical packaging demand accelerates for extractables-tested liner suppliers. |
| Plasma Surface Treatment Scale-Up | Atmospheric plasma enables PET recycling pathways without solvent-based primers. |
Study Parameters
Multiple input streams — technical interviews with coating chemists and precision converting engineers, procurement discussions with automotive and medical device OEMs, and regulatory validation with EMA and FDA compliance officers — were reconciled against secondary sources including ECHA restriction proposals, SEC filings from integrated forestry-chemical conglomerates, and trade data from European and North American pulp associations. Bottom-up volume estimates from coating line capacity and utilization rates were triangulated against top-down demand projections from adhesive tape and medical device production forecasts.
Historical growth patterns were cross-referenced against panel input from industry stakeholders to establish baseline assumptions across the projection horizon. Segmentation dimensions modeled include substrate type, cure chemistry technology, application end-use, and regional regulatory compliance tier. CAGRs were derived from weighted average growth across these segments, incorporating electric vehicle lightweighting program timelines, EU MDR implementation phases, and pharmaceutical packaging expansion trajectories in India as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electron-beam and UV-cure coating penetration would alter the outlook if water-based systems fail to achieve equivalent release profile consistency. Forecasts reflect assumptions regarding ECHA PFAS restriction timing, automotive qualification cycle compression sustainability, and Nordic pulp supply security. A model refresh is warranted upon material change in REACH Annex XVII enforcement intensity or fluorosilicone substitution technology breakthrough.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Lining Market