
 Sealant Films Market | 2026-2036
Sealant Films Market Size, Share, and Industry Trends Forecast 2026-2036
Sealant Films Market Analytics
Asset-light leasing models for coextrusion lines are rewriting competitive entry economics in sealant films. Amcor leverages its backward integration into resin compounding to sustain margin control across polyethylene and polypropylene grades. Berry Global anchors North American supply through multi-site blown film operations serving food packaging converters. UFlex competes on cost structure from its Indian manufacturing base, exporting rolls and pouches to Middle Eastern and African markets.
Sealant films are multilayer polymer structures engineered to bond dissimilar substrates under heat and pressure, typically achieving seal strengths of 15-40 N/15mm depending on resin grade and coextrusion architecture. Their primary commercial purpose is to create hermetic closures that prevent moisture ingress, oxygen transmission, and microbial contamination in packaged goods. Polyethylene formulations dominate volume due to their balance of seal initiation temperature and hot-tack performance, while coextruded film technology captures premium pricing through tailored barrier stacks for medical and automotive applications. Pouch and bag forms are gaining share as e-commerce fulfillment drives demand for unitized, shelf-ready packaging formats.
REACH registration requirements and EU MDR compliance for medical-grade films are elevating testing burdens and documentation costs for European market access. FDA food-contact notifications and EPA resin precursor rules shape formulation choices in the United States, particularly for recycled content incorporation. China's GB standards and SAMR packaging safety directives impose parallel conformity obligations for imported films. Stakeholders must monitor regulatory divergence between jurisdictions to avoid dual-certification costs that erode cross-border competitiveness.
Market Dynamics
Coextrusion technology maturation is compressing the cost premium between commodity polyethylene sealants and engineered multilayer barrier films, forcing converters to reposition on formulation expertise rather than equipment scale alone.
Growth Catalysts
- E-commerce fulfillment surge:Unitized pouch formats for last-mile delivery are pulling demand for high-clarity, puncture-resistant sealant structures across food and consumer goods channels.
- EU MDR compliance deadlines:Medical device packaging mandates for traceability and sterility assurance are accelerating qualification of coextruded barrier films for pharmaceutical applications.
- China's domestic coextrusion buildout:Local converters in Jiangsu and Guangdong provinces are scaling capacity for medical and industrial end uses, reducing import dependence.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing swings compress margin predictability for polyethylene-dominant formulations.
- Specialty resin supply concentration:Ionomer and metallocene polyethylene supply chains concentrate among a handful of global polymer producers, creating bottleneck risk.
- Hot-tack performance ceiling:Current polyethylene ionomer blends face thermal limits in high-speed form-fill-seal applications above 400 pouches per minute.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates for export-oriented drug products are opening specification windows for multilayer barrier sealants with tamper-evident functionality.
- Mechanical recycling integration:FDA food-contact notifications for post-consumer recycled polyethylene are enabling closed-loop supply structures for quick-service restaurant packaging.
- Digital print compatibility:Water-based ink adhesion on sealant surfaces is converging with coextrusion surface treatment advances, unlocking short-run customization for regional brands.
Industry Challenges
- Coextrusion die design expertise:Five to seven layer architectures require rheological modeling capabilities scarce among mid-tier converters.
- Dual-certification burden:Parallel REACH registration and FDA food-contact notification timelines stretch product launch cycles by 18-24 months for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sealant Films Market |
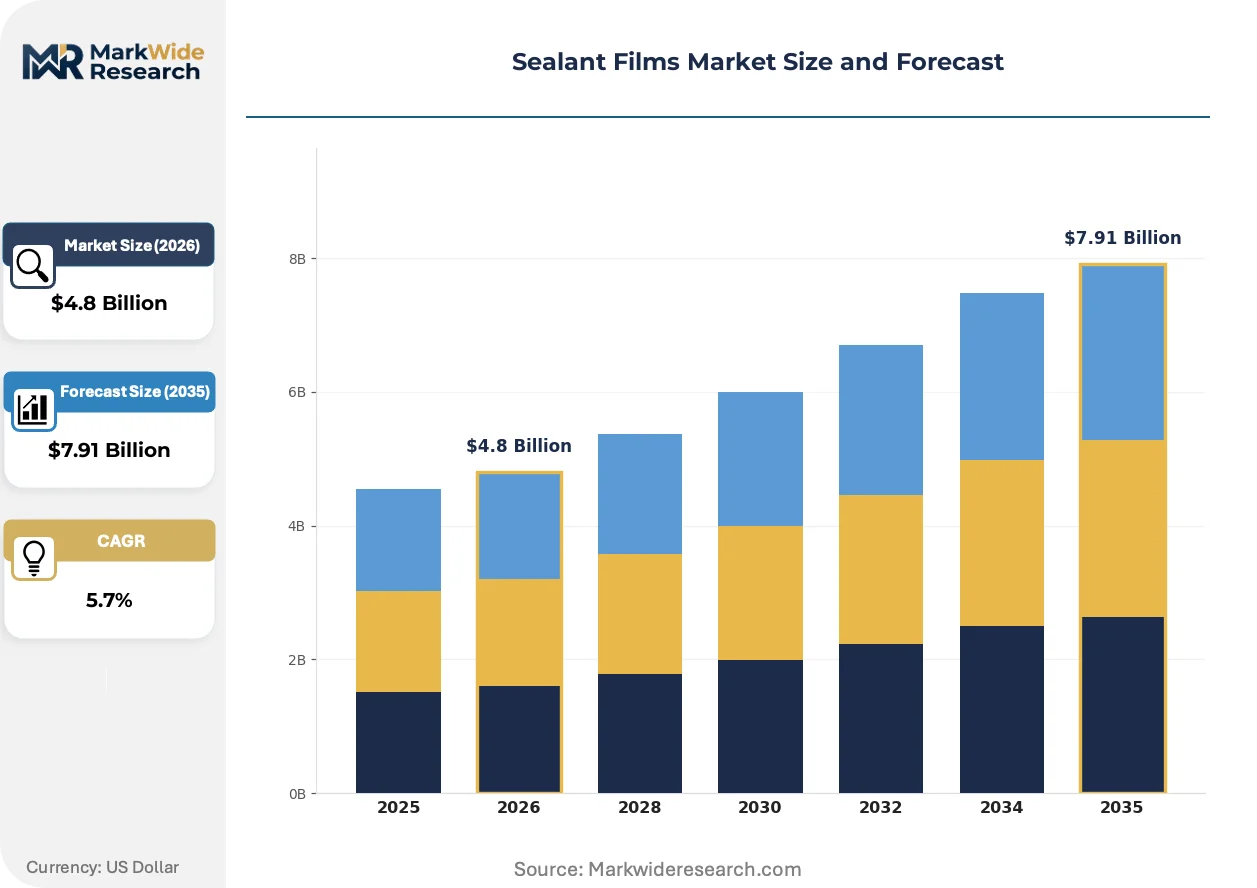
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
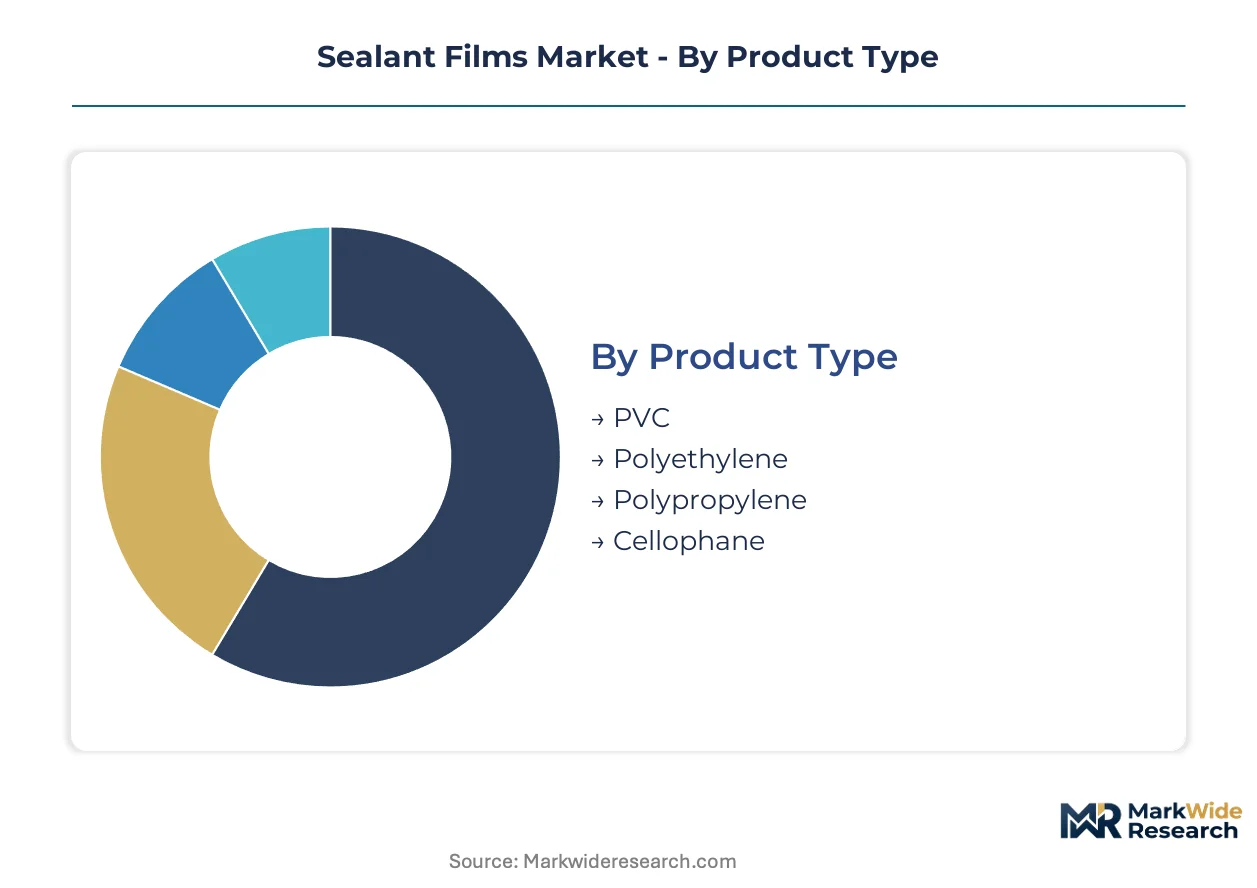
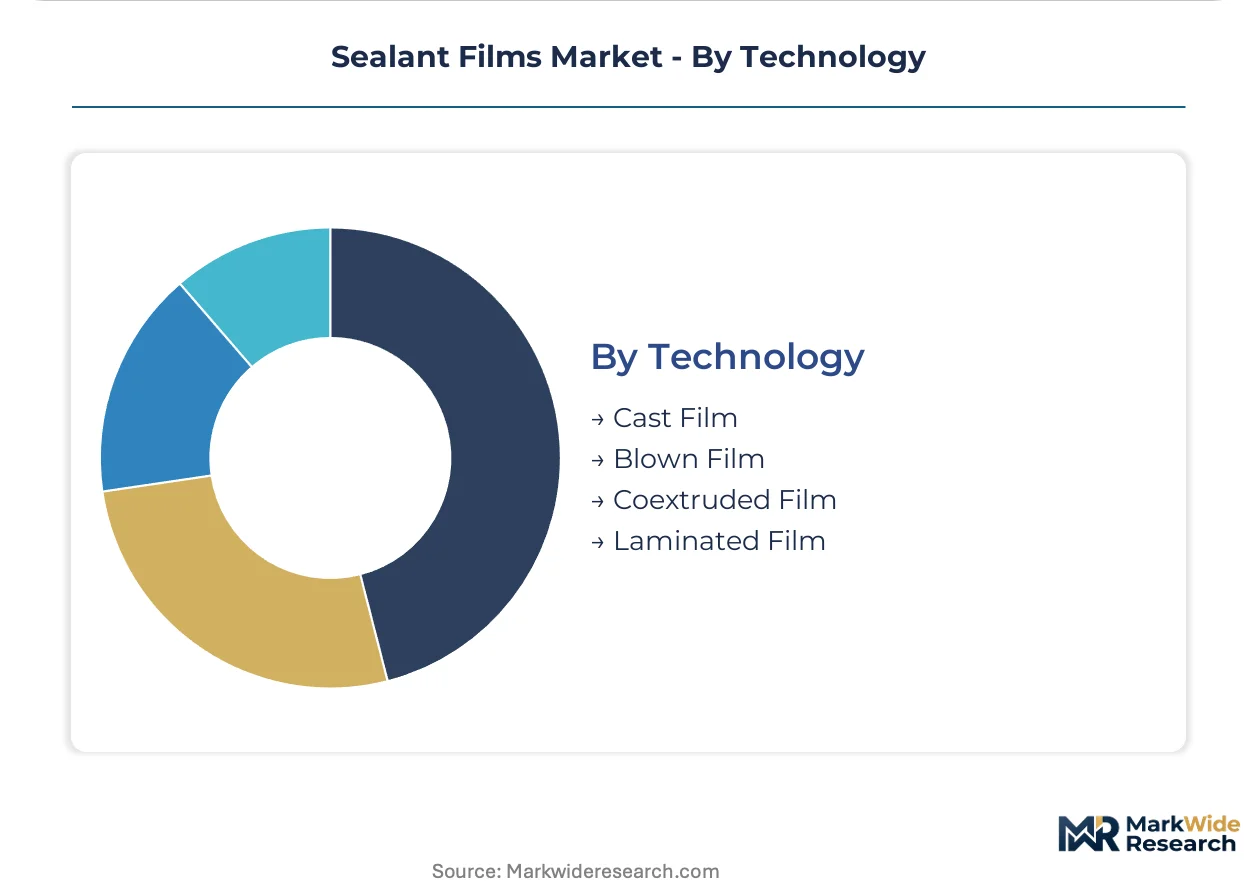
| Segmentation | Product Type: PVC, Polyethylene, Polypropylene, Cellophane Application: Food Packaging, Medical Use, Industrial Applications, Automotive Components Form: Rolls, Sheets, Pouches, Bags Technology: Cast Film, Blown Film, Coextruded Film, Laminated Film |
| Companies Covered | Amcor, Berry Global, Sealed Air, Mondi Group, Coveris, Toray Industries, UFlex, ProAmpac, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sealant Films Market Evolving Landscape
Active barrier technologies and circular material qualifications are redefining competitive differentiation in sealant film supply, shifting value capture from commodity resin sourcing toward formulation science and regulatory navigation capabilities.
Metallocene polyethylene plastomer formulations are collapsing the performance gap between conventional LDPE sealants and premium ionomer grades in frozen food applications. Major North American poultry processors are qualifying these materials for blast-freeze compatibility at reduced seal initiation temperatures. The substitution is collapsing pricing tiers that previously separated commodity from performance-grade sealant specifications.
REACH SVHC candidate list expansion is forcing systematic substitution of slip additives and antiblock agents in European food-contact films. ECHA evaluation of long-chain perfluorinated substances is accelerating migration toward silicone and erucamide alternatives. Medical packaging converters in Germany and the Netherlands are absorbing reformulation costs to maintain MDR compliance for sterile barrier systems.
Direct-to-converter digital specification platforms are compressing the traditional distributor channel for standard sealant film grades. Large North American flexible packaging groups are consolidating resin procurement through integrated ERP-to-ERP connections with compounders. The disintermediation is most advanced in polyethylene-rich formulations where technical specification is commoditized and logistics optimization dominates sourcing decisions.
Sealant Films Market Segmentation
Sealant film specifications diverge sharply across end-use requirements, with medical and food-contact applications demanding validated migration limits while industrial segments prioritize cost-efficient hermetic performance. Understanding these dimensional splits enables suppliers to align coextrusion investments with qualified demand pools rather than commoditized volume plays.
Product Type:
Cost tier stratification separates commodity polyolefins from specialty grades commanding formulation premiums.
- Polyethylene:Metallocene and ionomer-modified grades balance seal initiation temperature against hot-tack performance in frozen food applications. North American poultry processors are qualifying these materials for blast-freeze lines to reduce energy costs.
- Polypropylene:Cast and oriented variants serve high-temperature retort applications where thermal resistance exceeds polyethylene capabilities. Medical sterilization pouch demand in Germany and the Netherlands is pulling clarified random copolymer grades.
- PVC:Plasticized formulations retain niche positions in blister packaging for pharmaceutical tablets where clarity and thermoformability dominate specification.
- Cellophane:Regenerated cellulose structures persist in premium confectionery wrapping where biodegradability and dead-fold characteristics justify unit cost premiums.
Polyethylene commands the established base. The steepest expansion runs through polypropylene as retort medical applications multiply.
Application:
Customer type segmentation distinguishes regulated life-science buyers from price-sensitive industrial procurement.
- Food Packaging:Extended shelf-life specifications for modified-atmosphere structures drive multilayer coextrusion complexity. E-commerce fulfillment surge for unitized pouch formats is reshaping converter capacity toward puncture-resistant high-clarity grades.
- Medical Use:Sterile barrier systems for pharmaceutical devices require validated seal integrity and traceability documentation. EU MDR compliance deadlines are accelerating qualification timelines for coextruded barrier films.
- Industrial Applications:Moisture-sensitive electronics and chemical containment prioritize seal strength over optical properties. Chinese domestic converters in Jiangsu province are scaling capacity to serve regional industrial demand.
- Automotive Components:Underhood cable bundling and filter sealing applications demand thermal stability to 150°C. Specified grades compete against molded rubber gaskets on assembly-line efficiency.
Food packaging retains volume leadership. Medical use is climbing the fastest as regulatory compliance deepens specification stickiness.
Form:
Supply chain configuration varies with converter equipment and downstream handling requirements.
- Pouches:Pre-formed three-side-seal and stand-up configurations integrate zipper and spout functionality for liquid and granular products. Last-mile delivery optimization is pulling demand for unitized shelf-ready formats.
- Bags:Side-gusseted and quad-seal structures serve bulk dry goods and frozen protein distribution. Form-fill-seal line speeds above 400 units per minute stress hot-tack performance limits.
- Rolls:Unconverted film on cores supplies in-house forming operations at large food processors and contract packagers. Logistics efficiency favors regional toll-slitting networks.
- Sheets:Cut-size flat stock serves manual packaging operations and small-batch thermoforming in medical device assembly.
Rolls dominate upstream supply to converters. Pouches are gaining share fastest as brand owners outsource forming complexity.
Technology:
Process maturity separates capital-intensive coextrusion from legacy equipment bases.
- Coextruded Film:Five to seven layer architectures tailor barrier, seal, and structural properties in single-pass production. Rheological modeling capabilities for die design concentrate among specialized engineering groups.
- Blown Film:Tubular extrusion with internal bubble cooling dominates polyethylene-rich formulations for cost efficiency. Berry Global anchors North American supply through multi-site operations.
- Cast Film:Chill-roll casting delivers gauge uniformity and optical clarity for lamination and printing applications. Higher line speeds suit volume-commoditized grades.
- Laminated Film:Adhesive and extrusion lamination bonds dissimilar substrates for hybrid performance unattainable in monolithic structures. Secondary processing adds cost and lead time.
Blown film holds the installed capacity base. Coextruded film is expanding most quickly as barrier specifications tighten across food and medical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in sealant films increasingly reflect regional self-sufficiency initiatives rather than long-haul supply chains. Import dependence is contracting in Asia as domestic coextrusion capacity scales, while European converters absorb compliance costs to maintain export competitiveness.
United States
FDA food-contact notification requirements and EPA resin precursor rules are accelerating reformulation cycles for recycled-content grades. The USDA oversees bio-based packaging claims that influence procurement at national food processors. Multi-site blown film operations in Wisconsin and Illinois anchor North American supply to pouch converters serving e-commerce fulfillment channels.
Germany
EU MDR compliance deadlines for sterile barrier systems are pulling demand for validated coextruded films from pharmaceutical device manufacturers. ECHA evaluation of perfluorinated slip additives is forcing systematic migration toward silicone alternatives. Medical packaging clusters in Baden-Württemberg and Bavaria concentrate rheological modeling expertise for five-to-seven-layer die architectures.
China
Domestic converters in Jiangsu and Guangdong provinces are scaling coextruded capacity for medical and industrial end uses, reducing import dependence. SAMR packaging safety directives and GB standards impose conformity obligations that parallel REACH and FDA regimes. Yangtze River Delta toll-slitting networks optimize logistics efficiency for unconverted roll supply to regional food processors.
India
CDSCO serialization mandates for export-oriented pharmaceuticals are opening specification windows for multilayer barrier sealants with tamper-evident functionality. FSSAI food-contact regulations are tightening migration limits for domestic packaging applications. Gujarat-based manufacturing platforms leverage cost structures to export rolls and pouches to Middle Eastern and African markets.
Japan
METI carbon neutrality roadmaps are pressuring converters to qualify mechanically recycled polyethylene for food-contact applications. PMDA traceability requirements for medical device packaging align with EU MDR standards. Kansai-region coextrusion specialists supply high-clarity grades for premium confectionery and electronics moisture-barrier applications.
Sealant Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation expertise. The vendor base stratifies between resin compounders with captive film production and independent converters leasing coextrusion capacity. Three archetypes dominate: backward-integrated material scientists, asset-light toll manufacturers, and regional roll exporters competing on logistics optimization. Competitive moves concentrate on M&A for barrier technology access and multi-site capacity expansion to anchor converter relationships.
Among diversified packaging conglomerates, Amcor exemplifies the material-science archetype through captive resin compounding capabilities. Berry Global anchors the multi-site manufacturing tier with distributed blown film operations across North American industrial corridors. UFlex occupies the cost-driven export position from its Indian manufacturing base. These three represent distinct strategic vectors: formulation control, geographic density, and emerging-market scale.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Sealed Air |
| Mondi Group |
| Coveris |
| Toray Industries |
| UFlex |
| ProAmpac |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta freight corridors transmit resin cost volatility directly into sealant film pricing tiers, concentrating margin pressure on converters lacking backward integration while amplifying price differentiation between commodity polyethylene grades and engineered multilayer specifications.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the sealant films market. Price differentiation separates FDA food-contact certified grades from industrial non-contact specifications, with volume scale and geographic delivery cost as secondary drivers. Cost compression in commodity polyethylene tiers is intensifying because metallocene plastomer substitution collapses historical performance premiums. Food packaging converters demonstrate highest price sensitivity due to thin margins on high-volume pouch contracts, while medical device manufacturers accept premium positioning for MDR-compliant sterile barrier documentation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for sealant film procurement. Manufacturing concentration centers on China, Germany, and the United States for coextruded barrier grades, with India emerging as a cost-competitive export hub. Raw material dependencies rest on ethylene feedstock from naphtha crackers, metallocene catalyst systems, and ionomer resin supply concentrated among a handful of global polymer producers. Single-source vulnerability in specialty resin channels creates bottleneck exposure for medical-grade formulations. Distribution runs through regional toll-slitting networks that optimize logistics efficiency for unconverted roll supply to downstream converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rheological modeling expertise for five-to-seven-layer coextrusion die design represents the critical capability gap constraining competitive entry, with fewer than a dozen specialized engineering groups worldwide possessing validated simulation capabilities for complex multilayer architectures.
For Market Incumbents: Insulate formulation control by deepening backward integration into resin compounding and expanding multi-site blown film capacity across North American industrial corridors. Asset-light leasing models for coextrusion lines from specialized engineering groups defend margin position against capital-intensive new entrants. Prioritize MDR compliance documentation investment to maintain specification stickiness in European pharmaceutical packaging channels. For New Entrants and Emerging Players: Mid-tier Indian pharmaceutical packaging converters represent the most penetrable entry point for multilayer barrier sealants with tamper-evident functionality. CDSCO serialization mandates for export-oriented drug products open specification windows where incumbent qualification cycles lag demand acceleration. Pursue toll manufacturing partnerships with Gujarat-based resin compounders to bypass capital barriers in coextrusion line ownership. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive film production assets underperforming against standalone packaging specialists. Long-term viability hinges on regulatory navigation capabilities rather than commodity resin access, favoring targets with documented REACH and FDA notification track records. Watch for EU MDR compliance deadline clustering as an inflection indicator for medical-grade film valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Amcor's captive polyethylene and polypropylene grades sustain margin control across formulation tiers. |
| Multi-Site Blown Film Capacity Expansion | Berry Global's distributed Wisconsin and Illinois operations anchor North American supply to pouch converters. |
| MDR Compliance Documentation Investment | German and Dutch medical packaging clusters absorb reformulation costs to maintain sterile barrier qualification. |
| Asset-Light Coextrusion Line Leasing | Specialized engineering groups in Jiangsu province rewrite competitive entry economics for barrier film production. |
| Digital Specification Platform Development | ERP-to-ERP connections between North American flexible packaging groups and compounders compress distributor channels. |
Research Methodology
The analysis maps coextruded film, blown film, cast film, and laminated film sub-sectors, each validated through procurement directors at food packaging converters, technical R&D leads at resin compounders, and regulatory affairs managers at medical device manufacturers. Primary interview intelligence triangulates against secondary sources including FDA food-contact notification databases, ECHA REACH registration filings, SEC 10-K disclosures from packaging conglomerates, and customs trade data on polyethylene resin imports. Bottom-up demand modeling from end-use application volumes converges with top-down supply-side capacity assessments across regional production clusters.
Forecast assumptions hold regulatory compliance timelines and ethylene feedstock pricing regimes as fixed boundary conditions across the projection horizon, while varying coextrusion technology adoption rates and recycled content incorporation trajectories. Segmentation dimensions modeled include product type, application channel, form factor, and technology process, with regional regulatory cluster as an overlay variable. CAGRs derive from logistic growth curve fitting against historical penetration patterns, with inputs from medical device packaging sterilization pouch demand curves and e-commerce fulfillment format adoption rates.
Macroeconomic conditions sit as an overlay; deviation in crude-linked naphtha pricing, currency volatility in resin-importing economies, or abrupt regulatory divergence between REACH and FDA regimes would shift the trajectory. Forecasts reflect documented assumptions about coextrusion die design expertise concentration and specialty resin supply chain structure. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Global High Barrier Packaging Films Market