
 Japan Food Cling Film Market | 2026-2036
Japan Food Cling Film Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Cling Film Market Foresight
Polymer engineering talent scarcity is bifurcating the competitive landscape between integrated resin producers and specialized converters. Kureha Corporation leverages captive PVDC resin technology to sustain premium positioning in high-barrier segments. Mitsubishi Chemical Holdings anchors volume supply through backward integration into polyethylene feedstocks. Futamura Chemical differentiates via cellulose-based film expertise for sustainability-driven buyers.
Japan food cling film comprises thin, flexible polymer sheets—typically 8–15 microns for household grades, extending to 20–40 microns for commercial rolls—manufactured through blown or cast extrusion with cling additives for self-adhesion, designed primarily to extend shelf life by limiting oxygen and moisture transmission. PE grades dominate household volume due to cost efficiency and microwave safety, while PVDC commands commercial kitchens where oxygen barrier performance determines protein preservation quality. The thickness dimension reveals structural margin concentration: medium and thick rolls serve institutional foodservice with higher per-unit pricing and contract stickiness, whereas thin films face commoditization pressure in retail channels.
METI enforces container and packaging recycling targets under the Act on Promotion of Resource Circulation, compelling manufacturers to certify recycled content ratios or pay ecological fees. JIS standards for food-contact plastics, administered by the Ministry of Health, Labour and Welfare, mandate specific migration limits for plasticizers in PVC cling films used with fatty foods. PMDA oversight of food-contact notifications adds compliance layers for novel biopolymer introductions. Stakeholders must monitor whether forthcoming revisions to Japan's plastic waste reduction roadmap will mandate minimum bio-based content thresholds that reshape material selection across the value chain.
Market Dynamics
METI's enforcement of container and packaging recycling targets under the Act on Promotion of Resource Circulation is forcing resin producers and converters to reconfigure material portfolios around certified recycled content ratios or face escalating ecological fees.
Growth Catalysts
- Prepared meal packaging expansion:Foodservice operators in Tokyo's dense hospitality corridor are expanding cling film deployment for bento and deli packaging, driving volume pull through commercial-grade specifications.
- Biodegradable material mandates:Japan's Plastic Resource Circulation Act is accelerating shifts toward biodegradable and recycled-content films, creating compliance-driven replacement cycles across institutional buyers.
- Kanto region demand concentration:Retail and hospitality infrastructure density around Tokyo generates disproportionate volume absorption, concentrating procurement scale and contract stickiness among regional distributors.
Market Restraints
- Polymer engineering talent scarcity:Specialized converter capabilities in high-barrier film formulation are concentrating among integrated resin producers, limiting mid-tier competitor access to premium segments.
- PVDC feedstock dependency:Kureha Corporation's captive resin technology anchors oxygen-barrier supply, creating bottleneck risk for commercial kitchen buyers requiring protein preservation performance.
- Microwave safety limitations:PVC cling films face technical constraints for high-temperature applications, restricting penetration in prepared meal segments requiring dual cold-hot packaging compatibility.
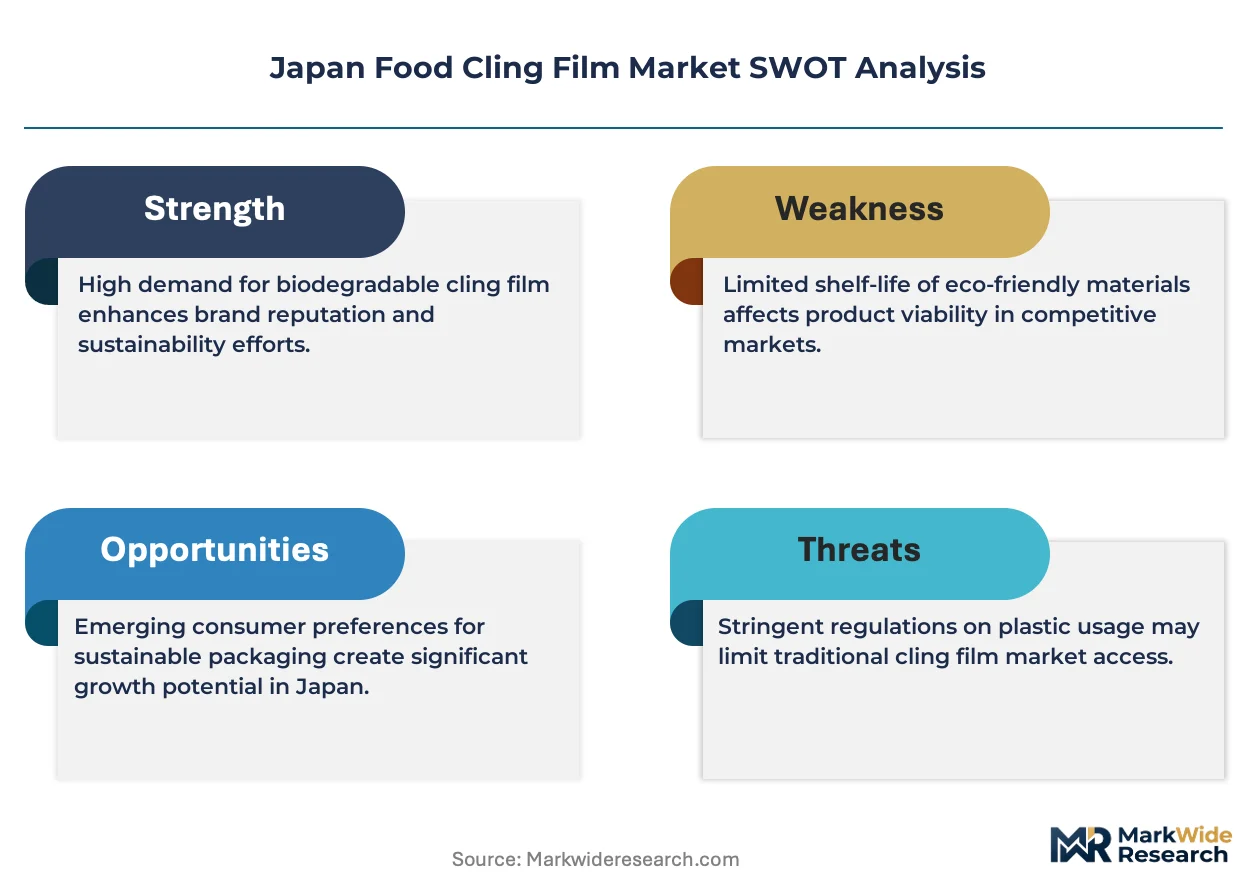
Strategic Opportunities
- Cellulose-based film white space:Futamura Chemical's existing expertise in cellulose substrates positions sustainability-driven buyers for bio-based transitions as METI thresholds tighten.
- Thick-roll institutional contracts:Medium and thick commercial grades serving foodservice operators carry higher per-unit pricing and longer contract durations than commoditized retail thin films.
- JIS migration limit certifications:Ministry of Health, Labour and Welfare standards for plasticizer limits in fatty food contact create differentiation pathways for compliant PVC alternatives.
Industry Challenges
- PMDA notification timelines:Novel biopolymer introductions face extended food-contact approval cycles, compressing product launch windows against regulatory deadline pressures.
- Blown versus cast extrusion capex:Equipment selection for cling additive integration requires significant capital commitment, stranding mid-scale converters in legacy process configurations.
- Recycled content verification systems:METI certification requirements demand traceability infrastructure that smaller converters lack, fragmenting competitive access to eco-fee exemptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Cling Film Market |
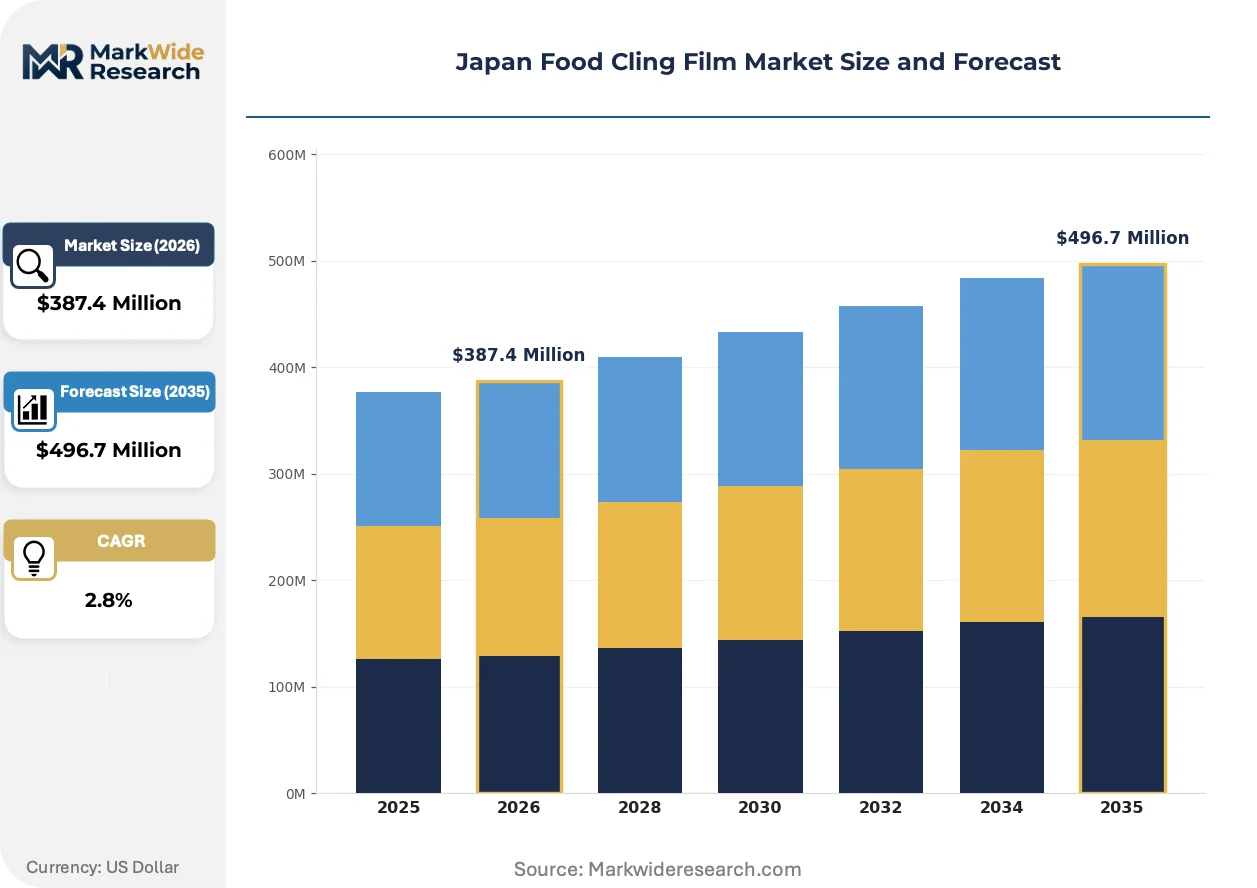
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $496.7 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PE, PVC, PVDC, Others End User: Foodservice, Retail, Household, Catering Thickness: Thin, Medium, Thick, Super Thick Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Kureha Corporation, BENKAI Co., Ltd., Mitsubishi Chemical Holdings Corp, KOHJIN Film & Chemicals, Nan Ya Plastics Corporation, Asahi Kasei Corporation, Riken Technos Corp, Futamura Chemical Co., Ltd., Shin-Etsu Polymer Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Cling Film Market Shifts & Advancements
Material science advances and regulatory compression are restructuring competitive advantage around barrier performance, biodegradability certification, and microwave compatibility rather than commodity volume scale.
Polylactic acid blends enhanced with plasticized starch are decomposing under industrial composting conditions within 180 days, meeting METI biodegradability thresholds. Premium retail chains in Osaka and Nagoya are piloting these films for organic produce packaging. The technology is decomposing price premiums for conventional PE grades in sustainability-positioned channels.
JIS S 2053 and S 2054 standards for food-contact plastics, administered by the Ministry of Health, Labour and Welfare, mandate specific migration limits for plasticizers in PVC cling films used with fatty foods. Manufacturers must reformulate additive packages or exit fatty food applications. Commercial kitchen buyers are responding by accelerating PVDC and PE transitions in protein-handling operations.
Central kitchen procurement consolidation among mid-size restaurant chains is compressing supplier counts and extending contract durations. Distributors serving the Kansai region are losing share to direct manufacturer relationships. This pattern is most visible in Osaka's prepared meal production cluster, where volume concentration enables custom specification negotiation.
Japan Food Cling Film Market Segmentation
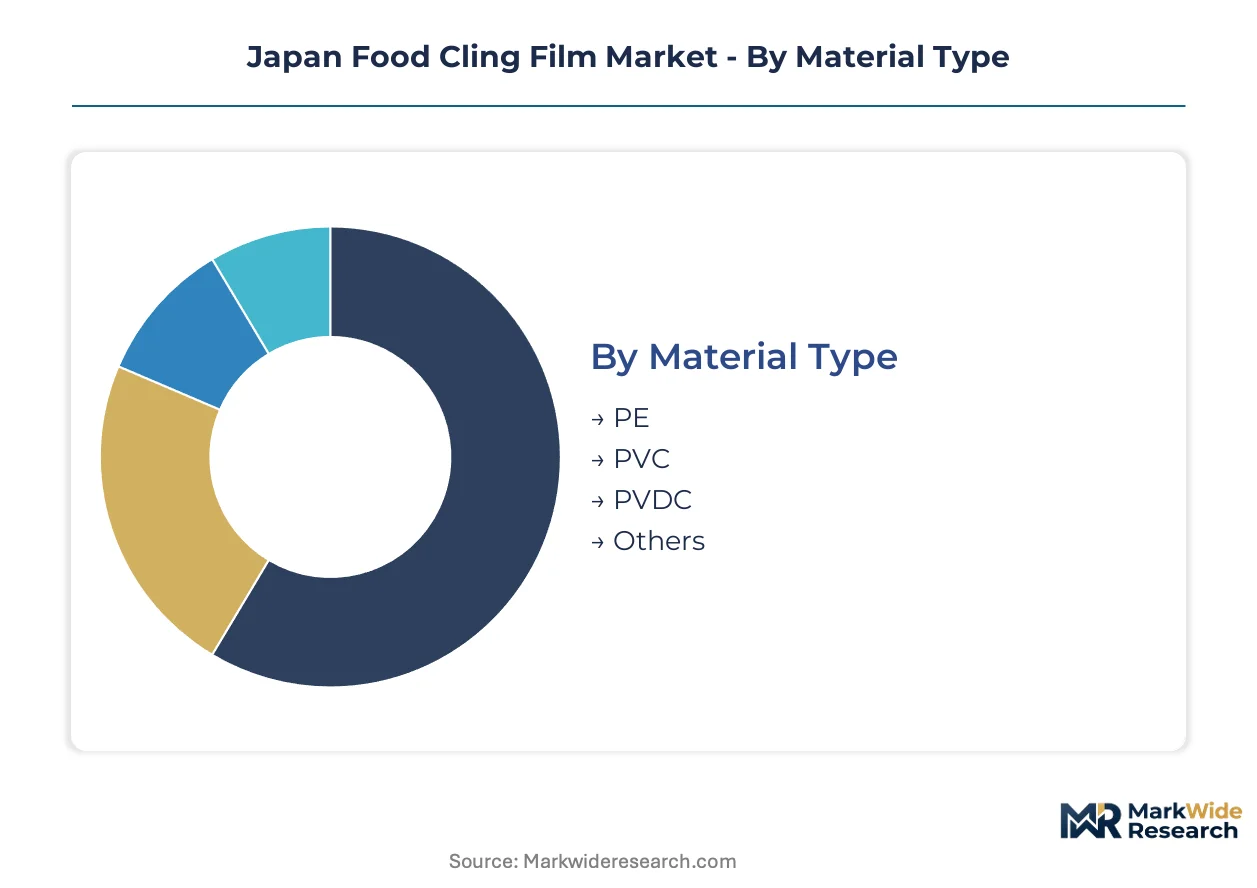
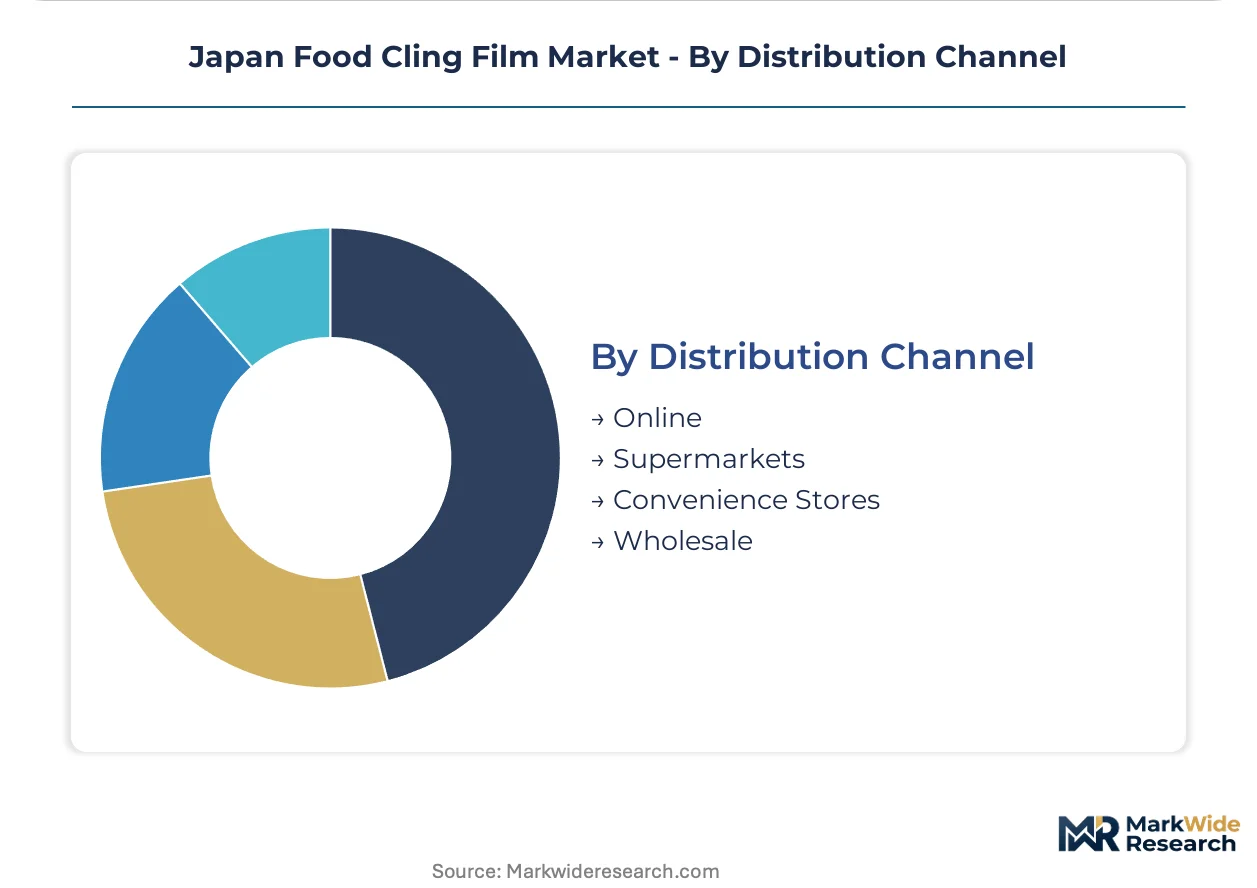
Material composition and thickness specifications determine barrier performance and regulatory compliance pathways across Japan's food cling film value chain. End-user concentration in Tokyo's prepared meal corridor and Kansai's institutional foodservice clusters shapes procurement scale and contract structures. Distribution channel evolution reflects e-commerce penetration in household segments against wholesale stickiness in commercial supply.
Material Type:
Domestic resin production anchors PE and PVDC supply, while PVC compounding relies partly on imported plasticizer feedstocks subject to JIS migration limit enforcement.
- PE:Polyethylene grades dominate household volume through blown extrusion with cling additives, offering microwave safety and cost efficiency. Tokyo metropolitan retail chains specify PE for bento packaging requiring dual cold-hot compatibility.
- PVC:Plasticized polyvinyl chloride films provide optical clarity and hand-wrap tackiness for deli counter applications. Osaka's supermarket prepared food sections favor PVC for protein display aesthetics despite fatty food contact constraints under Ministry of Health, Labour and Welfare standards.
- PVDC:Kureha Corporation's captive resin technology commands commercial kitchen oxygen-barrier requirements.
- Others:Emerging PLA-starch blends and cellulose substrates target METI biodegradability thresholds.
PE holds the largest share; momentum sits with PVDC as protein preservation standards tighten in foodservice procurement.
End User:
Customer type stratification separates institutional volume contracts from fragmented household purchasing patterns.
- Foodservice:Central kitchen operators and restaurant chains in Tokyo's dense hospitality corridor drive thick-roll specifications with 12-24 month contract durations. METI recycling certification requirements concentrate procurement among integrated suppliers capable of traceability documentation.
- Retail:Supermarket deli counters and convenience store chains demand medium-thickness films with printed branding compatibility. Nagoya's retail consolidation is compressing supplier counts toward direct manufacturer relationships.
- Household:Thin PE rolls dominate consumer pantry stocking through supermarket and online channels.
- Catering:Event and institutional catering operators in Kansai specify custom-width rolls for high-volume protein handling.
Foodservice generates the highest per-unit margins; household volume is expanding most quickly through e-commerce subscription models.
Thickness:
Dimension specifications correlate directly with application durability requirements and pricing tier separation.
- Thin:8-12 micron household grades face commoditization pressure in retail channels. Cast extrusion processes dominate thin film production for cost-sensitive consumer segments.
- Medium:15-20 micron specifications balance hand-wrap conformability with puncture resistance for retail deli operations. Kanto region supermarket chains specify medium grades for prepared vegetable packaging.
- Thick:25-35 micron commercial rolls serve institutional foodservice with machine-wrap compatibility and extended roll lengths. Contract stickiness is highest in this tier due to equipment calibration requirements.
- Super Thick:40+ micron specifications address heavy-duty catering and protein freezing applications with maximum puncture resistance.
Thick rolls command premium pricing; medium grades are gaining share fastest as retail prepared meal packaging expands.
Distribution Channel:
Channel structure reflects procurement scale concentration and sustainability certification verification requirements.
- Online:E-commerce platforms capture household replenishment purchasing with subscription bundling. Amazon Japan and Rakuten are expanding private-label PE film offerings with recycled content claims.
- Supermarkets:Aeon and Ito-Yokado chains dominate household stock-up purchasing with seasonal promotional cycles. Shelf placement negotiations favor suppliers with METI ecological fee exemptions.
- Convenience Stores:7-Eleven and Lawson procurement concentrates thin-roll household emergency purchasing.
- Wholesale:Foodservice distributor networks in Osaka and Tokyo maintain contract stickiness through technical specification support and volume pricing.
Wholesale holds the largest share; online channels are climbing the fastest as subscription models penetrate metropolitan households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's regional cling film consumption patterns diverge sharply between Tokyo's prepared meal corridor and Kansai's institutional foodservice clusters, with thickness specifications and material preferences tracking local culinary traditions and regulatory enforcement intensity.
Kanto/Tokyo
Tokyo's dense hospitality infrastructure drives thick-roll commercial specifications for central kitchen operators. METI's recycling certification requirements concentrate procurement among integrated suppliers capable of traceability documentation. The metropolitan retail chains specify PE grades for bento packaging requiring dual cold-hot compatibility, while Shinjuku's foodservice distributors maintain contract stickiness through technical specification support.
Kansai/Osaka
Osaka's supermarket prepared food sections favor PVC for protein display aesthetics despite fatty food contact constraints under Ministry of Health, Labour and Welfare standards. The city's central kitchen procurement consolidation among mid-size restaurant chains compresses supplier counts and extends contract durations. Kansai's institutional catering operators specify custom-width rolls for high-volume protein handling, with volume concentration enabling direct manufacturer relationships.
Chubu/Nagoya
Nagoya's retail consolidation is compressing supplier counts toward direct manufacturer relationships for medium-thickness films. Aeon and Ito-Yokado chains dominate household stock-up purchasing with seasonal promotional cycles, with shelf placement negotiations favoring suppliers with METI ecological fee exemptions. The region's automotive worker canteen networks drive institutional volume through wholesale distributor networks.
Kyushu
Kyushu's regional food processors are piloting PLA-starch blends for organic produce packaging under METI biodegradability thresholds. Local convenience store chains concentrate thin-roll household emergency purchasing, while Fukuoka's growing prepared meal production cluster attracts direct manufacturer procurement relationships. The island's distance from resin production centers elevates logistics costs for smaller converters.
Hokkaido
Hokkaido's dairy and seafood processing industries demand maximum puncture resistance in 40+ micron specifications for protein freezing applications. The prefecture's cold chain infrastructure requires extended roll lengths for machine-wrap compatibility in distribution centers. Sapporo's retail chains lag metropolitan areas in biodegradable film adoption due to supply chain distance and certification verification challenges.
Japan Food Cling Film Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's food cling film market, with captive resin technology and backward integration into polyethylene feedstocks defining competitive position. The structure rewards players controlling barrier performance specifications or sustainability certifications. Three archetypes dominate: integrated resin producers with captive technology, specialized converters with formulation expertise, and diversified chemical conglomerates with volume scale. Capacity expansion in biodegradable substrates and strategic partnerships for recycled content verification represent the dominant competitive moves.
Within the integrated resin producer tier, Kureha Corporation and Mitsubishi Chemical Holdings exemplify contrasting positioning strategies. Kureha anchors oxygen-barrier supply through captive PVDC resin technology, while Mitsubishi Chemical Holdings commands volume supply through backward integration into polyethylene feedstocks. Futamura Chemical occupies a position within the specialized converter archetype, with cellulose-based film expertise targeting sustainability-driven buyers. These three companies represent the competitive spectrum from premium barrier performance to bio-based transitions.
| Leading Market Players |
|---|
| Kureha Corporation |
| BENKAI Co., Ltd. |
| Mitsubishi Chemical Holdings Corp |
| KOHJIN Film & Chemicals |
| Nan Ya Plastics Corporation |
| Asahi Kasei Corporation |
| Riken Technos Corp |
| Futamura Chemical Co., Ltd. |
| Shin-Etsu Polymer Co., Ltd. |
| Others |
Supply & Pricing Matrix
Captive PVDC resin production at Kureha Corporation and backward integration into polyethylene feedstocks at Mitsubishi Chemical Holdings create scale economies that set price floors across Japan's food cling film tiers. These integrated positions concentrate margin capture among resin producers while converters face commoditization pressure in thin-film retail channels.
Pricing Analysis
Long-term offtake contracts dominate foodservice procurement, with central kitchen operators in Tokyo's hospitality corridor locking 12-24 month agreements for thick-roll specifications. Three-tier pricing structure across premium barrier grades, standard PE films, and economy PVC tiers tracks certification levels under JIS migration limits and METI ecological fee exemptions. Cost compression in thin household grades intensifies as e-commerce subscription models compress per-unit margins. Retail chains exhibit highest price sensitivity, while institutional buyers prioritize performance consistency over unit economics.
Supply Chain Analysis
Kureha Corporation's captive vinylidene chloride monomer supply anchors a critical chokepoint for oxygen-barrier film availability across Japan's commercial kitchen sector. Domestic resin production draws from naphtha crackers in Chiba and Osaka, while plasticizer feedstocks for PVC compounding source from South Korean and Chinese petrochemical complexes. Single-source vulnerability concentrates in PVDC resin technology, where proprietary polymerization expertise limits supplier alternatives. Distribution runs through foodservice wholesale networks in Tokyo and Osaka, with direct manufacturer relationships displacing regional distributors in consolidated procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated central kitchen operators and retail chains, with procurement consolidation among mid-size restaurant chains in Osaka and Nagoya compressing supplier counts and extending contract durations.
For Market Incumbents: Fortify barrier technology positions against cellulose-based substitutes by deepening captive resin expertise and accelerating JIS-compliant formulation certification. METI's tightening biodegradability thresholds threaten PVC-dependent portfolios, making backward integration into bio-based feedstocks a critical defensive lever. For New Entrants and Emerging Players: Anchor in Kyushu's PLA-starch blend pilot programs for organic produce packaging, where METI certification verification gaps create temporary procurement flexibility. Foodservice distributors serving Hokkaido's seafood processors represent the most penetrable channel, with custom-width super-thick specifications enabling specification-based entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized converters with cellulose substrate expertise as sustainability mandates accelerate material transitions. Long-term viability rests on bio-based certification infrastructure rather than commodity scale. Watch PMDA notification timelines for novel biopolymers as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Secures METI compliance pathways as ecological fee thresholds tighten for petroleum-derived films. |
| JIS Migration Limit Certification Investment | Unlocks fatty food contact applications for PVC alternatives under Ministry of Health, Labour and Welfare enforcement. |
| Cellulose Substrate Capacity Expansion | Positions Futamura Chemical's expertise for sustainability-driven procurement shifts in premium retail channels. |
| Direct Manufacturer Relationship Development | Bypasses wholesale distributor margins in Nagoya's consolidating retail procurement landscape. |
| Recycled Content Traceability Infrastructure | Enables METI ecological fee exemptions that determine shelf placement at Aeon and Ito-Yokado chains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, JIS standard documentation, and customs trade records for resin and film imports. Interviews with polymer engineering directors at integrated resin producers, procurement managers at central kitchen operators, technical specification leads at foodservice distributors, and sustainability officers at retail chains combined with bottom-up volume modeling and top-down market sizing triangulation.
Segmentation dimensions modeled include material composition across PE, PVC, PVDC and emerging bio-based substrates; thickness tiers from household thin grades through commercial super-thick specifications; end-user categories spanning foodservice, retail, household and catering; and distribution channel structure across online, supermarket, convenience store and wholesale pathways. CAGRs derive from regression analysis against macroeconomic indicators and regulatory deadline schedules, with forecast inputs incorporating PMDA approval timelines and METI recycling target trajectories.
Decision-makers should treat outputs as directional under assumptions of steady METI enforcement intensity and stable naphtha feedstock pricing; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as biodegradability certification thresholds and biopolymer approval timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market