
 Volatile Corrosion Inhibitors (VCI) Packaging Market | 2026-2036
Volatile Corrosion Inhibitors (VCI) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Corrosion Inhibitors (VCI) Packaging Market Analytics
Industrial distribution for VCI packaging is narrowing as specialized corrosion-protection distributors consolidate shelf space against general packaging resellers. BRANOpac GmbH leverages its European compound manufacturing base to supply blended masterbatches directly to film extruders. Cortec Corporation sustains a differentiated position through captive production of amine-carboxylate chemistry at its Minnesota facility. Daubert Cromwell competes on geographic density, operating regional blending plants across the US Midwest and Southeast to shorten lead times for just-in-time automotive programs.
Volatile Corrosion Inhibitors comprise vapor-phase corrosion inhibitors—typically amine salts of carboxylic acids or nitrite-free azole derivatives—impregnated into polymer films, papers, or coatings at concentrations between 3-8 gsm; these compounds volatilize to form a molecular adsorption layer on ferrous and non-ferrous metal surfaces, blocking oxygen and moisture ingress during storage and transit. Films dominate value capture due to higher unit margins and compatibility with automated packaging lines in automotive and electronics sectors, while paper retains volume leadership in heavy machinery and export crating where puncture resistance matters less than cost absorption. The aerospace end-use segment concentrates demand for aluminum-compatible formulations free of volatile amines that could stress-corrode aircraft alloys, creating a premium tier segmented from general industrial applications.
EPA oversight of volatile organic compound emissions from VCI film extrusion shapes manufacturing location decisions in the United States, while REACH registration requirements in the European Union constrain which chemistries suppliers may import or compound within member states. Japan's METI maintains JIS standards for corrosion protection in precision instrument export packaging, creating a certification barrier for non-domestic film producers. Stakeholders must monitor regulatory divergence between nitrite-restrictive frameworks and performance-demanding end-use specifications to anticipate which formulation platforms will retain multi-regional eligibility.
Market Dynamics
REACH compliance in the European Union is redirecting formulation R&D toward nitrite-free alternatives, compressing legacy chemistry platforms while creating first-mover advantages for suppliers with pre-qualified compound libraries.
Growth Catalysts
- Automotive OEM expansion:Inbound metal parts logistics in Germany and Mexico are scaling VCI film procurement for just-in-time assembly lines.
- Ocean freight protection:Precision metal exports from China's Yangtze River Delta manufacturing cluster require extended corrosion protection during multi-week transit.
- REACH-driven substitution:Tightening permissible amine-based VCI chemistries under EU regulation is accelerating demand for compliant nitrite-free formulations.
Market Restraints
- Raw material concentration:Masterbatch compound supply concentrates among European specialty chemical producers, creating input cost volatility for film extruders.
- Technical performance gaps:Nitrite-free alternatives exhibit shorter protection windows on ferrous alloys in high-humidity environments, limiting substitution velocity.
- Regulatory fragmentation:Divergence between EPA VOC emission rules and REACH registration requirements forces dual-track formulation development.
Strategic Opportunities
- Aerospace certification tier:Aluminum-compatible formulations free of volatile amines command premium positioning for aircraft alloy protection.
- Distribution consolidation:Specialized corrosion-protection distributors are narrowing shelf space against general packaging resellers, favoring technical specialists.
- Regional blending proximity:Geographic density of compounding plants shortens lead times for automotive just-in-time programs in the US Midwest and Southeast.
Industry Challenges
- Formulation talent scarcity:Chemists with expertise in vapor-phase inhibitor synthesis and polymer compatibility are concentrated among legacy suppliers.
- Certification timeline compression:JIS standards for precision instrument export packaging in Japan create multi-quarter approval barriers for non-domestic film producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Corrosion Inhibitors (VCI) Packaging Market |
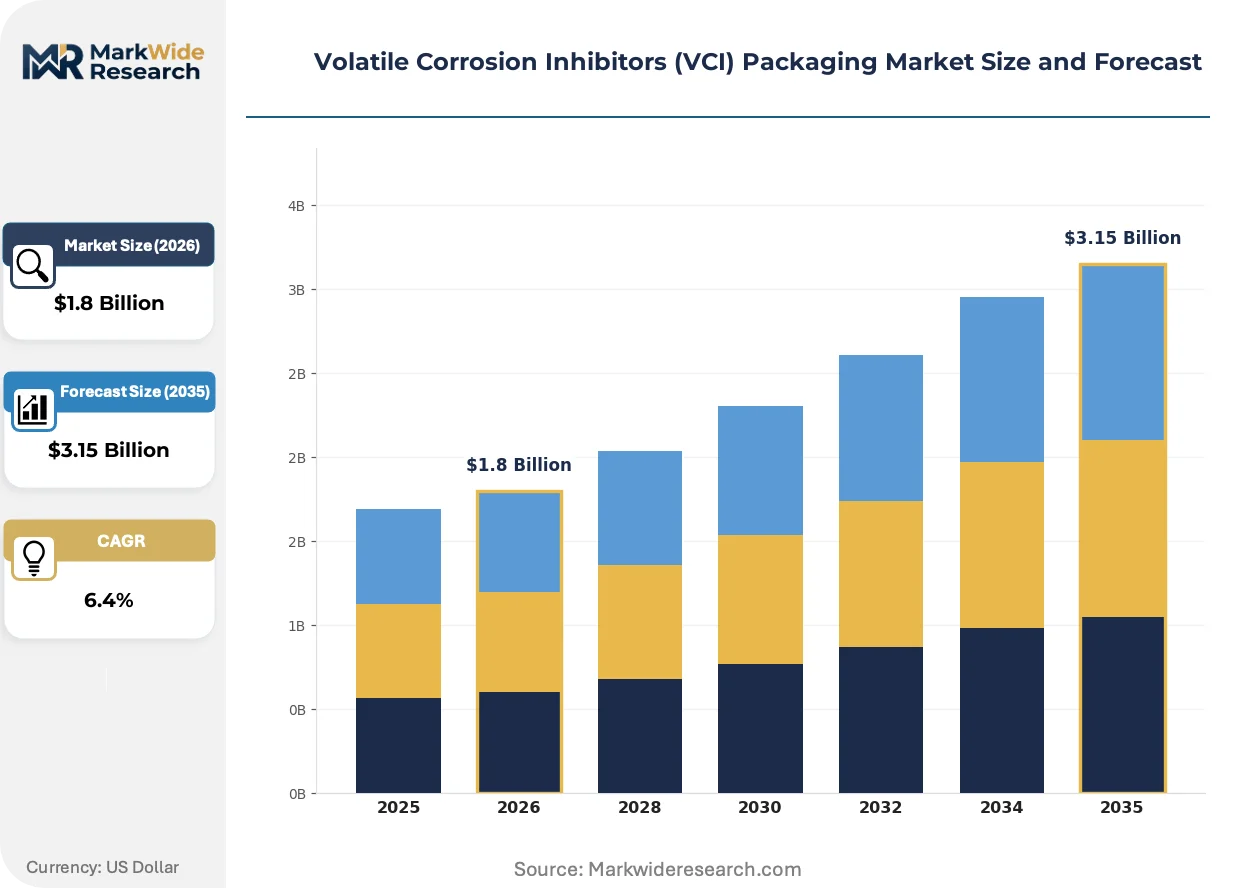
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Paper, Coatings, Bags Material: Polyethylene, Paperboard, Polypropylene, Aluminum End User: Aerospace, Automotive, Electronics, Metalworking Application: Storage, Shipping, Export, Preservation |
| Companies Covered | BRANOpac GmbH, AICELLO CORPORATION, Cortec Corporation, Intertape Polymer Group, Transcendia, Armor Protective Packaging, Northern Technologies International Corporation, Rust-X, Daubert Cromwell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Corrosion Inhibitors (VCI) Packaging Market Evolving Landscape
Formulation platforms and manufacturing processes are diverging as regulatory pressure and end-use specialization reshape competitive requirements across automotive, aerospace, and precision electronics verticals.
Multilayer coextrusion technology is migrating from commodity stretch-wrap applications into engineered VCI film structures with controlled inhibitor release profiles. Tier-one automotive suppliers in Germany and Mexico are qualifying these films for automated packaging lines. The technology is migrating from standard polyethylene substrates toward ethylene-vinyl alcohol barrier layers that extend protection duration.
REACH registration requirements in the European Union are constraining which chemistries suppliers may import or compound within member states. ECHA evaluation of amine carboxylates is forcing reformulation toward azole derivatives and plant-based extracts. Aerospace end-users are responding by segregating supply chains: EU-qualified formulations for European MRO networks, EPA-registered alternatives for North American operations.
Buyer concentration among automotive OEMs is compressing supplier margins while elevating technical service requirements. Tier-one metal stampers are consolidating procurement under single-source VCI film contracts with embedded logistics support. This pattern is most visible in Germany, where inbound parts networks for electric vehicle platforms demand synchronized delivery windows.
Volatile Corrosion Inhibitors (VCI) Packaging Market Segmentation
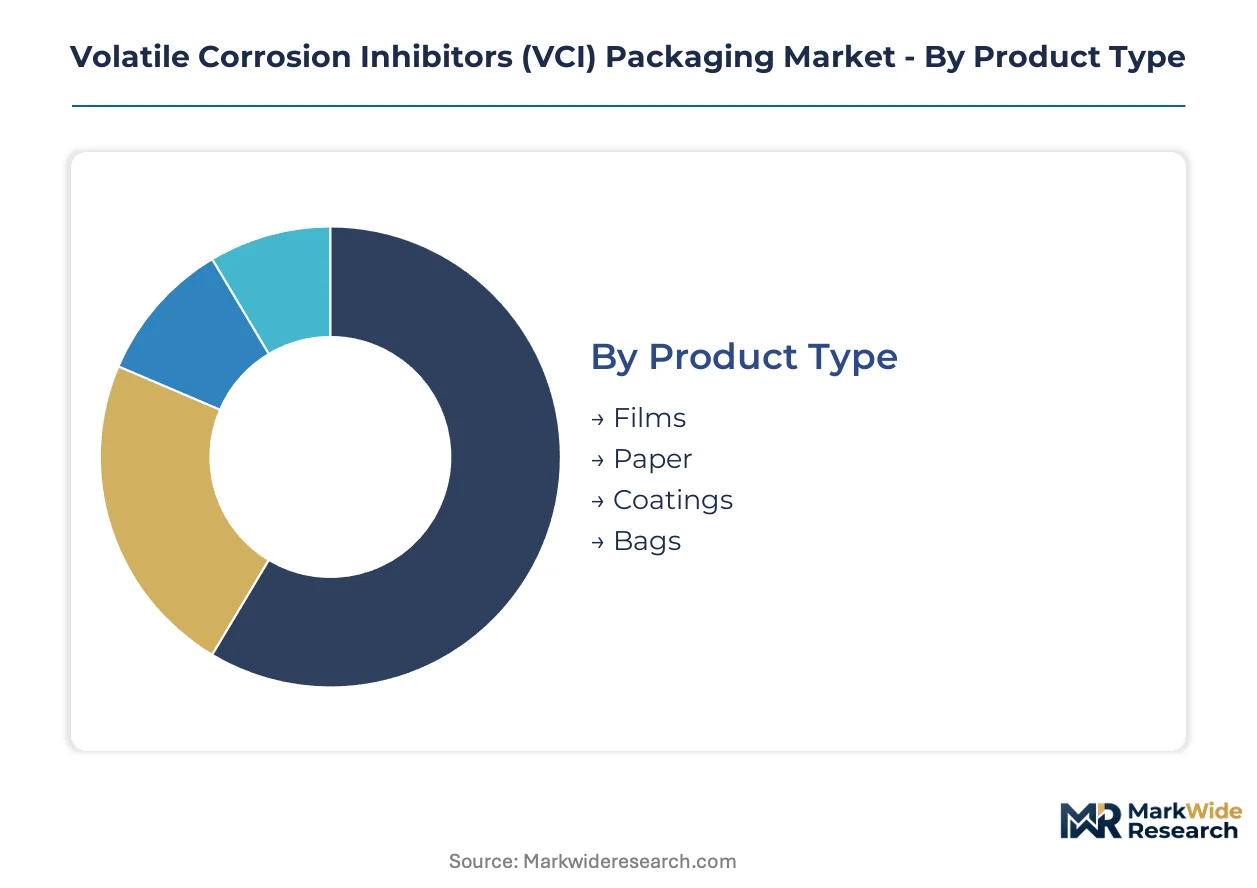
VCI packaging segments diverge sharply by protection duration, automation compatibility, and regulatory compliance burden. Film and paper substrates command divergent margin structures, while aerospace and automotive end-users impose incompatible certification standards.
Product Type:
Mature extrusion technologies dominate commodity films, whereas emerging multilayer structures capture premium positioning through controlled release profiles.
- Films:Polyethylene and ethylene-vinyl alcohol multilayer structures carry 3-8 gsm inhibitor loadings, enabling automated heat-sealing on automotive packaging lines in Germany and Mexico. REACH-compliant nitrite-free formulations command 15-20% price premiums over legacy amine-carboxylate platforms.
- Paper:Kraft and glassine substrates impregnated with vapor-phase inhibitors serve heavy machinery export crating where puncture resistance matters less than cost absorption. China's Yangtze River Delta cluster consumes volume for precision metal ocean freight protection.
- Coatings:Waterborne and solvent-based liquid VCI systems spray or dip-coat complex geometries inaccessible to film wrapping. Metalworking shops in the US Midwest favor coatings for intermittent part protection between machining operations.
- Bags:Pre-formed gusseted and flat pouches integrate zip closures for electronics component kitting. Japanese precision instrument exporters specify JIS-certified bags to satisfy METI corrosion protection standards.
Films handle the majority of throughput; bags are expanding most quickly on share as electronics kitting standardizes.
Material:
Cost tiers separate commodity polyolefins from performance-engineered barrier substrates with extended protection windows.
- Polyethylene:Low-density and linear low-density grades dominate extruded film production for automotive inbound logistics. EPA VOC emission rules constrain US-based extrusion capacity expansion.
- Paperboard:Recycled-content corrugated and solid fiber boards serve machinery crating with VCI-impregnated liners. European converters face ECHA scrutiny of amine-based inhibitor chemistries.
- Polypropylene:Biaxially oriented and cast films offer higher temperature resistance for under-hood automotive applications. Mexico's expanding OEM assembly plants specify PP for engine component protection.
- Aluminum:Laminated foil structures provide absolute moisture barriers for aerospace alloy preservation. Aircraft MRO networks demand aluminum-compatible formulations free of volatile amines that stress-corrode alloys.
Polyethylene absorbs the greatest volume; aluminum laminates command the steepest expansion trajectory in aerospace-certified tiers.
End User:
Application-specific performance requirements fragment supply chains across certification-intensive verticals.
- Aerospace:Aluminum, titanium, and magnesium alloy protection demands amine-free azole derivatives or plant-based inhibitors. Separate EU-qualified and EPA-registered formulations segregate European and North American MRO supply chains.
- Automotive:Just-in-time inbound metal parts logistics in Germany and Mexico drive automated VCI film consumption. Tier-one stampers consolidate procurement under single-source contracts with embedded logistics support.
- Electronics:Printed circuit board and connector protection requires non-corrosive, residue-free vapor-phase inhibitors. Precision instrument exporters from China's Yangtze River Delta specify extended-duration protection for multi-week ocean transit.
- Metalworking:Job shops and contract manufacturers use VCI papers and coatings for inter-operation rust prevention. US Midwest regional blending plants shorten lead times for fragmented, small-batch demand.
Automotive channels move the greatest material tonnage; aerospace specifications are climbing the fastest on value per kilogram.
Application:
Duration and environmental exposure severity determine substrate and formulation selection across the protection lifecycle.
- Storage:Warehouse and yard protection for raw steel and finished components employs low-cost paper and polyethylene film. Humidity-controlled indoor environments tolerate shorter-duration inhibitor formulations.
- Shipping:Domestic truck and rail transit requires moderate-duration protection against condensation cycling. Automotive suppliers in Germany specify synchronized delivery windows matching assembly line takt times.
- Export:Ocean freight exposes containers to salt spray and temperature fluctuations over multi-week voyages. China's precision metal exporters specify ethylene-vinyl alcohol barrier films for Yangtze River Delta origin shipments.
- Preservation:Long-term mothballing of military, aerospace, and infrastructure components demands hermetic sealing with desiccant integration. REACH-compliant nitrite-free formulations are displacing legacy chemistries for European defense applications.
Shipping applications dominate transaction frequency; preservation contracts are gaining share fastest in defense and infrastructure verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for REACH-compliant nitrite-free formulations, while Chinese producers compete on volume for extended-duration ocean freight protection. This asymmetry shapes procurement patterns across automotive inbound logistics and precision metal export corridors.
Germany
Automotive OEMs in Stuttgart and Munich are scaling VCI film procurement for electric vehicle platform assembly lines. ECHA enforcement of amine carboxylate restrictions is accelerating reformulation toward azole derivatives. The Baden-Württemberg precision metal cluster demands synchronized delivery windows matching just-in-time takt times.
United States
Tier-one automotive stampers in Michigan and Ohio are consolidating procurement under single-source contracts with embedded logistics support. EPA VOC emission rules constrain extrusion capacity expansion in the Midwest. Regional blending plants across Indiana and Tennessee shorten lead times for fragmented metalworking demand.
China
Precision metal exporters in the Yangtze River Delta require ethylene-vinyl alcohol barrier films for multi-week ocean transit to European and North American markets. MEE oversight of chemical manufacturing is tightening environmental compliance for VCI compound production. Shanghai and Suzhou manufacturing clusters specify extended-duration protection for high-humidity container voyages.
Mexico
OEM assembly plants in Nuevo León and Mexico City are expanding VCI film consumption for inbound metal parts logistics serving German and Japanese automakers. The country's automotive regulator aligns with EPA frameworks for VOC emissions from polymer processing. Bajío Region stamping operations specify polypropylene substrates for under-hood engine component protection.
Japan
Precision instrument manufacturers in Osaka and Nagoya specify JIS-certified VCI bags for METI-compliant export packaging. METI maintains certification barriers creating multi-quarter approval timelines for non-domestic film producers. Kansai region electronics exporters demand residue-free vapor-phase inhibitors for printed circuit board protection.
Volatile Corrosion Inhibitors (VCI) Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in compound and masterbatch supply. The vendor base organizes around three functional layers: captive compound manufacturers, regional film extruders, and specialized corrosion-protection distributors. Consolidation pressure concentrates among European specialty chemical producers supplying blended masterbatches to film converters. Dominant competitive moves include geographic densification of blending plants and qualification of multilayer coextrusion structures for automated automotive lines.
Among European compound specialists, BRANOpac GmbH exemplifies the integrated manufacturer archetype with captive production of blended masterbatches. Cortec Corporation anchors the North American tier through amine-carboxylate chemistry production at its Minnesota facility. Daubert Cromwell represents the geographic proximity strategy, operating regional blending plants across the US Midwest and Southeast to compress lead times for just-in-time automotive programs.
| Leading Market Players |
|---|
| BRANOpac GmbH |
| AICELLO CORPORATION |
| Cortec Corporation |
| Intertape Polymer Group |
| Transcendia |
| Armor Protective Packaging |
| Northern Technologies International Corporation |
| Rust-X |
| Daubert Cromwell |
| Others |
Value Network & Pricing Analysis
REACH-driven reformulation mandates in the European Union compress pricing power for legacy amine-carboxylate suppliers while widening spreads between REACH-compliant nitrite-free formulations and standard industrial grades. This regulatory chokepoint simultaneously concentrates supply chain leverage among European compound specialists and forces dual-track inventory strategies across automotive and aerospace procurement networks.
Pricing Analysis
Configured-to-order pricing for aerospace-certified aluminum-compatible formulations commands substantial premiums over standard polyethylene films serving automotive inbound logistics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with JIS-certified bags and REACH-compliant multilayer films occupying the premium tier against commodity paper and LDPE films. Cost compression in standard grades intensifies as automotive OEMs consolidate procurement under single-source contracts with embedded logistics support. Tier-one metal stampers in Germany and Mexico exhibit lowest price sensitivity due to just-in-time synchronization requirements, while fragmented US Midwest metalworking shops drive volume through spot purchasing.
Supply Chain Analysis
Extended payment terms from German automotive OEMs cascade through tier-one stampers to film extruders, compressing working capital for regional blending plants. Masterbatch compound supply concentrates in Germany, Belgium, and the Netherlands among European specialty chemical producers, with film extrusion capacity distributed across the US Midwest, Mexico, and China's Yangtze River Delta. Raw material dependencies encompass amine salts, azole derivatives, ethylene-vinyl alcohol barrier resins, and polyethylene feedstocks. Single-source vulnerability concentrates in REACH-compliant compound libraries held by BRANOpac GmbH and select integrated manufacturers. Distribution runs through specialized corrosion-protection distributors consolidating shelf space against general packaging resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VCI packaging market approaches a platform-economics inflection as REACH compliance and aerospace certification requirements fragment formulation platforms into non-interoperable regional ecosystems. Interoperability breaks down between EU-qualified and EPA-registered supply chains, forcing buyers into parallel qualification tracks.
For Market Incumbents: Pre-empt nitrite-free formulation gaps by accelerating azole derivative and plant-based extract R&D ahead of ECHA evaluation timelines. Captive production of blended masterbatches at European compound manufacturing bases defends margin position against specialty chemical distributors seeking upstream integration. Certification investment in JIS standards and aluminum-compatible amine-free formulations creates switching costs for aerospace MRO networks.
For New Entrants and Emerging Players: Build out regional blending proximity in Mexico's Bajío Region and the US Southeast to capture automotive just-in-time programs fleeing lead time constraints. White-space concentrates in nitrite-free formulations for European defense preservation contracts and residue-free vapor-phase inhibitors for Japanese precision instrument exporters. Go-to-market leverage rests on technical service bundling with embedded logistics support rather than price competition.
For Investors and Strategic Acquirers: REACH registration deadlines reshape the acquisition landscape toward compound specialists with pre-qualified libraries and captive azole derivative production. Long-term viability favors vertically integrated manufacturers controlling masterbatch formulation through film extrusion, with aerospace certification tiers offering durable margin protection. The signal to watch is ECHA enforcement intensity against amine carboxylate imports, which would accelerate substitution demand and revalue nitrite-free compound assets.
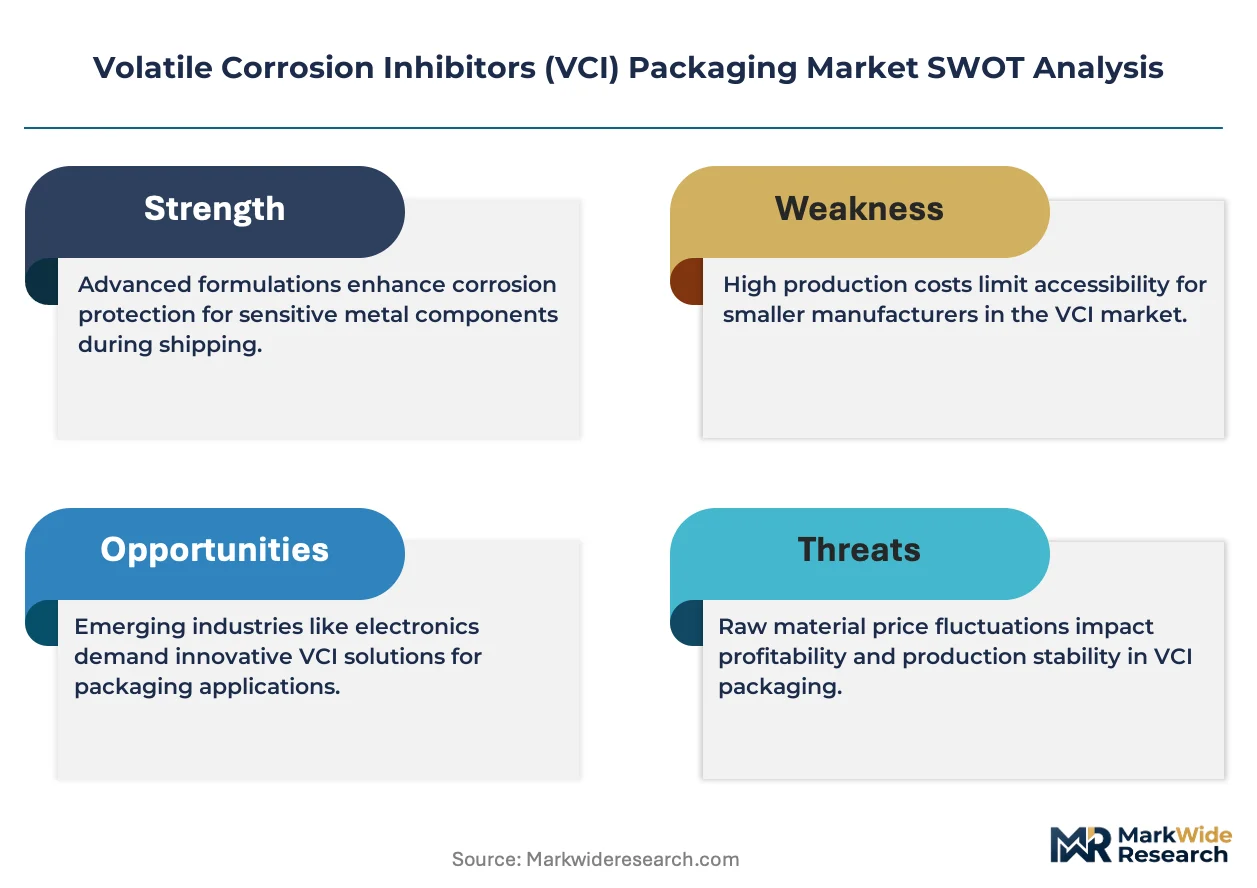
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Production | Captive compound supply insulates margin from European specialty chemical price volatility. |
| Multilayer Coextrusion Capacity Expansion | Controlled release profiles qualify for automated automotive packaging lines in Germany. |
| REACH-Compliant Formulation Pre-Qualification | Azole derivative libraries capture substitution demand from restricted amine-carboxylate users. |
| Regional Blending Plant Densification | Geographic proximity compresses lead times for just-in-time automotive programs. |
| Aerospace Certification Investment | Amine-free formulations access premium tier for aluminum alloy protection in aircraft MRO. |
Research Methodology
Initial hypotheses were tested against primary input from VCI compound chemists, automotive procurement managers at tier-one stampers, aerospace MRO supply chain directors, and specialized corrosion-protection distributors and refined through secondary validation. Primary interviews explored formulation R&D priorities, qualification timelines, and procurement consolidation patterns. Secondary sources encompassed ECHA registration databases, EPA VOC emission filings, JIS standard certification records, and customs trade data for VCI film and paper substrates. Bottom-up demand modeling from end-use consumption triangulated against top-down supply capacity estimates across European compound manufacturers and regional film extruders.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for nitrite-free formulations and multilayer barrier films. Segmentation dimensions included product type, material substrate, end-use vertical, and regional regulatory cluster. CAGRs were derived from unit consumption projections calibrated to automotive production forecasts and precision metal export volumes. Industry-specific inputs incorporated REACH enforcement probability assessments and JIS certification timeline distributions for non-domestic film producers.
Stress conditions across ECHA regulatory stringency, ocean freight duration volatility, and automotive production cycle amplitude were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substitution velocity for nitrite-free alternatives and aerospace certification adoption rates. Macroeconomic contraction, regulatory divergence acceleration, or breakthrough corrosion-protection technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market