
 Opioid Induced Side Effects Treatment Market | 2026-2036
Opioid Induced Side Effects Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Induced Side Effects Treatment Market Outlook
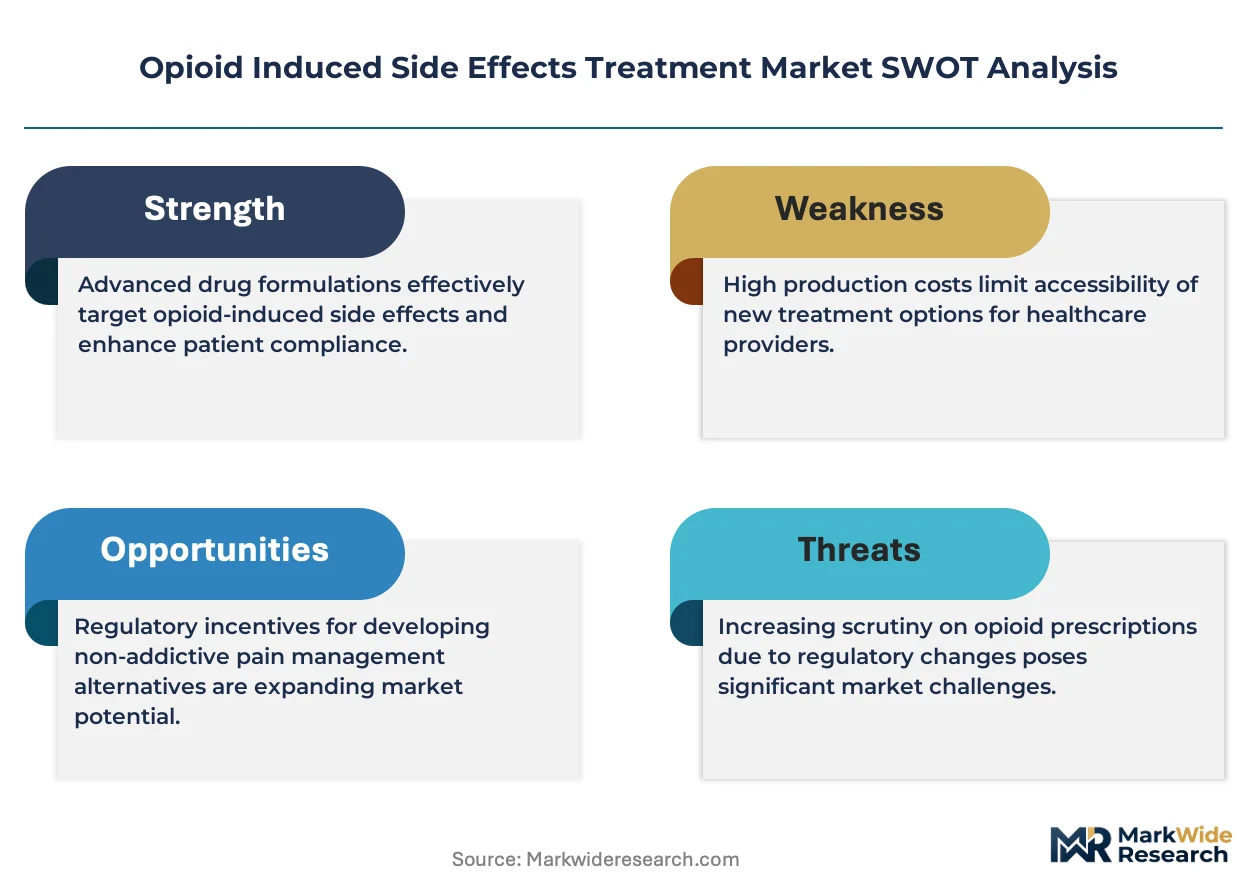
ISO 13485 certification is rotating as the decisive gating standard for device and drug-device combination manufacturers entering this space. Pfizer Inc. leverages its hospital formulary relationships to sustain access across acute care settings. Orexo AB specializes in sublingual film formulations that differentiate its portfolio from conventional tablet-based competitors.
Opioid induced side effects treatment encompasses pharmacological and non-pharmacological interventions designed to counteract adverse events including constipation, respiratory depression, nausea, sedation, and dependency arising from opioid analgesic therapy. These interventions typically employ peripherally acting mu-opioid receptor antagonists such as methylnaltrexone or naloxegol, which block opioid action in the gastrointestinal tract without crossing the blood-brain barrier to compromise central analgesia. Injectable antagonists dominate hospital revenue pools due to acute care urgency, while transdermal delivery modes represent the fastest-expanding segment as home-based pain management protocols extend treatment duration beyond inpatient stays. Combination therapies command premium positioning where polypharmacy regimens simultaneously address pain and preempt adverse effects.
The FDA Risk Evaluation and Mitigation Strategy mandates prescriber training and patient monitoring that directly expands the addressable market for side-effect mitigation products. EMA pharmacovigilance requirements under the EU Medical Device Regulation impose additional clinical documentation burdens on manufacturers seeking European market access. Stakeholders must monitor evolving REMS modifications and pharmacogenomic testing integration as these forces determine which product formats gain formulary preference across institutional purchasers.
Market Dynamics
Hospital pain management protocols are pivoting toward preemptive side-effect mitigation, with the FDA's REMS mandates forcing institutional purchasers to embed antagonist therapies directly into opioid prescribing workflows rather than treating adverse events reactively.
Growth Catalysts
- REMS Compliance Mandates:The FDA Risk Evaluation and Mitigation Strategy requires prescriber training and patient monitoring protocols that expand formulary slots for peripherally acting antagonists in acute care settings.
- Subacute Care Migration:Post-surgical recovery is shifting toward extended home-based protocols, creating demand for patient-administered transdermal and sublingual delivery formats.
- Pharmacogenomic Integration:CYP2D6 and OPRM1 testing is entering standard-of-care pathways, enabling personalized antagonist selection that improves therapeutic index and reduces trial-and-error prescribing.
Market Restraints
- API Supply Concentration:Naloxegol and methylnaltrexone active pharmaceutical ingredients rely on a limited base of contract manufacturers clustered in India and China.
- Reimbursement Compression:Medicare's Hospital Outpatient Prospective Payment System bundles side-effect treatments into procedure-based payments, squeezing standalone antagonist margins.
- Central Penetration Risk:Blood-brain barrier pharmacokinetics impose hard technical limits on peripheral selectivity, constraining dose escalation for severe opioid-induced constipation.
Strategic Opportunities
- Japan's Aging Surgical Cohort:METI reimbursement reforms for post-operative pain management are opening formulary access for combination opioid-antagonist products in tertiary hospitals.
- Biologics-Opioid Co-Development:Antibody-drug conjugate pipelines are creating adjacency demand for GI-protective antagonist co-formulations in oncology supportive care.
- Telehealth-Enabled Monitoring:Remote patient monitoring platforms are creating direct-to-patient distribution channels for home-use antagonist kits bypassing traditional hospital pharmacy gatekeepers.
Industry Challenges
- ISO 13485 Certification Timelines:Drug-device combination manufacturers face 18-24 month quality management system audits that delay European MDR compliance and market entry.
- Legacy EHR Integration:Antagonist prescribing decision support requires API connections to entrenched Epic and Cerner installations that resist third-party module adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Induced Side Effects Treatment Market |
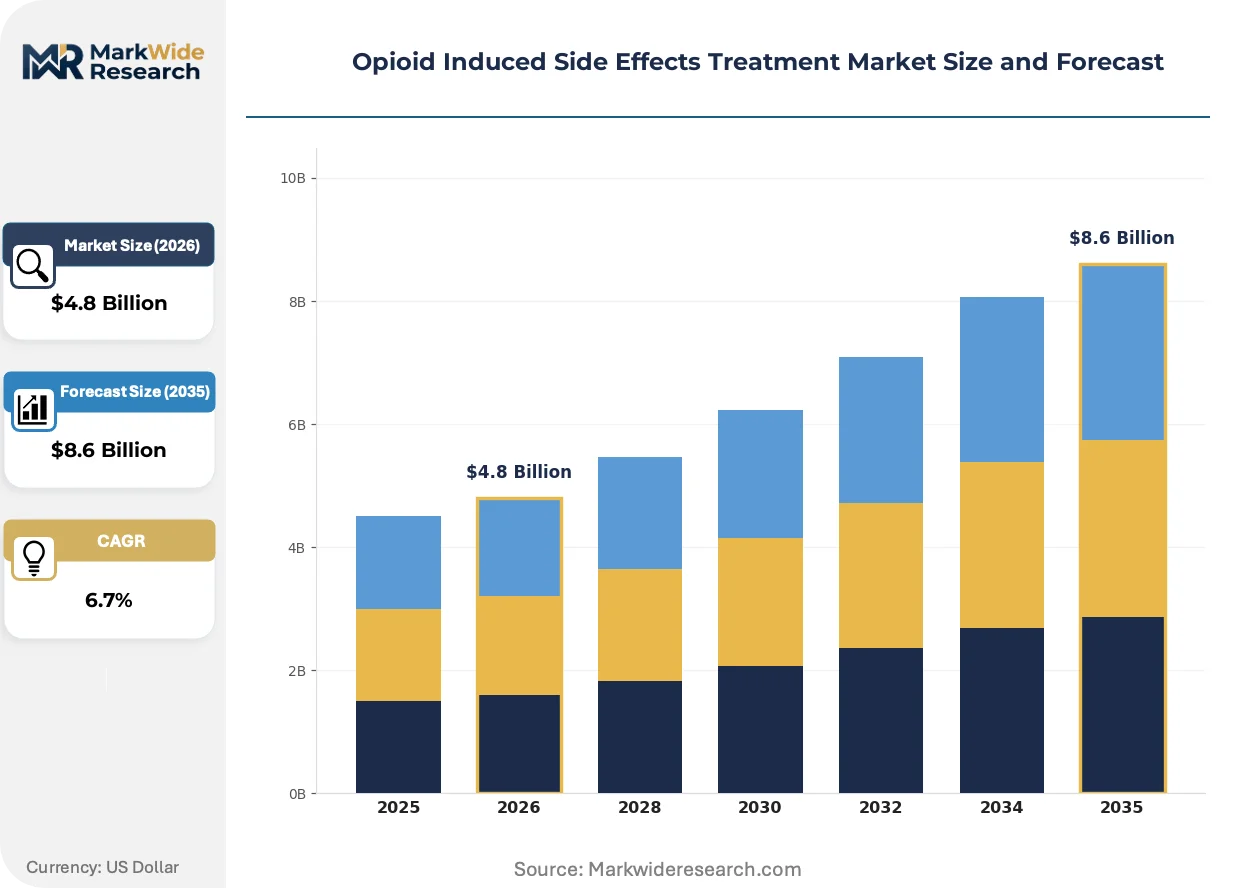
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antagonists, Agonists, Combination Therapies, Non-Pharmacological Treatments Therapy Area: Pain Management, Anxiety Disorders, Depression, Gastrointestinal Disorders End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Settings Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Indivior PLC, Orexo AB, Pfizer Inc., Alkermes, Viatris Inc., Teva Pharmaceutical Industries Ltd., Hikma Pharmaceuticals PLC, BioDelivery Sciences International Inc., Camurus AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Induced Side Effects Treatment Market Strategic Shifts
Delivery technology and regulatory data requirements are restructuring competitive advantage in side-effect mitigation, with format innovation outpacing molecular discovery as the primary value creation lever.
Sublingual film formulations are decomposing the tablet-dominated maintenance therapy segment by enabling faster onset and improved bioavailability in patients with compromised GI motility. Home health agencies and skilled nursing facilities are adopting these formats at twice the rate of traditional oral solids. The technology is decomposing hospital-centric revenue models by shifting administration authority to non-physician caregivers.
EMA's Medical Device Regulation pharmacovigilance requirements are imposing granular clinical documentation obligations on manufacturers seeking CE marking for drug-device combinations. Post-market surveillance data must now capture real-world antagonist efficacy in polypharmacy contexts. European hospital purchasing consortia are responding by demanding pre-submitted MDR technical files as a gating condition for tender participation.
Purchasing committees are consolidating vendor relationships around integrated pain-and-side-effect bundles rather than discrete antagonist procurement. Hospital systems are displacing standalone product contracts with single-source agreements covering opioid analgesics, antagonist co-therapies, and patient monitoring infrastructure. This concentration is most visible in United States integrated delivery networks where pharmacy benefit managers now control antagonist formulary placement.
Opioid Induced Side Effects Treatment Market Segmentation
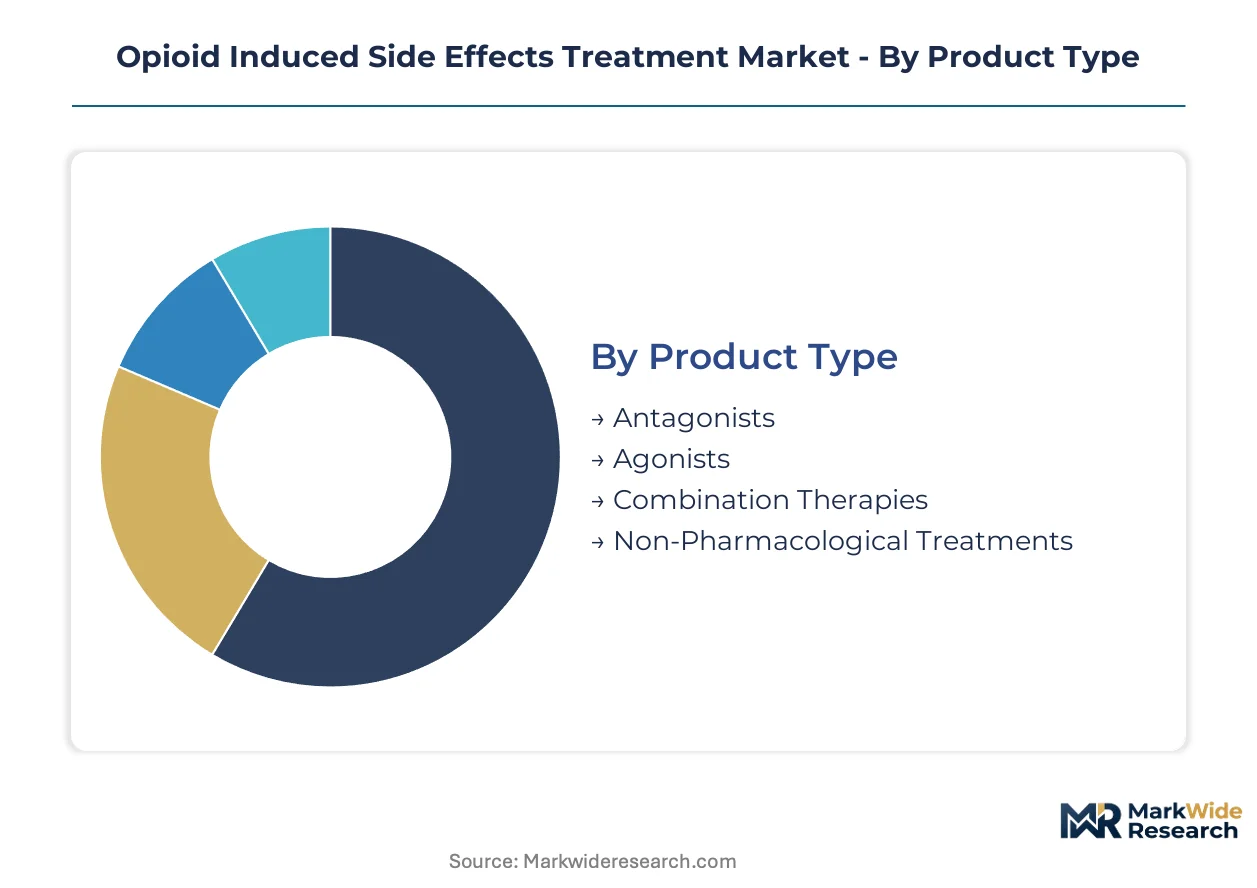
Segmentation in opioid side-effect mitigation reveals how regulatory pressure and care setting economics reshape product development priorities. Each dimension exposes different margin structures and compliance burdens that determine which formats capture institutional procurement budgets.
Product Type:
FDA REMS mandates and EMA MDR documentation requirements create divergent commercial hurdles across pharmacological categories, with drug-device combinations facing the steepest certification timelines.
- Antagonists:Peripherally acting mu-opioid receptor antagonists such as methylnaltrexone and naloxegol block GI tract opioid binding without crossing the blood-brain barrier. Hospital formularies in the United States prioritize these for REMS-compliant prescribing workflows, though Medicare bundled payments compress standalone margins.
- Combination Therapies:Co-formulations delivering analgesia with embedded side-effect prophylaxis command premium positioning in oncology supportive care. Integrated delivery networks in the United States are consolidating procurement around these bundles to simplify pharmacy benefit manager negotiations.
- Agonists:Partial agonist formulations with intrinsic ceiling effects reduce respiratory depression risk compared to full agonists.
- Non-Pharmacological Treatments:Acupuncture, cognitive behavioral therapy, and physical rehabilitation protocols address dependency and functional recovery without pharmacokinetic interactions.
Antagonists handle the majority of throughput; combination therapies are expanding most quickly as bundled procurement concentrates vendor relationships.
Therapy Area:
Clinical indication determines reimbursement coding and therefore addressable patient volume, with postsurgical protocols offering the clearest pathway to formulary inclusion.
- Pain Management:Acute and chronic pain protocols generate the largest prescription volumes for side-effect mitigation products. United States tertiary hospitals embed antagonist co-therapies directly into perioperative order sets to satisfy FDA monitoring obligations.
- Gastrointestinal Disorders:Opioid-induced constipation represents the most frequent dose-limiting adverse event requiring pharmacological intervention. Home health agencies in the United States are driving demand for patient-administered formats as subacute care extends beyond inpatient stays.
- Anxiety Disorders:Co-morbid anxiety in chronic pain patients complicates opioid titration and side-effect profiling.
- Depression:Polypharmacy with antidepressants alters CYP2D6 metabolism and antagonist selection criteria.
Pain management commands the dominant share of prescribing volume; gastrointestinal applications are gaining share fastest as home-based protocols proliferate.
End User:
Purchasing authority and reimbursement mechanism vary sharply across settings, with institutional buyers demanding different evidence packages than direct-to-patient channels.
- Hospitals:Acute care settings generate the highest revenue per patient for injectable antagonists due to urgency and monitoring infrastructure. Epic and Cerner EHR integration requirements create technical barriers for new entrants seeking prescribing decision support placement.
- Home Care Settings:Skilled nursing facilities and home health agencies are adopting sublingual and transdermal formats at twice the rate of traditional oral solids. United States Medicare home health benefit expansions are extending treatment duration and antagonist consumption per episode.
- Outpatient Clinics:Ambulatory surgical centers require rapid-onset formats compatible with same-day discharge protocols.
- Rehabilitation Centers:Long-term recovery facilities prioritize dependency mitigation over acute side-effect reversal.
Hospitals retain the largest absolute volume; home care settings are climbing the fastest as post-surgical migration accelerates.
Delivery Mode:
Route of administration determines manufacturing complexity, regulatory pathway, and patient compliance economics, with format innovation outpacing molecular discovery as the primary value lever.
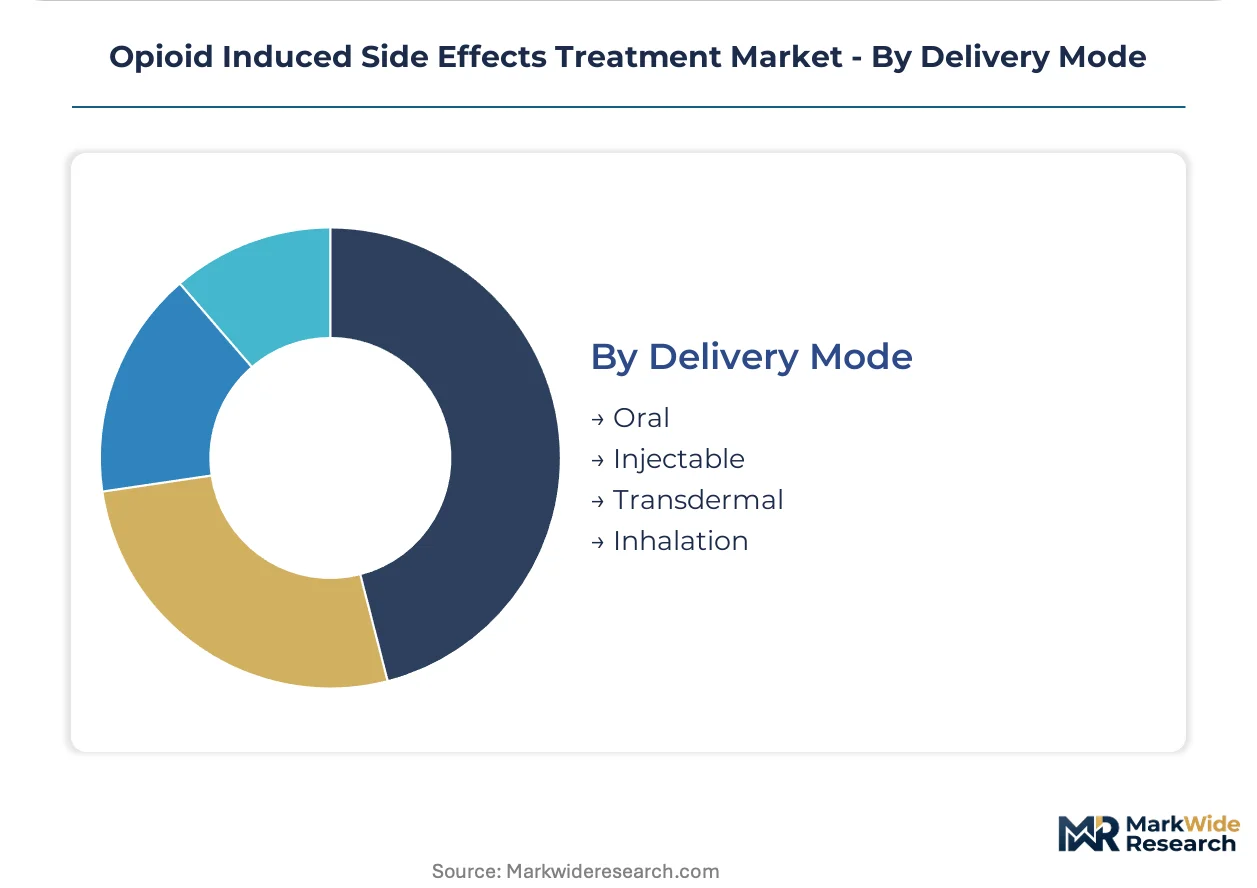
- Injectable:Intravenous and subcutaneous formulations dominate hospital revenue pools due to rapid onset and controlled administration. United States hospital outpatient prospective payment system bundles constrain standalone pricing for these acute care staples.
- Transdermal:Patch-based delivery enables steady-state plasma levels without first-pass metabolism or GI absorption variability. Japanese METI reimbursement reforms for post-operative pain management are opening formulary access for transdermal combination products in tertiary hospitals.
- Oral:Tablets and capsules remain the default maintenance therapy format despite compromised bioavailability in opioid-induced GI hypomotility.
- Inhalation:Pulmonary delivery offers rapid systemic absorption for rescue scenarios, though device development costs and EMA MDR documentation burdens limit manufacturer participation.
Injectable formats process the highest patient throughput; transdermal delivery is expanding most quickly on share as home-based protocols extend treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA REMS mandates and EMA MDR documentation requirements are reshaping procurement patterns across acute care systems. Hospital purchasing committees now embed side-effect mitigation products directly into opioid prescribing workflows rather than reactive procurement.
United States
Chronic pain prevalence and Medicare bundled payment structures concentrate antagonist demand in tertiary hospitals. The FDA Risk Evaluation and Mitigation Strategy mandates prescriber training and patient monitoring protocols that expand formulary slots for peripherally acting antagonists. Greater Boston and the Pacific Northwest anchor clinical trial networks for pharmacogenomic-guided antagonist selection.
Germany
Hospital outpatient prospective payment reforms are accelerating adoption of combination therapies in perioperative protocols. EMA pharmacovigilance requirements under the EU Medical Device Regulation impose granular clinical documentation obligations on manufacturers seeking CE marking. The Rhine-Ruhr metropolitan region hosts purchasing consortia that demand pre-submitted MDR technical files as tender conditions.
Japan
METI reimbursement reforms for post-operative pain management are opening formulary access for transdermal combination products in tertiary hospitals. The country's aging surgical cohort creates sustained demand for patient-administered formats as home-based protocols extend treatment duration. The Kanto region around Tokyo concentrates pharmaceutical distribution infrastructure for antagonist therapies.
United Kingdom
NHS Integrated Care Systems are consolidating vendor relationships around integrated pain-and-side-effect bundles rather than discrete antagonist procurement. MHRA post-Brexit regulatory autonomy is diverging from EMA pharmacovigilance timelines for drug-device combinations. The Greater Manchester and West Midlands clusters host pilot programs for telehealth-enabled antagonist monitoring in home care settings.
India
CDSCO accelerated approval pathways for opioid side-effect mitigation products are attracting contract manufacturing investment from multinational sponsors. The country's central pharmaceutical regulator is harmonizing pharmacovigilance requirements with ICH guidelines to facilitate export-oriented production. Maharashtra and Gujarat host API manufacturing clusters for naloxegol and methylnaltrexone active pharmaceutical ingredients.
Opioid Induced Side Effects Treatment Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with hospital formulary relationships and specialty formulation developers with differentiated delivery technologies. The competitive terrain splits between acute-care injectable specialists and home-care format innovators. Three archetypes dominate: large-cap diversified pharmas with institutional access, mid-cap formulation specialists with platform technologies, and emerging biotechs with novel antagonist mechanisms. Consolidation pressures are forcing portfolio diversification into combination therapies and geographic expansion into Japanese and European hospital systems.
Among formulation specialists, Orexo AB and Camurus AB occupy positions defined by sublingual film and long-acting injectable platforms respectively. Pfizer Inc. anchors the diversified pharmaceutical tier with hospital formulary relationships sustaining access across acute care settings. These three entities exemplify how delivery technology differentiation and institutional procurement channel control determine competitive positioning in side-effect mitigation markets.
| Leading Market Players |
|---|
| Indivior PLC |
| Orexo AB |
| Pfizer Inc. |
| Alkermes |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Hikma Pharmaceuticals PLC |
| BioDelivery Sciences International Inc. |
| Camurus AB |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both European market entry and price stratification, with audit timelines stretching 18-24 months and forcing manufacturers to recover qualification costs through premium positioning against uncertified competitors.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement between multinational sponsors and Indian contract manufacturers. Pricing stratifies across ISO 13485-certified, FDA-registered, and standard GMP tiers, with certification premiums widening as EMA MDR documentation burdens intensify. Cost compression in the standard tier stems from Medicare bundled payment expansion in United States hospital outpatient settings. Home health agencies exhibit highest price sensitivity due to fixed per-episode reimbursements, while tertiary hospital systems absorb premium pricing for REMS-compliant integrated bundles.
Supply Chain Analysis
API manufacturing concentration in Maharashtra and Gujarat creates single-source vulnerability for naloxegol and methylnaltrexone precursors. Active pharmaceutical ingredients draw from Indian chemical intermediate clusters and Chinese specialty chemical feedstocks. Tariff exposure on Chinese imports threatens margin stability for formulation specialists without backward integration. Distribution runs through pharmaceutical wholesalers serving hospital systems and direct-to-pharmacy channels for retail-dispensed maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against non-opioid analgesic substitution, with peripheral nerve stimulation and regional anesthesia protocols capturing post-surgical volumes previously reserved for opioid-antagonist combinations.
For Market Incumbents: Secure formulary lock-in through Epic and Cerner EHR integration investments that embed antagonist prescribing into perioperative order sets. Deepen backward integration into Indian API manufacturing to offset tariff exposure on Chinese chemical intermediates. Counter regional anesthesia substitution by co-developing GI-protective formulations with biologics pipelines in oncology supportive care.
For New Entrants and Emerging Players: Telehealth-enabled remote patient monitoring represents the most penetrable service layer, with incumbent pharmaceutical manufacturers lacking digital infrastructure to support direct-to-patient distribution. Target skilled nursing facilities and home health agencies in United States Medicare expansion regions where sublingual film adoption runs twice the rate of traditional oral solids. Enter through white-label partnerships with established telehealth platforms bypassing hospital pharmacy gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core pain management assets amid portfolio rationalization pressures. Five-to-ten year viability hinges on pharmacogenomic testing integration that personalizes antagonist selection and extends product lifecycle. Monitor FDA REMS modification announcements as the critical inflection signal determining which delivery formats gain institutional procurement preference.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Shortens EMA MDR compliance timelines for drug-device combination manufacturers seeking CE marking. |
| Pharmacogenomic Testing Partnership | Enables CYP2D6-guided antagonist selection that improves therapeutic index in polypharmacy patients. |
| Telehealth Platform Integration | Creates direct-to-patient channels for home-use antagonist kits bypassing hospital pharmacy gatekeepers. |
| Indian API Manufacturing Investment | Reduces tariff exposure on Chinese chemical intermediates for naloxegol and methylnaltrexone production. |
| EHR Decision Support Module Development | Secures prescribing workflow placement in Epic and Cerner installations dominating United States hospital systems. |
Study Parameters
The analysis maps peripherally acting antagonists, combination therapies, and non-pharmacological interventions, each validated through hospital formulary directors, regulatory affairs specialists, and home health procurement managers. Primary interviews with GPO contracts managers and pharmacy benefit managers combined with secondary validation against FDA REMS documentation, EMA MDR technical files, CMS Medicare claims data, and hospital procurement databases. Bottom-up patient volume modeling and top-down revenue triangulation cross-checked segmentation outputs.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions included product type, therapy area, end user setting, and delivery mode, with regional regulatory clusters capturing FDA, EMA, and METI framework variations. CAGRs derived from patient population growth, procedure volume trends, and formulary expansion rates. Forecast inputs incorporated REMS compliance penetration curves and pharmacogenomic testing adoption trajectories.
Forecasts assume regulatory continuity in FDA REMS and EMA MDR regimes; material policy shifts would require re-modeling of hospital procurement behavior and certification timelines. Practitioners should keep alternative scenarios live as pharmacogenomic standard-of-care integration and non-opioid analgesic substitution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Topical Pain Relief Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Global Morphine Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
OTC Painkiller Market
Pain Management
Global Chiropractic Care Market
Pain Management
Pain Relief Oil Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Palliative Care Market
Pain Management
Spine Pain Market
Pain Management
Neuralgia Treatment Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Heat Therapy Market