
 Ankylosing Spondylitis Market | 2026-2036
Ankylosing Spondylitis Market Size, Share, and Industry Trends Forecast 2026-2036
Ankylosing Spondylitis Market Intelligence
Aftermarket patient support and adherence programs is reshaping profitability in the Ankylosing Spondylitis landscape, pulling margin pools away from pure drug dispensing toward outcome-linked services. AbbVie Inc. leverages its immunology infrastructure to sustain high-touch patient onboarding across specialty pharmacy networks. Pfizer Inc. competes through biosimilar development capabilities that anchor cost positioning in competitive tender markets. Novartis AG differentiates via integrated digital monitoring tools that extend therapy persistence rates.
Ankylosing spondylitis constitutes a chronic inflammatory arthritis primarily affecting the axial skeleton, characterized by enthesitis, sacroiliitis, and progressive spinal fusion driven by HLA-B27-associated immune dysregulation; biologic therapies targeting IL-17 and TNF-alpha pathways have transformed disease modification by halting radiographic progression in moderate-to-severe cases. The biologics segment captures the dominant value share within product type classification, while the NSAIDs category retains substantial volume leadership as maintenance therapy for mild disease. Rheumatology dominates therapy area allocation, though pain management channels are expanding fastest as multidisciplinary care protocols integrate non-pharmacological intervention.
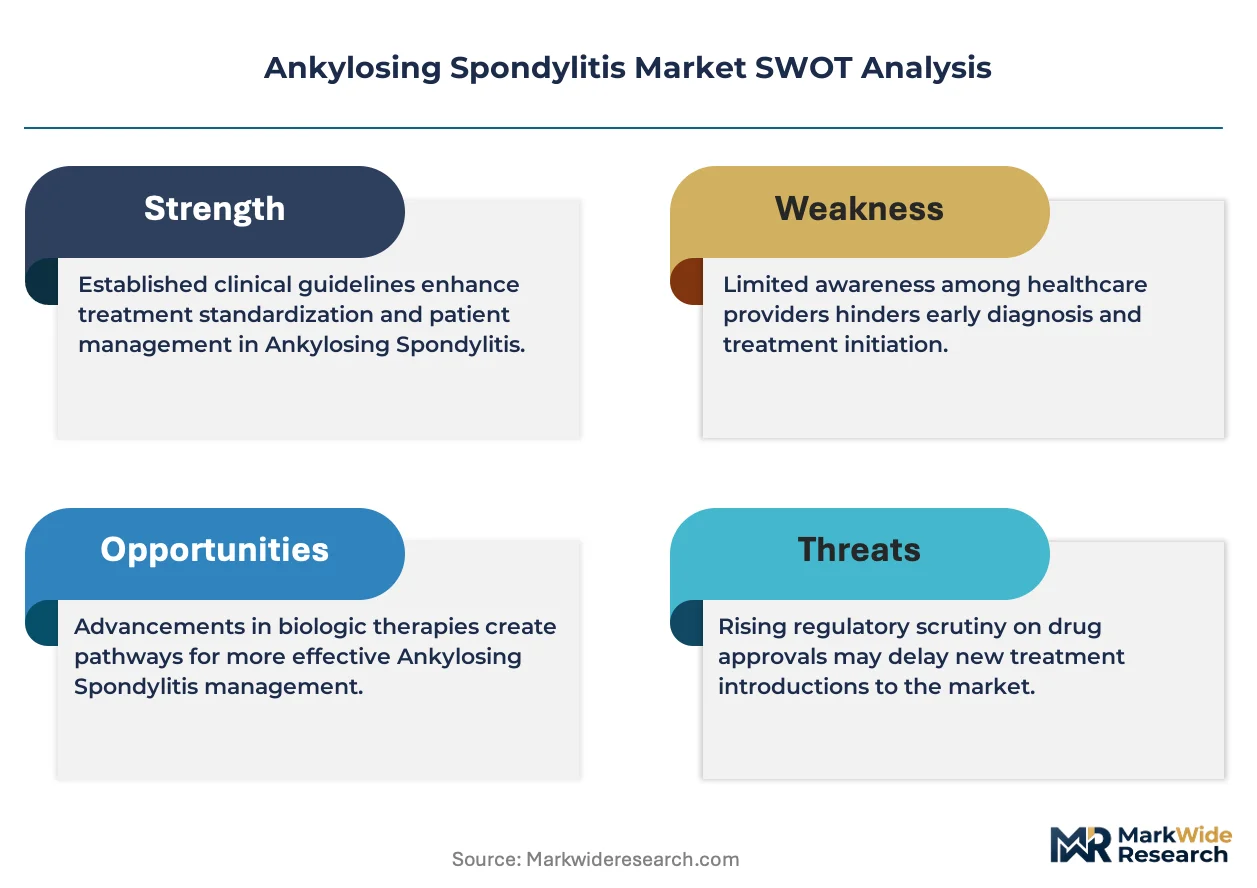
The FDA maintains stringent post-market surveillance requirements for biologic agents through REMS programs, while the EMA's MDR framework elevates clinical evidence standards for sustained market access across European member states. The IRA's Medicare price negotiation provisions directly reshape revenue architecture for established TNF inhibitors approaching exclusivity expiry. Stakeholders must monitor biosimilar substitution mandates and real-world evidence requirements as these regulatory instruments redefine competitive moats.
Market Dynamics
Biologic therapy pipelines are compressing development timelines through FDA accelerated approval pathways, while integrated care networks concentrate patient volumes into specialty rheumatology clinics that demand outcome-linked contracting.
Growth Catalysts
- IL-17 inhibitor expansion:Next-generation biologics targeting the IL-23/IL-17 axis demonstrate superior radiographic halting in head-to-head trials against TNF-alpha inhibitors, expanding eligible patient pools.
- Specialty pharmacy infrastructure:High-touch patient onboarding programs through integrated specialty networks improve therapy persistence and reduce discontinuation rates in moderate-to-severe cohorts.
- IRA Medicare negotiation provisions:Price transparency mandates for established biologics approaching exclusivity expiry accelerate biosimilar substitution protocols in US government channels.
Market Restraints
- Biologic manufacturing concentration:Active pharmaceutical ingredient production for monoclonal antibodies clusters in single-source contract manufacturing organizations, creating supply vulnerability.
- REMS program friction:FDA-mandated Risk Evaluation and Mitigation Strategies impose prescriber certification requirements that slow therapy initiation in community rheumatology practices.
- NSAID maintenance anchoring:Mild disease patients exhibit strong persistence with non-steroidal anti-inflammatory drugs, delaying biologic escalation and compressing addressable market expansion.
Strategic Opportunities
- Digital biomarker integration:Wearable spinal mobility monitoring combined with patient-reported outcome platforms enables remote disease activity tracking and personalized dosing algorithms.
- Multidisciplinary pain protocols:Physical therapy and cognitive behavioral intervention bundled with pharmacotherapy creates service revenue streams beyond drug dispensing margins.
- EMA MDR framework alignment:Elevated clinical evidence standards for European market access favor sponsors with robust real-world data infrastructure and post-market surveillance capabilities.
Industry Challenges
- Rheumatology workforce scarcity:Fellowship-trained specialists concentrate in academic medical centers, leaving community practices with limited biologic initiation expertise.
- Real-world evidence integration:Payers demand outcomes data from integrated data networks that require costly interoperability investments across electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ankylosing Spondylitis Market |
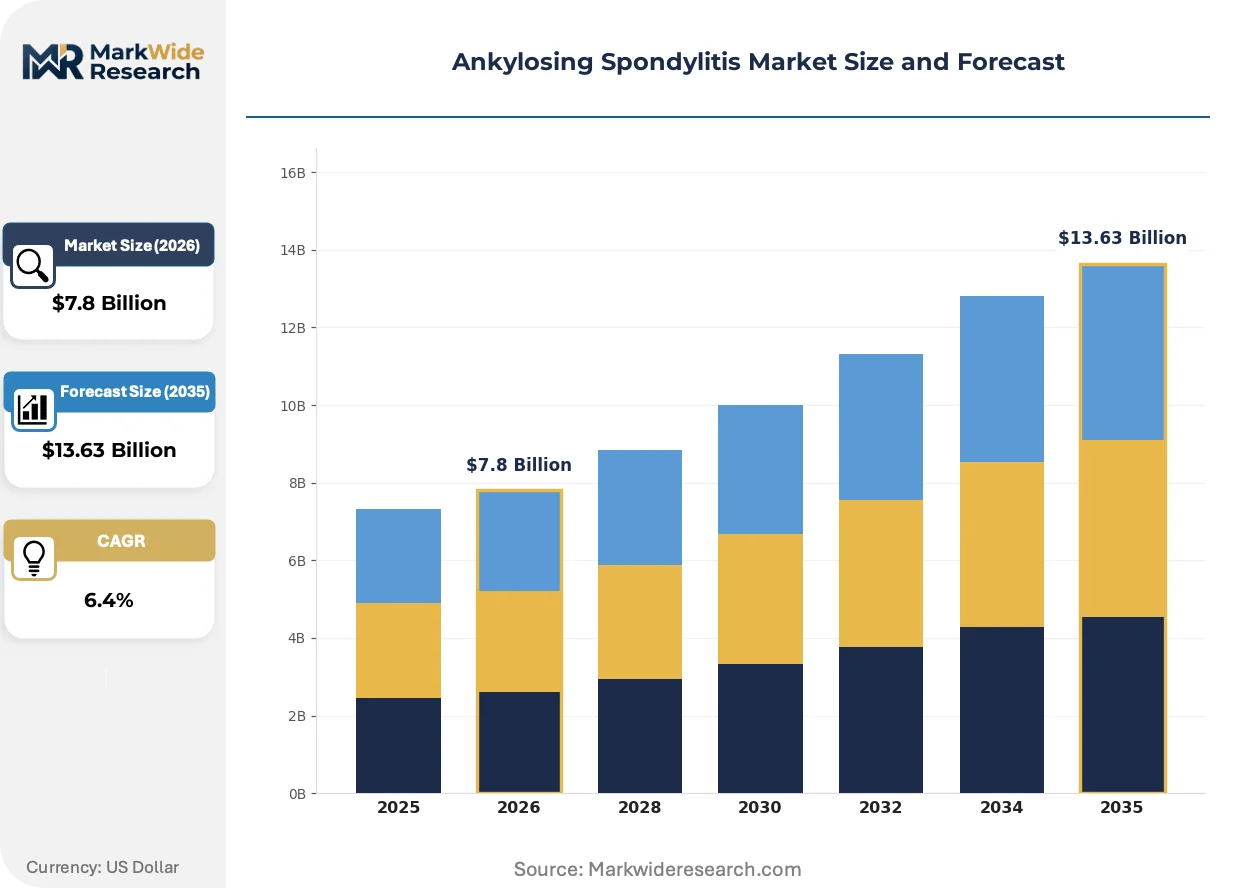
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Biologics, DMARDs, Corticosteroids Therapy Area: Rheumatology, Immunology, Orthopedics, Pain Management Administration Route: Oral, Injection, Intravenous, Topical End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | AbbVie Inc., Pfizer Inc., Novartis AG, Amgen Inc., Johnson & Johnson, Eli Lilly and Company, UCB S.A., Merck & Co., Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ankylosing Spondylitis Market Strategic Shifts & Innovations
Patient support ecosystems are displacing pure product-centric models, with stakeholders embedding digital adherence tools and remote monitoring into therapy protocols to extend persistence curves.
Biosimilar development platforms are migrating from simple bioanalytical equivalence toward interchangeable designation pathways that enable pharmacy-level substitution without prescriber intervention. Rheumatology clinics in competitive tender markets are prioritizing these agents to protect formulary positioning. The structural consequence is margin compression for originator molecules approaching patent cliff, forcing sponsors to defend position through outcome guarantees rather than clinical differentiation alone.
EMA's Medical Device Regulation framework elevates clinical evidence requirements for diagnostic devices used in disease monitoring and treatment selection. Manufacturers of spinal mobility assessment tools must now demonstrate analytical validity through prospective studies. European integrated care networks are responding by consolidating procurement around vendors with established MDR technical documentation, excluding smaller device developers lacking regulatory infrastructure.
Aftermarket service unbundling is fragmenting traditional pharmaceutical revenue architecture. Specialty pharmacies now compete on adherence coaching and injection training rather than dispensing efficiency alone. This shift is most visible in United States commercial channels where integrated delivery networks negotiate outcomes-based contracts that tie reimbursement to therapy persistence metrics measured at six-month intervals.
Ankylosing Spondylitis Market Segmentation
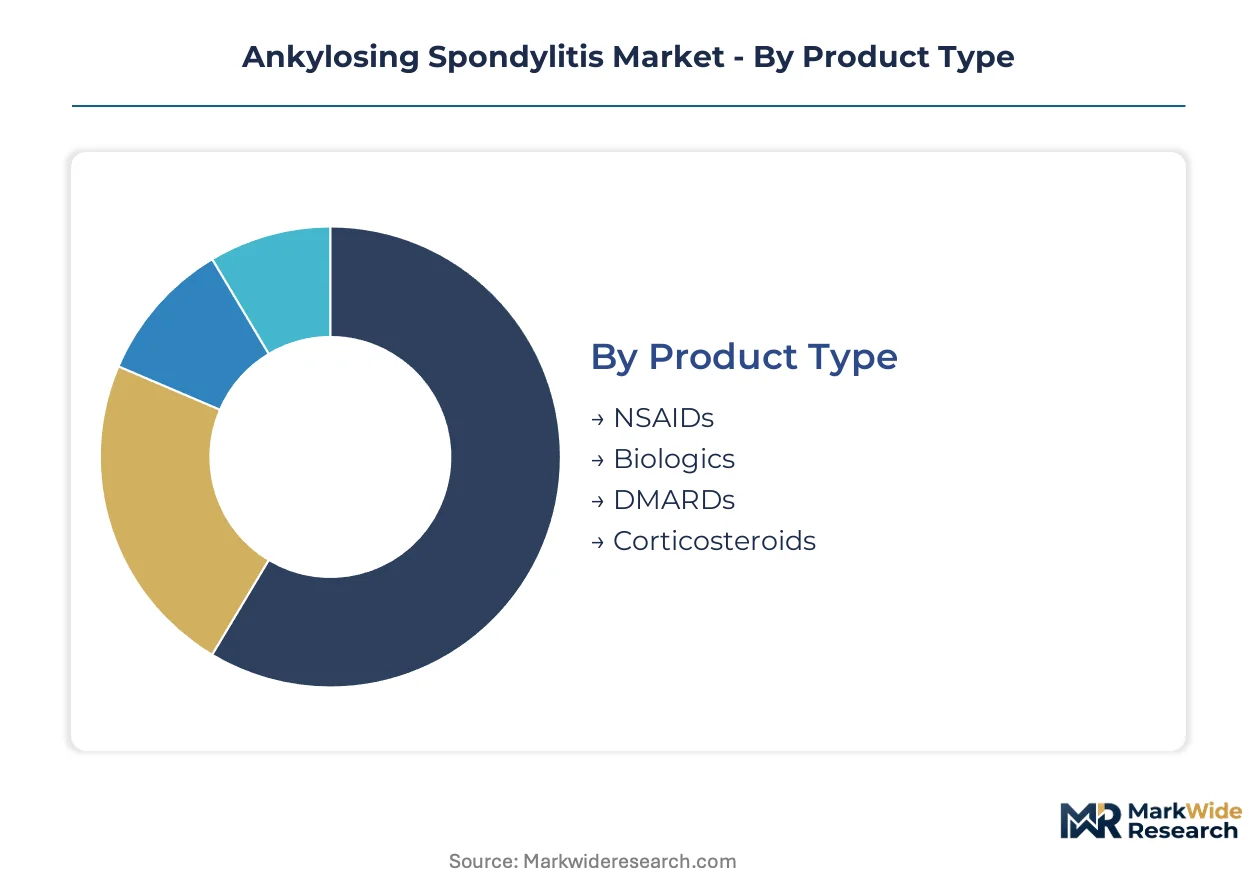
Ankylosing spondylitis treatment pathways diverge sharply by disease severity and patient risk stratification, creating distinct commercial segments with incompatible pricing architectures. Biologic eligibility criteria and administration logistics fragment the addressable population across four structural dimensions.
Product Type:
The use-case spectrum spans maintenance therapy for mild axial symptoms through disease-modifying intervention for progressive spinal fusion.
- Biologics:Monoclonal antibodies targeting IL-17 and TNF-alpha pathways halt radiographic progression in HLA-B27-positive patients with sacroiliitis. United States integrated care networks concentrate demand here as first-line intervention for moderate-to-severe disease, driven by FDA accelerated approval pathways compressing prescriber adoption timelines.
- NSAIDs:Non-steroidal anti-inflammatory drugs remain the foundational maintenance therapy for mild disease, with sustained-release formulations extending dosing intervals. Patient persistence with NSAIDs delays biologic escalation, particularly in European markets where EMA cost-effectiveness thresholds restrict early biologic access.
- DMARDs:Disease-modifying antirheumatic drugs address peripheral arthritis manifestations in spondyloarthritis spectrum patients.
- Corticosteroids:Short-course systemic and local injection formulations manage acute flares and enthesitis breakthrough symptoms.
The dominant share belongs to Biologics, while NSAIDs is closing the gap fastest through sustained-release formulation innovation expanding mild-disease capture.
Therapy Area:
Cost tier stratification separates high-complexity biologic management from protocolized pain intervention.
- Rheumatology:Fellowship-trained specialists in academic medical centers drive biologic initiation and radiographic monitoring protocols. United States demand concentrates in metropolitan specialty clinics with infusion center infrastructure, constrained by workforce scarcity leaving community practices with limited disease-modifying expertise.
- Pain Management:Multidisciplinary protocols integrating physical therapy and cognitive behavioral intervention are expanding fastest as integrated care networks bundle non-pharmacological services. Germany and the United Kingdom lead adoption here, with national health systems reimbursing bundled intervention codes.
- Immunology:Cross-disciplinary management addresses systemic inflammation and extra-articular manifestations including uveitis and inflammatory bowel disease.
- Orthopedics:Surgical intervention for severe spinal deformity and hip replacement in end-stage disease.
Rheumatology commands the highest per-patient revenue, though Pain Management is expanding most quickly through multidisciplinary bundling.
Administration Route:
Volume distribution reflects patient self-efficacy and reimbursement infrastructure for supervised infusion.
- Injection:Subcutaneous biologics and NSAID formulations dominate patient-managed therapy, with prefilled syringes and auto-injectors reducing training burden. United States specialty pharmacy networks compete on adherence coaching for this segment, with six-month persistence metrics driving outcomes-based contracts.
- Intravenous:Hospital and infusion center administration captures biologics requiring clinical monitoring, particularly for loading dose protocols. France and Italy maintain higher IV shares due to national reimbursement restricting home administration.
- Oral:NSAIDs and conventional DMARDs for maintenance therapy in mild-to-moderate disease.
- Topical:Localized corticosteroid delivery for enthesitis and peripheral joint involvement.
Injection holds the dominant patient volume position, while Intravenous is gaining share fastest through infusion center network expansion.
End User:
Customer type fragmentation reflects site-of-care economics and therapy complexity gradients.
- Clinics:Specialty rheumatology practices concentrate biologic prescribing and disease activity monitoring, with United States integrated delivery networks consolidating referrals into high-volume centers. REMS program certification requirements favor clinic-based initiation over community practice.
- Homecare:Self-administered subcutaneous biologics and oral maintenance therapies are shifting fastest here, supported by United States specialty pharmacy high-touch onboarding programs improving persistence curves.
- Hospitals:Acute flare management, surgical intervention, and IV biologic loading doses.
- Rehabilitation Centers:Physical therapy protocols and post-surgical functional recovery programs.
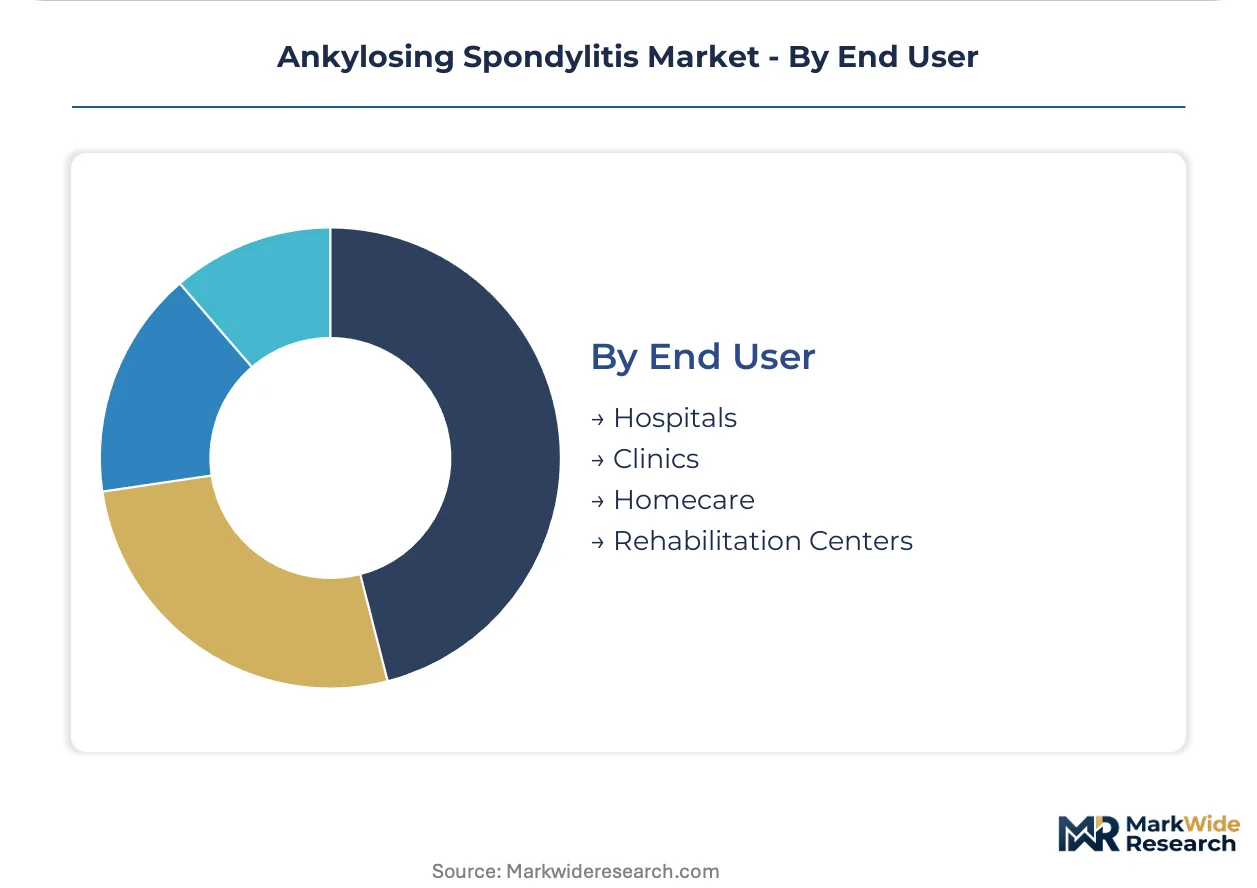
Clinics retain the dominant share of biologic-initiating encounters, while Homecare is climbing the fastest through patient support ecosystem maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States integrated care networks prioritize biologic first-line intervention, while European systems enforce cost-effectiveness thresholds that delay escalation. Asian markets exhibit pronounced heterogeneity between reimbursed biologic access in Japan and out-of-pocket NSAID maintenance in India.
United States
Specialty rheumatology clinics concentrate biologic prescribing through integrated delivery networks, with Medicare Advantage plans driving outcome-linked contracting. FDA REMS programs for TNF-alpha and IL-17 inhibitors impose prescriber certification requirements. The Boston-Cambridge corridor anchors biologic manufacturing infrastructure, with Massachusetts-based contract manufacturing organizations supplying monoclonal antibody active pharmaceutical ingredients.
Germany
Statutory health insurance funds enforce IQWiG cost-effectiveness assessments that restrict early biologic access to rapid radiographic progressors. EMA MDR framework compliance elevates evidence requirements for diagnostic devices used in spinal mobility monitoring. The Rhine-Ruhr metropolitan region concentrates pain management infrastructure, with Essen and Düsseldorf leading multidisciplinary protocol adoption.
Japan
PMDA accelerated approval pathways compress timelines for IL-17 inhibitors, while universal health coverage maintains broad biologic reimbursement. Ministry of Health, Labour and Welfare price adjustment rules trigger biennial price cuts for established therapies. The Kanto region around Tokyo dominates rheumatology specialist concentration, with academic medical centers in Chiba and Saitama driving biologic initiation protocols.
United Kingdom
NICE technology appraisals enforce cost-per-QALY thresholds that delay biologic access until NSAID failure is documented. NHS England integrated care systems are consolidating rheumatology referrals into high-volume centers. The Greater Manchester cluster leads outcome-based contracting pilots, with Salford Royal NHS Foundation Trust testing therapy persistence guarantees.
India
Out-of-pocket expenditure dominates mild-to-moderate disease management, with NSAID maintenance anchoring treatment pathways for uninsured populations. CDSCO accelerated approval pathways for biosimilars are expanding domestic manufacturing capacity. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient production, with Telangana-based contract manufacturers supplying biologic drug substances.
Ankylosing Spondylitis Market Key Industry Players
Capability concentration sits with integrated immunology specialists; scale advantage sits with diversified pharmaceutical conglomerates. The market structure exhibits tiered consolidation, with originator biologic sponsors defending position through outcome guarantees while biosimilar developers compete on interchangeable designation pathways. Three archetypes dominate: vertically integrated biologic manufacturers, specialty pharmacy service providers, and digital adherence platform vendors. Competitive moves center on M&A for patient support infrastructure and strategic partnerships for real-world evidence generation.
Among diversified pharmaceutical conglomerates, AbbVie Inc., Pfizer Inc., and Novartis AG exemplify distinct strategic positioning. AbbVie Inc. represents the integrated immunology archetype with established specialty pharmacy relationships. Pfizer Inc. anchors the biosimilar development tier through cost-positioning capabilities in tender markets. Novartis AG occupies the digital integration vector, with patient monitoring platforms extending therapy persistence. These three entities collectively illustrate how originator sponsors are unbundling pure product models toward outcome-linked service architectures.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| UCB S.A. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Others |
Cost & Logistics Intelligence
Single-source contract manufacturing organization concentration for monoclonal antibody active pharmaceutical ingredients creates simultaneous vulnerability in supply continuity and pricing power, compressing margin spreads between originator biologics and interchangeable biosimilars while forcing sponsors toward outcome-linked contracting to defend position.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and specialty pharmacies dominate United States commercial channels, with six-month therapy persistence metrics driving outcomes-based reimbursement tiers. Price differentiation rests on REMS program certification status and interchangeability designation pathways that enable pharmacy-level substitution without prescriber intervention. Cost compression in the TNF-alpha inhibitor category is intensifying as Medicare price negotiation provisions approach exclusivity expiry for established molecules. Community rheumatology practices exhibit highest price sensitivity due to limited infusion infrastructure, while academic medical centers with captive pharmacy networks maintain lowest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China for bioprocessing equipment components elevates total cost of ownership for monoclonal antibody manufacturing facilities. Active pharmaceutical ingredient production clusters in Massachusetts, Puerto Rico, and Ireland, with mammalian cell culture media and single-use bioreactor systems drawing from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in contract manufacturing organizations holding exclusive fill-finish capacity for prefilled auto-injector devices. Distribution runs through integrated specialty pharmacy networks that compete on adherence coaching rather than dispensing efficiency alone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket patient support services are expanding faster than drug dispensing margins, with adherence coaching and remote monitoring creating recurring revenue layers that outperform pure product economics.
For Market Incumbents: Harden outcome guarantee capabilities through real-world evidence infrastructure investments that defend against interchangeable biosimilar substitution. Anchor high-touch patient onboarding programs across specialty pharmacy networks to extend therapy persistence curves. Secure backward integration into diagnostic device partnerships that support spinal mobility monitoring bundled with biologic therapy. For New Entrants and Emerging Players: Establish a beachhead in pain management channels where multidisciplinary protocol bundling creates service revenue streams beyond drug margins. Target community rheumatology practices underserved by academic medical center concentration, offering REMS program certification support and infusion infrastructure partnerships. Lead with digital adherence platform integration that differentiates against originator-sponsored patient support ecosystems. For Investors and Strategic Acquirers: The market sits at a biosimilar penetration phase that favors vertically integrated manufacturers with interchangeable designation pathways and European MDR technical documentation capabilities. Long-term viability favors sponsors with captive specialty pharmacy relationships and robust post-market surveillance infrastructure. Watch FDA accelerated approval pathway expansion for IL-23/IL-17 axis inhibitors as the signal indicating originator defense strategy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeable Biosimilar Development | Pharmacy-level substitution without prescriber intervention reshapes competitive positioning in tender markets. |
| Real-World Evidence Infrastructure | Post-market surveillance capabilities satisfy EMA MDR framework requirements for European market access. |
| Specialty Pharmacy Partnership | High-touch patient onboarding programs improve six-month therapy persistence metrics driving reimbursement. |
| Digital Biomarker Integration | Wearable spinal mobility monitoring enables remote disease activity tracking and personalized dosing algorithms. |
| Multidisciplinary Pain Protocol | Physical therapy and cognitive behavioral intervention bundling creates service revenue beyond drug dispensing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA REMS program documentation, EMA MDR technical file databases, and Medicare formulary coverage decisions. Interviews with rheumatology fellowship directors, specialty pharmacy operations executives, payer access specialists, and biologic manufacturing quality leads were triangulated against ClinicalTrials.gov registry entries, SEC 10-K immunology segment disclosures, and IQWiG cost-effectiveness assessments. Bottom-up patient volume modeling and top-down pharmaceutical revenue reconciliation anchored segmentation outputs.
Forecast inputs span treatment line progression, administration route migration, patient risk stratification, and regional regulatory cluster evolution across the projection horizon. Analytical frameworks modeled biologic eligibility criteria expansion, NSAID-to-biologic escalation rates, and biosimilar substitution velocity by channel type. CAGRs were derived from trend extrapolation adjusted for Medicare price negotiation impact and IL-17 inhibitor pipeline entry assumptions.
Stress conditions across IRA negotiation timeline acceleration, rheumatology workforce scarcity deepening, and single-source manufacturing disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding biosimilar interchangeability designation timelines and EMA MDR enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market