
 Soft Tissue Sarcoma Market | 2026-2036
Soft Tissue Sarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tissue Sarcoma Market Outlook
The sarcoma-specialist clinician workforce is collapsing across community oncology networks, forcing complex cases toward tertiary centers where F. Hoffmann-La Roche Ltd. leverages its diagnostic-treatment integration and Bristol Myers Squibb sustains broad immuno-oncology development. Novartis AG anchors its position through radioligand therapy infrastructure. Pfizer Inc. competes via kinase inhibitor specialization while Merck & Co., Inc. differentiates through checkpoint inhibitor combinations in underserved histologies.
Soft tissue sarcoma encompasses malignant neoplasms arising from mesenchymal tissues including fat, muscle, nerve, and connective tissue, characterized by histologic diversity across more than fifty subtypes with variable grades and metastatic potential. These tumors require multimodal management integrating systemic therapy with surgical resection and radiation. Immunotherapy commands expanding development investment as checkpoint inhibitors demonstrate activity in specific translocation-associated subtypes, while targeted therapy occupies narrower but higher-margin niches defined by actionable genomic alterations. Hospitals dominate the end user landscape due to infrastructure requirements for multidisciplinary sarcoma boards, though ambulatory surgical centers are capturing selected infusion visits as oral regimens proliferate.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks shape how sponsors design pivotal trials for rare sarcoma subtypes, compressing timelines but demanding robust confirmatory evidence. The EU AI Act introduces new compliance dimensions for diagnostic algorithms used in histopathologic classification. Stakeholders must monitor how regulatory convergence on real-world evidence standards affects post-approval commitment feasibility and portfolio prioritization across histology-specific development programs.
Market Dynamics
The central structural force reshaping soft tissue sarcoma treatment is the collapse of specialist clinical capacity in community settings, which is concentrating complex case management within tertiary academic centers equipped for genomic stratification and multimodal therapy coordination.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for rare sarcoma subtypes are incentivizing sponsors to pursue histology-specific indications with biomarker-enriched trial designs.
- Radioligand Therapy Infrastructure:Academic medical centers in Germany and the United States are deploying alpha-emitter and beta-emitter delivery systems for metastatic disease.
- Genomic Profiling Adoption:Next-generation sequencing panels are expanding across oncology practices, identifying actionable fusions in translocation-driven subtypes.
Market Restraints
- Specialist Workforce Scarcity:Fellowship-trained sarcoma medical oncologists and orthopedic oncologists concentrate in fewer than fifty United States institutions, creating access bottlenecks.
- Confirmatory Evidence Burden:EMA conditional marketing authorization frameworks demand robust post-approval commitment feasibility that stretches smaller sponsors.
- Orphan Drug Cost Structures:Small addressable populations per histology limit pricing flexibility for targeted agents against kinase inhibitors.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:Priority review pathways for innovative oncology products create first-mover positioning in Asia-Pacific's second-largest pharmaceutical market.
- Ambulatory Infusion Migration:Oral tyrosine kinase inhibitors and subcutaneous immunotherapy formulations are shifting selected treatment visits from hospitals to specialized infusion centers.
- Real-World Evidence Integration:EU regulatory convergence on post-approval study standards enables label expansion through patient registry data rather than prospective trials.
Industry Challenges
- Histopathologic Classification Complexity:WHO classification updates every five years create diagnostic algorithm revalidation requirements for digital pathology platforms.
- Cross-Border Trial Recruitment:Rare subtype prevalence necessitates multi-country enrollment, exposing sponsors to divergent national ethics committee timelines.
- Supply Chain Cold-Chain Integrity:Cell therapy and radiopharmaceutical products require temperature-controlled logistics that few contract manufacturers can guarantee.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tissue Sarcoma Market |
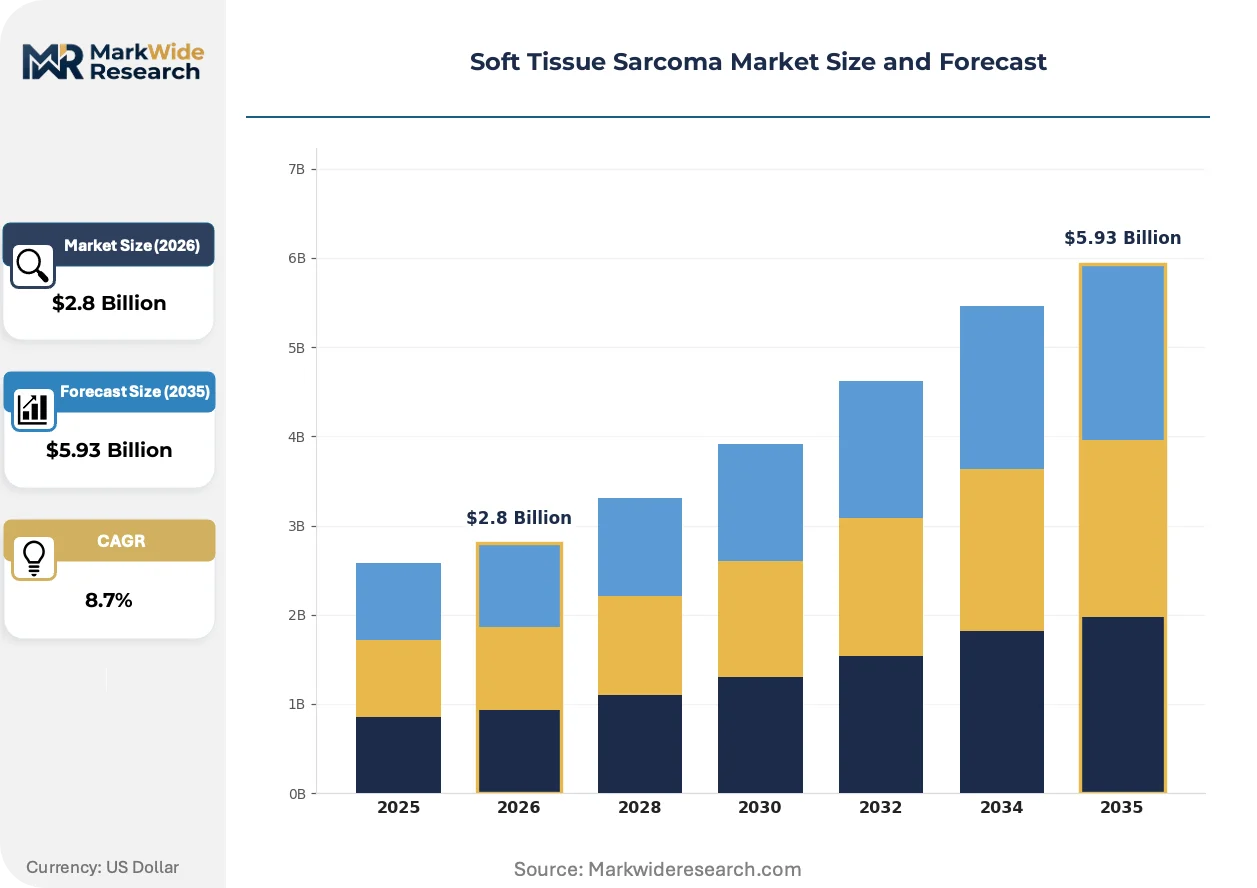
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Therapy Area: Oncology, Pain Management, Palliative Care, Genetic Disorders Delivery Mode: Intravenous, Oral, Subcutaneous, Surgical |
| Companies Covered | F. Hoffmann-La Roche Ltd., Pfizer Inc., Bristol Myers Squibb, Novartis AG, Bayer AG, Eli Lilly and Company, AstraZeneca plc, Merck & Co., Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tissue Sarcoma Market Strategic Shifts
Checkpoint inhibitor development is fragmenting across histology-specific biomarker subsets, while regulatory frameworks and care delivery models undergo parallel recalibration to accommodate precision oncology workflows.
Artificial intelligence diagnostic tools are fragmenting traditional pathology workflows by automating immunohistochemistry pattern recognition and fusion detection. Academic medical centers in the United States and Germany are piloting these platforms for intraoperative margin assessment. The EU AI Act's risk classification system is forcing manufacturers to restructure conformity assessment procedures for algorithms supporting treatment decisions.
REACH authorization requirements for novel cytotoxic payloads are extending lead times for European manufacturing sites supplying clinical trial materials. Sponsors are responding by qualifying United States and Swiss contract manufacturing organizations as parallel supply sources. This geographic diversification is compressing European production capacity utilization for radiolabeled compounds.
Patient advocacy organizations are consolidating referral networks to direct complex cases toward centers with sarcoma-specific tumor boards. United States-based foundations are publishing outcomes data that steers commercial payer prior authorization decisions. This channel consolidation is disadvantaging community oncology practices lacking multidisciplinary infrastructure.
Soft Tissue Sarcoma Market Segmentation
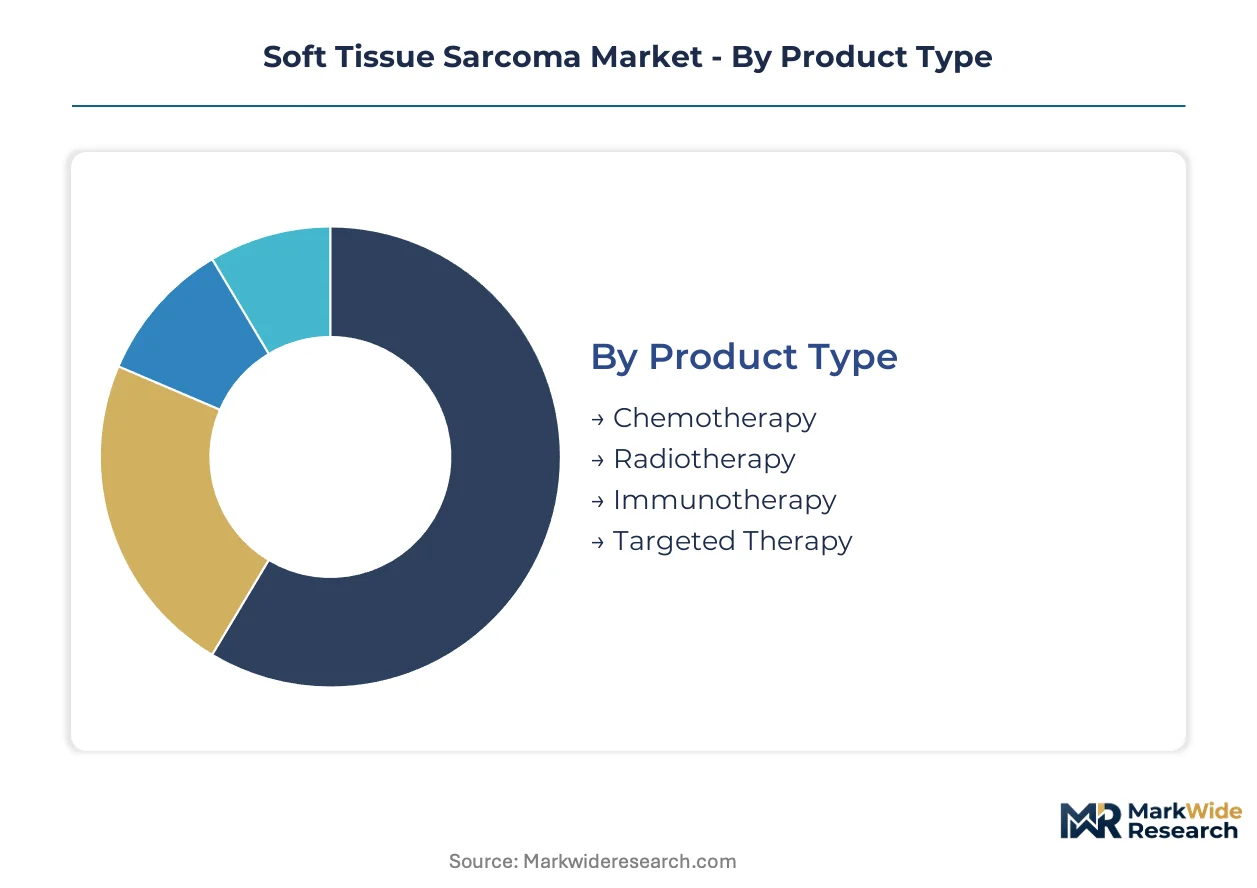
Soft tissue sarcoma treatment pathways fragment across therapeutic modalities and care settings, with channel economics dictating where specific interventions concentrate. Multimodal protocols require precise alignment between product characteristics and institutional capabilities.
Product Type:
Chemotherapy flows predominantly through hospital infusion centers with established cytotoxic handling protocols, while oral targeted agents migrate toward specialty pharmacy channels.
- Chemotherapy:Anthracycline-based regimens remain first-line systemic therapy for most histologies, with doxorubicin-ifosfamide combinations administered in tertiary centers equipped for cardiotoxicity monitoring. Demand concentrates in United States academic medical centers where sarcoma-specific protocols justify infrastructure investment.
- Targeted Therapy:Tyrosine kinase inhibitors including pazopanib and larotrectinib address actionable genomic alterations in translocation-driven subtypes. Germany and Japan lead adoption where companion diagnostic integration is strongest.
- Immunotherapy:Checkpoint inhibitors demonstrate activity in specific molecular subsets, requiring biomarker-enriched trial access.
- Radiotherapy:External beam and brachytherapy modalities integrate with surgical planning in multidisciplinary sarcoma boards.
By volume, chemotherapy leads. By growth pace, targeted therapy is expanding most quickly.
End User:
Institutional capabilities determine patient routing, with complex cases requiring genomic stratification concentrating where multidisciplinary infrastructure exists.
- Hospitals:Academic medical centers in the United States, Germany, and Japan dominate complex case management through sarcoma-specific tumor boards integrating surgical oncology, medical oncology, and radiation oncology. These centers capture referrals from collapsed community specialist networks.
- Ambulatory Surgical Centers:Selected infusion visits for oral kinase inhibitors and subcutaneous immunotherapy formulations shift to specialized outpatient settings as regimens proliferate. United States sites lead this migration.
- Clinics:Community oncology practices handle stable patients on maintenance therapy where protocols are standardized.
- Research Institutions:Phase I and II trial enrollment concentrates at sites with dedicated sarcoma programs and existing radioligand infrastructure.
Hospitals capture the majority of value. Ambulatory Surgical Centers are gaining share fastest.
Therapy Area:
Clinical focus determines reimbursement pathways and regulatory precedent, with oncology commanding development investment while supportive care occupies narrower niches.
- Oncology:Systemic therapy development targets histology-specific indications through FDA accelerated approval pathways, with checkpoint inhibitors and radioligand therapies commanding priority review. EMA conditional marketing authorization frameworks shape European confirmatory study design.
- Palliative Care:Symptom management protocols integrate with curative intent therapy, requiring coordination between tertiary centers and community hospice providers.
- Pain Management:Neuropathic pain from nerve sheath tumors drives specialized referral patterns.
- Genetic Disorders:Hereditary sarcoma syndromes including Li-Fraumeni syndrome require surveillance protocols at specialized centers.
Oncology dominates absolute spending. Palliative Care shows the steepest expansion trajectory as integration models mature.
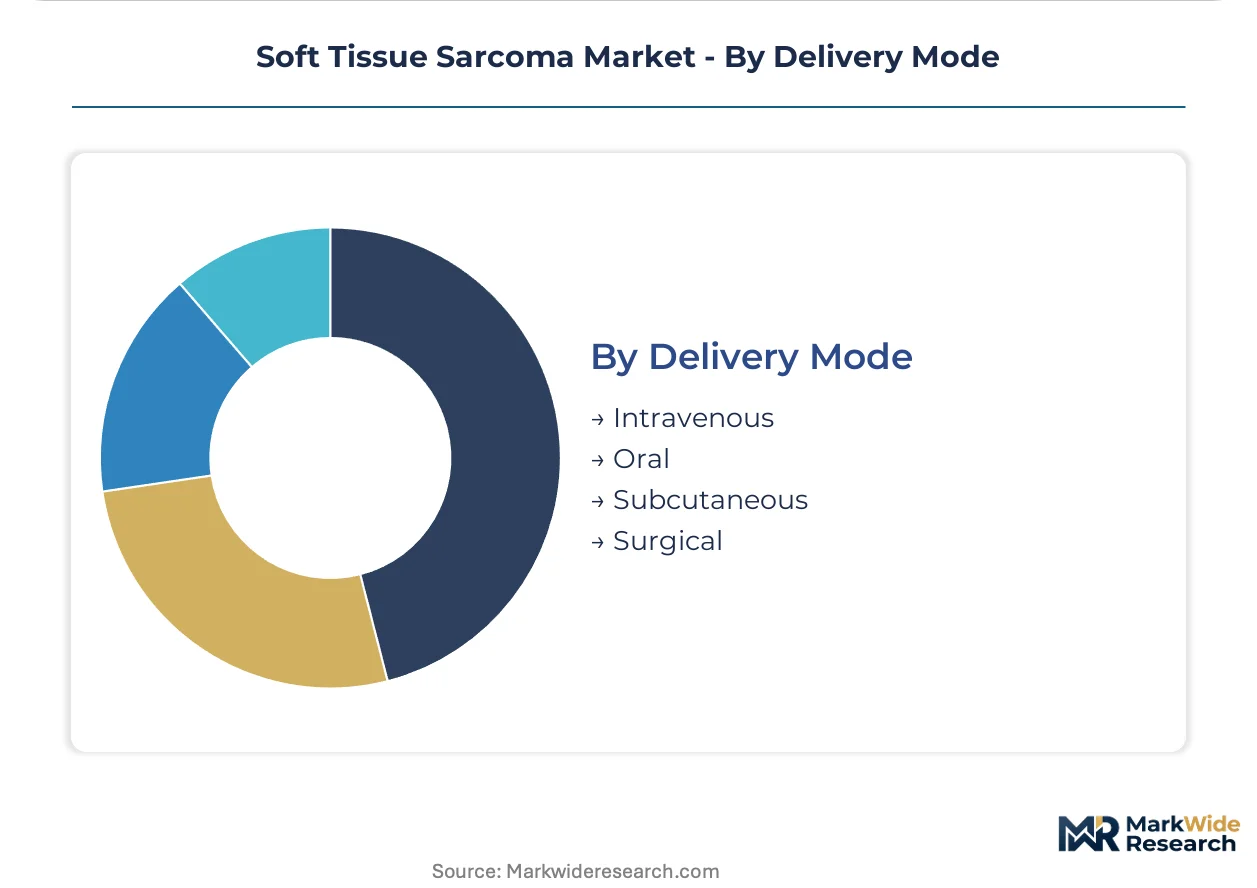
Delivery Mode:
Route of administration shapes site-of-care economics and patient compliance, with infusion requirements anchoring hospital utilization while oral options enable channel migration.
- Intravenous:Cytotoxic chemotherapy and monoclonal antibodies require infusion center capacity with nursing specialization in adverse event management. United States hospitals maintain this infrastructure most extensively.
- Oral:Tyrosine kinase inhibitors reduce treatment burden and enable community dispensing, though adherence monitoring remains challenging.
- Subcutaneous:Immunotherapy formulations under development promise reduced infusion chair time.
- Surgical:Resection remains definitive for localized disease, with margin assessment protocols varying by institution.
Intravenous administration leads by procedure volume. Oral delivery is climbing the fastest as kinase inhibitor portfolios expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for novel sarcoma therapies concentrates in the United States and Germany while Japan's reimbursement negotiations compress margins for comparable agents. This asymmetry reshapes where sponsors prioritize first launches and where they delay market entry.
United States
Academic medical centers in Houston, New York, and Boston attract complex referrals from collapsed community specialist networks. FDA accelerated approval pathways compress development timelines for histology-specific indications. The MD Anderson Cancer Center and Memorial Sloan Kettering anchor sarcoma-specific tumor board infrastructure that integrates genomic stratification with multimodal therapy coordination.
Germany
Radioligand therapy infrastructure at university hospitals in Heidelberg, Munich, and Essen drives adoption of alpha-emitter and beta-emitter delivery systems for metastatic disease. EMA conditional marketing authorization frameworks demand robust post-approval commitment feasibility that stretches smaller sponsors. The German Cancer Research Center anchors companion diagnostic integration for translocation-driven subtypes.
Japan
PMDA Sakigake designation creates first-mover positioning for innovative oncology products in Asia-Pacific's second-largest pharmaceutical market. National Health Insurance price negotiations constrain reimbursement for targeted agents against kinase inhibitors. The National Cancer Center Hospital in Tokyo concentrates Phase I and II trial enrollment for checkpoint inhibitor combinations in underserved histologies.
United Kingdom
NICE technology appraisals create access bottlenecks for high-cost targeted therapies despite strong academic research output. The NHS England specialized commissioning framework concentrates sarcoma surgery at designated supra-regional centers in London, Birmingham, and Manchester. The Royal Marsden Hospital anchors digital pathology pilot programs for immunohistochemistry pattern recognition.
Switzerland
Swissmedic approval timelines attract sponsors seeking parallel European launch strategies alongside EMA procedures. Basel and Zurich host radiopharmaceutical manufacturing clusters supplying clinical trial materials across Western Europe. Roche's diagnostic-treatment integration anchors specialized sarcoma centers in Lausanne and Geneva with companion diagnostic infrastructure.
Soft Tissue Sarcoma Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the soft tissue sarcoma market. Large-cap pharmaceutical conglomerates with integrated diagnostic capabilities dominate histology-specific indication development, while mid-size biotechnology firms concentrate on single-asset precision therapies for genomic subsets. Three archetypes define competitive positioning: broad immuno-oncology developers, radioligand therapy infrastructure builders, and kinase inhibitor specialists. M&A activity targets companion diagnostic capabilities, while strategic partnerships secure access to academic medical center trial networks.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify the diagnostic-therapy integration archetype, with Roche's tissue-agnostic development strategies and Novartis's radioligand infrastructure investments representing divergent paths to sarcoma market positioning. Bristol Myers Squibb anchors the broad immuno-oncology developer tier through checkpoint inhibitor portfolio breadth, while Merck & Co., Inc. occupies a comparable position through combination therapy development in molecular subsets. Pfizer Inc. represents the kinase inhibitor specialization archetype with targeted agent portfolios addressing actionable genomic alterations.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Bristol Myers Squibb |
| Novartis AG |
| Bayer AG |
| Eli Lilly and Company |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks gate both manufacturer qualification and reimbursement tiering simultaneously, compressing development timelines for histology-specific indications while stratifying price access across institutional buyers with genomic stratification capabilities.
Pricing Analysis
United States academic medical centers command premium pricing for novel checkpoint inhibitors and radioligand therapies against compressed Japanese reimbursement rates following PMDA Sakigake negotiations. Pricing stratifies across premium, standard, and economy tiers defined by biomarker-enrichment level, companion diagnostic bundling, and institutional volume commitments. Cost compression in oral kinase inhibitor segments intensifies as specialty pharmacy channels proliferate subcutaneous immunotherapy formulations. Community oncology practices exhibit highest price sensitivity due to collapsed sarcoma-specialist workforce capacity, while tertiary centers with multidisciplinary tumor boards absorb premium positioning.
Supply Chain Analysis
United States and Switzerland anchor radiopharmaceutical manufacturing clusters supplying alpha-emitter and beta-emitter clinical trial materials across Western Europe. Cold-chain logistics for cell therapy and radiolabeled compounds draw from specialized contract manufacturing organizations with temperature-controlled distribution certification. Single-source vulnerability concentrates in isotope production reactors supplying lutetium-177 and actinium-225 for targeted radioligand delivery. Distribution runs through hospital-based nuclear medicine pharmacies with cyclotron infrastructure, limiting ambulatory surgical center penetration for metastatic disease protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating toward United States academic medical centers with sarcoma-specific tumor boards, fragmenting community oncology practice influence over formulary decisions and channel routing.
For Market Incumbents: Fortify diagnostic-therapy integration through companion diagnostic infrastructure investments at Roche and Novartis, while securing exclusive trial network access at MD Anderson and Memorial Sloan Kettering against emerging radioligand therapy specialists. Backward integration into isotope production capacity hedges supply disruption for alpha-emitter portfolios. For New Entrants and Emerging Players: Lead with biomarker-enriched trial designs targeting underserved translocation-driven subtypes at German university hospitals in Heidelberg and Essen, where radioligand infrastructure exceeds patient recruitment capacity. White-space concentrates in subcutaneous immunotherapy formulations shifting selected infusion visits from tertiary centers to specialized ambulatory settings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radioligand therapy infrastructure buildouts, favoring platform acquisitions with existing isotope supply agreements and cyclotron networks over de novo manufacturing qualification. Acquisition targets with FDA breakthrough therapy designation and companion diagnostic partnerships offer strongest long-term viability signals through confirmatory study execution.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Roche's tissue-agnostic development strategies accelerate histology-specific indication timelines through integrated biomarker validation. |
| Radioligand Infrastructure Buildout | Novartis anchors metastatic disease positioning through alpha-emitter and beta-emitter delivery system deployment at German university hospitals. |
| Biomarker-Enriched Trial Design | Pfizer's kinase inhibitor specialization targets actionable genomic alterations with FDA accelerated approval pathway compression. |
| Subcutaneous Formulation Development | Merck's checkpoint inhibitor combinations enable ambulatory surgical center migration reducing hospital infusion chair dependency. |
| Real-World Evidence Integration | Bristol Myers Squibb leverages EU regulatory convergence on post-approval study standards for label expansion through patient registry data. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with sarcoma medical oncologists, regulatory affairs leads at pharmaceutical sponsors, hospital procurement managers at academic medical centers, and payer access specialists. Primary fieldwork with multidisciplinary tumor board directors and nuclear medicine pharmacists validated secondary data on radioligand therapy infrastructure deployment. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Variance decomposition across therapeutic modality, delivery route, and institutional capability dimensions shaped the analytical framework for projection horizon development. CAGRs derived from histology-specific prevalence modeling, treatment line penetration curves, and pricing tier elasticity estimates. Forecast inputs incorporated biomarker testing adoption rates, companion diagnostic co-approval timelines, and sarcoma-specialist workforce concentration indices.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA conditional marketing authorization frameworks; material policy shifts in orphan drug exclusivity periods or real-world evidence standards would require re-modeling. Recalibration cycles align with material shifts in biomarker-enriched trial readouts, radioligand therapy reimbursement decisions, and multidisciplinary center accreditation expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Global Cancer Biological Therapy Market