
 Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market | 2026-2036
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market Foresight
Orphan drug designation status is bifurcating the competitive landscape between developers with validated regulatory pathways and those without. Biogen leverages its established neurology infrastructure to sustain Riluzole distribution across major markets. Mitsubishi Tanabe Pharma Corporation anchors the Japanese market through deep relationships with domestic neurology centers. Amylyx Pharmaceuticals differentiates through its dual-mechanism approach that has reshaped prescriber expectations for new ALS entrants.
Amyotrophic lateral sclerosis treatment encompasses pharmacological and supportive interventions targeting upper and lower motor neuron degeneration, with drug candidates typically requiring demonstration of survival prolongation or functional score improvement in placebo-controlled trials. The primary purpose is slowing disease progression and preserving patient autonomy through multidisciplinary care. Motor neuron protection therapies currently occupy the largest addressable patient pool, while anti-inflammatory mechanisms represent the fastest-growing investigational focus as developers target neuroinflammation pathways. Oral administration dominates current revenue due to riluzole and edaravone tablet formulations, though intravenous injection formats command premium positioning in hospital-based neurology settings.
FDA orphan drug incentives and EMA's PRIME designation for neurological conditions shape which candidates receive priority review resources and market exclusivity periods. The EU AI Act and FDA guidance on decentralized clinical trials are altering how real-world evidence gets incorporated into ALS regulatory submissions. Stakeholders must monitor how health technology assessment bodies in Germany, France, and England are recalibrating cost-effectiveness thresholds for single-mechanism versus combination ALS therapies.
Market Dynamics
FDA and EMA orphan drug incentives are compressing development timelines and reshaping competitive entry patterns for ALS therapeutics. Developers now prioritize regulatory pathway validation over traditional commercial infrastructure buildout.
Growth Catalysts
- EMA PRIME Designation:Priority review resources accelerate neurological orphan drug assessments across European member states. German and French health technology assessment bodies align reimbursement timelines with accelerated regulatory approvals.
- Real-World Evidence Integration:FDA guidance on decentralized clinical trials enables broader patient recruitment through telemedicine-enabled neurology networks. Remote monitoring technologies capture functional score data outside traditional site-based settings.
- Neuroinflammation Targeting:Anti-inflammatory mechanisms represent the fastest-growing investigational focus as developers redirect R&D spend toward glial cell modulation pathways. Academic medical centers in Japan and the United States expand dedicated ALS biomarker discovery programs.
Market Restraints
- Specialized Neurology Infrastructure Concentration:ALS diagnosis and management capacity clusters in tertiary referral centers across Germany, the United States, and Japan. Patient access constraints outside these hub regions limit addressable population reach.
- Placebo-Controlled Trial Requirements:EMA and FDA survival prolongation endpoints demand extended study durations with high patient attrition rates. Trial cost structures escalate as enrollment competes for limited eligible participants.
- Single-Mechanism Therapy Ceiling:Riluzole and edaravone demonstrate modest efficacy profiles that constrain prescriber enthusiasm. Payers in England and France apply stringent cost-effectiveness thresholds to incremental therapeutic benefits.
Strategic Opportunities
- Combination Therapy Development:Dual-mechanism approaches targeting both oxidative stress and neuroinflammation pathways reshape prescriber expectations. Developers with validated regulatory pathways gain priority positioning for fast-track designations.
- Hospital-Based Infusion Services:Intravenous edaravone formats command premium positioning in Japanese and German neurology centers with dedicated infusion capacity. Site-of-care expansion creates service-based differentiation beyond oral formulations.
- Patient Registry Integration:Multidisciplinary care programs in the United States leverage longitudinal outcome tracking to demonstrate value. Real-world data infrastructure supports post-approval evidence generation for payer negotiations.
Industry Challenges
- Biomarker Validation Gaps:Reliable surrogate endpoints for disease progression remain elusive across motor neuron protection trials. Regulatory submissions depend on extended survival or ALSFRS-R functional score demonstrations with high variability.
- Specialized Neurology Workforce Scarcity:ALS-specific clinical expertise concentrates in academic medical centers. Community neurology practices lack training infrastructure for complex multidisciplinary care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market |
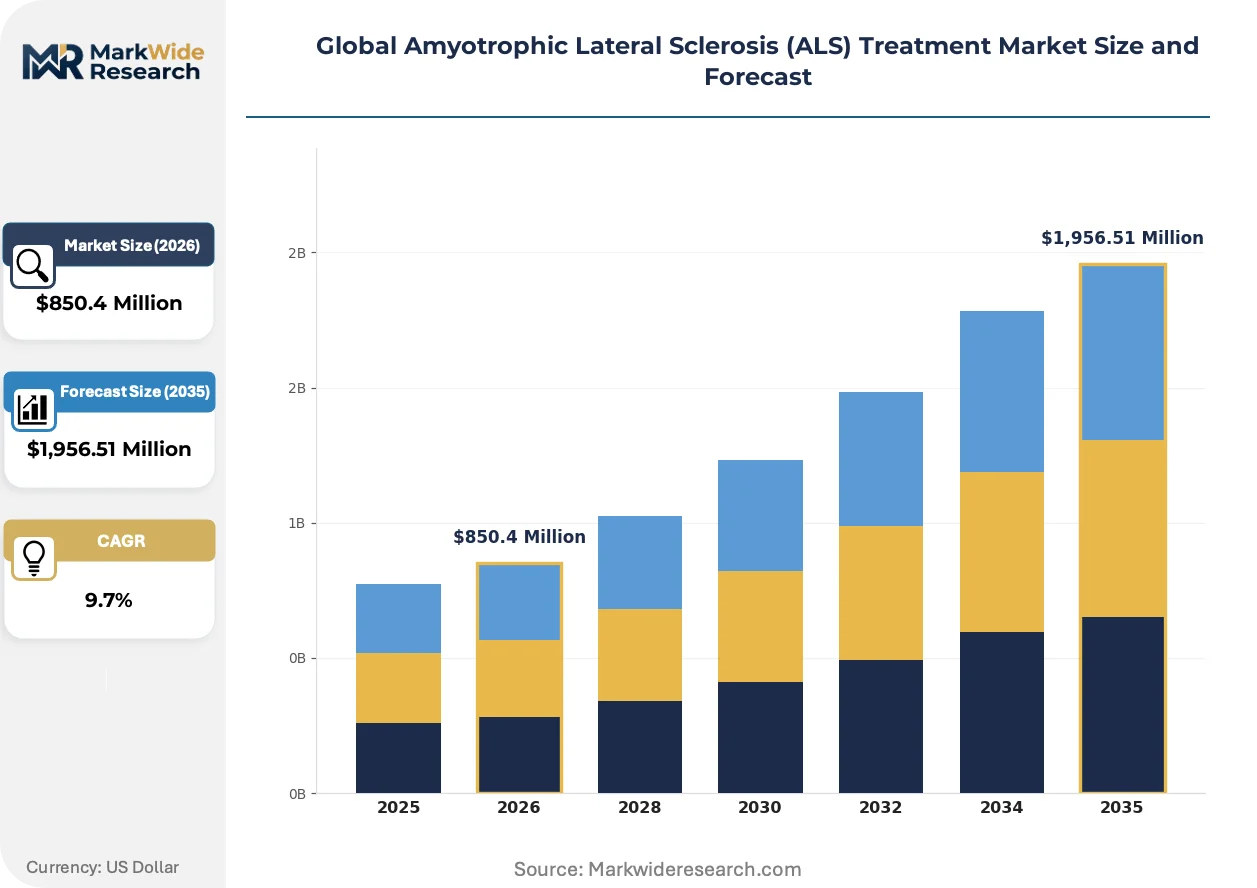
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,956.51 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riluzole, Edaravone, Sodium Phenylbutyrate, Tirasemtiv, Dexpramipexole Therapy Area: Motor Neuron Protection, Oxidative Stress Reduction, Anti-inflammatory, Muscle Strength Enhancement, Neurotransmission Modulation End User: Specialized Neurology Clinics, Rehabilitation Centers, Home Care Patients, Long-term Care Facilities, Research Institutes Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Injection, Nasal Spray, Transdermal Patch |
| Companies Covered | Biogen, Mitsubishi Tanabe Pharma Corporation, Amylyx Pharmaceuticals, BrainStorm Cell Therapeutics, Ionis Pharmaceuticals, Sanofi, F. Hoffmann-La Roche, Otsuka Pharmaceutical, Cytokinetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market Shifts & Advancements
Digital biomarker capture and decentralized trial infrastructure are compressing traditional clinical development timelines. Regulatory science advances enable faster evidence generation for rare neurodegenerative conditions.
Antisense oligonucleotide platforms targeting SOD1 and C9orf72 genetic subtypes are bifurcating the ALS therapeutic landscape. Precision medicine programs at Massachusetts General Hospital and University of California medical centers prioritize genetic screening for trial matching. Biomarker-driven patient stratification is compressing enrollment timelines and enabling targeted efficacy demonstrations in defined molecular subpopulations.
The EU AI Act establishes governance frameworks for algorithmic analysis of neurological imaging and speech pattern data. Developers incorporating AI-enabled progression monitoring must document training data provenance and performance validation. German and French regulators prioritize submissions with embedded algorithmic impact assessments for decentralized diagnostic tools.
Specialized ALS center networks are consolidating patient referrals away from general neurology practices. University of Tokyo Hospital and Heidelberg University Hospital anchor hub-and-spoke models that centralize clinical trial access. Site concentration demands that developers build dedicated field medical teams rather than deploying generalist sales infrastructure.
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market Segmentation
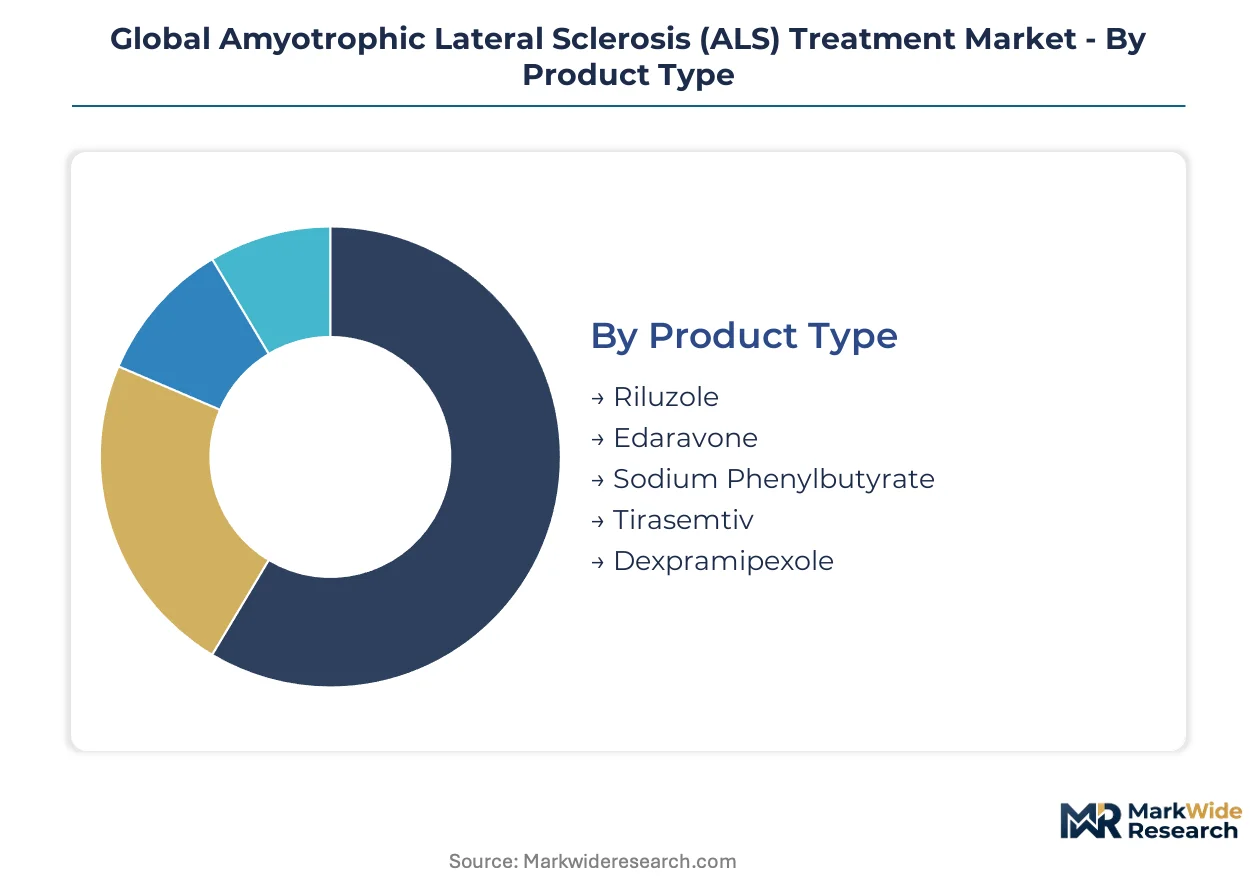
ALS treatment segmentation reveals how drug developers align formulation choices with site-of-care capabilities and prescriber workflows. Channel economics favor oral agents for community neurology while infusion-dependent therapies concentrate in academic medical centers.
Product Type:
Channel distribution splits between hospital pharmacy procurement for intravenous formats and retail specialty pharmacy for oral agents.
- Riluzole:The glutamate release inhibitor remains the foundational oral therapy distributed through specialty pharmacy networks. German and United States neurology clinics prescribe riluzole as first-line standard of care, though prescriber enthusiasm is tempered by modest survival benefits.
- Edaravone:Free radical scavenger available in both oral and intravenous formulations commands premium positioning in Japanese and German hospital infusion centers. Mitsubishi Tanabe Pharma anchors distribution through deep relationships with domestic neurology centers where site-of-care administration drives reimbursement.
- Sodium Phenylbutyrate:Ammonia-scavenging agent with ALS applications flows through academic medical center pharmacies.
- Tirasemtiv:Fast skeletal muscle troponin activator targets respiratory function preservation in specialized clinics.
- Dexpramipexole:Mitochondrial protective agent distributed through investigational new drug protocols and expanded access programs.
By volume, riluzole leads. By growth pace, edaravone is ahead.
Therapy Area:
Cost tier stratification separates premium-priced novel mechanisms from commoditized glutamate modulation approaches.
- Motor Neuron Protection:Core therapeutic objective targeting upper and lower motor neuron degeneration through glutamate antagonism and mitochondrial support. United States academic medical centers prioritize neurofilament biomarker correlation with motor neuron preservation endpoints.
- Oxidative Stress Reduction:Free radical scavenging mechanisms command reimbursement premiums in German and Japanese health technology assessments. Payers apply stringent cost-effectiveness thresholds to incremental benefits beyond standard of care.
- Anti-inflammatory:Glial cell modulation represents the steepest expansion trajectory as developers redirect R&D spend toward neuroinflammation pathways.
- Muscle Strength Enhancement:Fast skeletal muscle activation targets respiratory decline in late-stage patients.
- Neurotransmission Modulation:Emerging approaches targeting neuromuscular junction integrity remain investigational.
Motor neuron protection commands the largest patient pool. Anti-inflammatory mechanisms are gaining share fastest.
End User:
Customer type determines whether therapy requires multidisciplinary care coordination or standalone pharmaceutical intervention.
- Specialized Neurology Clinics:Tertiary referral centers in Heidelberg, Boston, and Tokyo anchor ALS diagnosis and management capacity. These hubs centralize clinical trial access and concentrate prescriber influence for new therapy adoption.
- Rehabilitation Centers:German and United States facilities integrate respiratory therapy with disease-modifying drug administration. Outcome-based contracting pilots are emerging in England and France for coordinated care bundles.
- Home Care Patients:Oral riluzole and edaravone tablet formulations enable community-based administration.
- Long-term Care Facilities:Institutional settings manage advanced-stage respiratory and nutritional support.
- Research Institutes:Academic medical centers at University of California and University of Tokyo drive biomarker discovery and trial enrollment.
Specialized neurology clinics handle the most complex cases. Home care is expanding most quickly as oral formulations proliferate.
Delivery Mode:
Supply concentration for sterile injectable manufacturing shapes which formats achieve commercial scale.
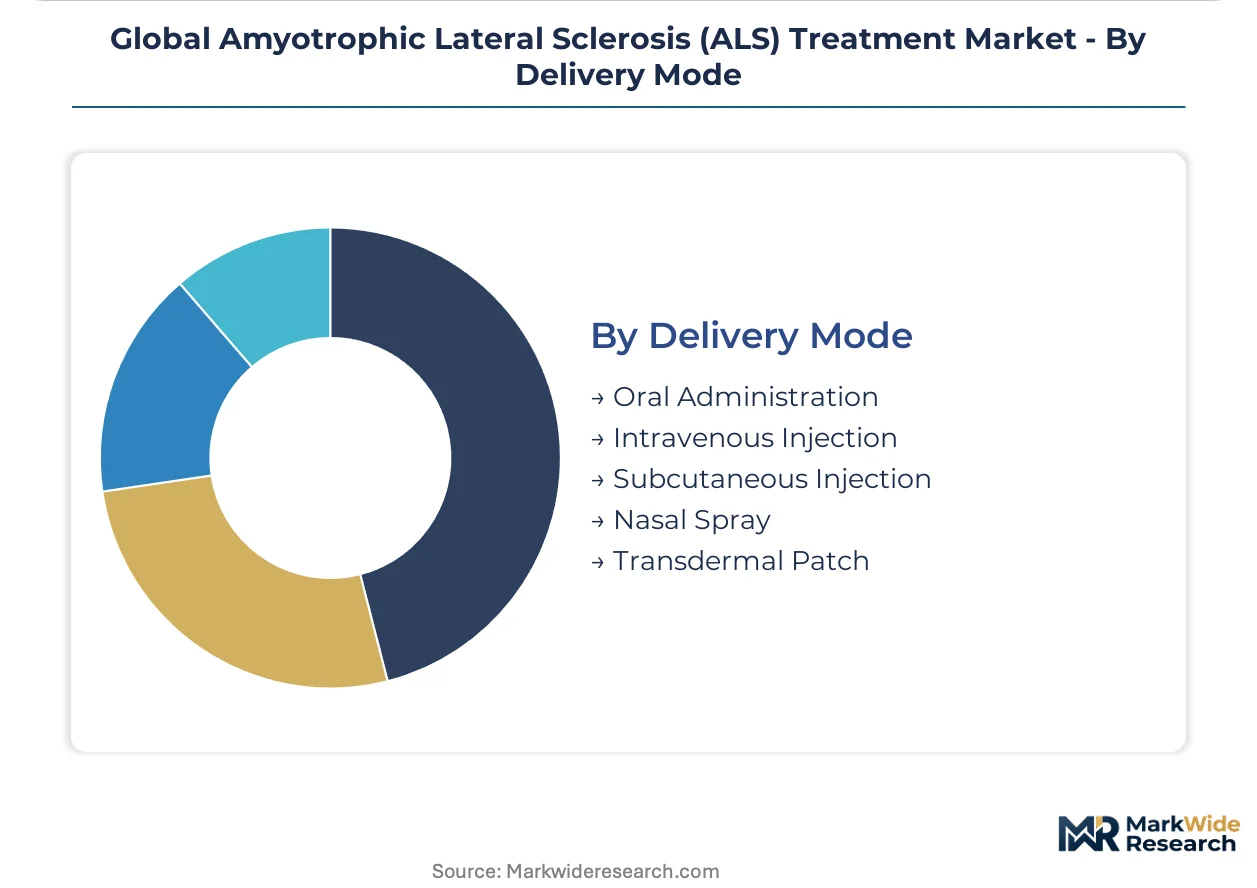
- Oral Administration:Tablet and suspension formulations dominate retail specialty pharmacy distribution. Riluzole and edaravone oral formats enable broad patient access outside infusion-capable centers.
- Intravenous Injection:Hospital-based administration commands premium reimbursement in Japanese and German neurology centers with dedicated infusion capacity. Site-of-care requirements limit addressable population to tertiary referral networks.
- Subcutaneous Injection:Self-administration potential is reshaping prescriber expectations for patient autonomy.
- Nasal Spray:CNS-targeted delivery remains investigational with limited commercial infrastructure.
- Transdermal Patch:Sustained-release skin delivery is preclinical for ALS applications.
Oral administration leads by patient volume. Intravenous injection maintains the highest revenue per treated patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA's PRIME designation are compressing development timelines and reshaping competitive entry patterns across major pharmaceutical markets. Patient access concentrates in tertiary referral networks where multidisciplinary care infrastructure supports clinical trial enrollment and specialized therapy administration.
United States
Academic medical centers in Boston and California anchor the largest ALS clinical trial networks. FDA accelerated approval pathways for neurological orphan drugs enable priority review resources and extended market exclusivity periods. Massachusetts General Hospital and University of California medical centers drive biomarker discovery programs that stratify patients for precision medicine approaches.
Germany
Heidelberg University Hospital and Berlin-Brandenburg neurology clusters centralize diagnosis capacity for rare neurodegenerative conditions. EMA PRIME designation aligns German health technology assessment reimbursement timelines with accelerated regulatory approvals. Baden-Württemberg and Bavaria host the densest concentration of specialized infusion centers for hospital-based ALS therapy administration.
Japan
Domestic neurology center relationships anchor market access for approved therapies. PMDA orphan drug incentives compress review timelines for motor neuron protection candidates. University of Tokyo Hospital anchors hub-and-spoke referral models that centralize clinical trial access and concentrate prescriber influence for new therapy adoption.
United Kingdom
National Health Service specialized neurology services concentrate ALS management in London and regional tertiary centers. NICE cost-effectiveness thresholds apply stringent scrutiny to single-mechanism therapies with modest efficacy profiles. England's outcome-based contracting pilots are emerging for coordinated care bundles integrating respiratory therapy with disease-modifying drug administration.
France
ANSM regulatory pathways prioritize neurological orphan drugs with demonstrated survival prolongation endpoints. Paris and Lyon academic medical centers host the primary ALS biomarker discovery and patient registry infrastructure. Haute Autorité de Santé health technology assessments recalibrate reimbursement thresholds for combination versus single-mechanism ALS therapies.
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory pathway validation and neurology center access dimensions. The competitive structure bifurcates between developers with established orphan drug designations and entrants navigating first-time regulatory submissions. Three archetypes dominate: multinational neurology incumbents with distribution infrastructure, biotech specialists with precision medicine platforms, and academic spinouts with gene-targeting technologies. M&A activity targets biomarker discovery capabilities, while strategic partnerships concentrate on decentralized clinical trial networks.
Within the multinational neurology tier, Biogen and F. Hoffmann-La Roche occupy positions anchored by established regulatory relationships and hospital pharmacy access. Mitsubishi Tanabe Pharma Corporation exemplifies the regional specialist archetype through deep domestic center relationships. Amylyx Pharmaceuticals represents the emerging dual-mechanism developer segment that has reshaped prescriber expectations for new entrants.
| Leading Market Players |
|---|
| Biogen |
| Mitsubishi Tanabe Pharma Corporation |
| Amylyx Pharmaceuticals |
| BrainStorm Cell Therapeutics |
| Ionis Pharmaceuticals |
| Sanofi |
| F. Hoffmann-La Roche |
| Otsuka Pharmaceutical |
| Cytokinetics |
| Others |
Supply & Pricing Matrix
Ninety-day sterile injectable inventory cycles at Japanese and German hospital pharmacies concentrate procurement leverage with tertiary neurology centers, translating site-of-care dependence into premium pricing power for intravenous edaravone formats while compressing margins for oral agents distributed through fragmented retail specialty networks.
Pricing Analysis
Certification level creates the primary spread between FDA-approved orphan drugs and pre-approval expanded access programs. Three-tier pricing structure across premium infusion-center administration, standard oral tablet distribution, and economy generic riluzole segments dominates the market. Cost compression in the oral tablet tier intensifies as pharmacy benefit managers consolidate formulary control. Academic medical centers with dedicated ALS programs exhibit lowest price sensitivity due to bundled reimbursement models, while community neurology practices face highest sensitivity from capitated payment structures.
Supply Chain Analysis
Strategic stockpiling of intravenous edaravone vials prevails in Japanese and German hospital systems, contrasting with just-in-time oral tablet fulfillment through United States specialty pharmacies. Active pharmaceutical ingredient production draws from Switzerland, India, and Japan for glutamate modulators and free radical scavengers. Single-source vulnerability concentrates in sterile injectable manufacturing for hospital-based administration. Distribution runs through hospital pharmacy procurement committees at academic medical centers, bypassing traditional wholesale channels for premium-positioned therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways and EMA PRIME designation mechanisms are compressing development timelines for ALS therapeutics, creating a high-growth disruption window as regulatory science advances enable faster evidence generation for rare neurodegenerative conditions.
For Market Incumbents: Consolidate biomarker discovery capabilities through acquisition of academic spinouts with neurofilament quantification platforms. Deepen relationships with Massachusetts General Hospital and University of Tokyo Hospital referral networks to defend against precision medicine entrants targeting genetic subtypes. Prioritize backward integration into sterile injectable manufacturing to secure supply continuity for hospital-based infusion services.
For New Entrants and Emerging Players: Differentiate on decentralized clinical trial infrastructure that captures real-world evidence through telemedicine-enabled neurology networks. Target the anti-inflammatory mechanism segment as the most penetrable white space, where prescriber expectations remain unformed and biomarker-driven stratification can compress enrollment timelines. Pursue site-of-care partnerships with German rehabilitation centers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antisense oligonucleotide manufacturing as precision medicine programs require dedicated production facilities. Long-term viability favors developers with validated regulatory pathways and embedded algorithmic progression monitoring compliant with EU AI Act governance frameworks. Acquisition target archetype: biotech specialists with SOD1 or C9orf72 genetic subtype platforms and established academic medical center relationships. Watch for PMDA orphan drug incentive expansions as the inflection signal indicating Japanese market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA and EMA incentives compress review timelines and extend market exclusivity for neurological candidates. |
| Biomarker Discovery Partnership | Academic medical center collaborations at Heidelberg and University of Tokyo accelerate patient stratification capabilities. |
| Decentralized Trial Infrastructure | Telemedicine-enabled neurology networks expand patient recruitment beyond traditional site-based constraints. |
| Hospital Infusion Service Expansion | Site-of-care capacity in German and Japanese tertiary centers commands premium reimbursement positioning. |
| Precision Medicine Platform Development | Antisense oligonucleotide targeting of SOD1 and C9orf72 subtypes bifurcates the therapeutic landscape. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue disclosures to anchor market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions including therapy mechanism, administration route, patient population genetics, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating clinical trial advancement rates, regulatory approval velocity, and health technology assessment reimbursement timelines. Neurofilament biomarker correlation data and ALSFRS-R progression metrics served as disease-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside continued orphan drug incentive stability and tertiary referral network concentration would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway validation and prescriber adoption curves for combination therapies. Revision becomes warranted when health technology assessment thresholds in Germany, France, or England cross stringency thresholds that displace single-mechanism therapies from formulary access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market