
 Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market | 2026-2036
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market Analytics
European biologics manufacturing is broadening its role in SPMS drug supply as contract production organizations expand fill-finish capacity for monoclonal antibodies. Biogen leverages its decades-long neurology franchise to sustain deep relationships with academic medical centers. Novartis anchors its position through integrated access programs that bridge hospital and homecare settings. Roche competes aggressively in the infusion segment with established logistics networks across major European markets.
Secondary Progressive Multiple Sclerosis treatment encompasses disease-modifying therapies administered after an initial relapsing-remitting phase transitions to steady neurological decline, typically involving monoclonal antibodies targeting CD20-positive B cells or sphingosine-1-phosphate receptor modulators that slow disability progression. The primary purpose is to reduce relapse frequency, limit magnetic resonance imaging lesion accumulation, and preserve functional independence in patients with confirmed progression. Monoclonal antibodies command the dominant share of product-type value due to premium pricing and infusion-center dependency, while oral immunomodulators represent the fastest-expanding delivery-mode category as patients seek alternatives to clinic-based administration. Homecare end-user channels are capturing disproportionate growth as reimbursement shifts favor subcutaneous self-administration over hospital infusion.
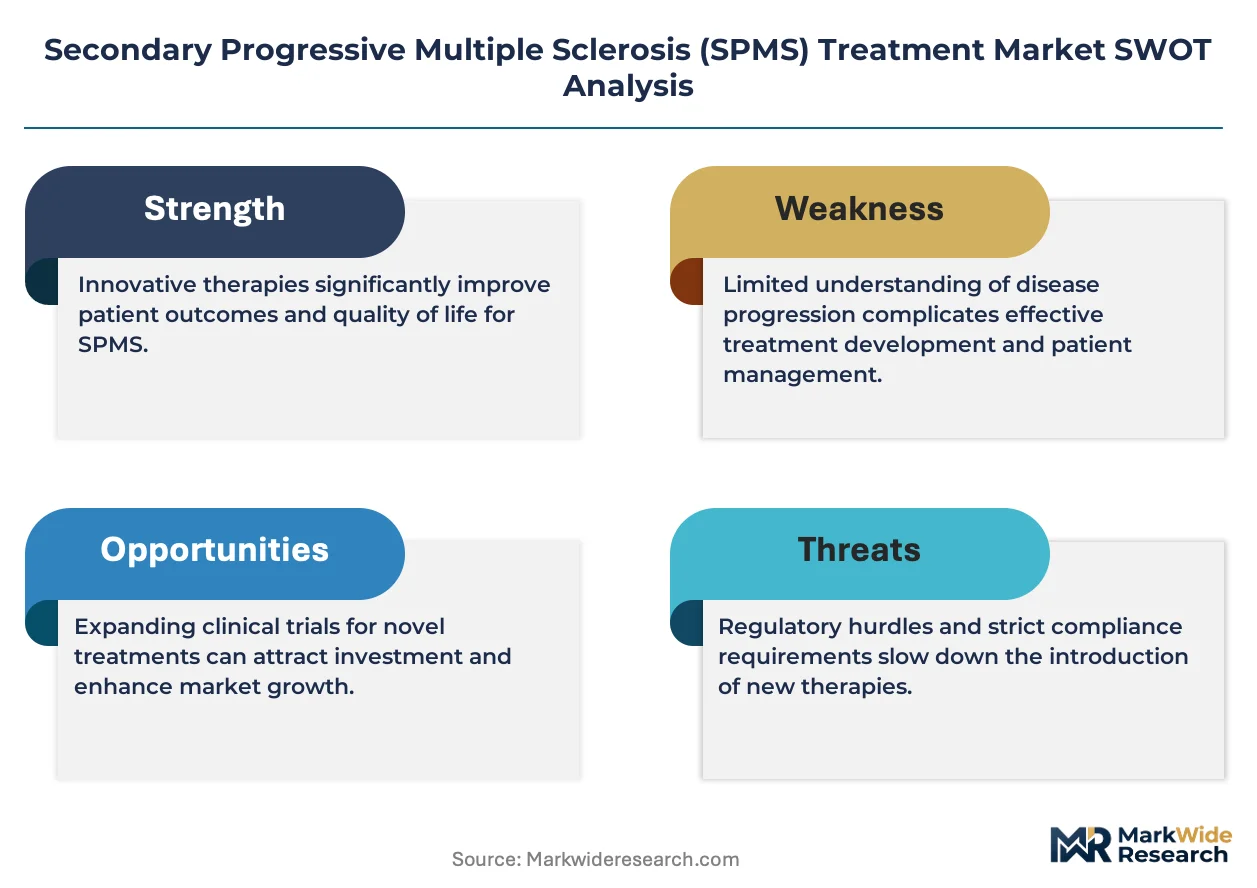
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathway both shape SPMS therapy development timelines, creating divergent evidence requirements across Atlantic markets. HIPAA compliance costs and GDPR-mandated patient data protections add operational complexity to multinational clinical programs and real-world evidence collection. Stakeholders must monitor how CMS national coverage determinations and NICE technology appraisals reconcile over the coming decade, as divergent health technology assessment methodologies threaten to fragment commercial access for next-generation neuroprotective agents.
Market Dynamics
FDA's accelerated approval pathway for neurodegenerative therapies is compressing clinical trial timelines and reshaping evidence generation requirements for progressive MS drug developers. This regulatory shift forces sponsors to design adaptive protocols that integrate real-world data collection from the outset.
Growth Catalysts
- CMS Reimbursement Policy:Medicare's preference for outpatient infusion centers over hospital-based care is expanding addressable patient populations and reducing site-of-care costs for monoclonal antibody administration.
- CD20-Targeted B Cell Depletion:Advances in monoclonal antibody engineering are improving efficacy profiles and reducing infusion-related reactions, accelerating neurologist adoption of B-cell therapies.
- European Manufacturing Scale-Up:Contract production organizations across Germany and Switzerland are expanding fill-finish capacity for biologics, securing supply chain resilience for chronic immunotherapy demand.
Market Restraints
- Biologics Input Concentration:Reliance on Chinese-sourced recombinant proteins and fermentation media creates vulnerability to trade disruptions and quality variability in upstream supply.
- Progressive Disability Measurement Heterogeneity:Lack of standardized clinical endpoints for neurological decline slows regulatory consensus and complicates payer value assessment across health technology appraisal bodies.
- Oral Sphingosine Modulator Substitution:Patient preference for self-administered pills over clinic-based infusions threatens pricing power and site-of-service economics for infused therapies.
Strategic Opportunities
- Homecare Administration Channel:Subcutaneous formulation development for anti-CD20 agents is enabling self-injection programs that bypass infusion center dependency and capture patient convenience premiums.
- NICE Technology Appraisal Alignment:Convergence between UK cost-effectiveness thresholds and German AMNOG assessments is creating harmonized access pathways for next-generation neuroprotective agents.
- Real-World Evidence Infrastructure:GDPR-compliant patient registries across France, Germany, and Italy are generating post-market outcome data that supports label expansion and differentiated reimbursement negotiations.
Industry Challenges
- Neuroimmunology Specialist Shortage:Limited fellowship-trained MS neurologists constrains patient identification and treatment initiation rates in community practice settings.
- HIPAA-GDPR Compliance Integration:Multinational clinical programs face operational friction reconciling US patient privacy requirements with European data protection mandates for cross-border trial coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market |
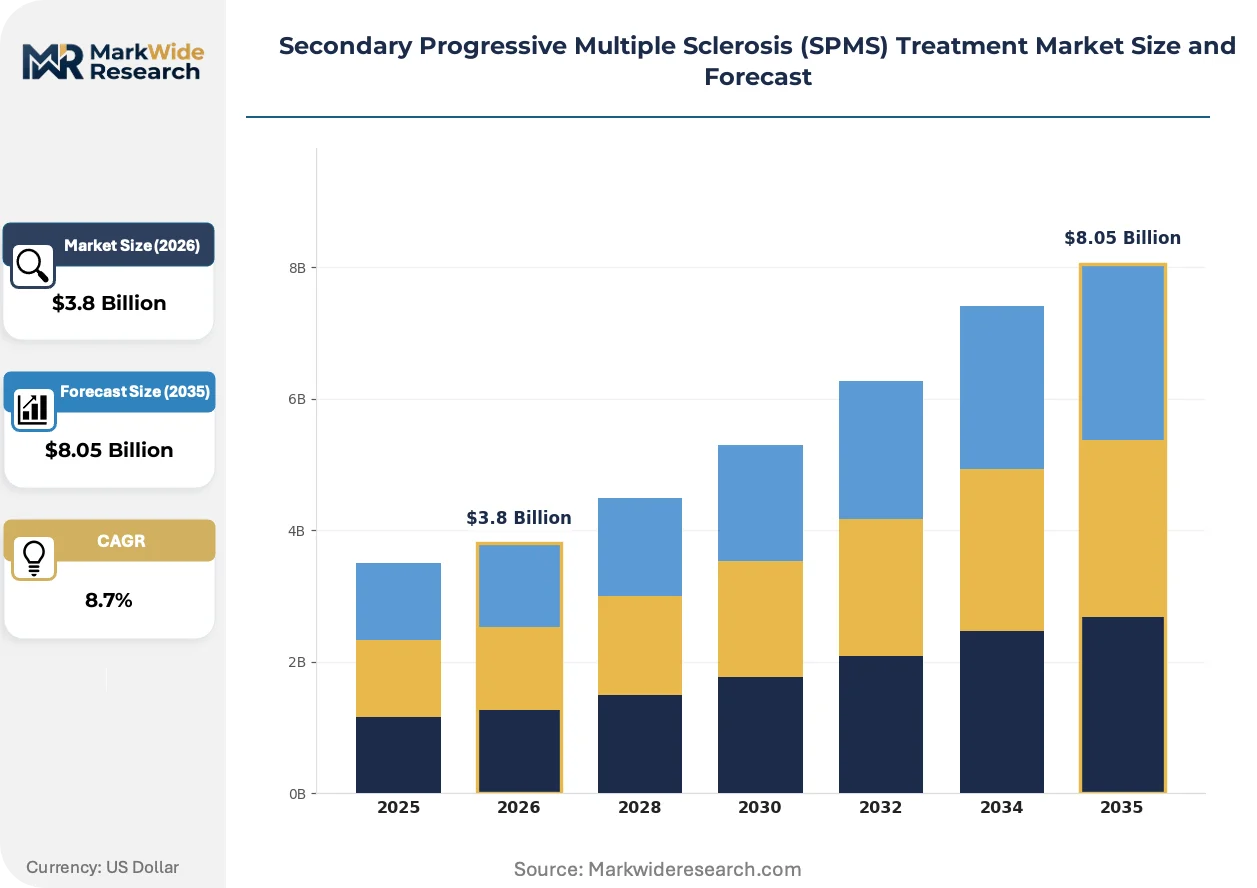
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Immunomodulators, Chemotherapy Delivery Mode: Injection, Infusion, Oral, Topical End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Treatment Protocol: Standard Care, Personalized Therapy, Combination Therapy, Emerging Treatments |
| Companies Covered | Biogen, Novartis, Sanofi, Roche, EMD Serono, TG Therapeutics, Bristol-Myers Squibb, Tiziana Life Sciences, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market Evolving Landscape
Digital biomarker integration and decentralized trial platforms are fundamentally altering how progressive MS therapies demonstrate clinical value and reach patient populations. These innovations compress evidence generation cycles while expanding geographic reach.
Artificial intelligence-powered magnetic resonance imaging analysis is automating lesion quantification and disability progression tracking for clinical trial endpoints. Neurology clinics across the United States and Germany are deploying these tools to standardize patient monitoring and reduce rater variability. The technology is automating the extraction of regulatory-grade outcome data that previously required manual neuroradiologist review, shrinking trial duration and accelerating submission timelines.
EMA's conditional marketing authorization pathway is creating staggered evidence requirements that diverge from FDA accelerated approval standards. European sponsors must commit to post-authorization efficacy studies while US counterparts focus on confirmatory trials, fragmenting development strategy. This divergence most affects monoclonal antibody developers who must design dual-track protocols to satisfy both agencies simultaneously.
Patient advocacy organizations are consolidating purchasing influence and demanding transparent value demonstration from manufacturers. Payers in the United Kingdom and Netherlands are responding by unbundling drug reimbursement from supportive care services, forcing providers to justify each cost component separately. This behavioral shift is most visible in Germany, where sickness funds now require individualized progression risk stratification before authorizing high-cost biologics.
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market Segmentation
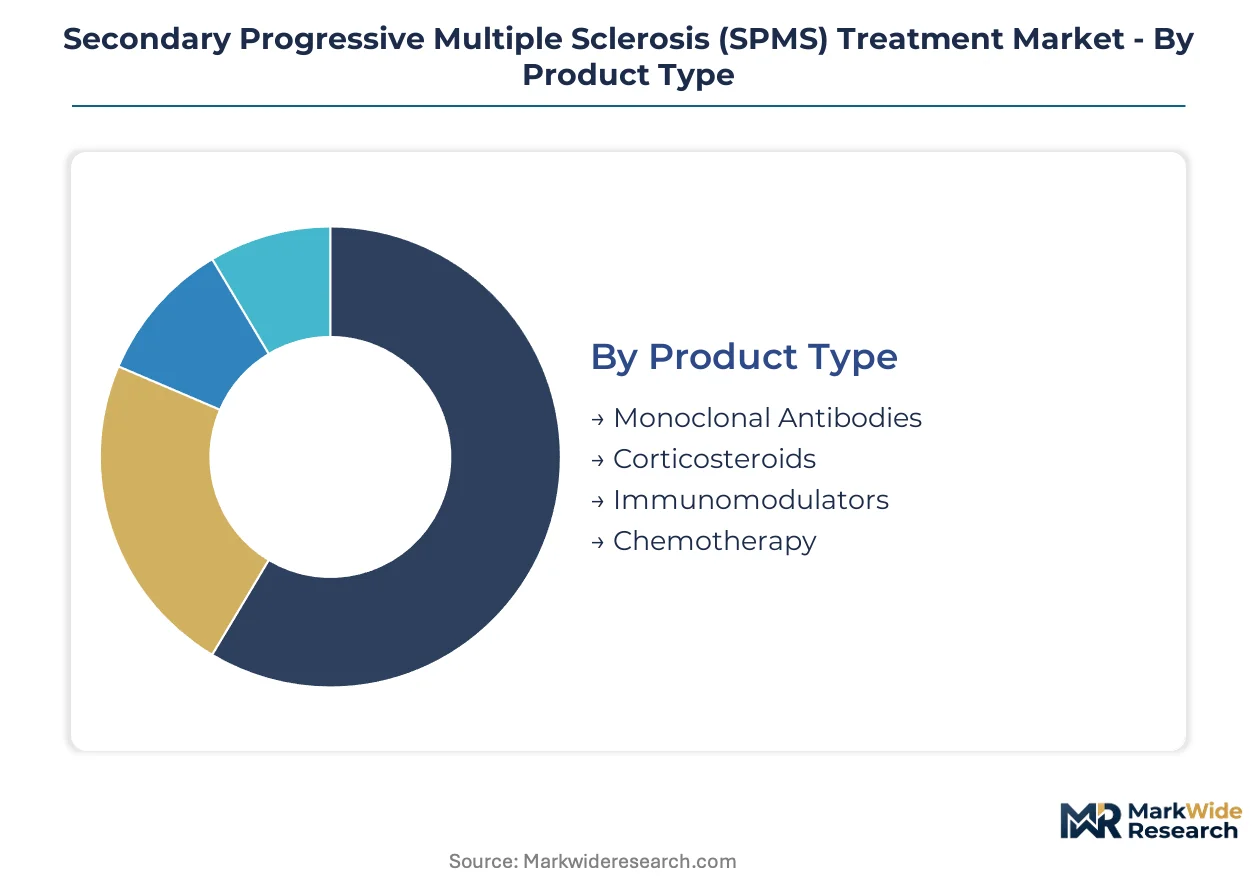
SPMS treatment segmentation reveals distinct operational models across therapy administration. Product type determines reimbursement complexity and site-of-care requirements. Delivery mode shapes patient adherence patterns and healthcare system capacity planning.
Product Type:
Standalone biologics dominate infusion center workflows, while embedded oral agents integrate into broader neurological management protocols.
- Monoclonal Antibodies:Engineered proteins targeting CD20-positive B cells require cold-chain logistics and specialized nursing supervision. Demand concentrates in United States Medicare outpatient centers where reimbursement favors infusion-based administration over hospital admission.
- Immunomodulators:Sphingosine-1-phosphate receptor modulators and related compounds alter lymphocyte trafficking to reduce CNS inflammation. German neurologists prescribe these as first-line oral alternatives where patient mobility constraints limit clinic visits.
- Corticosteroids:Acute relapse management agents administered in pulse-dose protocols.
- Chemotherapy:Mitoxantrone and similar cytotoxic agents reserved for aggressive progression cases with cardiac monitoring requirements.
Volume placements concentrate in Monoclonal Antibodies; the faster expansion belongs to Immunomodulators.
Delivery Mode:
Cost tier stratification separates premium infusion services from economy oral self-administration, with injection formats bridging the gap.
- Infusion:Intravenous monoclonal antibody delivery demands dedicated chair time, pre-medication protocols, and post-infusion observation. United States neurology clinics expand capacity in response to CMS reimbursement differentials favoring outpatient sites.
- Oral:Self-administered small-molecule therapies eliminate travel burden for mobility-impaired patients. French and Italian patient registries document higher persistence rates versus infusion alternatives, driving formulary preference shifts.
- Injection:Subcutaneous depot formulations enabling home administration with nursing oversight.
- Topical:Symptomatic adjuncts for spasticity and neuropathic pain management.
Infusion captures the highest per-patient revenue; subcutaneous injection formats are climbing the fastest as biologics developers reformulate for home use.
End User:
Application context distinguishes acute intervention settings from chronic disease management infrastructure.
- Homecare:Subcutaneous administration and remote monitoring platforms enable progression management outside institutional walls. United Kingdom integrated care boards expand home nursing contracts to reduce hospital utilization among wheelchair-dependent cohorts.
- Hospitals:Academic medical centers anchor clinical trial recruitment and complex case consultation. German university hospitals concentrate magnetic resonance imaging capacity and specialist neurology fellowship training.
- Clinics:Community neurology practices handling stable patients on established protocols.
- Rehabilitation Centers:Physical therapy integration with disease-modifying therapy coordination.
Hospital placements retain the highest case complexity; homecare channels are gaining share fastest as subcutaneous biologics proliferate.
Treatment Protocol:
Customer type segmentation separates standardized payer-driven pathways from individualized access programs.
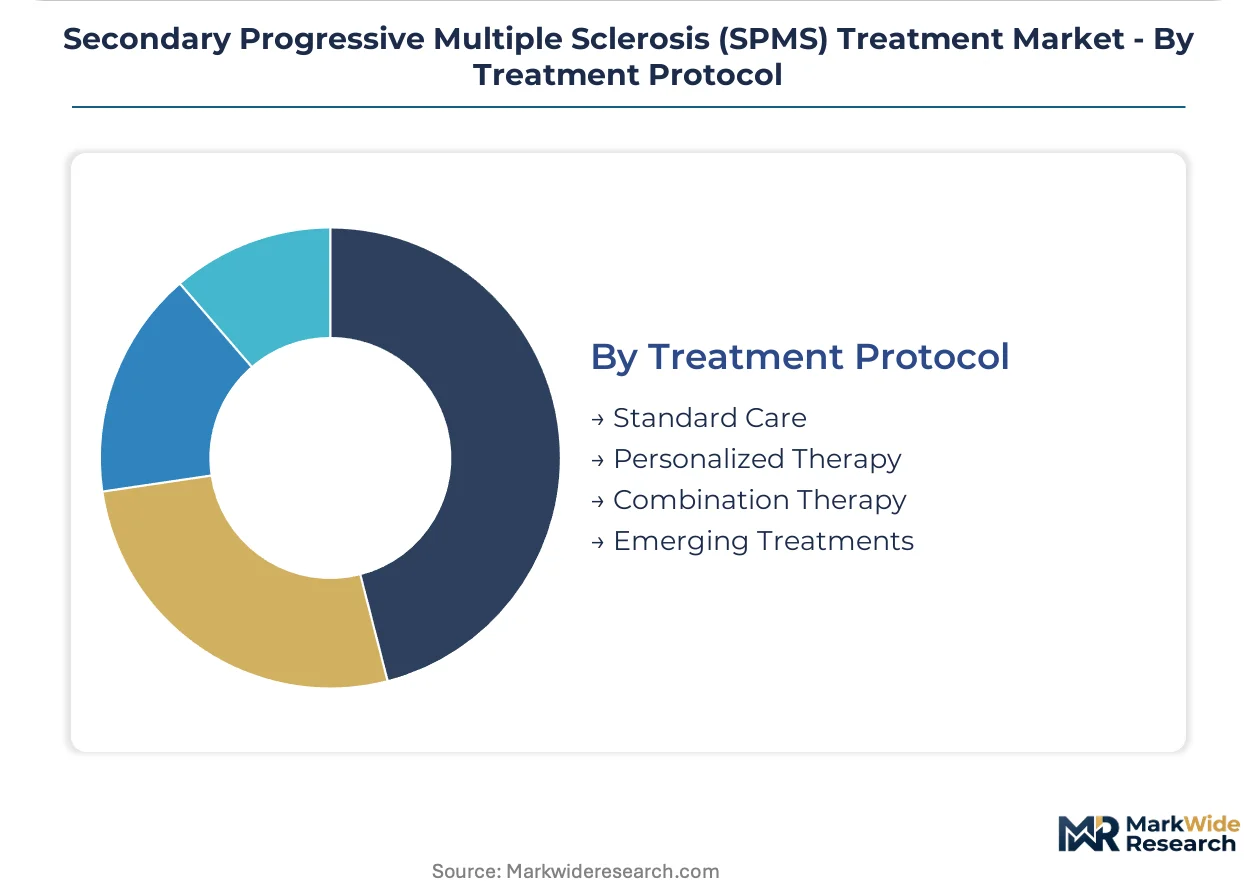
- Standard Care:Established escalation algorithms from platform injectables to high-efficacy biologics. NICE technology appraisals in England dictate sequential therapy authorization based on disability progression metrics.
- Personalized Therapy:Biomarker-stratified selection matching patient immunological profiles to mechanism of action. Swiss neurologists leverage HLA-typing and antibody status to optimize first-line decisions.
- Combination Therapy:Concurrent disease-modifying and symptomatic agents.
- Emerging Treatments:Experimental neuroprotective and remyelination strategies in academic protocols.
Standard care protocols dominate prescription volume; personalized therapy approaches show the steepest expansion trajectory as biomarker infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant protein fermentation capacity in Germany and Switzerland anchors European biologics supply chains for SPMS monoclonal antibody production. Contract manufacturing organizations in Basel and Munich expand fill-finish operations to serve chronic immunotherapy demand across Atlantic markets. Neurology clinic networks in the United States concentrate infusion capacity where Medicare reimbursement differentials favor outpatient administration.
United States
Academic medical centers in Boston and Baltimore drive clinical trial recruitment for progressive MS neuroprotective agents. FDA's accelerated approval pathway compresses development timelines for sponsors designing adaptive protocols with integrated real-world data collection. Neurology clinics across Florida and Texas expand infusion chair capacity to capture CMS reimbursement differentials favoring outpatient sites over hospital-based care.
Germany
Sickness funds mandate individualized progression risk stratification before authorizing high-cost biologics for wheelchair-dependent cohorts. AMNOG assessments create harmonized access pathways that influence NICE technology appraisal convergence across European markets. University hospitals in Berlin and Heidelberg concentrate magnetic resonance imaging capacity and specialist neurology fellowship training for complex case management.
Switzerland
Neurologists in Zurich and Geneva leverage HLA-typing and antibody status to optimize first-line therapy decisions through biomarker-stratified selection. Swissmedic maintains rigorous pharmacovigilance standards that shape post-authorization study commitments for monoclonal antibody developers. The Basel biotech cluster hosts contract manufacturing organizations expanding viral clearance and aseptic processing capacity for CD20-targeted therapies.
United Kingdom
Integrated care boards expand home nursing contracts to reduce hospital utilization among immobile patient populations seeking subcutaneous alternatives. NICE technology appraisals dictate sequential therapy authorization based on standardized disability progression metrics that constrain formulary access. The London-Southeast corridor concentrates patient advocacy organizations consolidating purchasing influence and demanding transparent value demonstration from manufacturers.
France
ANSM and CNIL oversight creates operational friction for multinational clinical programs reconciling patient privacy with cross-border trial coordination requirements. GDPR-compliant patient registries in Paris and Lyon generate post-market outcome data supporting label expansion and differentiated reimbursement negotiations. Neurology practices in the Île-de-France region document higher persistence rates for oral immunomodulators versus infusion alternatives, driving formulary preference shifts.
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market Competitive Landscape
Global majors compete with regional champions across infusion logistics and homecare administration channels. The vendor base concentrates around three strategic tiers: integrated pharmaceutical conglomerates with neurology franchises, mid-cap biotech specialists in B-cell depletion mechanisms, and contract service providers enabling manufacturing scale-up. Consolidation pressures favor players with captive fill-finish capacity and established payer relationships. Dominant competitive moves include subcutaneous formulation development to bypass infusion center dependency and real-world evidence infrastructure investments to support accelerated regulatory pathways.
Among neurology-focused pharmaceutical conglomerates, Biogen, Novartis, and Roche occupy positions exemplifying distinct competitive archetypes. Biogen represents the academic medical center anchor model with decades-long specialist relationships. Novartis exemplifies integrated access program architecture bridging institutional and homecare settings. Roche sits within the infusion logistics specialization tier with established cold-chain networks across major European markets.
| Leading Market Players |
|---|
| Biogen |
| Novartis |
| Sanofi |
| Roche |
| EMD Serono |
| TG Therapeutics |
| Bristol-Myers Squibb |
| Tiziana Life Sciences |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Subcutaneous formulation development for anti-CD20 agents is compressing site-of-service economics while redistributing value capture from infusion centers to homecare channels. This delivery-mode transition simultaneously erodes premium pricing for hospital-based administration and concentrates manufacturing scale-up in contract production organizations across Germany and Switzerland.
Pricing Analysis
Service unbundling separates drug reimbursement from supportive care in United Kingdom and Netherlands payer contracts. Three-tier pricing structure across premium infused biologics, standard oral immunomodulators, and economy corticosteroid protocols reflects site-of-care dependencies. Cost compression in the infusion segment intensifies as subcutaneous alternatives capture patient convenience premiums. Community neurology practices exhibit highest price sensitivity; academic medical centers with trial recruitment mandates show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle high-complexity monoclonal antibody demand while specialty distributors serve outpatient infusion networks. Fill-finish capacity concentrates in Switzerland, Germany, and Ireland for European biologics supply. Upstream fermentation media and recombinant protein inputs draw from Chinese and Indian sources. Single-source vulnerability in CD20-targeted active pharmaceutical ingredients threatens continuity. Distribution runs through cold-chain logistics specialists with established neurology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fill-finish capacity bottlenecks at European contract manufacturing organizations prop pricing power for sponsors with captive production, constraining supply elasticity against rising SPMS patient identification rates.
For Market Incumbents: To counter oral sphingosine modulator substitution, anchor infusion center relationships through real-world evidence partnerships and deepen backward integration into viral clearance capacity at Basel and Munich manufacturing sites. For New Entrants and Emerging Players: FDA's accelerated approval pathway in the United States opens a window for adaptive protocol designs with integrated post-market data collection. Target homecare administration channels with subcutaneous formulation development and pursue biomarker-stratified patient selection as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap biotech specialists with Phase II neuroprotective assets and established payer access infrastructure. Long-term viability hinges on regulatory convergence between FDA and EMA evidence standards. Watch for NICE technology appraisal alignment with German AMNOG assessments as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home administration bypassing infusion center dependency and capturing patient convenience premiums. |
| Real-World Evidence Infrastructure Investment | Supports FDA accelerated approval and EMA conditional marketing authorization pathway commitments simultaneously. |
| Biomarker-Stratified Patient Selection | Matches HLA-typing and antibody status to mechanism of action for personalized therapy positioning. |
| Integrated Access Program Architecture | Bridges hospital and homecare settings through Novartis-style reimbursement navigation services. |
| Fill-Finish Capacity Expansion | Secures supply chain resilience for chronic immunotherapy demand at Basel and Munich contract manufacturing sites. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing underwent iterative triangulation.
Granularity-level framing modeled treatment line, dosage form, administration route, and patient population segments across the projection horizon. CAGRs derived from disability progression rate assumptions, therapy switching probabilities, and reimbursement policy trajectory analysis. Forecast inputs incorporated neurologist adoption curves for B-cell depletion therapies and site-of-care shift elasticities.
Caveats apply where regulatory divergence between FDA and EMA, trade disruption in Chinese-sourced recombinant proteins, or neuroimmunology specialist shortage could materially shift the outlook. Forecasts reflect assumptions about accelerated approval pathway utilization and conditional marketing authorization convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Market