
 Tinea Corporis Market | 2026-2036
Tinea Corporis Market Size, Share, and Industry Trends Forecast 2026-2036
Tinea Corporis Market Analytics
Allylamine compounds are rebalancing treatment economics as they displace older azole-based formulations in first-line topical therapy. Pfizer leverages its manufacturing scale to sustain broad distribution across retail pharmacy networks. Novartis differentiates through R&D intensity in novel antifungal mechanisms. Sun Pharmaceuticals anchors its position with cost-competitive generic topical offerings across emerging markets.
Tinea corporis is a superficial dermatophyte infection of glabrous skin, typically caused by Trichophyton rubrum, Microsporum canis, or Epidermophyton floccosum, presenting as pruritic, annular, erythematous lesions with raised borders and central clearing. The condition requires antifungal agents capable of disrupting ergosterol biosynthesis or fungal cell membrane integrity to achieve mycological cure. Topical antifungals occupy the largest volume share due to favorable safety profiles and direct lesion targeting, while systemic antifungals capture premium positioning for refractory or extensive infections. Combination therapy represents the fastest-expanding segment as clinicians address rising treatment failure rates and mixed-pathogen presentations.
The FDA oversees antifungal drug approval and post-market surveillance in the United States, while the EMA governs centralized marketing authorization across European member states, with both agencies tightening quality standards for topical excipient safety. ISO 13485 certification requirements for dermatological manufacturing facilities shape supplier qualification and market access barriers. Stakeholders must monitor evolving resistance patterns and regulatory scrutiny on combination therapy labeling to align portfolio investments with clinical utility demands.
Market Dynamics
Allylamine compounds are displacing azole-based formulations as first-line topical therapy, compressing treatment duration from four weeks to one-to-two weeks and reordering prescribing patterns across dermatology clinics and retail pharmacy networks.
Growth Catalysts
- FDA Streamlined Approval:The FDA's abbreviated pathways for generic topical antifungals accelerate market entry for cost-competitive formulations, expanding patient access across pharmacy benefit programs.
- Combination Therapy Protocols:Clinicians are adopting corticosteroid-antifungal combinations to address mixed-pathogen presentations and treatment failures, creating new prescription volume in refractory cases.
- Telemedicine Triage:Dermatology platforms are routing tinea corporis cases to asynchronous photo-based diagnosis, funneling patients directly to topical antifungal fulfillment without in-person consultation delays.
Market Restraints
- Terbinafine Raw Material Concentration:Active pharmaceutical ingredient synthesis for allylamines clusters with Chinese contract manufacturers, exposing formulators to supply disruption risk from environmental compliance inspections.
- Topical Excipient Scrutiny:EMA tightening of safety standards for penetration enhancers and preservatives forces reformulation cycles that extend development timelines by twelve to eighteen months.
- Self-Diagnosis Substitution:Patients misidentify tinea corporis as eczema or psoriasis, initiating inappropriate corticosteroid monotherapy that masks symptoms and delays antifungal initiation.
Strategic Opportunities
- India Outpatient Expansion:Tier-two and tier-three Indian cities present underpenetrated demand as dermatology clinic networks extend beyond metropolitan centers and pharmacy chains standardize cold-chain distribution for topical creams.
- Long-Acting Depot Formulations:Sustained-release topical vehicles using polymeric film-forming technology could reduce dosing frequency from twice-daily to weekly, improving adherence in pediatric and elderly populations.
- Point-of-Care Diagnostics:Rapid dermatophyte identification assays at retail clinics enable targeted therapy selection, creating pull-through for premium branded antifungals over empirical generic prescribing.
Industry Challenges
- Antifungal Stewardship Training:Primary care physicians require updated protocols to distinguish tinea corporis from mimicking conditions, yet continuing medical education programs lack dedicated dermatophyte modules.
- ISO 13485 Facility Certification:Dermatological manufacturing sites face intensified audit schedules for quality management compliance, stretching quality assurance staffing across multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinea Corporis Market |
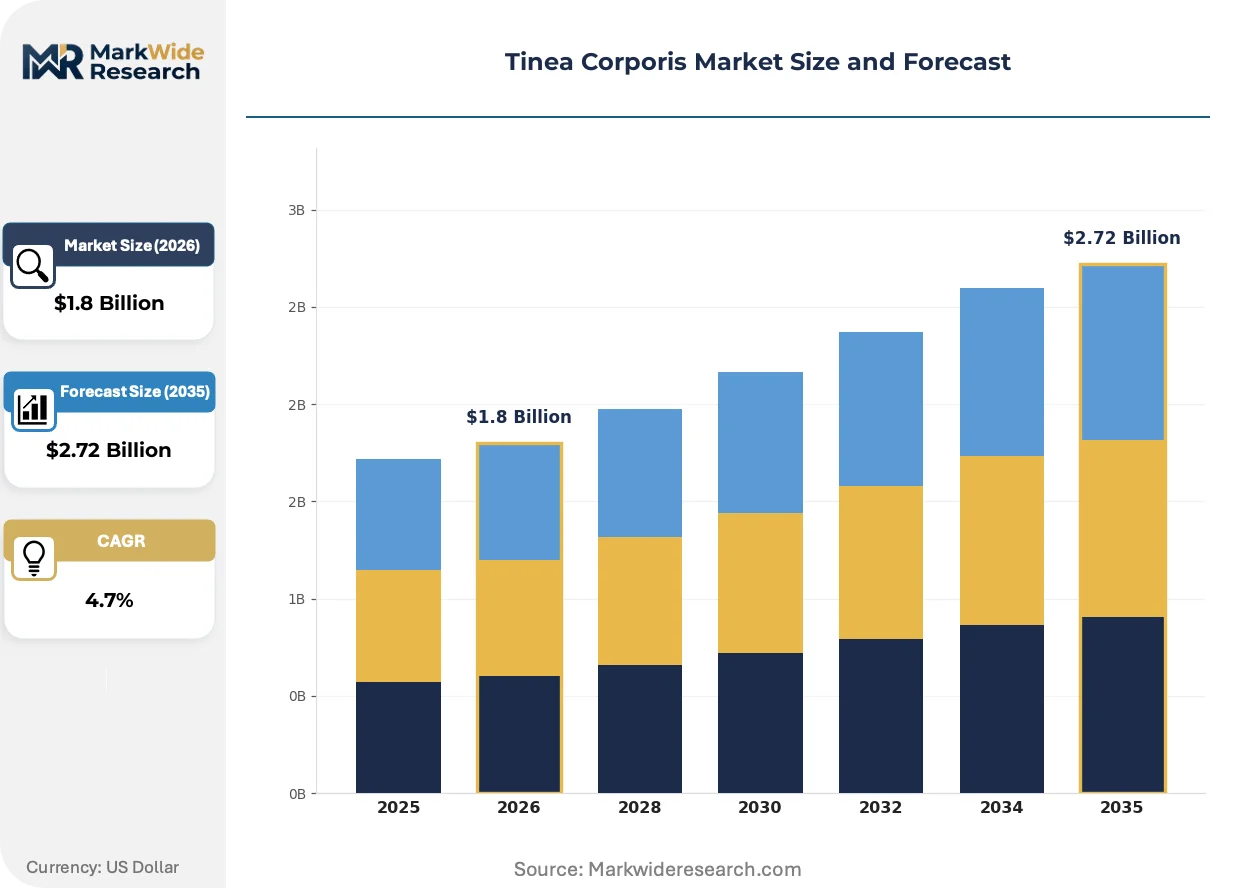
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Systemic Antifungals, Combination Therapy, Herbal Remedies End User: Hospitals, Dermatology Clinics, Homecare Settings, Pharmacies Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales Formulation: Creams, Ointments, Tablets, Powders |
| Companies Covered | Pfizer, Merck, Novartis, Bayer, GlaxoSmithKline, Perrigo Company, Johnson and Johnson, Sun Pharmaceuticals, Taro Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinea Corporis Market Evolving Landscape
Topical formulation science is advancing through nanocarrier delivery systems and combination chemistry, while regulatory agencies tighten post-market surveillance and prescribing behavior shifts toward rapid diagnostic confirmation.
Nanostructured lipid carriers encapsulating terbinafine hydrochloride are converging with microneedle array patches to enhance stratum corneum penetration in hyperkeratotic lesions. Academic medical centers in Germany and South Korea are piloting these systems for refractory tinea corporis cases. This convergence is compressing the efficacy gap between topical and oral antifungal regimens for moderate infections.
EMA's revised excipient safety guidelines now mandate carcinogenicity screening for novel penetration enhancers in topical dermatological products. Formulators must submit extended toxicology packages that add six to nine months to development timelines. Small and mid-sized generic manufacturers are responding by reverting to established excipient portfolios rather than innovating novel delivery vehicles.
Retail pharmacy chains are unbundling diagnostic counseling from product dispensing, deploying trained pharmacists to perform lesion examination and KOH preparation guidance before recommending specific antifungal agents. This service model is displacing physician-first consultation patterns in the United Kingdom and Australia. Community pharmacy networks capture margin from both the diagnostic interaction and the subsequent product sale.
Tinea Corporis Market Segmentation
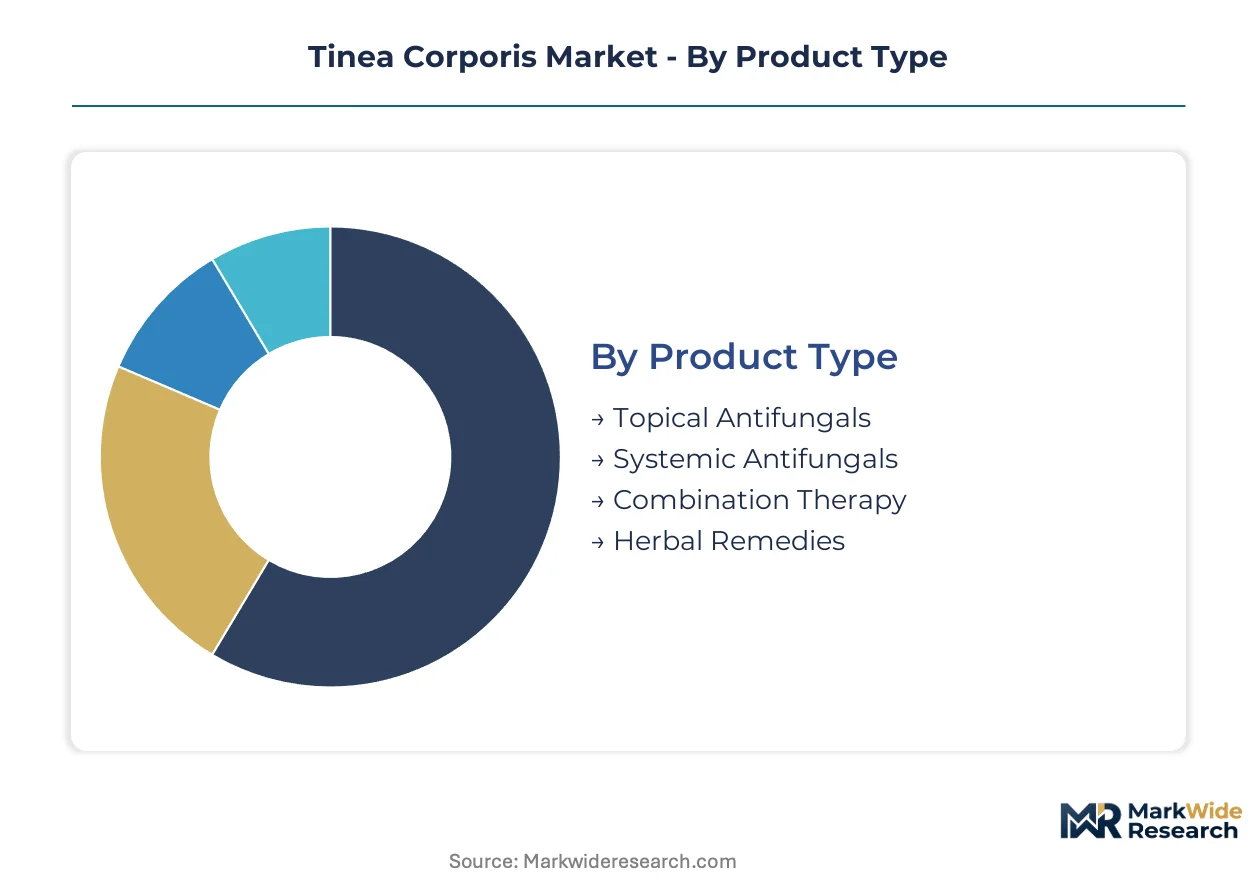
Segmentation in the tinea corporis market determines which regulatory pathways manufacturers must navigate and where commercial resources concentrate. Product type and formulation choices directly shape FDA versus EMA filing strategies, while end-user and channel segmentation dictates pricing architecture and promotional investment.
Product Type:
FDA 505(b)(2) applications dominate systemic antifungal approvals, while topical formulations leverage abbreviated ANDA pathways; combination therapies face heightened scrutiny under EMA's revised excipient safety guidelines.
- Topical Antifungals:Allylamine and azole-based creams and gels applied directly to lesions, with terbinafine hydrochloride and clotrimazole comprising the majority of prescriptions. Demand concentrates in United States retail pharmacy networks where direct-to-consumer advertising and pharmacist counseling drive selection of branded and generic alternatives.
- Systemic Antifungals:Oral agents including itraconazole and fluconazole reserved for refractory, extensive, or immunocompromised patient cases. Prescribing clusters in United States dermatology clinics and hospital outpatient departments where KOH confirmation precedes initiation, constrained by hepatotoxicity monitoring requirements.
- Combination Therapy:Corticosteroid-antifungal fixed-dose products addressing mixed-pathogen presentations and inflammatory symptoms.
- Herbal Remedies:Tea tree oil and neem-based preparations sold as cosmetics or dietary supplements outside formal drug approval frameworks.
Leading the category by volume: Topical Antifungals. Growing fastest: Combination Therapy.
End User:
Cost tier stratification separates institutional procurement from retail self-pay, with reimbursement depth varying sharply across settings.
- Hospitals:Inpatient and emergency department prescribing for severe or disseminated dermatophyte infections, typically systemic regimens under pharmacy and therapeutics committee formularies.
- Dermatology Clinics:Specialized settings where KOH preparation and culture confirmation guide targeted therapy selection, generating premium pricing for rapid diagnostic-therapeutic bundling.
- Homecare Settings:Self-administered topical regimens supported by telemedicine triage and direct-to-patient fulfillment, expanding most quickly as asynchronous dermatology platforms reduce consultation friction.
- Pharmacies:Community and retail locations where pharmacist-led lesion examination and product recommendation displace physician-first consultation patterns in United Kingdom and Australian markets.
Volume concentrates in Pharmacies. Steepest expansion trajectory: Homecare Settings.
Distribution Channel:
Customer type fragmentation—institutional buyers versus individual consumers—determines contract structure and margin retention.
- Online Pharmacies:E-commerce platforms and telemedicine-integrated fulfillment capturing self-diagnosing patients seeking convenience and price transparency, with cold-chain logistics requirements limiting topical cream shipping in tropical climates.
- Retail Pharmacies:Brick-and-mortar chains dominating United States volume through insurance network participation and 340B program eligibility, facing margin compression from generic substitution mandates.
- Hospital Pharmacies:Captive procurement operations governed by group purchasing organization contracts and antimicrobial stewardship committee oversight.
- Direct Sales:Manufacturer-to-provider arrangements for specialty systemic antifungals requiring risk evaluation and mitigation strategies.
Retail Pharmacies lead channel volume. Online Pharmacies gain share fastest.
Formulation:
Supply concentration in excipient manufacturing shapes which dosage forms face procurement risk from environmental compliance inspections.
- Creams:Oil-in-water emulsions preferred for intertriginous areas and weeping lesions, with United States compounding pharmacies producing patient-specific strengths for pediatric populations.
- Ointments:Occlusive petrolatum-based vehicles selected for hyperkeratotic plaques on palms and soles, requiring longer manufacturing cycles due to homogenization steps.
- Tablets:Oral solid dosage forms for systemic therapy subject to FDA bioequivalence studies and EMA quality target product profile requirements.
- Powders:Talc or starch-based formulations for moisture control in occluded skin folds, with talc safety litigation in United States driving reformulation to cornstarch alternatives.
Creams dominate formulation volume. Ointments climb fastest on geriatric and diabetic foot applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology clinics and retail pharmacy networks concentrate the largest prescription volume for tinea corporis treatments. FDA approval pathways and direct-to-consumer advertising sustain branded-generic competition across the market.
United States
High diagnosis rates and robust pharmacy infrastructure drive sustained demand for topical antifungals. FDA streamlined approval pathways for generic formulations accelerate cost-competitive entry. Major retail pharmacy chains in metropolitan areas deploy pharmacist-led lesion examination services.
Germany
Academic medical centers pioneer nanocarrier delivery systems for refractory cases. EMA excipient safety guidelines mandate extended toxicology screening for novel penetration enhancers. Berlin and Heidelberg host pilot programs combining rapid diagnostics with targeted therapy selection.
India
Tier-two and tier-three cities present underpenetrated demand as dermatology networks extend beyond metropolitan centers. CDSCO regulatory frameworks govern topical drug manufacturing quality. Mumbai and Hyderabad anchor generic production clusters serving domestic and export markets.
United Kingdom
Community pharmacy networks displace physician-first consultation through trained pharmacist lesion examination. NHS reimbursement policies favor cost-effective generic prescribing over branded alternatives. London and Manchester lead adoption of asynchronous telemedicine triage platforms.
Australia
Retail pharmacy chains capture diagnostic counseling margin alongside product dispensing. TGA post-market surveillance requirements tighten quality standards for topical excipients. Sydney and Melbourne concentrate telemedicine-integrated fulfillment operations for remote patient populations.
Tinea Corporis Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-intensive multinationals commanding premium positioning while generic fabricators compete on cost and distribution reach. The vendor base organizes around three archetypes: large-cap pharmaceutical conglomerates with integrated R&D and manufacturing, mid-sized generic specialists leveraging regional regulatory expertise, and contract development organizations supplying active pharmaceutical ingredients. Consolidation pressures favor players with captive supply chains and broad pharmacy network relationships. Competitive moves concentrate on portfolio diversification into combination therapies and geographic expansion into underpenetrated outpatient markets.
Among the research-intensive tier, Pfizer and Novartis exemplify scale-driven positions anchored in broad distribution infrastructure and novel mechanism development. Sun Pharmaceuticals occupies a cost-competitive archetype with emerging market manufacturing advantages. These three entities represent distinct strategic postures: multinational R&D intensity, global generic volume, and regional cost leadership.
| Leading Market Players |
|---|
| Pfizer |
| Merck |
| Novartis |
| Bayer |
| GlaxoSmithKline |
| Perrigo Company |
| Johnson and Johnson |
| Sun Pharmaceuticals |
| Taro Pharmaceutical Industries |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap generic manufacturers in India and China anchor terbinafine API production, translating concentrated upstream ownership into pricing discipline that resists commoditization pressure from Western retail pharmacy chains. Their captive fermentation and synthesis capabilities buffer margin erosion even as EMA excipient scrutiny extends development timelines for finished dose formulators.
Pricing Analysis
Volume concentrates in generic topical creams where retail pharmacy substitution mandates compress margins, while premium positioning persists for combination therapies and systemic agents requiring hepatotoxicity monitoring. Three-tier pricing structure separates rapid-diagnostic bundled dermatology clinic services from standard retail pharmacist counseling and economy self-pay channels. Pricing pressure stems from FDA abbreviated approval pathways flooding retail networks with bioequivalent alternatives. Hospital procurement committees exhibit lowest price sensitivity due to stewardship committee formulary controls, whereas online pharmacy price transparency drives aggressive discounting in the self-pay segment.
Supply Chain Analysis
Terbinafine hydrochloride synthesis rests on Chinese contract manufacturers clustered in Zhejiang and Jiangsu provinces, with Indian API specialists in Hyderabad and Mumbai providing secondary sourcing for azole intermediates. Key inputs include allylamine precursors, petroleum-derived ointment bases, and film-forming polymers for sustained-release prototypes. Single-source vulnerability concentrates in environmental compliance inspections disrupting Chinese fermentation facilities. Distribution runs through United States retail pharmacy networks and European community pharmacy chains, with cold-chain logistics constraining topical cream fulfillment in tropical climates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tinea corporis market sits in a formulation-technology transition as nanocarrier delivery systems displace conventional cream vehicles, compressing the efficacy gap between topical and oral regimens.
For Market Incumbents: Anticipate allylamine API supply disruption from Chinese environmental inspections by qualifying secondary Indian manufacturers under CDSCO frameworks. Lock in dermatology clinic network contracts before point-of-care diagnostics enable targeted generic substitution. Prioritize ISO 13485 certification investments to defend against EMA facility audit intensity. For New Entrants and Emerging Players: Telemedicine-integrated fulfillment platforms present the most penetrable channel for asynchronous diagnosis-to-prescription workflows. Target tier-two Indian cities where dermatology clinic networks extend beyond metropolitan cold-chain infrastructure. Lead with pharmacist training programs that bundle lesion examination certification with product distribution rights. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized generic topical specialists with captive API supply in India facing working capital pressure from extended EMA development timelines. Long-term viability hinges on portfolio diversification into combination therapies and sustained-release vehicles. Watch FDA ANDA approval velocity for generic allylamines as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Therapy Pipeline Expansion | Corticosteroid-antifungal fixed-dose products address rising treatment failure rates in refractory cases. |
| Point-of-Care Diagnostic Integration | Rapid KOH preparation assays at retail clinics enable targeted therapy selection over empirical prescribing. |
| Long-Acting Depot Formulation Development | Polymeric film-forming technology reduces pediatric dosing frequency from twice-daily to weekly applications. |
| Indian Tier-Two City Distribution Buildout | Cold-chain standardization in emerging dermatology networks captures underpenetrated outpatient demand. |
| EMA Excipient Safety Compliance Investment | Extended toxicology packages for novel penetration enhancers preempt twelve-to-eighteen month development delays. |
Research Methodology
Multi-period observation of FDA ANDA approval velocity, EMA centralized marketing authorization timelines, and retail pharmacy generic substitution rates anchored the trend analysis, supplemented by interviews with dermatology clinic directors, hospital pharmacy and therapeutics committee members, CDSCO regulatory affairs leads, and Indian API manufacturing executives. Secondary validation drew from FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov dermatophyte protocol registrations, and United States 340B program utilization data. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure estimates across the analysis window.
Segment-weighting applied product type, formulation, end-user setting, and distribution channel dimensions to derive volume and value outputs over the projection horizon. CAGRs were computed from fitted growth curves adjusted for regulatory pathway acceleration effects and telemedicine adoption inflection points. Treatment failure rate trends and combination therapy protocol penetration served as industry-specific forecast inputs alongside allylamine API supply concentration metrics.
Several conditions sit outside the modeled scope, including off-label herbal remedy consumption, veterinary dermatophyte product diversion, and cosmetic-grade tea tree oil substitution. Forecasts reflect documented assumptions about FDA approval pathway stability and EMA excipient guideline implementation timing. Antifungal resistance pattern emergence, Chinese environmental enforcement intensity, and telemedicine reimbursement policy shifts represent the small set of named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market