
 Scleritis Market | 2026-2036
Scleritis Market Size, Share, and Industry Trends Forecast 2026-2036
Scleritis Market Outlook
EMA's tightened pharmacovigilance requirements for ocular biologics is recalibrating the cost-of-entry calculus for European market participants. Novartis leverages its deep immunology pipeline to sustain leadership in biologic scleritis interventions. Bristol-Myers Squibb anchors its position through autoimmune expertise that extends into rare ophthalmic indications. Regeneron Pharmaceuticals differentiates via retinal therapy platforms that compete for specialist prescriber attention and hospital formulary slots.
Scleritis constitutes a serious inflammatory condition of the sclera, the white outer layer of the eye, characterized by severe pain, erythema, and potential threat to vision; treatment typically involves systemic corticosteroids, immunosuppressants, or targeted biologics depending on severity and underlying systemic association. The condition demands precise diagnostic differentiation from episcleritis and close monitoring for complications such as scleral thinning or uveal involvement. Injectable therapies command the deepest margin pools due to biologic pricing and infusion center economics, while topical agents occupy the high-volume entry segment for anterior disease management. Eye clinics represent the fastest-growing end-user channel as outpatient biologic administration expands and specialist referral networks consolidate regionally.
FDA oversight of ophthalmic biologics, EMA's MDR framework for device-drug combinations, and WHO essential medicines criteria for corticosteroid access collectively shape product development priorities and market access trajectories across jurisdictions. These frameworks determine trial design, manufacturing standards, and reimbursement eligibility for novel therapeutic entrants. Stakeholders must monitor how payer evidence requirements for biologic therapies evolve against the backdrop of autoimmune disease budget impact assessments.
Market Dynamics
The FDA's evolving guidance on ophthalmic biologics is compressing clinical trial timelines while elevating evidence thresholds, forcing developers to restructure development programs around adaptive study designs and real-world data collection.
Growth Catalysts
- Infusion center economics:Hospital-based ophthalmology departments are expanding outpatient biologic administration capacity, creating dedicated scleritis treatment protocols that streamline patient throughput and specialist utilization.
- EMA pharmacovigilance frameworks:Tightened post-market surveillance requirements for ocular biologics are accelerating investment in patient registries and long-term safety databases that support differentiated labeling claims.
- Biologic pricing models:Injectable therapies command sustained premium positioning through value-based contracting mechanisms that tie reimbursement to treatment response metrics in refractory cases.
Market Restraints
- Corticosteroid dependency:Systemic corticosteroids remain the first-line standard despite toxicity profiles, creating a high clinical threshold for biologic switching that slows adoption curves.
- Diagnostic complexity:Precise differentiation between scleritis and episcleritis demands specialist expertise that concentrates in tertiary eye care centers, limiting addressable patient pools.
- Reimbursement heterogeneity:Payer evidence requirements for biologic therapies vary across United States commercial plans and Medicare Advantage contracts, fragmenting market access strategies.
Strategic Opportunities
- Eye clinic channel expansion:Regional specialist referral networks are consolidating, creating integrated delivery networks that centralize biologic administration and capture patient volume from dispersed practices.
- Device-drug combination pathways:The EMA's MDR framework for device-drug combinations is opening regulatory routes for sustained-release ocular implants that reduce injection frequency.
- Autoimmune comorbidity protocols:Rheumatology-ophthalmology co-management programs are emerging as a channel for earlier biologic intervention in scleritis associated with systemic vasculitis.
Industry Challenges
- Ocular immunology specialization:The scarcity of fellowship-trained uveitis specialists constrains prescriber base expansion and limits protocol adoption outside major academic medical centers.
- Biologic cold chain integrity:Temperature-controlled logistics for ophthalmic biologics require specialized distribution infrastructure that elevates operational complexity for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scleritis Market |
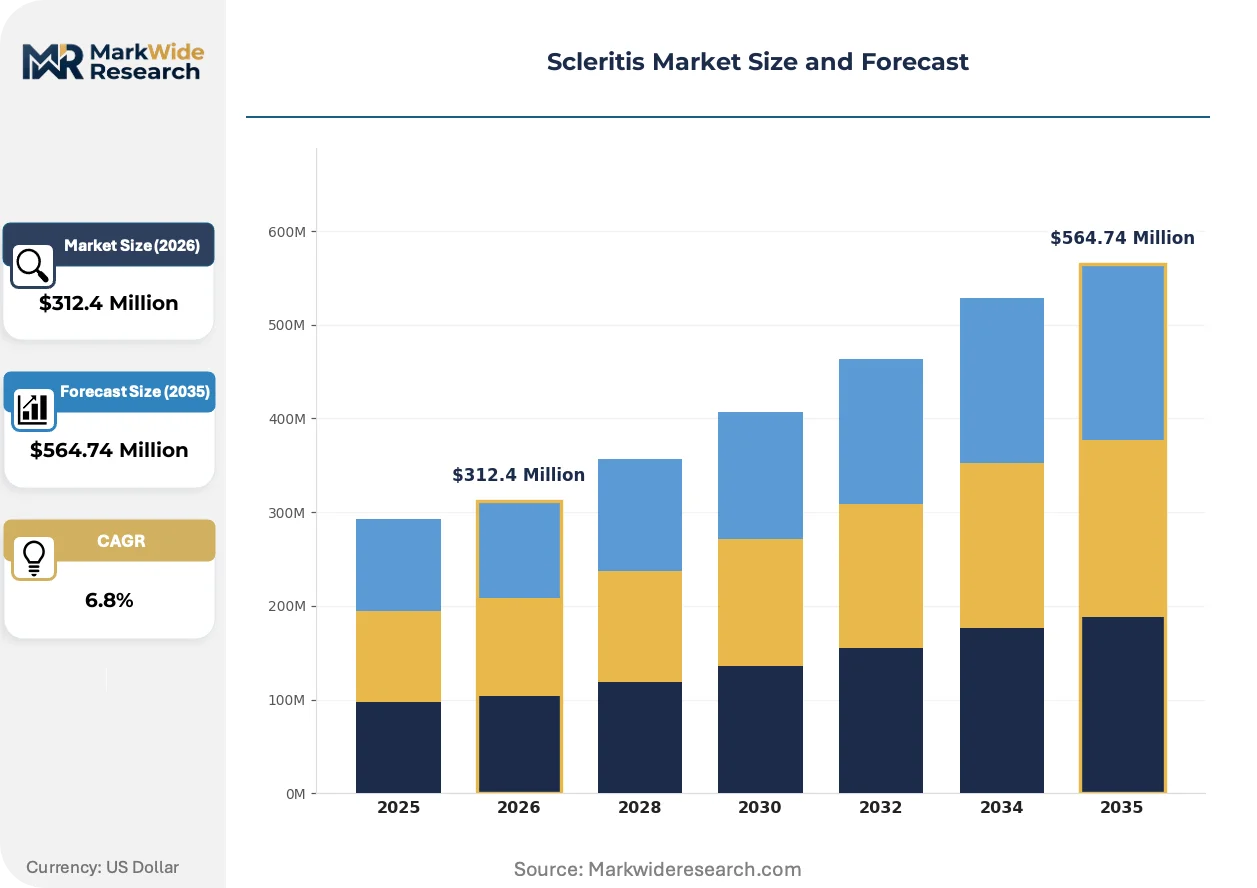
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Injectable Therapies, Surgical Procedures, Antimicrobials End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Intravitreal, Subconjunctival, Oral, Ocular Implants Application: Specialized Care, Emergency Treatment, Post-operative Care, Routine Check-ups |
| Companies Covered | Novartis, Amgen, Roche, Bristol-Myers Squibb, Pfizer, Regeneron Pharmaceuticals, Allergan, Santen Pharmaceutical, Horizon Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scleritis Market Strategic Shifts
Biologic therapy platforms are displacing conventional immunosuppression through mechanism-based targeting, while regulatory agencies recalibrate approval standards and care delivery models fragment across site-of-service boundaries.
Subconjunctival sustained-release implants are automating drug delivery for anterior scleritis by eliminating patient adherence variability. Tertiary eye care centers in the United States are piloting these devices for steroid-sparing maintenance therapy. This automation is compressing the treatment burden differential between biologics and conventional systemic therapy.
The EMA's tightened pharmacovigilance requirements for ocular biologics are mandating prospective safety registries as a condition of marketing authorization. Developers must now embed post-authorization study commitments into clinical development timelines. European market participants are responding by pre-positioning patient identification infrastructure and data capture systems prior to launch.
Specialist referral networks are consolidating regionally, concentrating biologic administration volume within integrated eye clinic platforms. Independent ophthalmology practices are affiliating with hospital systems to access formulary contracts and infusion center capacity. This channel shift is most visible in United States metropolitan markets where payer steerage incentives favor site-of-service cost differentials.
Scleritis Market Segmentation
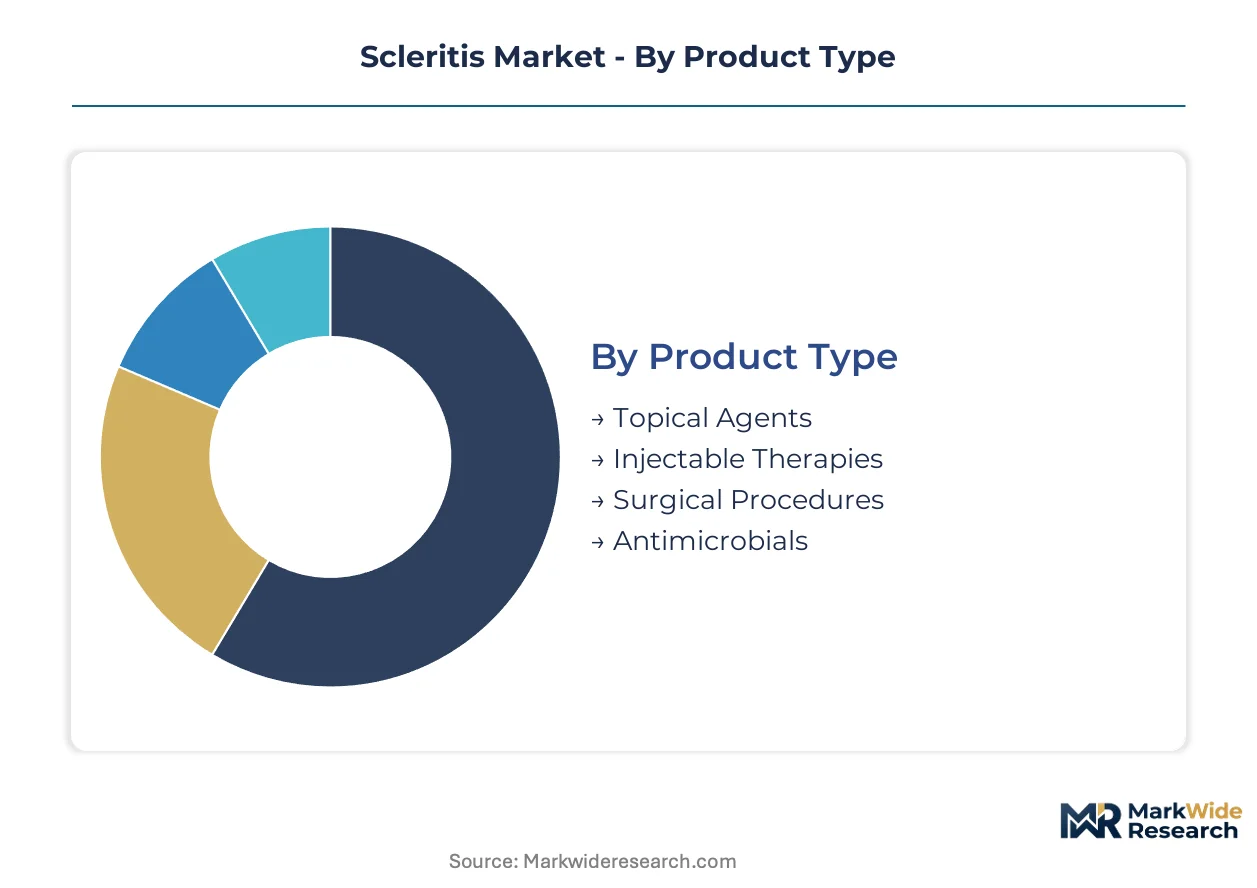
Scleritis treatment pathways fragment across site-of-service economics, biologic administration infrastructure, and diagnostic complexity tiers. Segmentation reveals where margin pools concentrate versus where patient volumes scale.
Product Type:
Standalone biologic formulations command premium positioning through infusion center capture, while embedded combination therapies integrate diagnostic and therapeutic workflows.
- Injectable Therapies:Biologic formulations including anti-TNF and anti-IL-6 agents deliver mechanism-based immunosuppression through hospital-based ophthalmology departments. Demand concentrates in United States tertiary eye care centers where rheumatology-ophthalmology co-management protocols drive earlier biologic switching in refractory cases.
- Topical Agents:Corticosteroid and non-steroidal anti-inflammatory formulations provide first-line anterior disease management through high-frequency dispensing. Volume scales through eye clinic channels in metropolitan markets where payer steerage favors outpatient site-of-service cost differentials.
- Surgical Procedures:Scleral grafting and patch graft interventions address complications including scleral thinning and perforation.
- Antimicrobials:Systemic and topical antimicrobial coverage targets infectious scleritis etiologies requiring pathogen-directed therapy.
Volume placements concentrate in Topical Agents; the faster expansion belongs to Injectable Therapies.
End User:
Cost tier stratification separates high-acuity inpatient administration from ambulatory channels capturing site-of-service arbitrage.
- Hospitals:Academic medical centers and community hospital ophthalmology departments anchor biologic infusion capacity, specialist referral networks, and emergency scleritis intervention. United States metropolitan clusters dominate formulary contract access for advanced immunotherapy.
- Eye Clinics:Regional specialist networks and integrated delivery platforms consolidate outpatient biologic administration, diagnostic imaging, and long-term monitoring. Affiliation with hospital systems enables infusion center access and payer contract participation.
- Ambulatory Surgical Centers:Same-day surgical intervention and implant procedures target cost-sensitive payers.
- Research Institutions:Clinical trial sites and academic research centers drive novel therapeutic investigation and registry participation.
Patient throughput concentrates in Hospitals; Eye Clinics are climbing the fastest as regional networks consolidate.
Delivery Mode:
Application specificity determines whether delivery integrates into routine outpatient workflows or requires specialized surgical infrastructure.
- Intravitreal:Direct vitreal cavity injection of corticosteroids and biologics addresses posterior segment involvement and uveal extension. United States retina specialists and uveitis fellowship-trained ophthalmologists control access through hospital-based surgical suites.
- Ocular Implants:Sustained-release subconjunctival and intravitreal implants automate drug delivery, eliminating adherence variability for maintenance therapy. Tertiary centers pilot steroid-sparing protocols with EMA MDR framework compliance requirements shaping development timelines.
- Subconjunctival:Periocular depot formulations provide intermediate-duration corticosteroid release for anterior disease.
- Oral:Systemic corticosteroids and immunosuppressants remain first-line for diffuse and necrotizing disease variants.
Procedure frequency concentrates in Intravitreal administration; Ocular Implants are gaining share fastest through sustained-release automation.
Application:
Customer type segmentation separates acute intervention episodes from longitudinal management relationships with distinct reimbursement profiles.
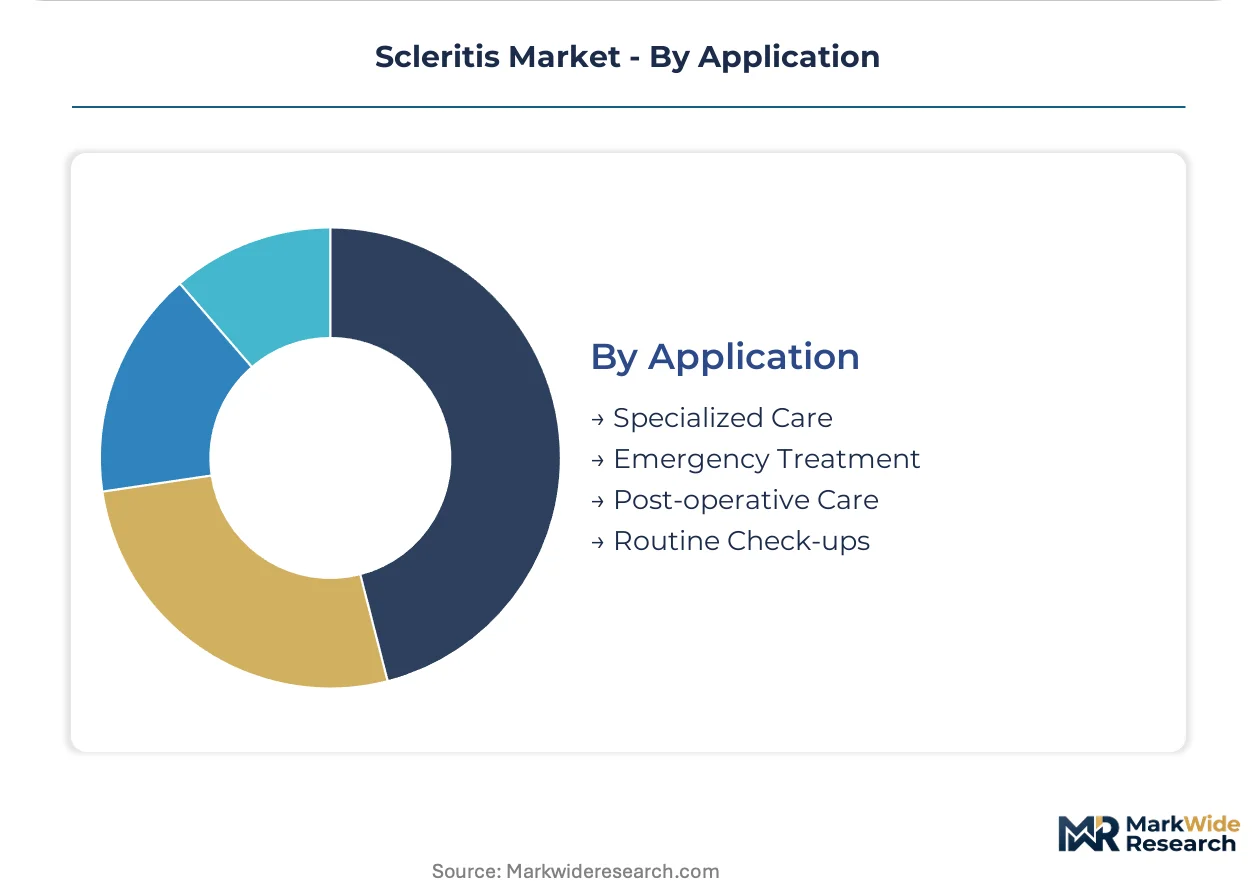
- Specialized Care:Fellowship-trained uveitis specialists and academic medical centers manage refractory, necrotizing, and systemic disease-associated scleritis through biologic protocols. United States tertiary eye care centers concentrate prescriber expertise and infusion infrastructure.
- Emergency Treatment:Acute presentation management including scleritis mimics, infectious etiologies, and vision-threatening complications demands rapid diagnostic differentiation and intervention.
- Post-operative Care:Surgical follow-up and complication management integrates implant monitoring and graft surveillance.
- Routine Check-ups:Maintenance monitoring and disease activity assessment supports long-term immunosuppression management.
Clinical encounters concentrate in Specialized Care; Emergency Treatment shows steepest expansion trajectory as diagnostic protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary eye care centers concentrate demand for biologic scleritis therapies, with rheumatology-ophthalmology co-management protocols driving earlier intervention in refractory cases. Hospital-based infusion capacity and specialist referral networks anchor adoption curves for advanced immunotherapy.
United States
FDA oversight of ophthalmic biologics shapes clinical trial design and approval timelines for developers targeting refractory disease. Medicare Advantage contracts and commercial payer evidence requirements fragment market access strategies across metropolitan markets. Boston and Baltimore academic medical centers pilot sustained-release implant protocols for steroid-sparing maintenance therapy.
Germany
EMA pharmacovigilance frameworks mandate prospective safety registries as conditions of marketing authorization for ocular biologics. The MDR framework for device-drug combinations opens regulatory pathways for sustained-release implants reducing injection frequency. Heidelberg and Munich university hospitals anchor specialist referral networks for necrotizing scleritis intervention.
Japan
PMDA consultation procedures for ophthalmic biologics compress development timelines through parallel scientific advice pathways. National health insurance reimbursement criteria for biologic therapies require demonstration of corticosteroid refractoriness. Tokyo and Osaka metropolitan clusters concentrate fellowship-trained uveitis specialists and infusion infrastructure.
United Kingdom
NICE technology appraisals for ophthalmic biologics establish cost-effectiveness thresholds that shape formulary access in National Health Service trusts. The MHRA's post-Brexit regulatory autonomy enables accelerated access pathways for innovative therapies. London and Manchester academic medical centers coordinate multicenter registry participation for EMA-aligned pharmacovigilance.
Switzerland
Swissmedic marketing authorization procedures for biologics emphasize quality system inspections and batch release protocols. Federal compulsory health insurance reimbursement decisions for high-cost ophthalmic therapies reference German and French pricing benchmarks. Basel and Zurich university hospitals integrate into cross-border specialist networks serving alpine region referral catchments.
Scleritis Market Competitive Environment
United States pharmaceutical developers anchor the biologic therapy tier; European and Japanese specialists hold positions in conventional immunosuppression and device-drug combinations. Market structure concentrates around large-cap immunology portfolios with ophthalmic extensions, mid-cap retinal therapy platforms competing for specialist attention, and regional players in topical formulations. Three archetypes dominate: integrated immunology conglomerates with deep autoimmune pipelines, retinal-focused biotechs leveraging uveitis specialist relationships, and ophthalmic device-drug combination developers. Competitive moves center on rheumatology-ophthalmology co-management program partnerships and sustained-release implant development timelines.
Within the integrated immunology tier, Novartis and Bristol-Myers Squibb occupy positions reflecting deep autoimmune expertise extending into rare ophthalmic indications. Regeneron Pharmaceuticals exemplifies the retinal therapy platform archetype, competing for hospital formulary slots and specialist prescriber attention against immunology-focused rivals. These three anchors represent distinct strategic postures: portfolio breadth against indication depth against platform specialization.
| Leading Market Players |
|---|
| Novartis |
| Amgen |
| Roche |
| Bristol-Myers Squibb |
| Pfizer |
| Regeneron Pharmaceuticals |
| Allergan |
| Santen Pharmaceutical |
| Horizon Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees and Medicare Advantage pharmacy benefit managers anchor pricing power in the scleritis market, concentrating demand for biologic therapies within formulary contracting frameworks that reward volume commitments and treatment response guarantees.
Pricing Analysis
Short lead-time availability commands premium positioning in biologic scleritis therapies, with hospital-based infusion centers negotiating rapid replenishment clauses against standard procurement schedules. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroids stratifies by mechanism specificity and administration complexity. Cost compression in topical corticosteroid tiers is intensifying because of generic substitution and payer steerage toward outpatient site-of-service alternatives. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers demonstrate lowest sensitivity through cost-plus accounting and research subsidy offsets.
Supply Chain Analysis
Temperature-controlled freight logistics for ophthalmic biologics elevate distribution costs substantially, requiring validated cold chain infrastructure from manufacturing through final patient administration. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and Singapore for biologic formulations, while corticosteroid raw materials source predominantly from India and China. Supply chain risk centers on single-source vulnerability for monoclonal antibody cell lines and fermentation capacity constraints. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with direct-to-clinic delivery models bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scleritis market operates as a cost-of-compliance arena where EMA pharmacovigilance frameworks and FDA ophthalmic biologic guidance erect substantial barriers to entry, rewarding players with pre-positioned patient registry infrastructure and adaptive trial capabilities.
For Market Incumbents: Cement formulary dominance through rheumatology-ophthalmology co-management program partnerships that lock in specialist referral flows and biologic switching protocols. Expand backward integration into cold chain distribution infrastructure to capture logistics margins and guarantee supply continuity against temperature excursion risks. Threat of mid-cap retinal therapy platforms competing for hospital pharmacy committee attention demands sustained KOL investment in uveitis fellowship programs. For New Entrants and Emerging Players: Sustained-release ocular implant technology offers a technology-first wedge into steroid-sparing maintenance protocols where injection frequency reduction commands premium positioning. Target eye clinic channel consolidation in United States metropolitan markets where regional network affiliation creates formulary access pathways absent from dispersed independent practice settings. Go-to-market angle should emphasize EMA MDR framework pre-compliance to accelerate European market entry against slower-moving incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor device-drug combination developers with Swissmedic quality certifications and pilot clinical data in necrotizing scleritis subpopulations. Long-term viability hinges on portfolio breadth across anterior and posterior segment indications with autoimmune comorbidity coverage. Signal to watch is rheumatology-ophthalmology joint venture formation velocity as indicator of protocol standardization and biologic adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Patient Registry Infrastructure Buildout | EMA pharmacovigilance mandates require prospective safety databases as marketing authorization conditions. |
| Sustained-Release Implant Development | MDR framework compliance opens regulatory pathways for injection-frequency-reducing ocular devices. |
| Rheumatology-Ophthalmology Partnership Programs | Co-management protocols drive earlier biologic intervention in systemic disease-associated scleritis cases. |
| Cold Chain Distribution Investment | Temperature-controlled logistics capabilities secure supply continuity for biologic therapies. |
| Uveitis Fellowship Training Sponsorship | Specialist pipeline expansion addresses prescriber scarcity constraining protocol adoption outside academic centers. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database reviews and hospital procurement contract analyses. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated quantitative assumptions and calibrated adoption curve parameters. Bottom-up patient flow modeling and top-down immunology market sizing were triangulated against infusion center capacity surveys and biologic pricing disclosure patterns.
Historical trendline analysis of corticosteroid-to-biologic switching rates, infusion center expansion trajectories, and specialist fellowship graduation volumes established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived through log-linear regression of proxy immunology indication expansion patterns adjusted for scleritis-specific diagnostic complexity and refractory case prevalence.
Several conditions sit outside the modeled scope, including novel infectious scleritis etiologies, gene therapy platform disruptions, and radical reimbursement restructuring under single-payer scenarios. Forecasts reflect assumptions about sustained corticosteroid refractoriness definitions and biologic access pathway stability. Stakeholders should weight assumptions against their own operating context and monitor FDA guidance evolution for ophthalmic biologics as a critical revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Ovarian Cancer Therapeutics Market