
 Global Specialty Pharmaceuticals Market | 2026-2036
Global Specialty Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Pharmaceuticals Market Foresight
Specialty pharmacy distribution is reconfiguring around limited distribution networks and hub service models that manage prior authorization and patient adherence. Roche leverages its diagnostics-pharmaceutical integration to control companion testing pathways. Novartis anchors its position through CAR-T cell therapy manufacturing scale. Eli Lilly and Company differentiates via peptide therapeutic innovation in metabolic disease.
Specialty pharmaceuticals encompass complex molecules requiring cold-chain handling, sterile compounding, or patient-specific manufacturing, with functional parameters including parenteral administration routes and biologic stability thresholds. These products serve therapeutic areas where standard small-molecule drugs fail, particularly in oncology and autoimmune conditions. Monoclonal antibodies occupy the largest revenue pool due to established reimbursement and manufacturing infrastructure. Advanced Therapy Medicinal Products represent the fastest-expanding segment as gene and cell therapies gain regulatory approvals. Oncology dominates therapy area demand, with immunology showing concentrated pricing power.
The FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for accelerated approvals, post-market surveillance, and manufacturing inspections that fragment market access timelines. REACH and the EU MDR impose additional substance safety and device-drug combination requirements on European entrants. Stakeholders must monitor evolving biosimilar interchangeability designations and gene therapy durability data to calibrate portfolio investments and manufacturing commitments.
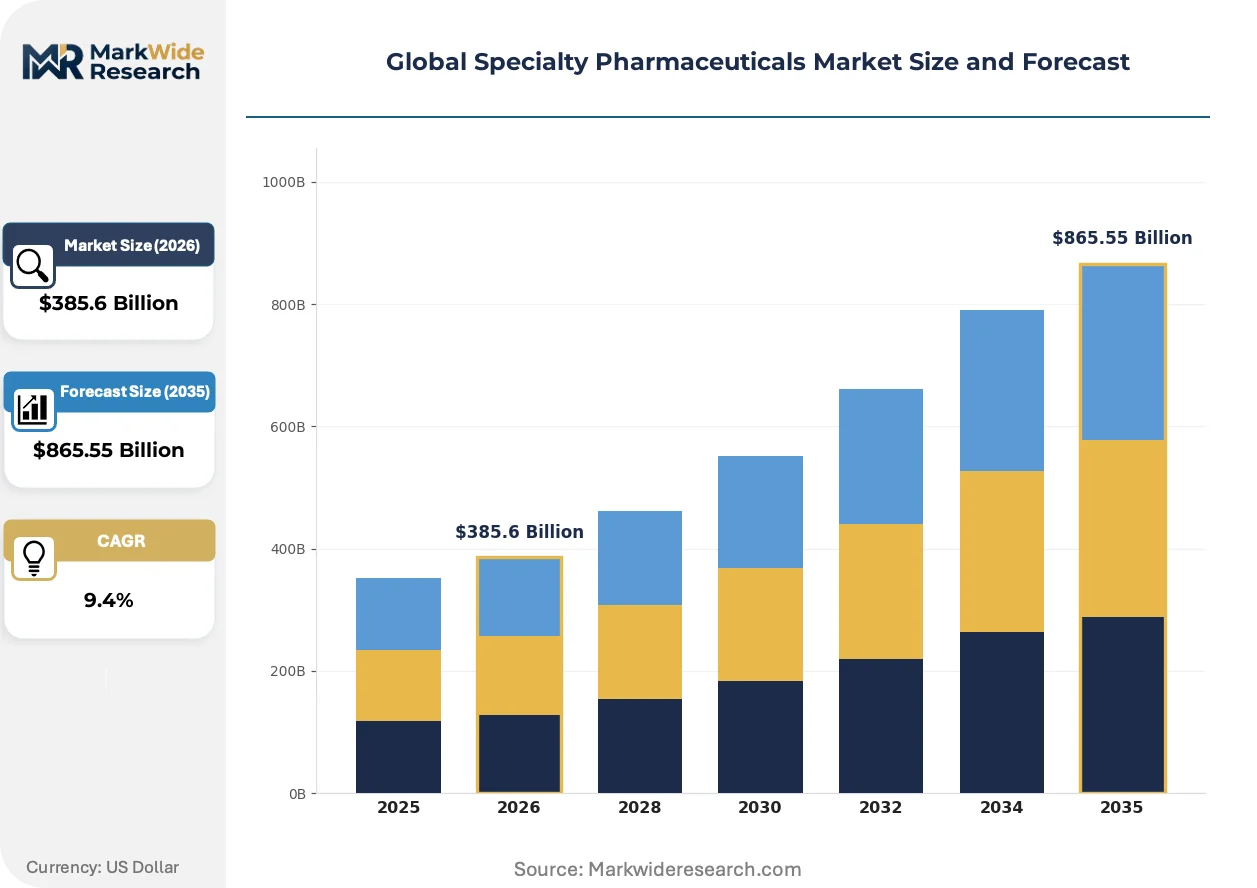
Market Dynamics
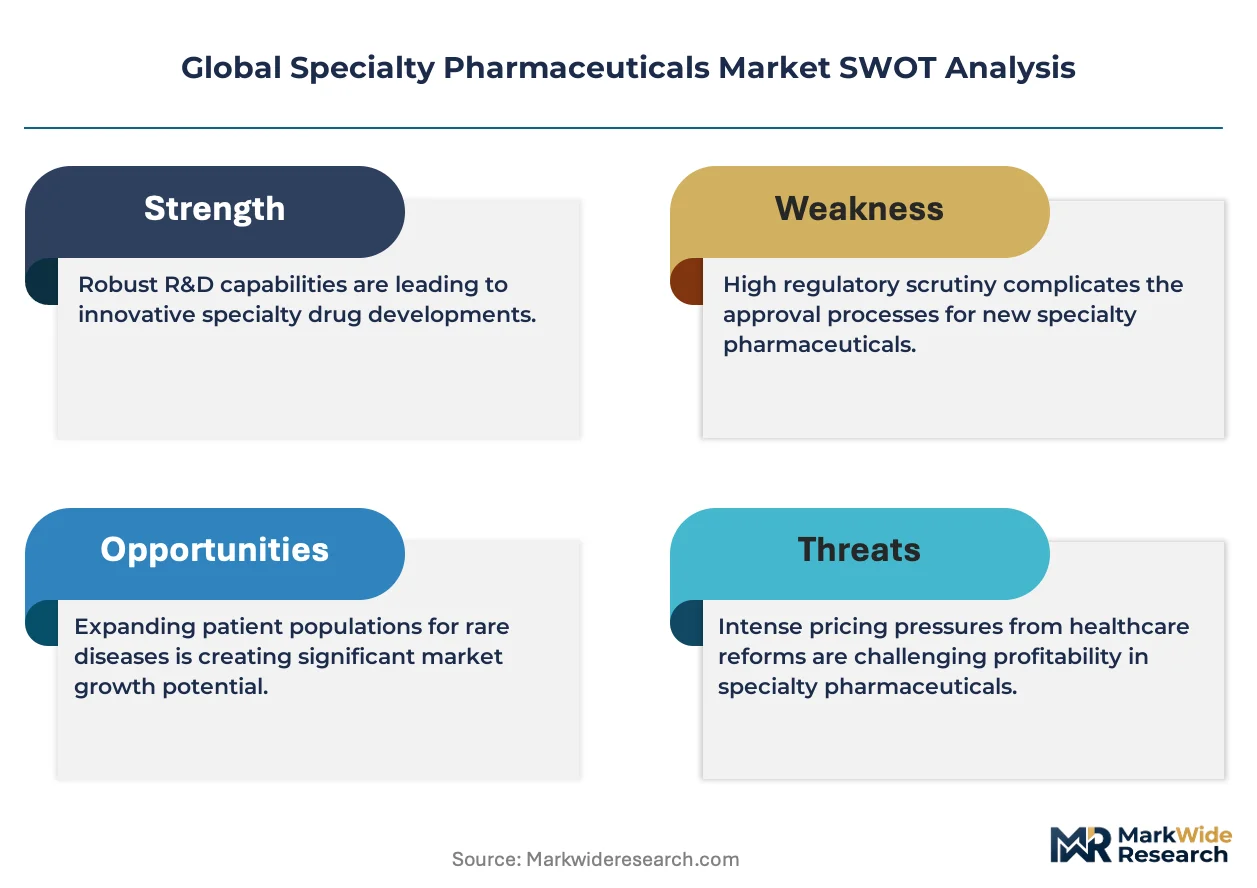
Companion diagnostic integration is compressing development timelines and forcing pharmaceutical manufacturers to secure parallel regulatory clearances for drugs and their paired tests. This structural pressure is reconfiguring R&D partnerships and reshaping how clinical evidence packages are assembled for FDA, EMA, and PMDA submissions.
Growth Catalysts
- FDA Accelerated Approval Pathway:This framework permits earlier market entry for therapies addressing unmet medical needs, particularly in oncology, contingent on confirmatory trials. The mechanism compresses time-to-revenue for developers of breakthrough biologics.
- CAR-T Manufacturing Scale-Up:Automated cell processing platforms are expanding production capacity for patient-specific immunotherapies. Health systems in Germany and Japan are investing in point-of-care manufacturing infrastructure to reduce vein-to-vein timelines.
- Biologics Reimbursement Frameworks:Germany's G-BA and Japan's Chuikyo have established favorable pricing mechanisms for high-cost specialty drugs demonstrating added therapeutic benefit. These structures sustain premium pricing for innovative modalities.
Market Restraints
- Cold-Chain Infrastructure Concentration:Ultra-low temperature storage and distribution capabilities concentrate among third-party logistics providers in the United States and Western Europe. This geographic clustering limits market access for temperature-sensitive gene therapies in emerging markets lacking validated cold-chain networks.
- Plasmid DNA Supply Bottlenecks:Viral vector manufacturing depends on high-quality plasmid inputs produced by a contracted supplier base. Capacity constraints at specialized CDMOs are extending lead times for cell therapy developers.
- EMA Post-Authorization Safety Study Requirements:Conditional marketing authorizations mandate extensive real-world evidence collection. The compliance burden diverts resources from pipeline expansion toward pharmacovigilance infrastructure.
Strategic Opportunities
- Hub Service Model Penetration in Brazil:Limited distribution networks and patient support programs remain underdeveloped in Latin America's largest pharmaceutical market. ANVISA's evolving biosimilar pathway creates entry points for integrated specialty pharmacy services.
- Peptide-Drug Conjugate Innovation:Convergence of peptide targeting precision with cytotoxic payloads is opening new therapeutic indices in solid tumors. ADC engineering expertise is transferring to this adjacent modality class.
- India's PLI Scheme for Biopharmaceuticals:Production-linked incentives for biosimilar and recombinant protein manufacturing are attracting contract development investment. CDSCO's streamlined approval timelines for certain biologics categories reduce regulatory friction.
Industry Challenges
- ATMP Qualified Personnel Scarcity:Cell and gene therapy manufacturing requires expertise spanning virology, immunology, and cGMP compliance. The talent pool for aseptic processing of living drug products remains shallow relative to expansion plans.
- Companion Diagnostic Co-Development Complexity:Synchronizing pharmaceutical and in vitro diagnostic development timelines creates regulatory risk. Misalignment between CDx analytical validation and drug clinical readouts can delay submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Pharmaceuticals Market |
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $865.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Biosimilars, Advanced Therapy Medicinal Products, Monoclonal Antibodies, Peptide Therapeutics Therapy Area: Oncology, Rheumatology, Neurology, Rare Diseases, Immunology End User: Hospitals, Specialty Clinics, Research Institutes, Ambulatory Care Centers, Home Healthcare Distribution Channel: Specialty Pharmacies, Hospital Pharmacies, Direct-to-Physician, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Roche, Novartis, Eli Lilly and Company, Amgen, Merck, Johnson & Johnson, AstraZeneca, Gilead Sciences, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Pharmaceuticals Market Shifts & Advancements
Digital twin technology is virtualizing process development and quality assurance workflows across the specialty pharmaceutical value chain. These simulations compress validation timelines and reduce physical batch failures before commercial scale-up.
Digital twins of bioreactor operations are enabling real-time parameter optimization without interrupting active production runs. Contract manufacturers at Singapore's Tuas Biomedical Park and North Carolina's Research Triangle are deploying these virtual environments to accelerate tech transfer. The technology is virtualizing traditional scale-up risk, allowing developers to predict critical quality attributes across multiple production scales before committing physical capacity.
REACH substance registration requirements are forcing reformulation of excipients and device components in European-bound combination products. The regulatory pressure is accelerating migration toward bio-based alternatives for certain polymer materials. Oncology autoinjector developers are responding by qualifying new elastomer formulations that satisfy both EMA device-drug requirements and ECHA substance safety thresholds.
Hospital purchasing consortiums in the United States are consolidating specialty drug procurement under single-source agreements with integrated pharmacy benefit managers. This buyer concentration is displacing fragmented wholesaler relationships and demanding bundled adherence monitoring services. The restructuring is most visible in oncology infusion networks across Texas and Florida, where health systems are internalizing prior authorization management previously handled by external hubs.
Global Specialty Pharmaceuticals Market Segmentation
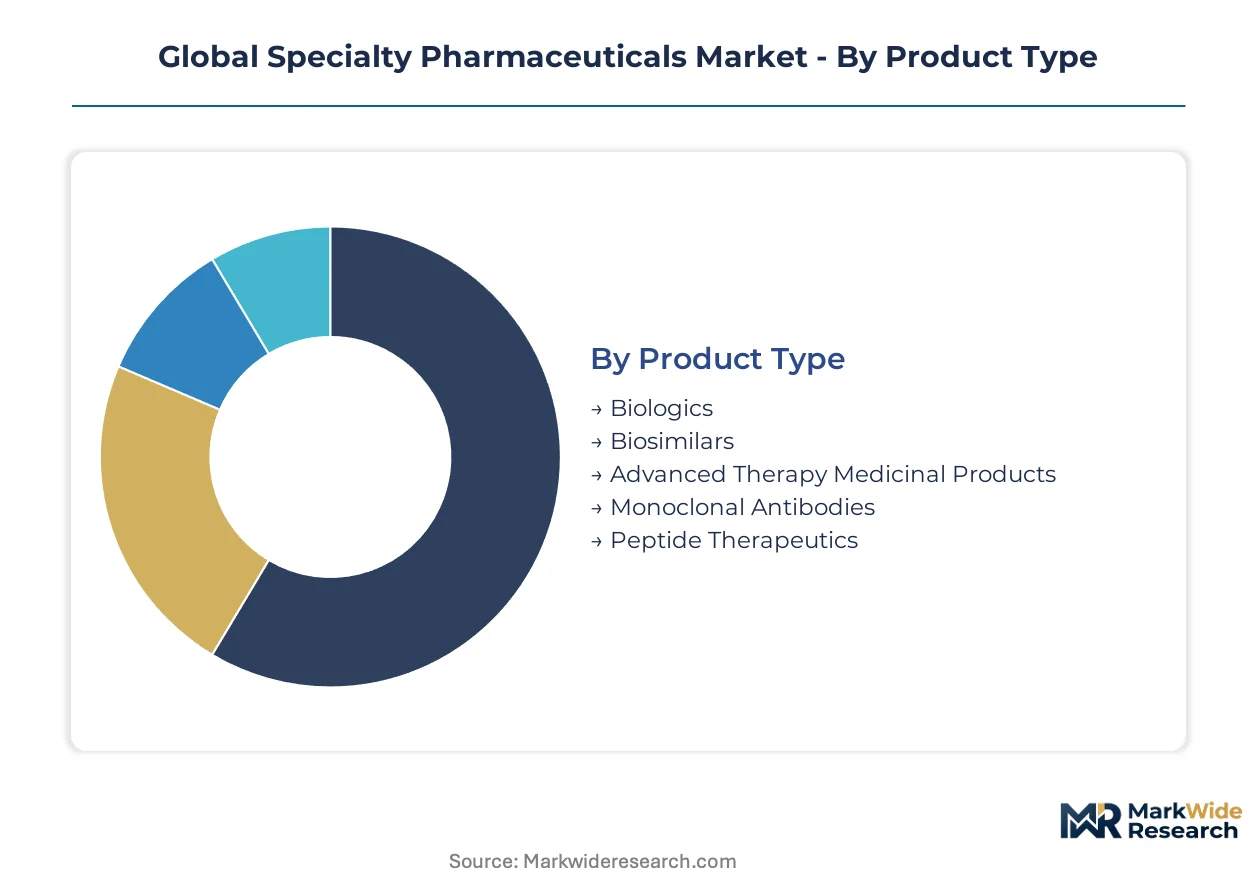
Specialty pharmaceutical segmentation reveals how molecular complexity, therapeutic application, and care setting interlock to determine pricing power, distribution requirements, and manufacturing investment. Each dimension carries distinct regulatory, reimbursement, and supply chain implications that reshape competitive positioning across the value chain.
Product Type:
Cost tier stratification separates blockbuster biologics from emerging modalities with divergent capital intensity and margin profiles.
- Biologics:Complex proteins manufactured in living cell systems demand sterile bioreactor capacity and cold-chain integrity. Demand concentrates in United States oncology infusion centers where Medicare Part B reimbursement sustains premium pricing for originator molecules.
- Advanced Therapy Medicinal Products:Patient-specific cell and gene therapies require vein-to-vein logistics coordination and point-of-care manufacturing infrastructure. German university hospitals and Japanese cancer centers are deploying automated cell processing platforms to compress production timelines.
- Monoclonal Antibodies:Established manufacturing templates and validated purification protocols anchor the largest revenue pool across autoimmune and oncology indications.
- Biosimilars:Interchangeability designations from FDA and EMA are unlocking pharmacy-level substitution in rheumatology and oncology supportive care.
- Peptide Therapeutics:Solid-phase synthesis and recombinant production methods serve metabolic disease applications with improved stability profiles.
Monoclonal antibodies hold installed capacity. Advanced Therapy Medicinal Products are rotating up the share rankings.
Therapy Area:
Application focus determines clinical trial design, companion diagnostic requirements, and prescriber concentration patterns.
- Oncology:Immunotherapy and targeted small molecules dominate pipeline investment, with FDA accelerated approvals compressing development timelines. United States academic medical centers concentrate demand for CAR-T and checkpoint inhibitor administration.
- Immunology:Rheumatoid arthritis and psoriasis indications sustain pricing power through differentiated mechanisms of action and limited biosimilar erosion.
- Rare Diseases:Ultra-small patient populations command orphan drug premiums and expedited regulatory pathways across EMA and PMDA jurisdictions.
- Neurology:Blood-brain barrier penetration challenges and complex diagnostic requirements limit competitive entry in multiple sclerosis and Alzheimer's disease.
Oncology commands development resources. Immunology is rotating up the share rankings.
End User:
Customer type dictates site-of-care economics, reimbursement mechanics, and adherence monitoring infrastructure.
- Hospitals:Integrated health systems in Texas and Florida are consolidating specialty drug procurement under single-source agreements with captive pharmacy benefit managers. Infusion center networks internalize prior authorization management and patient adherence tracking.
- Home Healthcare:Subcutaneous formulation advances and connected delivery devices are shifting administration from clinic to residential settings. Reimbursement frameworks in Germany and Japan are adapting to support remote patient monitoring for biologic self-injection.
- Specialty Clinics:Focused rheumatology and gastroenterology practices concentrate demand for immunology biologics with established REMS programs.
- Ambulatory Care Centers:Freestanding oncology infusion sites compete on vein-to-vein timelines and hub service integration.
- Research Institutes:Early-phase clinical trial sites drive demand for investigational ATMPs and companion diagnostic development.
Hospitals hold installed capacity. Home Healthcare is rotating up the share rankings.
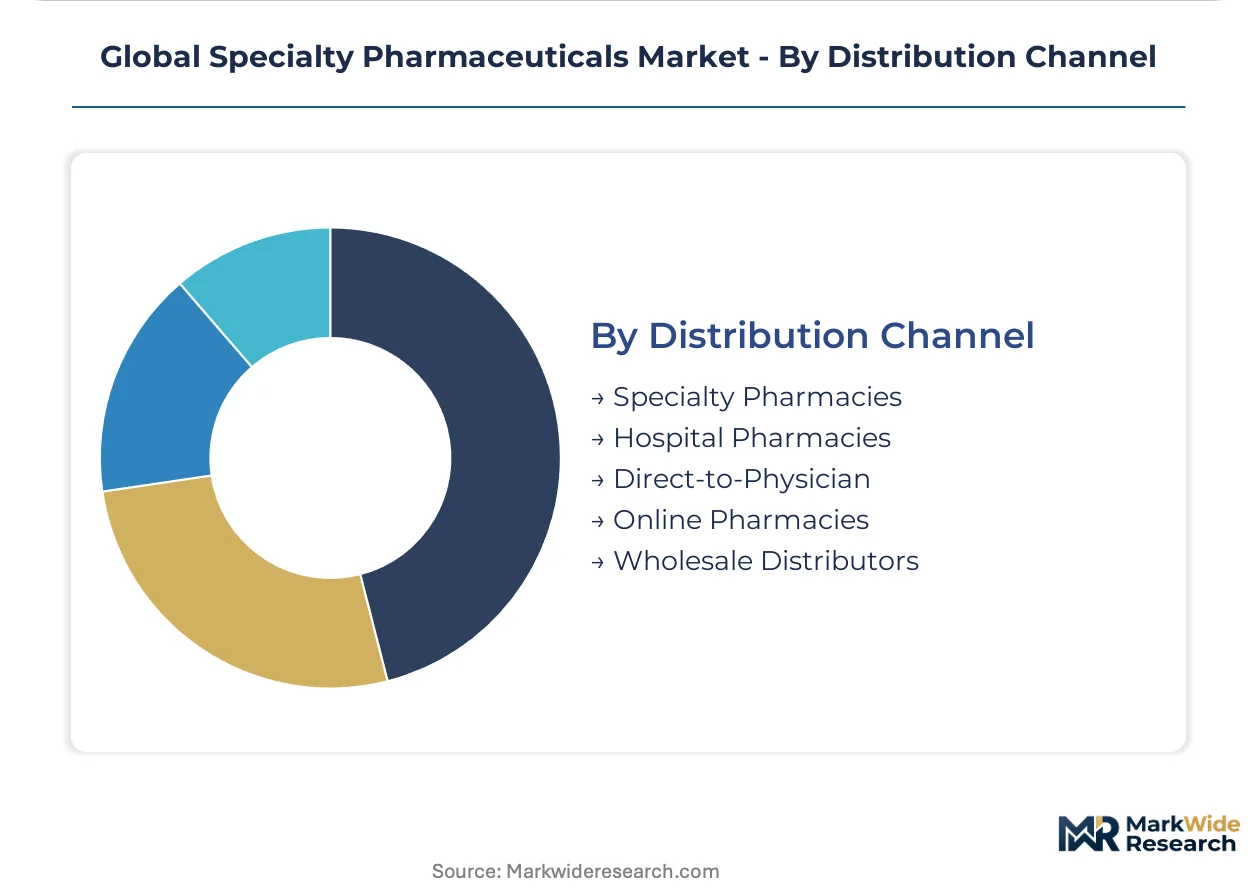
Distribution Channel:
Supply concentration patterns determine patient access timelines, data capture capabilities, and stakeholder margin allocation.
- Specialty Pharmacies:Limited distribution networks and hub service models manage prior authorization, benefits investigation, and adherence monitoring. United States specialty pharmacy consolidation is displacing fragmented wholesaler relationships.
- Hospital Pharmacies:Health system internalization of oncology drug procurement demands bundled adherence services and real-world evidence generation.
- Direct-to-Physician:Cell therapy vein-to-vein logistics require coordinated manufacturer-physician channels without intermediary storage.
- Wholesale Distributors:Cold-chain validation and ultra-low temperature capabilities concentrate among third-party logistics providers in the United States and Western Europe.
- Online Pharmacies:Regulatory frameworks for temperature-sensitive biologics remain underdeveloped outside established markets.
Specialty Pharmacies hold installed capacity. Hospital Pharmacies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and reimbursement reforms are redistributing specialty pharmaceutical manufacturing and consumption across major economies. Germany's G-BA benefit assessments, Japan's Chuikyo pricing mechanisms, and India's PLI scheme for biopharmaceuticals are accelerating facility investments and market access negotiations.
United States
Medicare Part B reimbursement sustains premium pricing for oncology biologics administered in hospital outpatient departments. The FDA's accelerated approval pathway compresses development timelines for breakthrough therapies. Texas and Florida health systems are consolidating specialty drug procurement under integrated pharmacy benefit managers.
Germany
G-BA early benefit assessments determine reimbursement levels for innovative biologics entering the statutory health insurance system. EMA post-authorization safety study requirements impose extensive real-world evidence collection obligations. Bavarian university hospitals are deploying automated cell processing platforms for CAR-T manufacturing.
Japan
Chuikyo pricing reviews establish favorable mechanisms for high-cost specialty drugs demonstrating added therapeutic benefit. PMDA regulatory standards for gene therapy durability data influence global development strategies. Tokyo and Osaka cancer centers are investing in point-of-care manufacturing infrastructure.
India
CDSCO streamlined approval timelines for certain biologics categories reduce regulatory friction for biosimilar developers. The PLI scheme for biopharmaceuticals attracts contract development investment for recombinant protein manufacturing. Maharashtra and Telangana clusters are expanding sterile bioreactor capacity.
Switzerland
Swissmedic maintains alignment with EMA standards while offering expedited pathways for orphan drugs and advanced therapies. Basel's pharmaceutical cluster concentrates diagnostics-pharmaceutical integration capabilities. The country's bilateral agreements with the EU facilitate combination product market access.
Global Specialty Pharmaceuticals Market Competitive Landscape
On the supply side, the industry is consolidating around integrated diagnostics-pharmaceutical platforms and patient-specific manufacturing capabilities. Large-cap developers with companion diagnostic capabilities and cell therapy manufacturing scale occupy the premium tier, while mid-cap biologics specialists and emerging gene therapy platforms populate growth segments. Strategic moves center on CAR-T manufacturing automation partnerships and limited distribution network consolidation for hub service penetration.
Within the integrated platform tier, Roche exemplifies diagnostics-pharmaceutical convergence, while Novartis anchors patient-specific immunotherapy manufacturing scale. Eli Lilly and Company occupies a position in peptide therapeutic innovation for metabolic disease applications.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Eli Lilly and Company |
| Amgen |
| Merck |
| Johnson & Johnson |
| AstraZeneca |
| Gilead Sciences |
| AbbVie |
| Others |
Supply & Pricing Matrix
Plasmid DNA manufacturing concentration in the United States and Western Europe anchors margin capture for cell therapy developers, while German G-BA benefit assessments determine reimbursement floors for innovative biologics entering statutory health insurance systems. This upstream supplier geography directly shapes where pharmaceutical manufacturers can sustain premium pricing versus where cost compression dominates.
Pricing Analysis
Volume-discount tiering structures separate originator biologics from biosimilars and emerging ATMPs across three distinct price bands. Medicare Part B reimbursement sustains premium pricing for oncology biologics administered in hospital outpatient departments, while Germany's G-BA and Japan's Chuikyo establish added-benefit thresholds that determine coverage levels. Pricing pressure stems from biosimilar interchangeability designations unlocking pharmacy-level substitution in rheumatology. Hospital purchasing consortiums in Texas and Florida exhibit highest price sensitivity through consolidated procurement under single-source agreements, whereas ATMP developers with patient-specific manufacturing maintain lowest sensitivity due to limited competitive alternatives.
Supply Chain Analysis
Export-control regimes limiting viral vector and plasmid DNA technology transfers constrain supply expansion for gene therapy developers. Manufacturing concentrates in the United States, Germany, and Switzerland where cGMP bioreactor capacity and automated cell processing platforms cluster. Cold-chain infrastructure draws from specialized third-party logistics providers with ultra-low temperature capabilities, while sterile compounding inputs rest on qualified elastomer and polymer suppliers. Single-source vulnerability runs through contracted CDMO capacity for patient-specific immunotherapies. Distribution runs through limited specialty pharmacy networks managing prior authorization and vein-to-vein logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against biosimilar substitution and CAR-T manufacturing scale-up by emerging competitors, treating this market as a substitution defense where interchangeability designations threaten originator revenue pools.
For Market Incumbents: Pre-empt biosimilar erosion by securing interchangeability-blocking formulation patents and backward integration into companion diagnostic manufacturing to control testing pathways. Invest in automated cell processing platforms at Bavarian and Tokyo manufacturing sites to compress vein-to-vein timelines against Novartis-scale competitors. Channel control through captive specialty pharmacy networks defends margin position against consolidated hospital purchasing consortiums. For New Entrants and Emerging Players: Pursue white-space penetration in Brazil's underdeveloped hub service infrastructure where ANVISA's evolving biosimilar pathway creates entry points for integrated patient support programs. Target India's PLI scheme for biopharmaceuticals to access CDSCO streamlined approval timelines for recombinant protein categories. A direct-to-physician distribution model bypasses concentrated specialty pharmacy networks for cell therapies requiring coordinated vein-to-vein logistics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO platforms possessing cGMP viral vector capacity and automated cell processing expertise. Long-term viability over the next decade hinges on manufacturing scale rather than pipeline depth alone. Acquisition targets should demonstrate locked-in partnerships with at least two of Roche, Novartis, or Eli Lilly. The signal to watch is EMA post-authorization safety study compliance burden diverting resources from pipeline expansion, which would compress valuations for conditional marketing authorization holders.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA parallel clearance requirements compress combined drug-test submission timelines for oncology developers. |
| CAR-T Manufacturing Automation | German university hospitals deploying automated platforms reduce vein-to-vein intervals for patient-specific immunotherapies. |
| Limited Distribution Network Consolidation | Specialty pharmacy hub services capture prior authorization and adherence monitoring revenue from fragmented wholesalers. |
| Peptide-Drug Conjugate Pipeline Expansion | ADC engineering expertise transfers to solid tumor applications with improved therapeutic indices. |
| Point-of-Care Manufacturing Infrastructure | Japanese cancer centers investing in localized cell processing bypass cold-chain concentration risks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA accelerated approval filings, EMA post-authorization safety study databases, ClinicalTrials.gov intervention records, and G-BA benefit assessment documentation. Bottom-up patient-flow modeling and top-down reimbursement expenditure analysis were triangulated to anchor volume and value estimates.
Calibration against historical approval-to-launch intervals and pricing trajectory patterns informed projection mechanics across the analysis window. Segmentation dimensions included molecular complexity tier, therapeutic area concentration, administration route, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating therapy line progression and biosimilar erosion rates. Forecast inputs encompassed CDSCO approval timeline trends and PLI scheme facility commissioning schedules.
Sensitivities concentrate around EMA conditional marketing authorization conversion rates and FDA confirmatory trial completion patterns. Forecasts reflect assumptions regarding G-BA and Chuikyo pricing mechanism stability. Material shifts in biosimilar interchangeability designation timelines or ATMP manufacturing scale-up success rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market