
 Adenosine Market | 2026-2036
Adenosine Market Size, Share, and Industry Trends Forecast 2026-2036
Adenosine Market Analytics
Modular dosing configurations for adenosine is hardening as hospitals seek flexible vial-to-syringe formats that reduce waste across weight-based protocols. Pfizer leverages its sterile injectable infrastructure to supply prefilled syringes into North American catheterization labs. Astellas Pharma anchors Japanese hospital demand through long-standing cardiology partnerships. Teva Pharmaceuticals competes on cost-positioned multi-dose vials for emerging market tenders.
Adenosine is a purine nucleoside composed of adenine bound to ribose, functioning as a short-acting AV nodal blocking agent with a half-life under 10 seconds due to rapid cellular uptake and metabolism. Manufacturers synthesize it via fermentation or chemical phosphorylation routes, with purity specifications typically exceeding 99% to meet injectable-grade pharmacopeial standards. Injectable formulations dominate revenue owing to the drug's negligible oral bioavailability and institutional preference for IV push administration in emergency arrhythmia conversion. Cardiac arrhythmia applications generate the deepest margin pools as procedural volumes in electrophysiology labs expand, while research laboratories represent a faster-growing demand pocket driven by adenosine receptor pharmacology studies.
FDA cGMP inspections and EMA Good Manufacturing Practice guidelines enforce sterility assurance and endotoxin limits that shape supplier qualification timelines for parenteral adenosine. The EPA monitors solvent discharge from chemical synthesis facilities, particularly dichloromethane use in phosphorylation pathways. WHO Model List of Essential Medicines inclusion sustains procurement priority in national health systems. Stakeholders must track how regional hospital formulary consolidation and biosimilar pressure on reference-listed prices reshape contracting leverage for originator manufacturers.
Market Dynamics
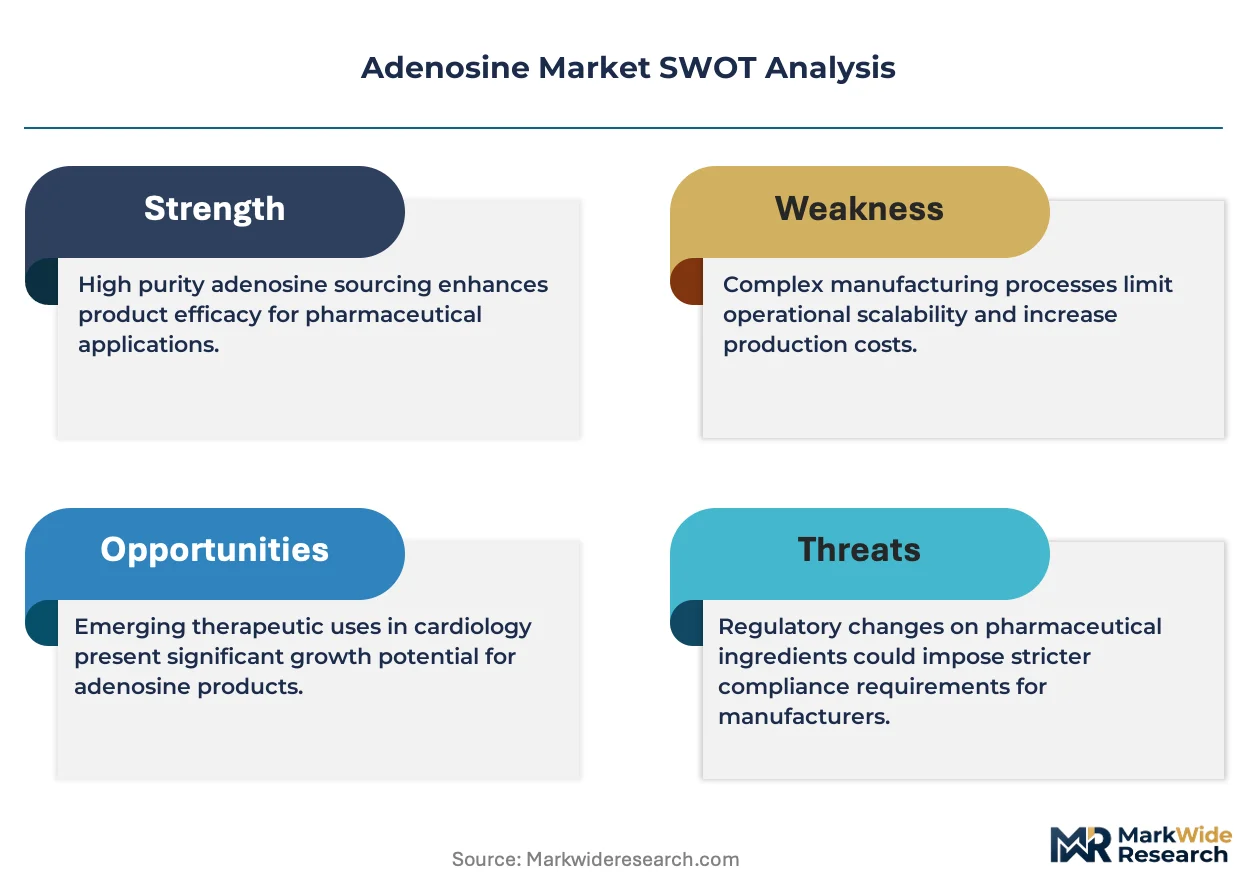
Hospital formulary consolidation and tightening sterility standards are compressing supplier margins while concentrating purchasing power among integrated health networks.
Growth Catalysts
- Catheterization Lab Expansion:Elective electrophysiology procedure volumes climb as tertiary cardiac centers add hybrid operating suites across the United States and Germany.
- FDA cGMP Enforcement:Heightened inspection frequency for parenteral antiarrhythmics is disqualifying subscale manufacturers and opening tender slots for qualified suppliers.
- Adenosine Receptor Research:Academic pharmacology departments in Japan and Switzerland are expanding compound procurement for inflammation and neurodegeneration studies.
Market Restraints
- Dichloromethane Feedstock Volatility:Chemical synthesis routes depend on solvent supplies subject to EPA discharge permitting delays and spot price swings.
- Single-Source Fermentation Capacity:Biotechnological production concentrates among three contract manufacturers in South Korea and Ireland, creating geographic supply risk.
- Oral Bioavailability Ceiling:Adenosine's rapid first-pass metabolism blocks tablet formulation development, restricting revenue to injectable formats with higher cold-chain costs.
Strategic Opportunities
- Prefilled Syringe Conversion:Catheterization labs in Texas and California are retiring multi-dose vials to reduce dosing errors and waste in weight-based protocols.
- Indian Hospital Tenders:WHO Essential Medicines status unlocks centralized procurement at state medical services corporations with multi-year supply agreements.
- Stability-Enhanced Lyophilization:Freeze-dried presentations are absorbing interest from rural hospitals with limited refrigeration infrastructure in Australia and Canada.
Industry Challenges
- Endotoxin Testing Bottlenecks:USP <85> Limulus amebocyte lysate assay capacity constraints at contract labs are extending batch release timelines.
- Sterile Fill-Finish Qualification:Isolator technology upgrades require capital deployment exceeding $40 million per line, favoring incumbents with depreciated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adenosine Market |
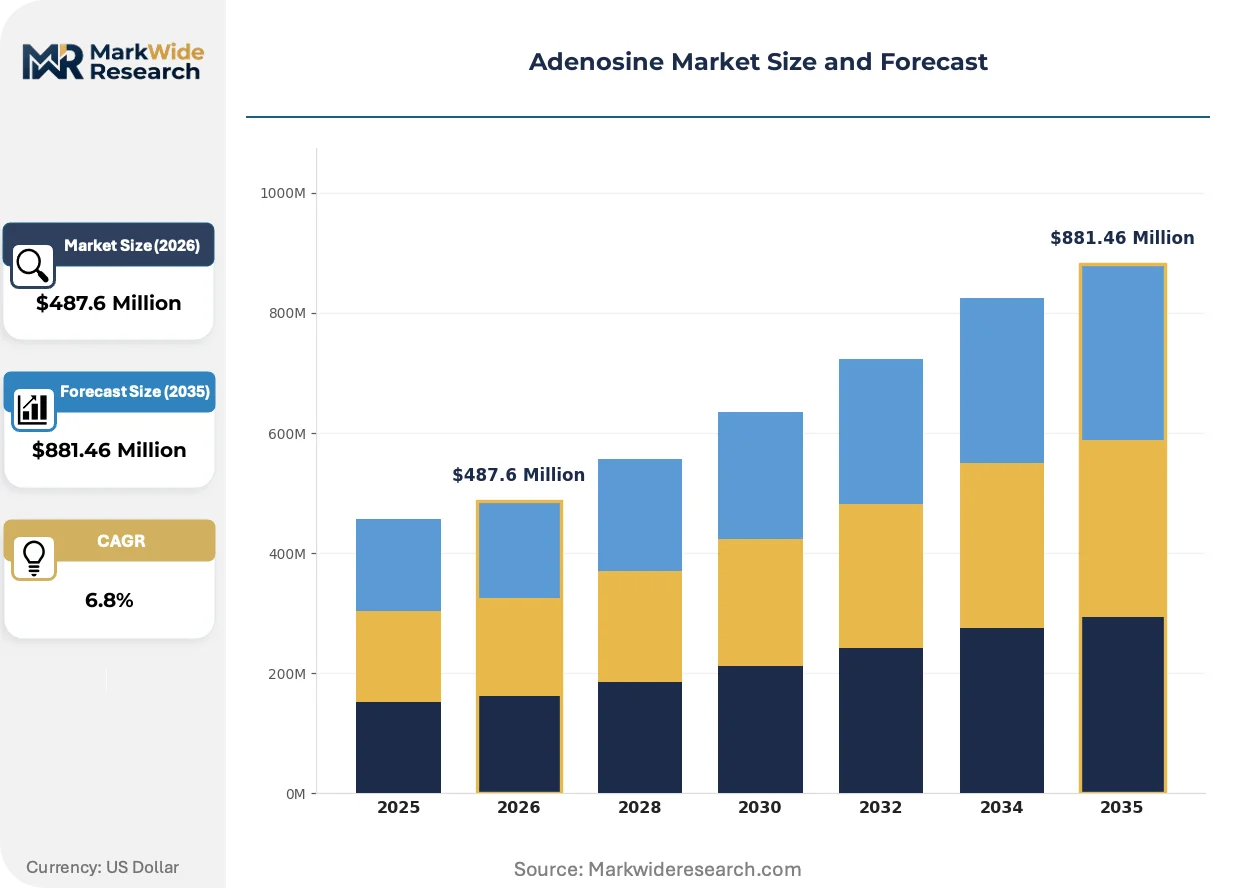
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Solution, Infusion, Inhalation Application: Cardiac Arrhythmia, Stress Testing, Antidote for Toxicity, Heart Surgery End User: Hospitals, Clinics, Pharmaceutical Companies, Research Laboratories Distribution Channel: Direct Sales, Online Pharmacy, Retail Pharmacy, Wholesale |
| Companies Covered | Astellas Pharma, Sanofi, Pfizer, Celon Laboratories, Torrent Laboratories, Sun Pharmaceuticals, Novartis, Sagent Pharmaceuticals, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adenosine Market Evolving Landscape
Manufacturing technology and procurement models are converging to reshape how adenosine reaches end-users, with sterility assurance and dosing precision commanding premium positioning.
Continuous manufacturing for parenteral nucleosides is absorbing capital allocation from batch fermentation systems. Pfizer and Lonza are retrofitting legacy stainless-steel trains with single-use bioreactor skids to reduce cross-contamination risk between cardiac and oncology product runs. This shift is absorbing smaller contract manufacturers unable to fund isolator technology upgrades, compressing the qualified supplier base to six facilities globally.
EMA's revised Annex 1 sterile manufacturing guidelines, effective August 2023, mandate barrier isolation for all Grade A operations. European fill-finish contractors are decommissioning open Restricted Access Barrier Systems and installing closed isolator lines with vaporized hydrogen peroxide decontamination cycles. Parenteral adenosine batches for EU hospital tenders now require six-month stability data from isolator-produced lots, extending development timelines for new market entrants.
Catheterization lab purchasing committees are consolidating vendor lists to single-source agreements with 24-hour emergency stockholding clauses. Texas Medical Center and Cleveland Clinic have eliminated secondary adenosine suppliers, trading price competition for guaranteed availability during STEMI surge events. This concentration is most visible in United States academic medical centers with electrophysiology fellowship programs exceeding 200 annual procedures.
Adenosine Market Segmentation
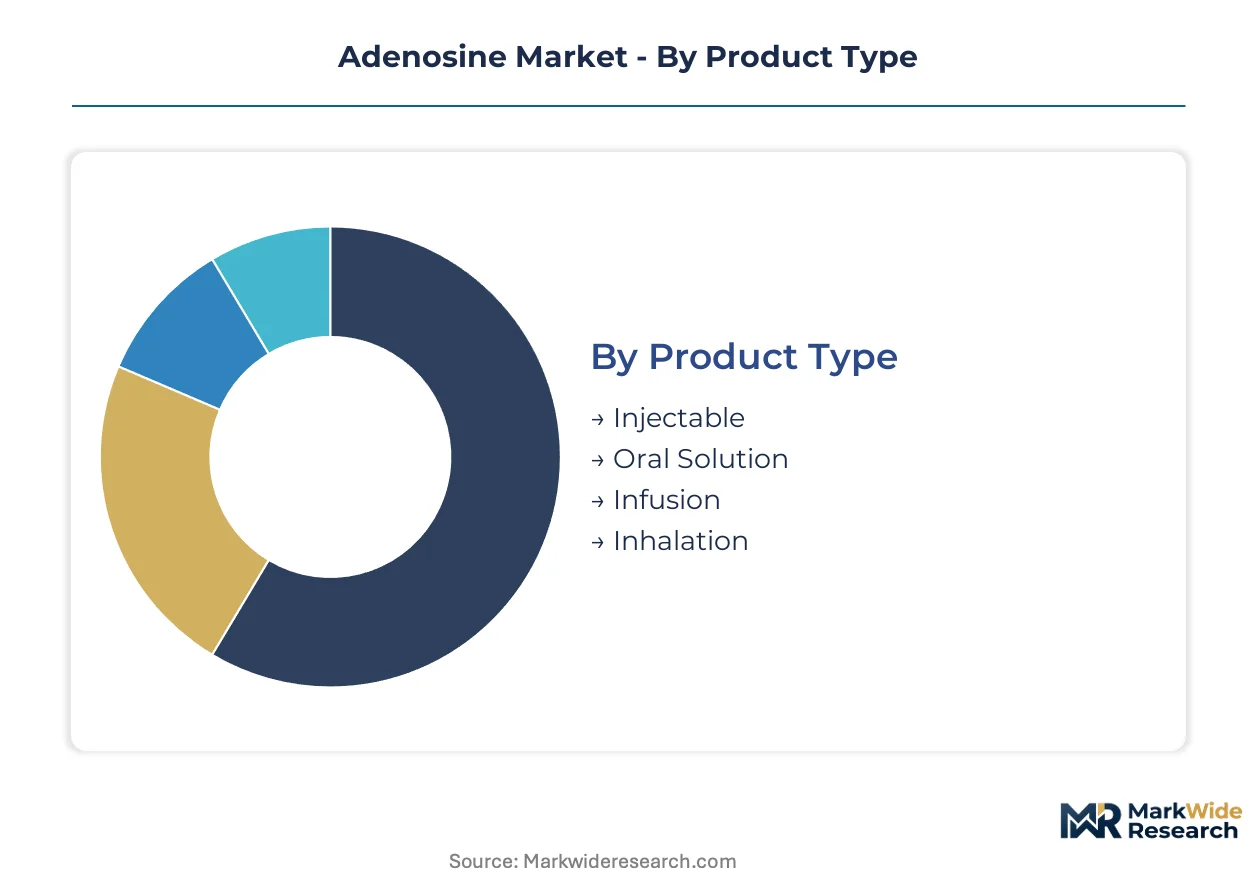
Adenosine's negligible oral bioavailability and ultra-short half-life create sharp divides between viable commercial formats and stranded development categories. Segmentation reveals where formulation chemistry, procedural economics, and regulatory pathways concentrate margin capture.
Product Type:
Hospital buyers differentiate primarily by administration speed and cold-chain burden in catheterization workflows.
- Injectable:Lyophilized or liquid formulations for IV push delivery dominate procurement volumes. Cleveland Clinic and Texas Medical Center specify prefilled syringes with barcoded weight-based dosing to reduce medication errors during STEMI surge events.
- Infusion:Continuous pump-compatible presentations serve stress testing protocols in outpatient cardiology suites. Demand concentrates in United States ambulatory surgical centers where 6-minute half-life infusions replace exercise tolerance tests for mobility-limited patients.
- Oral Solution:Bioavailability below 1% renders this format clinically nonviable for systemic antiarrhythmic effect. Compounding pharmacies in Germany and Switzerland stock limited quantities for veterinary and experimental pharmacology applications only.
- Inhalation:Nebulized delivery remains investigational for pulmonary hypertension modulation. Academic medical centers in Japan maintain small procurement volumes for adenosine receptor subtype studies.
Injectable formats lead volumes today; infusion presentations are gaining share fastest in outpatient migration.
Application:
Procedure reimbursement codes and electrophysiology lab throughput determine purchasing priority across clinical indications.
- Cardiac Arrhythmia:Supraventricular tachycardia conversion generates the deepest margin pools. United States catheterization labs administer adenosine in over 85% of SVT emergency presentations, with Medicare reimbursement sustaining high-volume purchasing.
- Stress Testing:Pharmacologic myocardial perfusion imaging absorbs growing volumes as aging populations limit exercise tolerance. German cardiology practices prefer adenosine over regadenoson for cost-sensitive statutory insurance contracts.
- Antidote for Toxicity:Dipyridamole and carbamazepine overdose reversal represents a narrow hospital pharmacy stocking category. Poison control centers in France and Australia maintain emergency reserves with 24-hour rotation requirements.
- Heart Surgery:Cardioplegia adjunct use in bypass procedures commands premium pricing for cold-blood myocardial preservation. Cleveland Clinic and Mayo Clinic specify high-purity endotoxin-tested lots for open-heart protocols.
Cardiac arrhythmia applications anchor revenue today; stress testing is climbing the fastest as outpatient cardiology expands.
End User:
Procurement scale and formulary control separate institutional buyers from fragmented clinical and research demand.
- Hospitals:Integrated delivery networks with electrophysiology fellowship programs consolidate annual purchasing exceeding 10,000 units. United States academic medical centers negotiate 36-month sole-source agreements with emergency stockholding clauses.
- Research Laboratories:Adenosine receptor pharmacology studies in inflammation and neurodegeneration drive compound procurement. University of Tokyo and ETH Zurich maintain standing orders for high-specific-activity radiolabeled preparations.
- Clinics:Independent cardiology practices purchase single-dose vials through group purchasing organizations. German MVZ networks achieve modest volume discounts through regional pharmacy cooperatives.
- Pharmaceutical Companies:Contract manufacturers and generic developers source API for formulation development. South Korean fermentation facilities supply multi-kilogram batches under FDA Type II drug master files.
Hospitals dominate procurement volumes today; research laboratories show the steepest expansion trajectory for specialty-grade material.
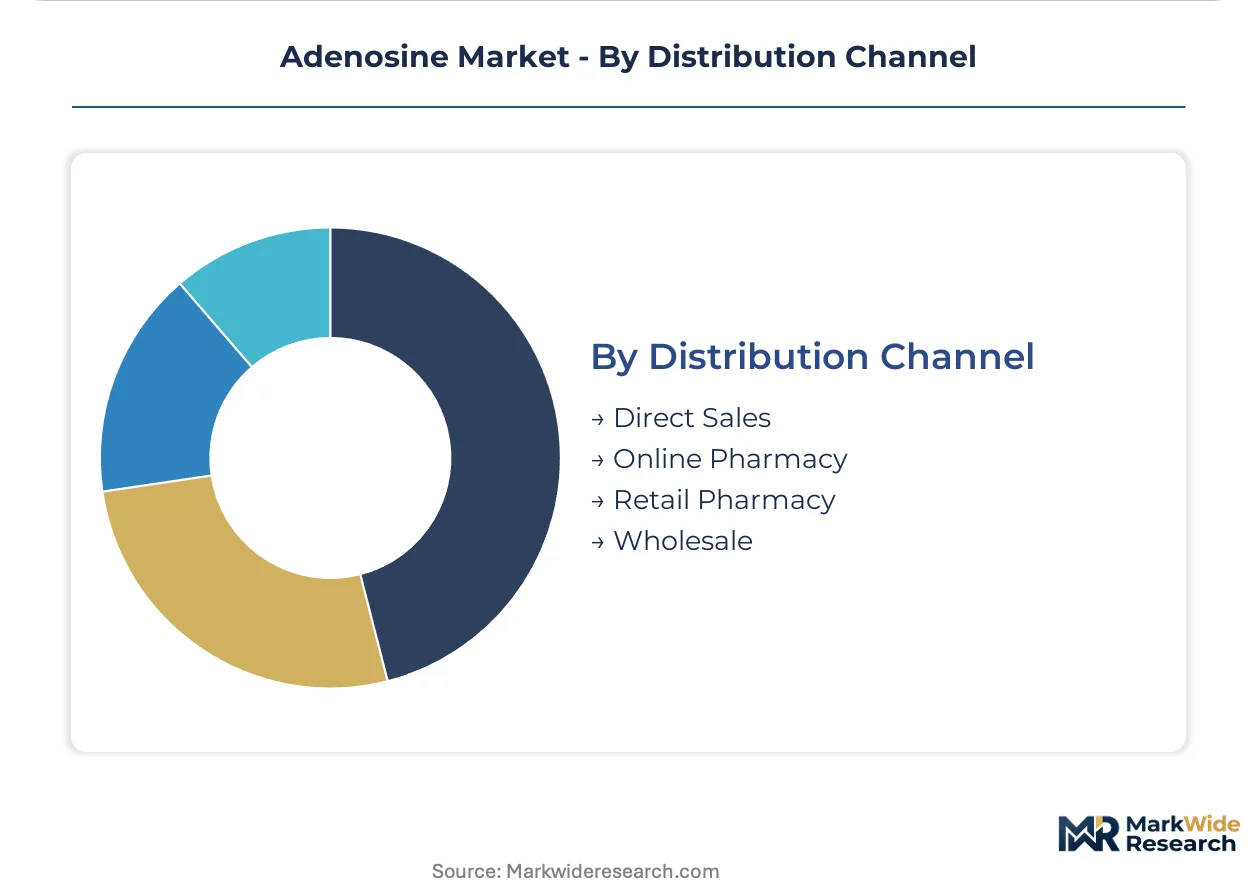
Distribution Channel:
Cold-chain integrity requirements and emergency availability clauses shape channel selection for parenteral antiarrhythmics.
- Direct Sales:Manufacturer-to-hospital contracts eliminate intermediary margin for high-volume catheterization lab accounts. Pfizer and Astellas maintain dedicated field inventory at United States academic medical centers.
- Wholesale:Cardinal Health and McKesson distribute to community hospitals with 48-hour replenishment guarantees. This channel absorbs price compression from generic multi-dose vial competition.
- Retail Pharmacy:Limited to emergency prescription fills for take-home stress testing protocols. CVS and Walgreens stock negligible volumes given institutional administration dominance.
- Online Pharmacy:Research-grade material moves through specialized biochemical suppliers. Sigma-Aldrich and Tocris serve academic laboratories with certificate-of-analysis documentation.
Direct sales capture the largest volume share today; wholesale channels are expanding most quickly in community hospital consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable adenosine production scaled through Japanese fermentation expertise in the 1980s before US catheterization lab demand reshaped formulation standards. European chemical synthesis routes later diversified supply geography. Today procurement concentrates where electrophysiology infrastructure and regulatory stringency intersect.
United States
Medicare reimbursement for SVT conversion procedures sustains hospital purchasing volumes exceeding 10,000 units annually at major academic centers. FDA cGMP inspections for parenteral antiarrhythmics have tightened sterility documentation requirements since 2023. The Texas Medical Center in Houston anchors North American demand through sole-source agreements with emergency stockholding clauses.
Germany
Statutory insurance contracts favor adenosine over regadenoson for pharmacologic stress testing in aging populations with limited exercise tolerance. EMA Annex 1 sterile manufacturing guidelines mandate barrier isolation for Grade A operations effective August 2023. The Rhine-Ruhr metropolitan region concentrates catheterization lab procurement through integrated MVZ network contracts.
Japan
Academic pharmacology departments at University of Tokyo and Kyoto University drive specialty-grade compound demand for adenosine receptor research. PMDA quality standards for injectable nucleosides enforce endotoxin limits below 0.5 EU per milligram. The Kansai region around Osaka hosts fermentation capacity serving domestic hospital tenders and API export contracts.
India
WHO Essential Medicines status unlocks centralized procurement at state medical services corporations with multi-year supply agreements. CDSCO manufacturing license requirements for sterile injectables filter subscale domestic producers. Maharashtra and Gujarat house fermentation facilities supplying multi-kilogram API batches under FDA Type II drug master files.
Switzerland
ETH Zurich and University Hospital Basel maintain standing orders for high-specific-activity radiolabeled adenosine preparations. Swissmedic inspection protocols for parenteral products align with EMA standards while permitting faster batch release timelines. The Basel-Liechtenstein corridor concentrates contract manufacturing for European hospital tenders.
Adenosine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterility assurance and fill-finish capability tiers. The supplier base compresses toward six qualified facilities globally as isolator technology upgrades absorb capital exceeding $40 million per line. Three archetypes dominate: originator pharmaceutical companies with depreciated sterile infrastructure, contract manufacturers with single-use bioreactor capabilities, and cost-positioned generic houses competing on multi-dose vial tenders. Competitive moves concentrate on prefilled syringe conversion partnerships and direct-to-hospital inventory placement.
Within the originator tier, Pfizer and Astellas Pharma occupy positions shaped by catheterization lab relationships and regional regulatory approvals. Teva Pharmaceuticals exemplifies the cost-competitive archetype through multi-dose vial positioning. These three anchors illustrate how manufacturing scale, geographic reach, and formulation format specialization stratify market access.
| Leading Market Players |
|---|
| Astellas Pharma |
| Sanofi |
| Pfizer |
| Celon Laboratories |
| Torrent Laboratories |
| Sun Pharmaceuticals |
| Novartis |
| Sagent Pharmaceuticals |
| Teva Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Dichloromethane solvent costs cascade from chemical phosphorylation facilities through three distinct pricing tiers for hospital buyers, with EPA discharge permitting delays in the United States amplifying cost volatility for generic multi-dose vials while originator prefilled syringes absorb premium positioning through sterility assurance investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-produced prefilled syringes from conventional multi-dose vials and commodity API tenders. Price differentiation hinges on endotoxin certification grade and volume commitment scale, with catheterization lab sole-source agreements commanding the highest premiums. Cost compression in the generic multi-dose tier is intensifying because Indian state tender consolidation favors lowest-unit-cost suppliers. Research laboratories exhibit the least price sensitivity due to radiolabeled specificity requirements.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Irish fermentation capacity for biotechnological production routes. Raw material flows draw from Chinese chemical intermediates, German pharmaceutical-grade solvents, and Japanese adenine base stocks. Tariff exposure on dichloromethane imports into the United States creates formulation cost uncertainty for domestic fill-finish contractors. Distribution runs through direct manufacturer-to-hospital contracts for high-volume accounts and wholesale channels for community hospital replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adenosine market functions as a regulatory compounder where EMA Annex 1 sterile manufacturing guidelines and FDA cGMP enforcement tighten supplier qualification barriers, concentrating margin capture among isolator-capable manufacturers.
For Market Incumbents: Cement catheterization lab relationships through 24-hour emergency stockholding clauses and prefilled syringe conversion partnerships. Threats from cost-positioned generic houses in Indian tenders demand backward integration into fermentation capacity to secure API supply. Isolator technology certification investment represents the critical defensive lever for European hospital access.
For New Entrants and Emerging Players: Launch via research-grade specialty compound distribution to academic pharmacology departments in Japan and Switzerland. The most penetrable segment lies in stability-enhanced lyophilized presentations for rural hospitals with limited cold-chain infrastructure in Australia and Canada. A go-to-market angle anchored in barrier isolation compliance for EMA hospital tenders unlocks qualified supplier status faster than commodity vial competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where subscale contract manufacturers face $40 million isolator upgrade requirements without depreciated infrastructure to absorb capital deployment. Acquisition targets with single-use bioreactor capabilities and existing FDA Type II drug master files offer the strongest five-to-ten year viability framing. The signal to watch is endotoxin testing assay capacity constraints at contract laboratories extending batch release timelines and compressing effective supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Upgrade | EMA Annex 1 compliance opens EU hospital tender access for qualified manufacturers. |
| Prefilled Syringe Conversion | Cleveland Clinic and Texas Medical Center sole-source agreements reduce dosing error liability. |
| Fermentation Capacity Expansion | South Korean facilities anchor biotechnological production for API export contracts. |
| Direct Hospital Inventory Placement | Pfizer field stockholding at academic medical centers secures STEMI surge availability. |
| Radiolabeled Compound Development | ETH Zurich and University of Tokyo partnerships capture research laboratory premium pricing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, catheterization lab directors, regulatory affairs leads at sterile fill-finish contractors, and GPO contracts specialists with secondary validation from FDA cGMP inspection records, EMA submission databases, hospital formulary listings, and WHO Essential Medicines procurement reports. Bottom-up volume modeling and top-down market sizing triangulated across these inputs to anchor segment-level estimates.
Segment-weighting approaches distributed value and volume across injectable format, cardiac arrhythmia versus stress testing application, hospital versus research laboratory end-use, and direct sales versus wholesale channel dimensions. CAGRs were derived from procedure volume trajectories in electrophysiology labs, reimbursement code stability, and regulatory enforcement intensity across the analysis window. Forecast inputs incorporated catheterization lab expansion pipelines, isolator technology adoption curves, and fermentation capacity utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA solvent discharge restrictions or PMDA endotoxin limit revisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market