
 Global Liposome Drug Delivery Market | 2026-2036
Global Liposome Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liposome Drug Delivery Market Foresight
Asset-light contract manufacturing partnerships is reconfiguring competitive entry in liposome drug delivery, lowering capital barriers for mid-scale developers. Gilead Sciences leverages captive manufacturing infrastructure for complex liposomal formulations. Pacira BioSciences specializes in sustained-release depot technologies that extend hospital formulary access. Johnson & Johnson anchors its position through integrated R&D spanning active targeting to commercial scale-up.
Liposome drug delivery systems are phospholipid bilayer vesicles engineered to encapsulate hydrophilic and hydrophobic therapeutic agents, with particle sizes typically ranging from 50 to 450 nanometers for optimal vascular permeability and cellular uptake. These structures primarily serve to enhance drug solubility, prolong circulation half-life, and enable targeted deposition at disease sites while reducing systemic toxicity. Liposomal injections currently occupy the dominant revenue position due to established intravenous administration in oncology protocols, while PEGylation technology leads growth as stealth coatings reduce reticuloendothelial clearance and enable repeated dosing cycles. Active targeting approaches differentiate emerging pipelines through ligand-directed delivery, though passive targeting retains broader clinical validation.
FDA accelerated approval frameworks and EMA nanomedicine reflection papers jointly shape development pathways, with both agencies requiring demonstration of bioequivalence for generic liposomal products that complex manufacturing makes difficult to replicate. ISO 10993 biocompatibility standards and USP lipid excipient monographs further constrain supplier qualification and raw material sourcing. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on liposomal characterization methods, as divergent analytical requirements threaten to fragment development strategies and duplicate clinical investments.
Market Dynamics
FDA accelerated approval pathways for nanomedicine products are compressing development timelines and reshaping capital allocation across the liposome drug delivery sector. This regulatory velocity is forcing manufacturers to front-load manufacturing scale-up investments before Phase III completion.
Growth Catalysts
- PEGylation technology maturation:Stealth coatings reduce reticuloendothelial clearance and enable repeated dosing cycles in oncology protocols. German university hospitals are expanding liposomal chemotherapy programs.
- Japan's reimbursement frameworks:Targeted drug delivery systems receive preferential coverage under METI-aligned health technology assessment pathways. Japanese payers favor reduced systemic toxicity profiles.
- EMA nanomedicine reflection papers:Regulatory clarity on characterization methods reduces clinical investment duplication across European development programs.
Market Restraints
- Phospholipid supply concentration:High-purity lipid excipient production clusters in select European and North American suppliers, creating raw material vulnerability.
- Bioequivalence demonstration requirements:FDA and EMA divergent analytical standards for generic liposomal products fragment development strategies.
- Complex manufacturing scalability:Particle size control and batch-to-batch consistency require specialized equipment that limits contract manufacturing flexibility.
Strategic Opportunities
- Active targeting ligand development:Antibody-conjugated and peptide-directed liposomes open precision oncology applications beyond passive EPR effects.
- Asset-light contract manufacturing partnerships:Mid-scale developers bypass capital barriers through specialized CDMO relationships in the United States and Germany.
- ISO 10993 biocompatibility standard harmonization:Converging international testing protocols reduce redundant qualification costs for multi-regional filings.
Industry Challenges
- Specialized formulation scientist scarcity:Phospholipid chemistry and nanoscale characterization expertise concentrates at established biopharma hubs.
- USP lipid excipient monograph compliance:Supplier qualification timelines extend raw material sourcing cycles and compress development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liposome Drug Delivery Market |
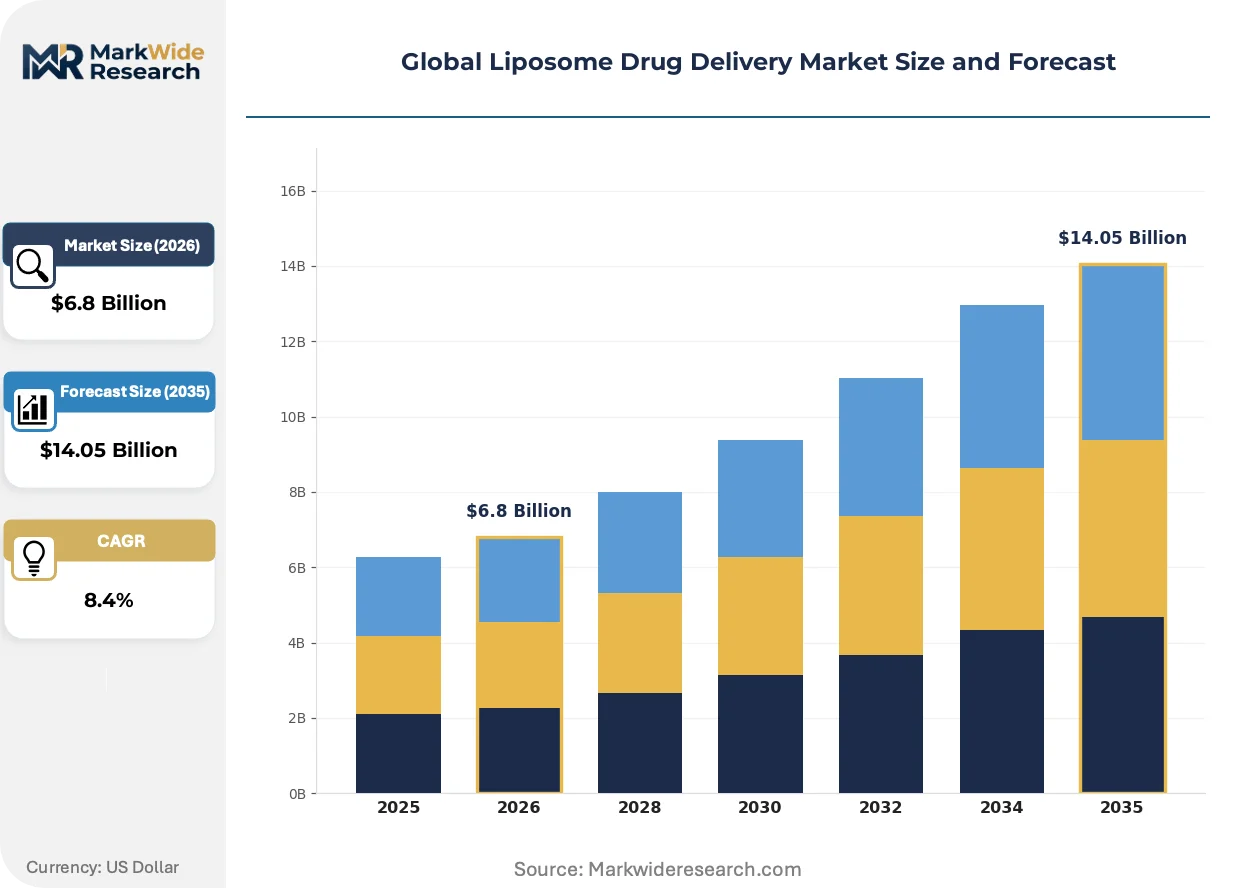
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomal Injections, Liposomal Ointments, Liposomal Capsules, Liposomal Tablets, Liposomal Suspensions Therapy Area: Oncology, Infectious Diseases, Vaccination, Gene Therapy, Dermatology End User: Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms, Clinical Research Centers Delivery Technology: Passive Targeting, Active Targeting, Triggered Release, PEGylation, Lipid-Based Nanocarriers |
| Companies Covered | Gilead Sciences, Inc., Pacira BioSciences, Inc., Luye Pharma Group, Johnson & Johnson, Ipsen Pharma, Spectrum Pharmaceuticals, Inc., Janssen Pharmaceuticals, Inc., Sun Pharmaceutical Industries Ltd., Celsion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liposome Drug Delivery Market Shifts & Advancements
Active targeting approaches are differentiating emerging pipelines while passive targeting retains broader clinical validation. Manufacturing innovation and regulatory convergence are simultaneously compressing development risk and expanding addressable therapeutic areas.
Multifunctional liposome architectures incorporating both therapeutic payloads and diagnostic imaging agents are migrating from preclinical oncology models into early-phase human trials. Academic medical centers in the United States and Germany are piloting theranostic protocols that combine drug delivery with real-time treatment monitoring. This convergence is collapsing the traditional separation between pharmaceutical and medical device development pathways.
REACH regulatory updates in Europe are tightening scrutiny of lipid excipient impurity profiles and supplier environmental compliance. Manufacturers must now document full supply chain sustainability credentials alongside traditional quality attributes. German and Swiss suppliers are investing in green chemistry process modifications to maintain EMA qualification status.
Hospital formulary committees are consolidating purchasing decisions around sustained-release depot technologies that reduce nursing administration burden. United States oncology departments favor single-infusion protocols that minimize inpatient bed utilization. Japanese payers are revising reimbursement categories to reward reduced hospitalization frequency in liposomal chemotherapy administration.
Global Liposome Drug Delivery Market Segmentation
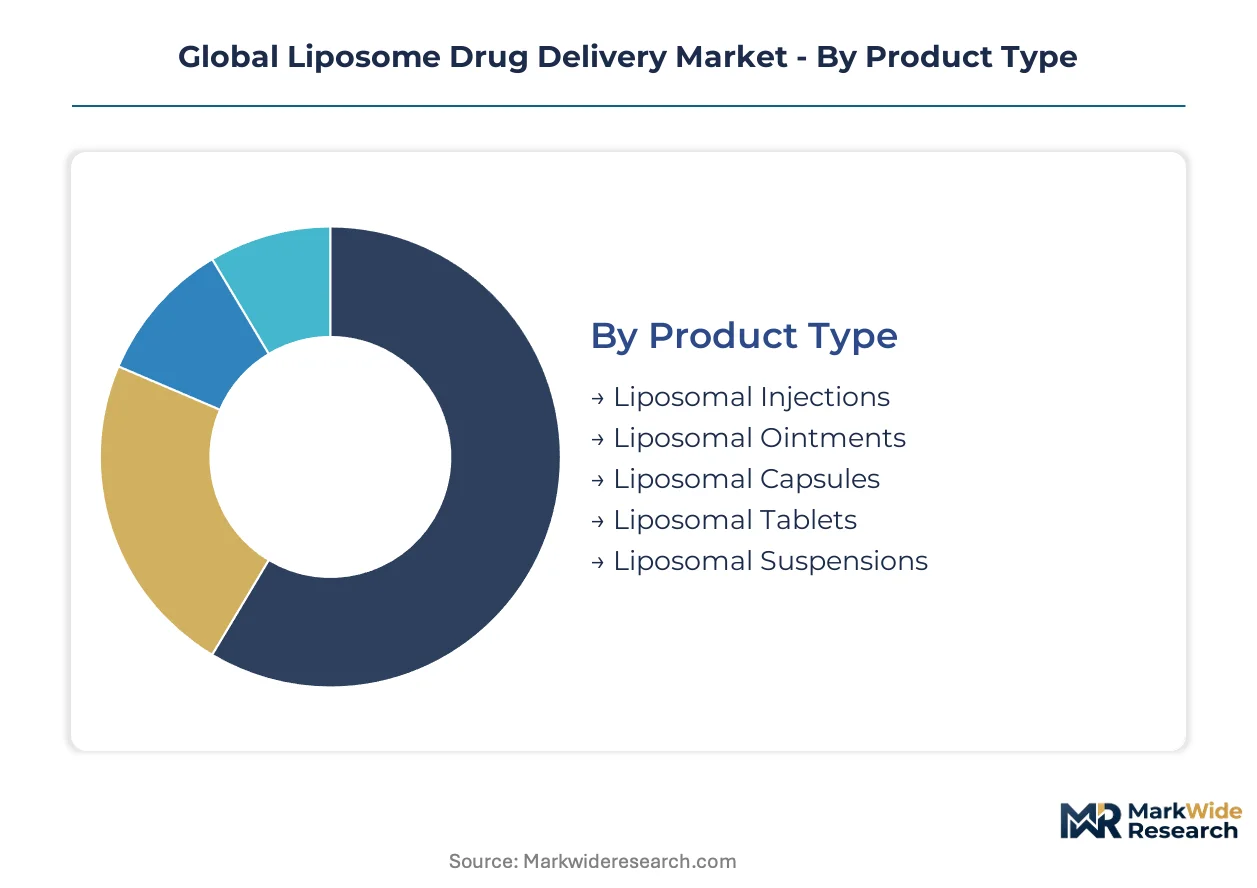
Segmentation in liposome drug delivery reveals how formulation complexity, therapeutic application, and manufacturing sophistication intersect to create distinct competitive arenas. Each dimension carries different regulatory burdens, capital requirements, and margin structures that determine viable entry strategies for developers and contract manufacturers.
Product Type:
Cost tier differentiation across liposome formulations reflects manufacturing complexity, sterility assurance requirements, and distribution infrastructure needs.
- Liposomal Injections:Aqueous core phospholipid vesicles administered intravenously require aseptic processing and cold chain logistics. United States oncology departments concentrate demand around single-infusion chemotherapy protocols that minimize hospital bed utilization.
- Liposomal Ointments:Semi-solid lipid matrices enable topical drug deposition across dermal layers with reduced systemic absorption. German dermatology clinics favor these formulations for localized corticosteroid delivery where skin penetration depth determines therapeutic index.
- Liposomal Capsules:Oral dosage forms encapsulating hydrophobic actives within phospholipid bilayers for lymphatic absorption.
- Liposomal Tablets:Compressed solid formulations combining liposomal complexes with excipient matrices for modified release.
- Liposomal Suspensions:Colloidal dispersions requiring particle size stability across shelf life for consistent dosing.
Liposomal injections hold installed capacity. Liposomal ointments are rotating up the share rankings.
Therapy Area:
Application-specific development pathways in liposome drug delivery map directly to unmet medical need severity, reimbursement generosity, and clinical validation depth.
- Oncology:Anthracycline and platinum-based chemotherapeutics encapsulated in PEGylated liposomes reduce cardiotoxicity and nephrotoxicity profiles. Japanese university hospitals are expanding protocols under METI-aligned reimbursement pathways that reward reduced systemic toxicity.
- Infectious Diseases:Amphotericin B and antiviral liposomal formulations improve therapeutic indices for immunocompromised patient populations. United States hospital formulary committees prioritize these products for fungal prophylaxis in transplant units.
- Vaccination:Liposomal adjuvant systems enhance antigen presentation through depot formation and dendritic cell targeting.
- Gene Therapy:Cationic liposome complexes facilitate nucleic acid transfection across cellular membranes for rare disease applications.
- Dermatology:Topical liposomal carriers improve bioavailability of anti-inflammatory and antimicrobial actives across stratum corneum barriers.
Oncology commands the steepest expansion trajectory. Infectious diseases applications are climbing the fastest among established therapy areas.
End User:
Customer type segmentation captures how liposome development capabilities distribute across organizational scales, risk appetites, and vertical integration preferences.
- Pharmaceutical Companies:Integrated developers with captive manufacturing infrastructure pursue complex multi-ligand formulations requiring specialized phospholipid chemistry expertise. These organizations concentrate in established biopharma hubs across the United States, Germany, and Japan.
- Contract Research Organizations:Asset-light service providers enable mid-scale developers to bypass capital barriers through specialized formulation and analytical capabilities. German CDMOs are expanding liposome manufacturing suites to capture EMA-aligned development programs.
- Biotechnology Firms:Venture-backed innovators leveraging platform liposome technologies for novel therapeutic modalities.
- Clinical Research Centers:Academic medical centers piloting theranostic liposome protocols combining drug delivery with diagnostic imaging agents.
Pharmaceutical companies retain the largest committed capacity. Contract research organizations are gaining share fastest among outsourced development partners.
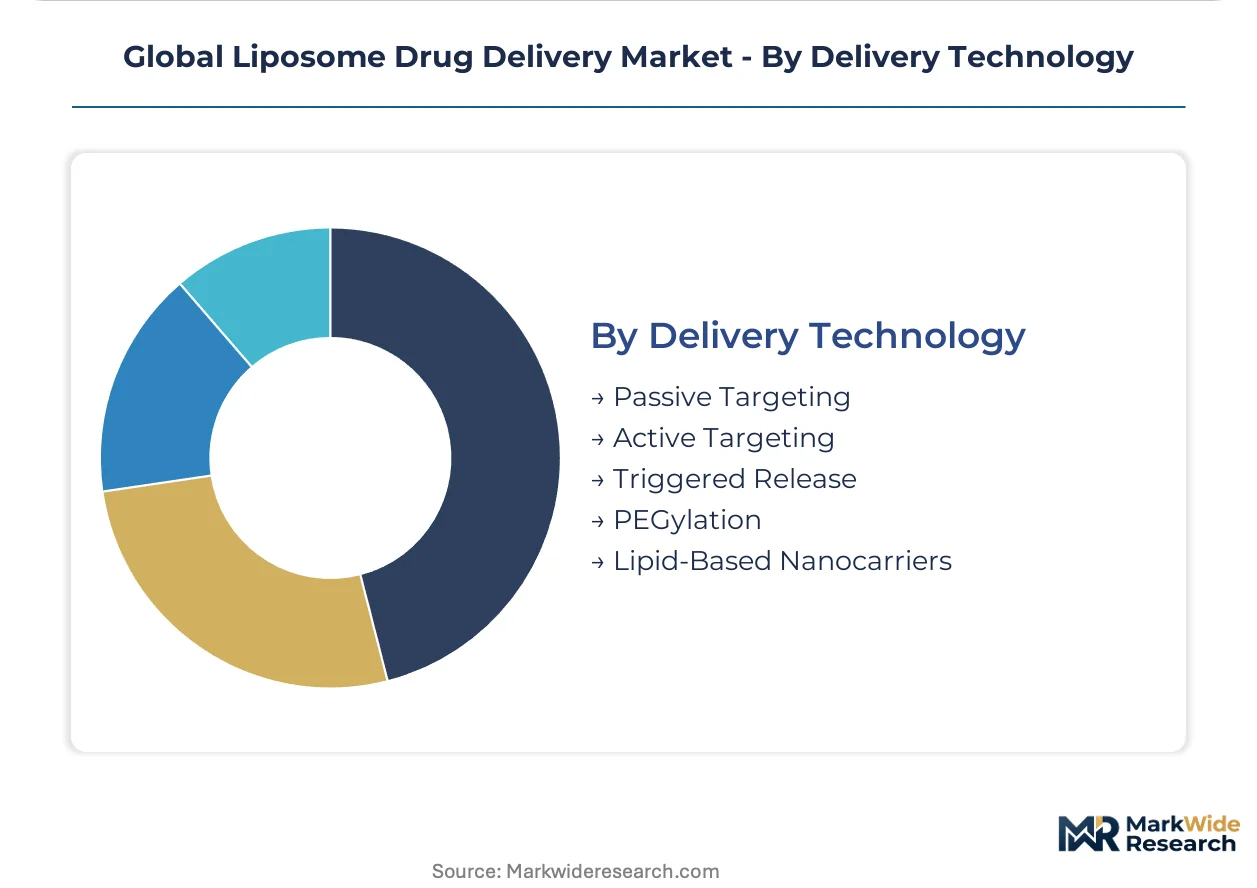
Delivery Technology:
Maturity gradients across targeting mechanisms reflect the gap between preclinical innovation and clinical validation in liposome engineering.
- Passive Targeting:Exploitation of enhanced permeability and retention effects in tumor vasculature relies on nanoscale particle distribution without surface modification. This approach retains the broadest clinical validation across FDA-approved liposomal products.
- PEGylation:Polyethylene glycol surface coatings create stealth properties that evade reticuloendothelial clearance and enable repeated dosing cycles. United States and Japanese oncology protocols increasingly specify PEGylated formulations for maintenance therapy regimens.
- Active Targeting:Antibody-conjugated and peptide-directed liposomes enable ligand-receptor mediated cellular uptake beyond passive accumulation.
- Triggered Release:pH-sensitive, temperature-responsive, or enzyme-activated liposome architectures enable spatiotemporal control of drug liberation.
- Lipid-Based Nanocarriers:Solid lipid nanoparticles and nanostructured lipid carriers offering alternative stability profiles to conventional phospholipid vesicles.
Passive targeting holds the deepest installed base. PEGylation technology is rotating up the share rankings as stealth coating patents expire and biosimilar competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for nanomedicine products compress development timelines in the United States. German EMA-aligned reimbursement frameworks reward targeted drug delivery systems. Japanese METI policies favor reduced systemic toxicity profiles in oncology protocols.
United States
University hospital oncology departments expand liposomal chemotherapy protocols under single-infusion regimens that minimize inpatient bed utilization. FDA nanomedicine guidance requires front-loaded manufacturing scale-up investments before Phase III completion. The Greater Boston biopharma cluster concentrates formulation scientists with phospholipid chemistry expertise.
Germany
EMA nanomedicine reflection papers reduce clinical investment duplication across European development programs. REACH regulatory updates tighten scrutiny of lipid excipient impurity profiles and supplier environmental compliance. Swiss and German suppliers invest in green chemistry process modifications to maintain qualification status.
Japan
METI-aligned health technology assessment pathways deliver preferential reimbursement coverage for targeted drug delivery systems. PMDA reviews compress timelines for liposomal products demonstrating reduced systemic toxicity. The Kanto region around Tokyo anchors pharmaceutical manufacturing infrastructure for complex formulations.
China
NMPA reforms accelerate approval timelines for innovative nanomedicine products meeting bioequivalence standards. Domestic manufacturers expand liposomal manufacturing capacity to capture oncology and infectious disease applications. The Yangtze River Delta biopharma corridor concentrates CDMO investments in specialized formulation suites.
India
CDSCO streamlined pathways for complex generic liposomal products attract contract manufacturing investments from multinational developers. Domestic pharmaceutical firms leverage cost advantages in high-purity lipid excipient sourcing. The Hyderabad-Visakhapatnam corridor expands sterile injectable capacity for liposomal formulations.
Global Liposome Drug Delivery Market Competitive Landscape
On the supply side, the industry is consolidating around integrated biopharma conglomerates with captive manufacturing infrastructure and specialized CDMOs serving mid-scale developers. Three archetypes dominate: vertically integrated innovators controlling end-to-end formulation, asset-light platform specialists leveraging contract partnerships, and emerging-market cost leaders scaling complex generic production. Dominant competitive moves include strategic CDMO partnerships that bypass capital barriers and M&A activity targeting phospholipid chemistry expertise.
Within the integrated innovator tier, Gilead Sciences and Johnson & Johnson exemplify archetypes with captive manufacturing infrastructure for complex liposomal formulations. Pacira BioSciences occupies a specialist position in sustained-release depot technologies. These three entities represent contrasting strategic postures: the diversified conglomerate, the focused platform company, and the technology-driven delivery specialist.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Pacira BioSciences, Inc. |
| Luye Pharma Group |
| Johnson & Johnson |
| Ipsen Pharma |
| Spectrum Pharmaceuticals, Inc. |
| Janssen Pharmaceuticals, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Celsion Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in German and Swiss high-purity phospholipid manufacturing is tightening supplier pricing power while compressing development timelines for mid-scale liposome developers. This utilization squeeze forces buyers into longer-term offtake commitments and shifts contract manufacturing negotiations toward capacity reservation fees.
Pricing Analysis
Certification level creates the primary spread across liposome formulations, with FDA-grade and EMA-aligned GMP batches commanding substantial premia over research-use material. Three-tier pricing structure across premium, standard, and economy levels reflects sterility assurance depth, particle size control precision, and cold chain infrastructure investment. Cost compression in standard-grade liposomal injections is intensifying because biosimilar competition and expiring PEGylation patents expand supplier pools. Hospital formulary committees exhibit highest price sensitivity for maintenance therapy regimens, while gene therapy developers show lowest sensitivity due to orphan disease pricing latitude.
Supply Chain Analysis
Contract manufacturing concentration rests with German CDMOs expanding liposome manufacturing suites and United States specialists serving FDA-aligned development programs. High-purity phospholipid production draws from Germany, Switzerland, and select North American suppliers, with hydrogenated soy phosphatidylcholine and synthetic distearoylphosphatidylcholine anchoring raw material dependencies. Single-source vulnerability in lipid excipient qualification timelines threatens batch release schedules. Distribution runs through cold chain logistics networks serving hospital pharmacy and specialty distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation scientist scarcity with phospholipid chemistry and nanoscale characterization expertise concentrates competitive advantage at established biopharma hubs. This capability gap shapes entry economics and partnership requirements across the value chain.
For Market Incumbents: Pre-empt biosimilar encroachment by locking multi-year phospholipid supply agreements before patent cliffs accelerate. Deepen backward integration into high-purity lipid excipient production or captive manufacturing infrastructure to defend margin position against CDMO pricing power. FDA-EMA regulatory convergence on characterization methods presents consolidation leverage through unified analytical platform investments. For New Entrants and Emerging Players: Pursue asset-light contract manufacturing partnerships in the United States and Germany to bypass capital barriers in sterile injectable capacity. Theranostic liposome applications combining drug delivery with diagnostic imaging agents represent the most penetrable white space, with academic medical center pilot programs offering validation pathways. Licensing active targeting ligand platforms from university technology transfer offices accelerates pipeline positioning without internal R&D scale. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across PEGylation and active targeting segments as manufacturing scale-up investments front-load before Phase III completion. Platform liposome technology specialists with ligand-directed delivery capabilities offer strongest long-term viability within a five-to-ten year window. Monitor FDA accelerated approval pathway utilization rates as inflection indicator for sector capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up Investment | Front-loaded capital deployment before Phase III completion compresses FDA approval timelines. |
| Active Targeting Ligand Licensing | Antibody-conjugated and peptide-directed platforms differentiate pipelines beyond passive EPR effects. |
| CDMO Partnership Expansion | Asset-light relationships in Germany and the United States bypass sterile injectable capacity barriers. |
| Regulatory Convergence Positioning | Unified FDA-EMA analytical platforms reduce duplicate clinical investment across filing jurisdictions. |
| Theranostic Protocol Development | Academic medical center pilots in the United States and Germany collapse pharmaceutical-device pathway separation. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and USP lipid excipient monographs preceded structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and contract manufacturing officers. Secondary validation drew from ISO 10993 biocompatibility standards, REACH regulatory updates, and Japanese METI health technology assessment pathways. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Assumptions held fixed include FDA accelerated approval pathway continuity, EMA nanomedicine reflection paper stability, and reimbursement framework generosity in the United States, Germany, and Japan. Variables tested across the analysis window encompassed therapy area expansion rates, delivery technology adoption curves, and end-user outsourcing propensity. CAGRs derived from segment-level growth trajectory modeling incorporating patient population epidemiology, treatment protocol penetration, and pricing elasticity by certification tier.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement austerity, phospholipid commodity pricing, or cross-border regulatory harmonization would shift the trajectory. Forecasts reflect documented assumptions regarding clinical trial success rates and manufacturing scale-up feasibility. Quarterly review of FDA nanomedicine guidance updates, EMA qualification status changes, and CDMO capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market