
 Global Histone Deacetylase Inhibitors Market | 2026-2036
Global Histone Deacetylase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Histone Deacetylase Inhibitors Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is realigning manufacturing standards for active pharmaceutical ingredients across European supply chains. Merck & Co. leverages its integrated chemical manufacturing footprint to secure precursor supply for hydroxamic acid derivatives. Novartis AG anchors its position through sustained R&D investment in combination epigenetic therapies. Bristol-Myers Squibb Company differentiates via its established oncology commercial infrastructure across North American and European hospital networks.
Histone deacetylase inhibitors are a class of epigenetic modulating compounds that block the enzymatic removal of acetyl groups from lysine residues on histone proteins, thereby altering chromatin structure and gene expression patterns in cancerous and other diseased cells. These agents typically function through zinc-dependent catalytic mechanisms at the enzyme active site, with hydroxamic acid derivatives exhibiting picomolar binding affinity. The therapy area dimension shows oncology commanding the primary revenue pool as hematologic malignancies drive first-line adoption, while rare disorders represents the fastest-expanding category as regulators prioritize epigenetic mechanisms for diseases with limited therapeutic alternatives. Oral delivery mode dominates prescription volumes due to patient compliance advantages in maintenance settings, though intravenous formulations sustain premium pricing in acute care environments.
The FDA's Breakthrough Therapy Designation and EMA's Priority Medicines scheme collectively compress development timelines and shape clinical trial investment priorities for developers targeting hematologic cancers. Japan's PMDA operates an accelerated approval pathway for orphan oncology indications that reduces review periods for novel epigenetic agents. China's NMPA has expanded its conditional approval framework to include histone modification therapies, opening access for domestic manufacturers such as Shenzhen Chipscreen Biosciences. Stakeholders must monitor evolving pharmacovigilance requirements for combination regimens as regulatory agencies tighten post-market surveillance for immune-related adverse events.
Market Dynamics
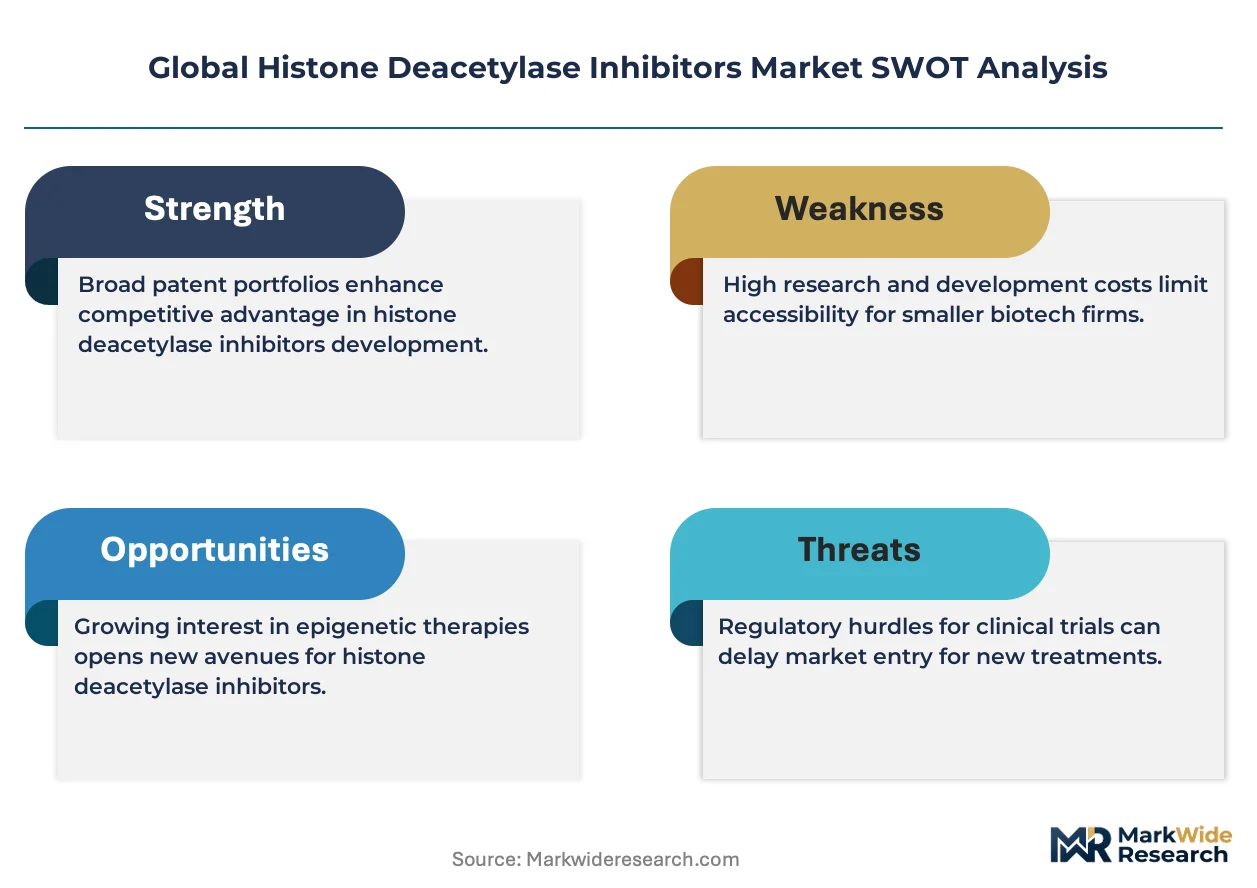
The FDA's Breakthrough Therapy Designation and EMA's Priority Medicines scheme are compressing clinical trial timelines and redirecting capital toward hematologic malignancy programs, while manufacturing investments cluster around hydroxamic acid precursor supply.
Growth Catalysts
- Orphan Drug Designation:The FDA's program accelerates development timelines for rare cancer indications, reducing regulatory review periods and enabling faster patient access to novel epigenetic agents.
- Combination therapy protocols:Oncology departments at academic medical centers are expanding HDAC inhibitor protocols in combination regimens, driving protocol adoption and maintenance therapy volumes.
- Japan's PMDA accelerated pathway:The regulator's orphan oncology framework reduces review periods for novel epigenetic agents, opening commercial access earlier in product lifecycles.
Market Restraints
- Hydroxamic acid precursor concentration:Active pharmaceutical ingredient supply chains concentrate precursor manufacturing in limited chemical manufacturing hubs, creating single-source vulnerability.
- Immune-related adverse event surveillance:Regulatory agencies are tightening post-market pharmacovigilance requirements for combination regimens, extending compliance costs and label restriction risk.
- Small-molecule substitution pressure:Emerging targeted protein degradation modalities and other epigenetic mechanisms present therapeutic alternatives in hematologic indications.
Strategic Opportunities
- China's conditional approval expansion:The NMPA framework now explicitly includes histone modification therapies, enabling domestic manufacturers to commercialize before full trial completion.
- Rare disorders category:Regulators are prioritizing epigenetic mechanisms for diseases with limited therapeutic alternatives, creating fastest-expanding revenue pools outside oncology.
- Intravenous-to-oral switching:Maintenance therapy settings favor oral delivery modes for compliance advantages, enabling portfolio expansion beyond acute care formulations.
Industry Challenges
- Combination regimen integration complexity:Immune-related adverse event profiling requires specialized pharmacovigilance infrastructure that many developers lack in-house.
- Zinc-dependent catalytic mechanism expertise:Picomolar binding affinity optimization demands rare structural biology and medicinal chemistry talent concentrated at limited research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Histone Deacetylase Inhibitors Market |
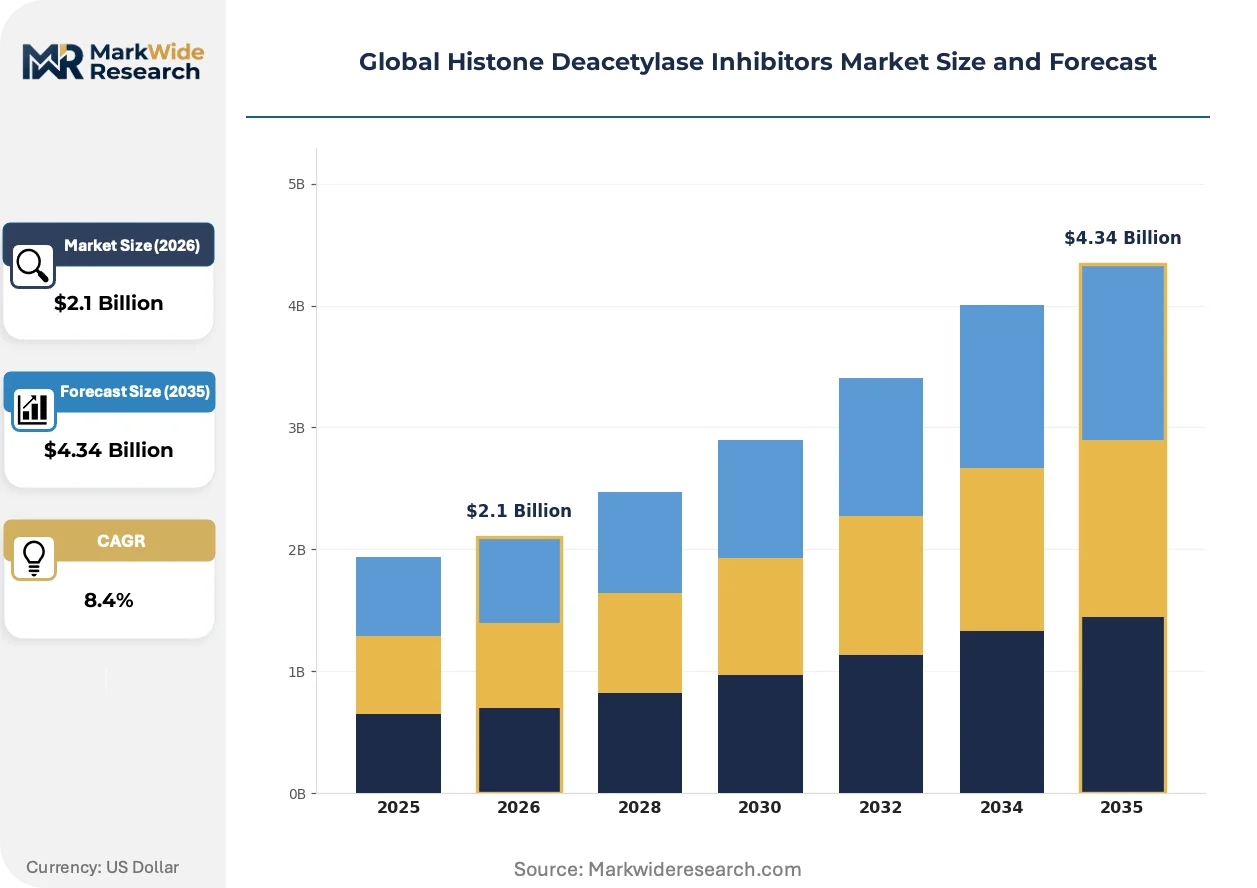
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxamic Acid, Benzamide, Cyclic Peptide, Short Chain Fatty Acid, Others Therapy Area: Oncology, Neurology, Immunology, Infectious Diseases, Rare Disorders End User: Hospitals, Specialty Clinics, Research Institutes, Contract Research Organizations Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal, Others |
| Companies Covered | Merck & Co., Novartis AG, Bristol-Myers Squibb Company, Syndax Pharmaceuticals Inc., Cetya Therapeutics Inc., Spectrum Pharmaceuticals, REGENACY PHARMACEUTICALS, INC., Shenzhen Chipscreen Biosciences Co., Ltd., Italfarmaco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Histone Deacetylase Inhibitors Market Shifts & Advancements
Epigenetic modulation platforms are fragmenting competitive positioning as developers pivot from single-agent HDAC inhibition toward multi-target chromatin remodeling strategies.
Isoform-selective HDAC inhibitors are overtaking pan-inhibitor architectures in late-stage pipelines. These agents target specific HDAC classes to reduce off-target toxicity while preserving anti-tumor efficacy. Hematologic oncology units at academic medical centers are adopting them for combination protocols. The technology is overtaking first-generation hydroxamic acid derivatives in premium pricing tiers.
The EU Green Deal's pharmaceutical sustainability criteria is realigning manufacturing standards for active pharmaceutical ingredients across European supply chains. ECHA REACH compliance now extends to solvent recovery and waste minimization in hydroxamic acid synthesis. German and Swiss contract manufacturers are retrofitting chemical plants to meet these specifications.
Hospital procurement committees are unbundling maintenance therapy decisions from acute care formularies, creating separate evaluation tracks for oral HDAC inhibitors. Specialty pharmacy distributors are displacing traditional wholesale channels for outpatient oncology dispensing. This shift is most visible in United States and Japanese reimbursement systems where maintenance therapy volumes concentrate.
Global Histone Deacetylase Inhibitors Market Segmentation
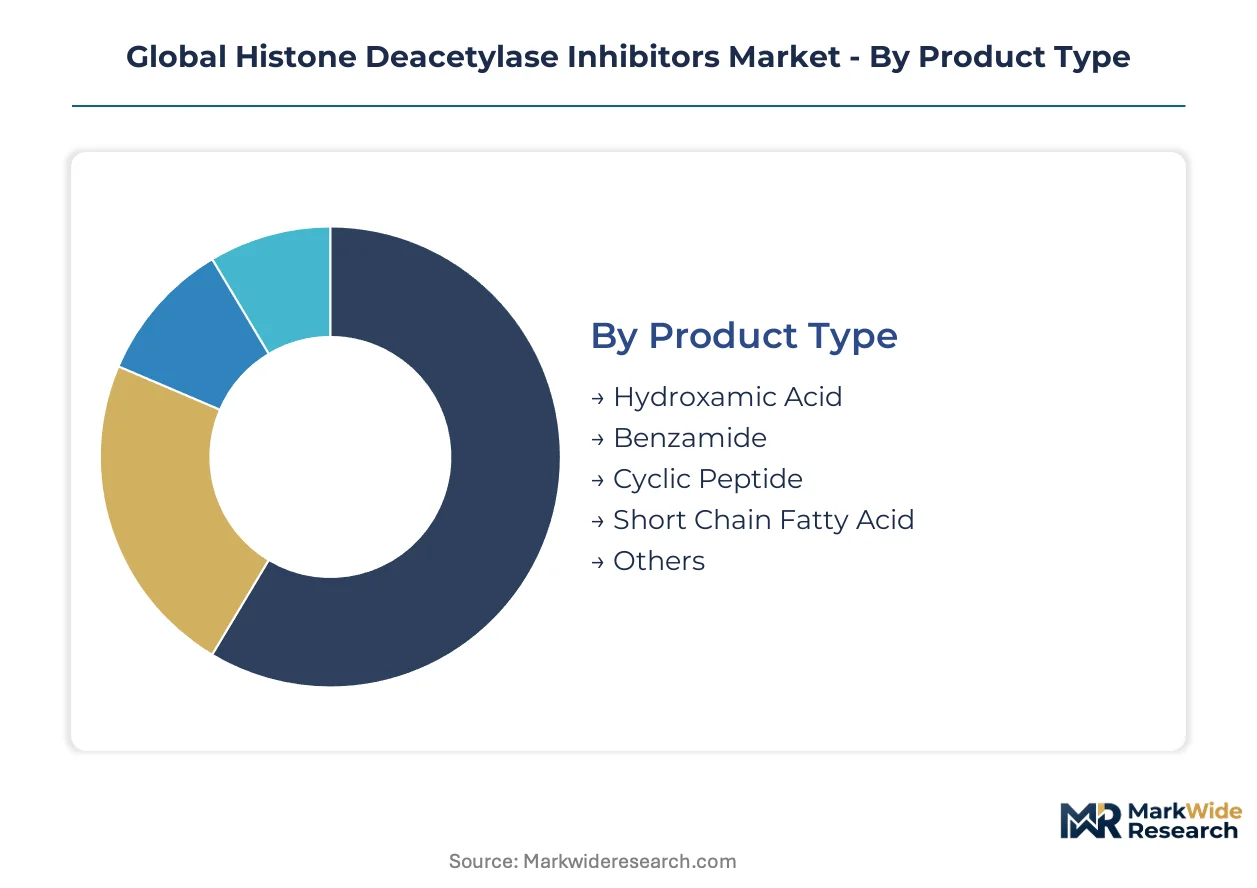
HDAC inhibitor segmentation reflects divergent technical architectures and clinical deployment contexts. Product chemistry dictates manufacturing complexity and regulatory pathway. Therapy area and delivery mode choices determine reimbursement positioning and competitive intensity.
Product Type:
Hydroxamic acid derivatives anchor the technical landscape through zinc-binding pharmacophores with established clinical validation.
- Hydroxamic Acid:These compounds coordinate zinc ions at the enzyme active site with picomolar binding affinity. Demand concentrates in United States academic medical centers where combination protocols for hematologic malignancies drive prescription volumes.
- Benzamide:Benzamide scaffolds offer improved isozyme selectivity profiles compared to pan-inhibitor architectures. German and Swiss oncology units favor these agents for reduced off-target toxicity in maintenance settings.
- Cyclic Peptide:Macrocyclic structures derived from natural product origins.
- Short Chain Fatty Acid:Butyrate analogs with weaker HDAC inhibition potency but favorable metabolic profiles.
- Others:Emerging chemotypes including electrophilic ketones and sirtuin-targeting modifications.
Hydroxamic acid leads on scale; benzamide leads on momentum.
Therapy Area:
Clinical application scope spans malignant and non-malignant indications with sharply divergent development economics.
- Oncology:Hematologic malignancies command the primary revenue pool as first-line adoption concentrates in diffuse large B-cell lymphoma and multiple myeloma protocols. United States and Japan reimbursement pathways for epigenetic therapies in oncology have matured fastest.
- Rare Disorders:Regulators prioritize epigenetic mechanisms for diseases with limited therapeutic alternatives. EMA's Priority Medicines scheme and FDA's Orphan Drug Designation compress development timelines for Friedreich's ataxia and Huntington's disease programs.
- Neurology:Neurodegenerative applications beyond rare disease categories.
- Immunology:Autoimmune modulation through T-regulatory cell enhancement.
- Infectious Diseases:Viral latency reversal strategies in HIV and hepatitis B.
Oncology leads on scale; rare disorders lead on momentum.
End User:
Site of care determines formulation preference and procurement channel structure.
- Hospitals:Acute care environments sustain premium pricing for intravenous formulations. Oncology departments at academic medical centers in Germany and Japan are expanding HDAC inhibitor protocols in combination regimens.
- Specialty Clinics:Outpatient oncology settings favor oral delivery for maintenance therapy compliance. United States specialty pharmacy distributors are displacing traditional wholesale channels for these dispensing volumes.
- Research Institutes:Preclinical and translational investigation of novel epigenetic combinations.
- Contract Research Organizations:Clinical trial execution for combination regimen development.
Hospitals lead on scale; specialty clinics lead on momentum.
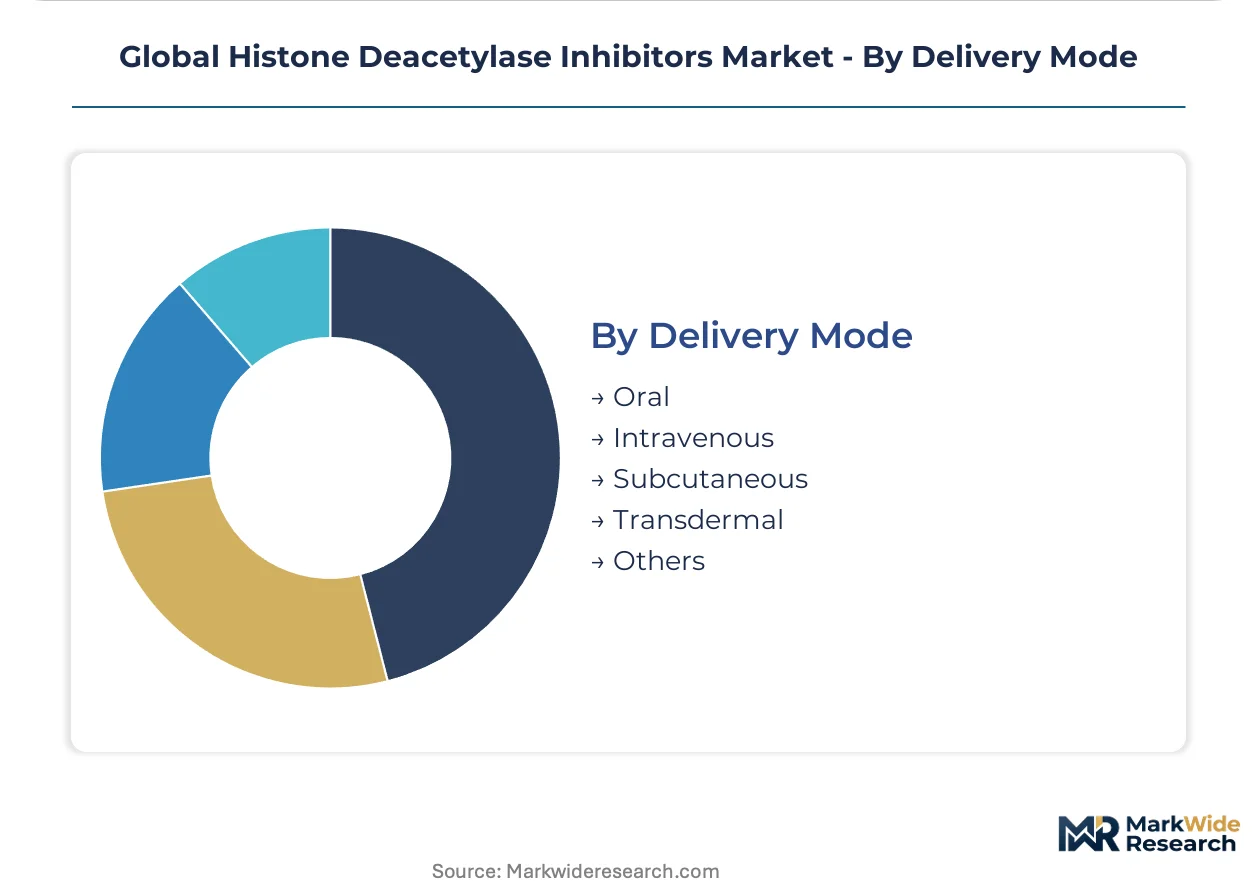
Delivery Mode:
Administration route shapes patient compliance economics and manufacturing investment priorities.
- Oral:Tablet and capsule formulations dominate prescription volumes in maintenance settings. Patient compliance advantages drive protocol adoption in United States and Japanese reimbursement systems where outpatient oncology volumes concentrate.
- Intravenous:Infusion formulations sustain premium pricing in acute care environments. Hospital procurement committees maintain separate evaluation tracks for these products distinct from maintenance therapy formularies.
- Subcutaneous:Depot and sustained-release injection technologies.
- Transdermal:Patch-based delivery for chronic administration scenarios.
- Others:Inhalation and intrathecal routes for specialized CNS targeting.
Oral leads on scale; intravenous leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Histone deacetylase inhibitor commercialization originated in United States academic medical centers during the early 2000s, with subsequent scale-up in German chemical manufacturing corridors and Japanese regulatory innovation. Geographic demand now clusters where epigenetic therapy reimbursement pathways have matured and hydroxamic acid precursor supply chains concentrate.
United States
Oncology departments at academic medical centers in Boston and New York Metro drive combination protocol adoption for hematologic malignancies. FDA Breakthrough Therapy Designation compresses clinical trial timelines for developers targeting diffuse large B-cell lymphoma. The Research Triangle in North Carolina anchors contract manufacturing for hydroxamic acid derivatives serving domestic formulation facilities.
Germany
Baden-Württemberg and North Rhine-Westphalia host retrofitting investments in chemical plants to meet EU Green Deal pharmaceutical sustainability criteria. ECHA REACH compliance now extends to solvent recovery in hydroxamic acid synthesis. Bavarian oncology units favor benzamide scaffolds for reduced off-target toxicity in maintenance therapy settings.
Japan
PMDA's accelerated approval pathway for orphan oncology indications reduces review periods for novel epigenetic agents, opening commercial access earlier in product lifecycles. Tokyo and Osaka academic medical centers expand HDAC inhibitor protocols in combination regimens. Kansai region manufacturers supply intravenous formulations for acute care environments.
China
NMPA conditional approval framework explicitly includes histone modification therapies, enabling domestic manufacturers to commercialize before full trial completion. Shenzhen Chipscreen Biosciences anchors development in the Pearl River Delta. Yangtze River Delta hospitals drive prescription volumes for oral maintenance formulations.
Switzerland
Swissmedic operates parallel review pathways with EMA for priority medicines in hematologic oncology. Basel and Zurich pharmaceutical clusters sustain R&D investment in combination epigenetic therapies. Swiss contract manufacturers specialize in high-potency hydroxamic acid derivative production for European supply chains.
Global Histone Deacetylase Inhibitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the isozyme selectivity spectrum, with isoform-specific architectures commanding pricing power over pan-inhibitor formulations. The vendor base organizes into three tiers: integrated pharmaceutical conglomerates with captive chemical manufacturing, mid-cap biotech specialists focused on rare disease indications, and domestic Chinese developers leveraging conditional approval pathways. Consolidation pressures concentrate in the mid-tier as combination regimen complexity demands specialized pharmacovigilance infrastructure. Dominant competitive moves include backward integration into hydroxamic acid precursor supply and geographic expansion through regulatory pathway arbitrage.
Within the integrated pharmaceutical tier, Merck & Co. and Novartis AG occupy positions defined by manufacturing scale and sustained R&D investment respectively. Bristol-Myers Squibb Company exemplifies the oncology commercial infrastructure archetype through its hospital network penetration across North American and European markets. These three entities represent distinct strategic postures: captive supply security, combination therapy innovation, and acute care formulation dominance.
| Leading Market Players |
|---|
| Merck & Co. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Syndax Pharmaceuticals Inc. |
| Cetya Therapeutics Inc. |
| Spectrum Pharmaceuticals |
| REGENACY PHARMACEUTICALS, INC. |
| Shenzhen Chipscreen Biosciences Co., Ltd. |
| Italfarmaco |
| Others |
Supply & Pricing Matrix
Isoform-selective architectures command substantial premiums over pan-inhibitor formulations, creating a bifurcation that manifests in both reimbursement tiers and precursor sourcing strategies. German and Swiss contract manufacturers capture margin premiums for high-potency hydroxamic acid derivatives, while commodity-grade suppliers in China face cost compression from ECHA REACH compliance burdens.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isoform-specific agents from first-generation hydroxamics from generic short-chain fatty acids. Certification under FDA Breakthrough Therapy and EMA Priority Medicines schemes anchors premium tier positioning. Cost compression in the commodity tier intensifies as Chinese domestic manufacturers exploit NMPA conditional approval pathways. Academic medical centers in the United States exhibit lowest price sensitivity for combination protocol agents, while outpatient specialty clinics in Japan prioritize compliance-driven cost efficiency.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate qualified suppliers for both intravenous and oral formulation precursors. Active pharmaceutical ingredient production concentrates in Germany, Switzerland, and China, with hydroxamic acid derivatives drawing from zinc salt and solvent feedstocks anchored in the Rhine-Ruhr and Yangtze River Delta corridors. Single-source vulnerability persists for picomolar-affinity optimization expertise concentrated at limited research institutions. Distribution runs through specialty pharmacy channels for maintenance therapy volumes and traditional hospital distributors for acute care formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japan's PMDA accelerated approval pathway and the United States' mature reimbursement infrastructure creates differential cost structures for developers targeting orphan oncology indications.
For Market Incumbents: Hedge against emerging targeted protein degradation modalities by deepening captive supply of hydroxamic acid precursors through backward integration into German chemical manufacturing corridors. Secure pharmacovigilance infrastructure for immune-related adverse event profiling in combination regimens, as regulatory agencies tighten post-market surveillance requirements. For New Entrants and Emerging Players: China's NMPA conditional approval framework opens a window for domestic manufacturers to commercialize histone modification therapies before full trial completion. Target rare disorders as the fastest-expanding revenue pool outside oncology, leveraging EMA Priority Medicines scheme compression for Friedreich's ataxia programs. Pursue hospital system partnerships in the Pearl River Delta for oral maintenance formulation adoption. For Investors and Strategic Acquirers: Consolidation pressure builds where combination regimen complexity demands specialized pharmacovigilance infrastructure that mid-cap biotech specialists lack in-house. Long-term viability favors integrated pharmaceutical conglomerates with captive chemical manufacturing and sustained R&D investment in multi-target chromatin remodeling strategies. Monitor isoform-selective HDAC inhibitor pipeline advancement as the inflection indicator for premium pricing tier sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Merck & Co.'s captive manufacturing footprint secures hydroxamic acid derivative supply chains against single-source vulnerability. |
| Regulatory Pathway Arbitrage | Shenzhen Chipscreen Biosciences leverages NMPA conditional approval to commercialize before full trial completion. |
| Isoform-Selective Pipeline Advancement | Novartis AG's sustained R&D investment targets specific HDAC classes to reduce off-target toxicity while preserving efficacy. |
| Specialty Pharmacy Channel Expansion | Bristol-Myers Squibb's hospital network penetration captures maintenance therapy volumes displacing traditional wholesale channels. |
| EU Green Deal Manufacturing Retrofit | German and Swiss contract manufacturers upgrade solvent recovery systems to meet ECHA REACH pharmaceutical sustainability criteria. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation. Bottom-up and top-down triangulation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases across the analysis window.
Rate-of-change decomposition separates volume drivers from pricing dynamics across therapy area, product chemistry, delivery mode, and regional regulatory cluster dimensions. CAGRs derive from segmented growth trajectory modeling incorporating orphan drug designation frequency, combination protocol adoption curves, and conditional approval pathway utilization rates.
Revisions become necessary when regulatory pathway timelines shift, pharmacovigilance requirements tighten, or targeted protein degradation modalities achieve clinical validation in hematologic indications. Deviation in hydroxamic acid precursor supply concentration or ECHA REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Global Ebola Virus Vaccine Market