
 Prescription Stimulants Market | 2026-2036
Prescription Stimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Stimulants Market Analytics
Software-defined dose titration is consolidating as a core service layer that manufacturers bundle with branded formulations. Takeda Pharmaceutical Co. Ltd leverages its extended-release portfolio to sustain reimbursement advantages across North American formularies. Novartis AG anchors European market presence through established methylphenidate supply chains. Eli Lilly and Company differentiates via lisdexamfetamine specialization in adult ADHD segments.
Prescription stimulants comprise controlled-substance psychostimulants—primarily methylphenidate, amphetamine salts, dexmethylphenidate, and lisdexamfetamine—synthesized through chiral resolution or prodrug modification to achieve specific duration-of-action profiles, prescribed mainly for attention deficit hyperactivity disorder and narcolepsy management. The therapy area dimension shows ADHD commanding the largest revenue pool while adult patient segments generate faster prescription velocity than pediatric cohorts. Amphetamine-class molecules retain pricing power relative to methylphenidate generics, concentrating margin capture among manufacturers with DEA quota access.
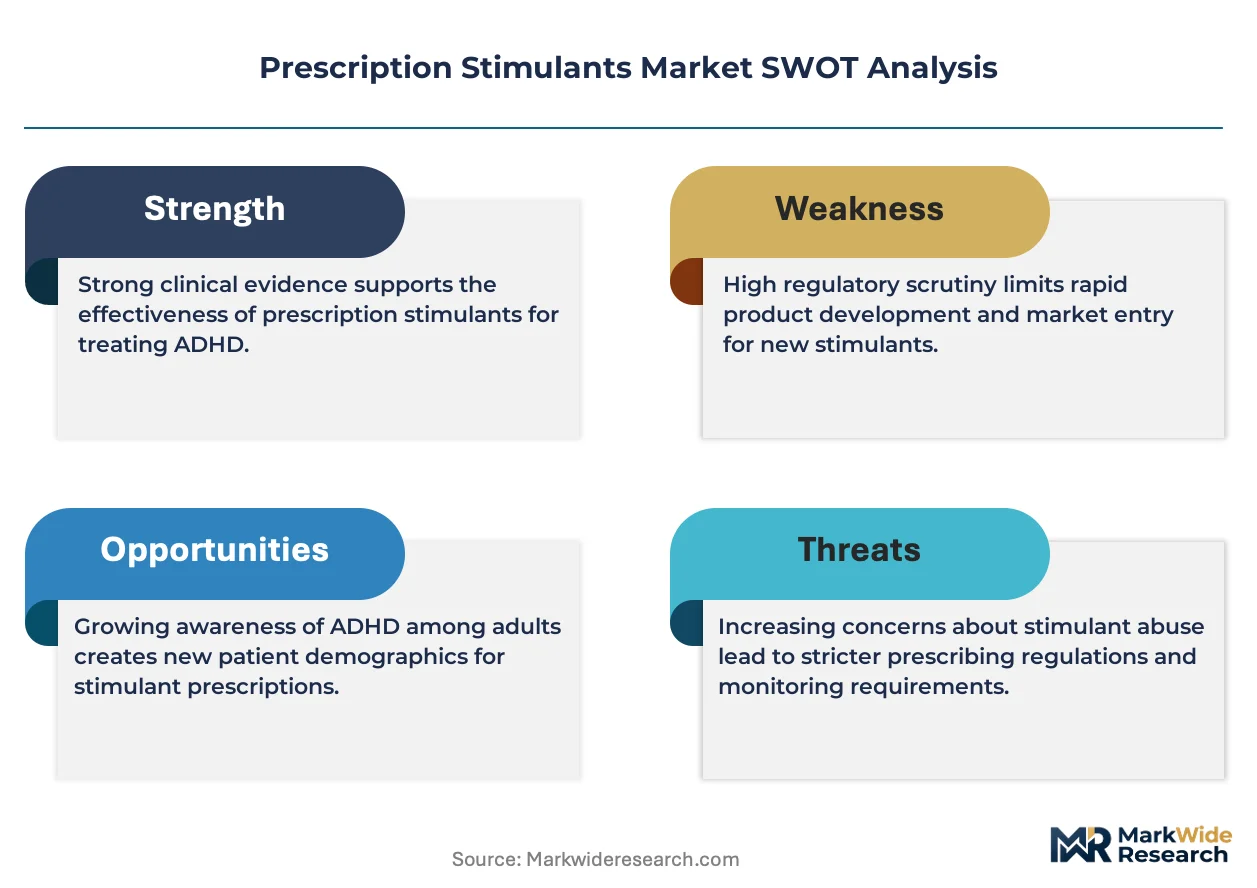
The FDA's Controlled Substances Act scheduling, DEA production quotas, and state-level prescription drug monitoring programs collectively restrict supply elasticity and shape competitive barriers to entry. EMA pharmacovigilance requirements and national health technology assessments in Germany and France add parallel compliance burdens for European market access. Stakeholders must monitor DEA quota allocation decisions and state-level telehealth prescribing rules as these directly determine volume availability and channel economics.
Market Dynamics
The DEA's annual production quota system creates artificial supply scarcity that manufacturers navigate through quota trading agreements and inventory staging strategies, fundamentally constraining volume elasticity regardless of prescription demand signals.
Growth Catalysts
- Adult ADHD diagnostic expansion:Revised DSM-5 criteria and workplace mental health programs broaden the addressable patient base beyond pediatric populations.
- Telehealth prescribing flexibility:Post-pandemic regulatory accommodations for controlled substance remote prescribing reduce geographic access barriers in rural United States markets.
- Extended-release formulation patents:Prodrug and osmotic delivery technologies extend effective patent life and sustain branded pricing power against immediate-release generics.
Market Restraints
- DEA quota concentration:Annual amphetamine and methylphenidate production limits allocate disproportionately to incumbent manufacturers, freezing new entrant supply access.
- Active pharmaceutical ingredient dependency:Bulk stimulant precursor synthesis concentrates among Chinese and Indian chemical manufacturers, exposing formulators to import tariff volatility.
- Schedule II dispensing friction:Federal and state-level prescription drug monitoring program mandates impose 30-day supply limits and in-person pickup requirements that compress pharmacy throughput.
Strategic Opportunities
- Digital therapeutics bundling:FDA-cleared cognitive training software and dose-optimization apps create reimbursement-advantaged combination products.
- Narcolepsy segment penetration:Underdiagnosed sleep disorder populations in Germany and France represent expansion vectors beyond ADHD saturation.
- Biosimilar methylphenidate pathways:EMA regulatory clarity on complex generic equivalence standards opens margin-compression strategies against legacy brands.
Industry Challenges
- Controlled substance compliance staffing:DEA registration maintenance and suspicious order monitoring require specialized pharmacy and logistics personnel that command wage premiums.
- Reimbursement prior authorization complexity:Payer step-therapy protocols and age-based coverage restrictions extend prescription fulfillment timelines and increase abandonment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Stimulants Market |
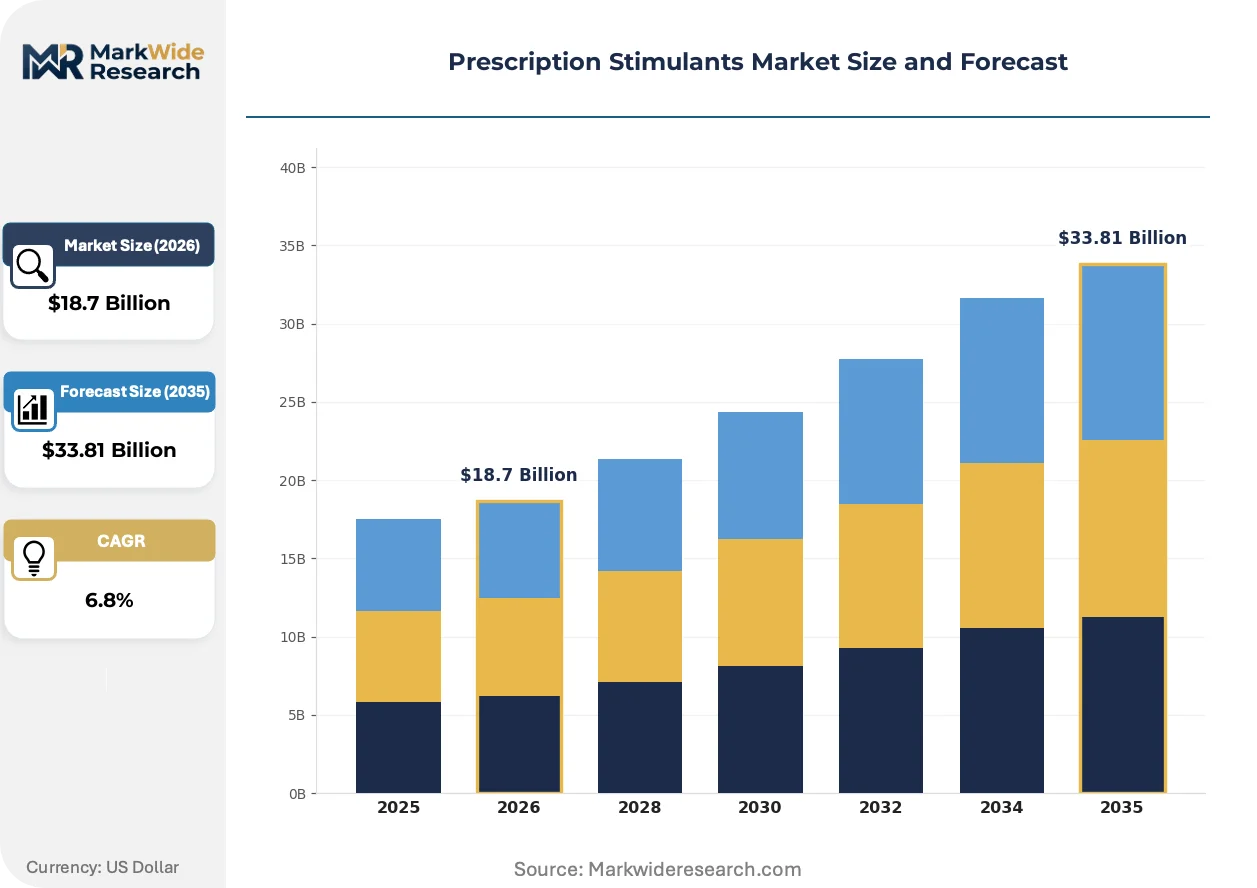
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylphenidate, Amphetamine, Dexmethylphenidate, Lisdexamfetamine Therapy Area: Attention Deficit Hyperactivity Disorder, Narcolepsy, Obesity, Depression End User: Pediatric Patients, Adult Patients, Geriatric Patients, Healthcare Professionals Distribution Channel: Pharmacies, Online Stores, Hospitals, Clinics |
| Companies Covered | Ironshore Pharmaceuticals Inc., Novartis AG, Takeda Pharmaceutical Co. Ltd, Azurity Pharmaceuticals Inc., Noven Therapeutics LLC, Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, Supernus Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Stimulants Market Evolving Landscape
Formulation science and digital delivery mechanisms are restructuring how patients initiate and maintain stimulant therapy, compressing the traditional physician-pharmacy-patient triad into integrated care platforms.
Abuse-deterrent polymer matrices and prodrug architectures are expanding into adult patient segments where diversion risk and workplace safety concerns previously limited prescribing confidence. Psychiatrists and primary care networks in the United States are adopting these formulations at rates exceeding pediatric transitions. The technology is expanding into employer-sponsored health plans that mandate tamper-resistant alternatives as a condition of coverage.
EMA's strengthened pharmacovigilance requirements for pediatric psychostimulants now mandate real-world cardiovascular outcome tracking across European member states. Manufacturers must fund post-authorization safety studies as a condition of marketing authorization renewal. Central nervous system drug sponsors in France and Germany are restructuring clinical development programs to incorporate these longitudinal data collection obligations.
Specialty pharmacy distribution is displacing traditional retail channels for controlled substance stimulants as payers consolidate fulfillment through restricted networks with integrated adherence monitoring. Mail-order and hub-and-spoke models with biometric verification are replacing community pharmacy pickup for maintenance prescriptions. This channel compression is most visible in United States commercial insurance segments where vertical integration between pharmacy benefit managers and specialty distributors has accelerated.
Prescription Stimulants Market Segmentation
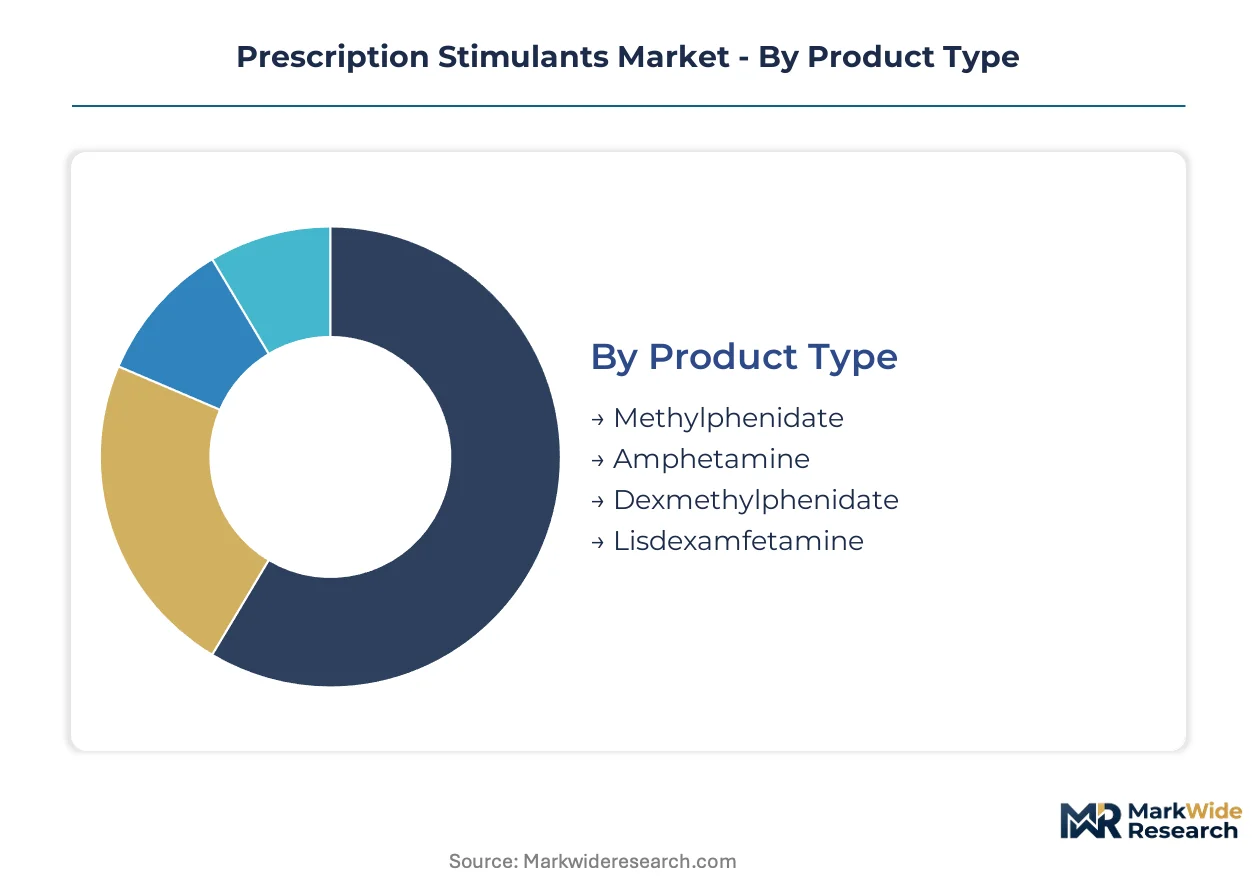
Segmentation in prescription stimulants determines quota allocation, pricing power, and channel strategy. DEA scheduling tiers and formulation patents create divergent margin structures across molecule classes and patient populations.
Product Type:
Volume concentrates in immediate-release generics while premium capture belongs to extended-release and prodrug architectures.
- Methylphenidate:The original racemic psychostimulant, available in immediate-release and osmotic-controlled formulations. Demand clusters in pediatric ADHD through Medicaid formularies where generic substitution rates exceed branded retention. DEA quota allocation favors established manufacturers with historical production baselines.
- Amphetamine:Mixed amphetamine salts and pure dextroamphetamine deliver stronger dopaminergic signaling for treatment-resistant cases. Adult patients in United States commercial insurance segments drive prescription velocity for extended-release variants that command prior authorization protection.
- Dexmethylphenidate:The d-threo enantiomer offers refined pharmacokinetics with reduced peripheral side effects. Prescribing concentrates among psychiatrists seeking smoother onset-offset profiles for adolescent patients.
- Lisdexamfetamine:A prodrug requiring enzymatic cleavage to release active dextroamphetamine, providing intrinsic abuse deterrence through delayed pharmacological effect. Workplace drug testing protocols and employer wellness programs favor this molecule for adult ADHD coverage.
Mature deployment sits with methylphenidate immediate-release. Newer deployment is concentrated in lisdexamfetamine prodrug formulations.
Therapy Area:
Application breadth spans neurodevelopmental disorders through metabolic and mood indications with divergent reimbursement pathways.
- Attention Deficit Hyperactivity Disorder:The foundational indication covering combined, inattentive, and hyperactive-impulsive presentations. Pediatric diagnostic protocols in United States school systems and workplace accommodation frameworks for adults sustain prescription volume across age strata.
- Narcolepsy:Excessive daytime sleepiness and cataplexy management utilizing stimulant wakefulness promotion. Underdiagnosis in French and German sleep medicine clinics creates expansion headroom beyond ADHD saturation.
- Obesity:Off-label and historical indications for appetite suppression with limited contemporary prescribing due to cardiovascular safety surveillance. Bariatric medicine specialists in select United States markets retain limited utilization.
- Depression:Adjunctive therapy for treatment-resistant major depressive disorder, particularly in geriatric populations where standard antidepressants prove insufficient. Psychiatric practices with interventional focus maintain niche prescribing.
Established utilization centers on ADHD. Narcolepsy applications are expanding most quickly as sleep disorder recognition improves.
End User:
Customer type dictates formulation preference, adherence technology adoption, and prescriber specialty access patterns.
- Pediatric Patients:School-age children and adolescents requiring symptom management compatible with academic scheduling. Caregiver-administered morning dosing and school nurse midday coverage shape product selection toward long-acting formulations with predictable duration.
- Adult Patients:Working-age individuals seeking cognitive performance optimization and workplace functioning improvement. This cohort generates the steepest prescription growth trajectory as diagnostic criteria broaden and employer mental health programs expand coverage.
- Geriatric Patients:Older adults with late-onset ADHD recognition or depression augmentation needs. Cardiovascular monitoring requirements and polypharmacy interactions limit stimulant initiation rates relative to younger populations.
- Healthcare Professionals:Prescriber education and sample access programs targeting psychiatrists, primary care physicians, and nurse practitioners with DEA registration for Schedule II controlled substances.
Volume concentration rests with pediatric patients. Adult patient segments are gaining share fastest as workplace mental health investment accelerates.
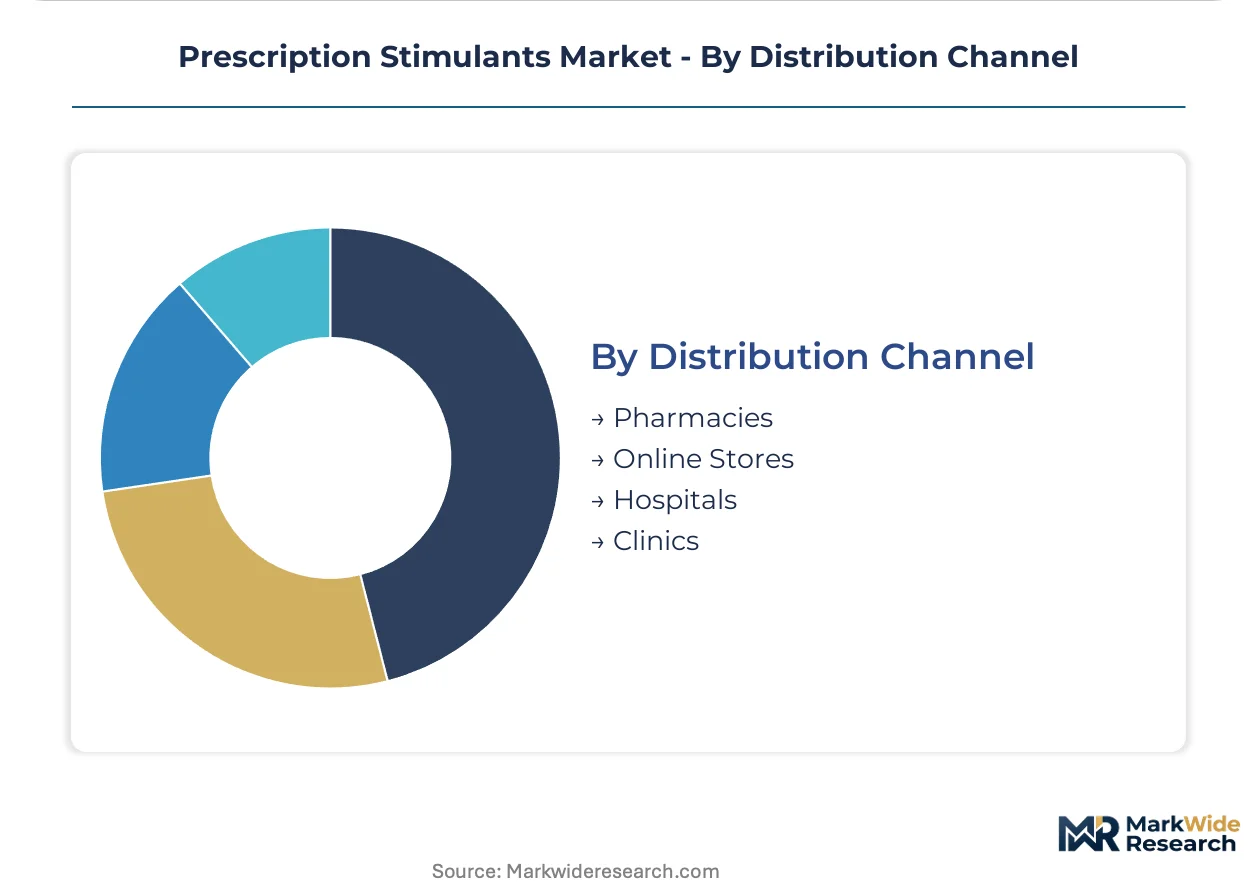
Distribution Channel:
Channel economics reflect controlled substance security requirements, reimbursement consolidation, and patient convenience preferences.
- Pharmacies:Community and retail locations with DEA registration for Schedule II dispensing and prescription drug monitoring program integration. State-mandated in-person pickup and 30-day supply limits compress throughput relative to standard medications.
- Online Stores:Mail-order fulfillment through specialty pharmacy networks with biometric verification and cold-chain logistics for controlled substances. Vertical integration between pharmacy benefit managers and distributors accelerates this channel in United States commercial segments.
- Hospitals:Inpatient and emergency department settings for acute narcolepsy management or ADHD medication initiation requiring observation. Formulary placement depends on therapeutic interchange policies and sedation reversal protocols.
- Clinics:Office-based dispensing in integrated behavioral health settings with on-site medication management. Direct distribution reduces pharmacy abandonment rates for patients with transportation or insurance barriers.
Traditional pharmacy infrastructure retains volume leadership. Online specialty distribution is displacing retail fastest where PBM-distributor integration has advanced.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in DEA-registered manufacturing sites across the United States, while consumption patterns diverge sharply between American and European prescribing cultures. Quota allocation systems in Washington determine supply availability for export markets.
United States
Adult ADHD diagnostic expansion and employer-sponsored mental health programs drive prescription velocity in commercial insurance segments. The FDA's Controlled Substances Act scheduling and DEA annual production quotas restrict supply elasticity regardless of demand signals. Philadelphia and Research Triangle Park host concentration of formulation science operations for extended-release architectures.
Germany
Sleep medicine clinics in Bavaria and North Rhine-Westphalia identify underdiagnosed narcolepsy populations as expansion vectors beyond ADHD saturation. The country's national pharmaceutical regulator mandates real-world cardiovascular outcome tracking for pediatric psychostimulants through post-authorization safety studies. Berlin anchors pharmacovigilance coordination across European member states.
France
Workplace mental health investment and revised diagnostic protocols broaden adult patient access beyond traditional pediatric prescribing. ANSM enforces strengthened pharmacovigilance requirements as a condition of marketing authorization renewal. Lyon and Paris clusters concentrate specialist psychiatric practices with DEA-equivalent controlled substance registration.
Canada
Telehealth prescribing accommodations and provincial formularies expand geographic access in rural markets beyond urban concentration. Health Canada scheduling decisions align with FDA frameworks while maintaining independent production quota negotiations. Toronto and Montreal host distribution hubs for cross-border specialty pharmacy networks.
Switzerland
Precision medicine approaches and employer wellness programs favor abuse-deterrent prodrug formulations in adult segments. Swissmedic maintains stringent pharmacovigilance standards that exceed baseline EMA requirements. Basel concentrates headquarters operations for manufacturers with integrated European supply chains.
Prescription Stimulants Market Competitive Landscape
Capital-heavy producers with DEA quota allocation compete with asset-light formulation specialists licensing delivery technologies. Market structure consolidates around incumbent manufacturers with historical production baselines, while new entrants face frozen supply access regardless of product differentiation. Three archetypes dominate: quota-anchored incumbents with extended-release patent portfolios, prodrug specialists leveraging intrinsic abuse deterrence, and generic immediate-release manufacturers serving Medicaid formularies. Dominant competitive moves include quota trading agreements between established players and strategic partnerships with digital therapeutics developers.
Among Swiss-based pharmaceutical conglomerates, Novartis AG occupies a position representing established methylphenidate supply chain presence across European markets. Takeda Pharmaceutical Co. Ltd exemplifies the quota-anchored incumbent archetype with extended-release portfolio concentration in North American formularies. Eli Lilly and Company sits within the prodrug specialization tier, anchoring adult ADHD segment positioning through lisdexamfetamine expertise. These three entities collectively represent the competitive spectrum from generic-facing legacy molecules to premium-priced abuse-deterrent architectures.
| Leading Market Players |
|---|
| Ironshore Pharmaceuticals Inc. |
| Novartis AG |
| Takeda Pharmaceutical Co. Ltd |
| Azurity Pharmaceuticals Inc. |
| Noven Therapeutics LLC |
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| Supernus Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Quota-anchored incumbents with DEA production allocations command pricing power through artificial supply scarcity, while private-equity-rolled-up specialty pharmacy networks extract margin through controlled-substance distribution consolidation. This ownership pattern concentrates pricing discipline in manufacturers with historical production baselines and distributors with biometric verification infrastructure.
Pricing Analysis
Margin tightening in immediate-release methylphenidate reflects Medicaid formulary substitution pressure and generic manufacturer concentration. Three-tier pricing structure across abuse-deterrent prodrugs, extended-release formulations, and immediate-release generics separates DEA quota-protected innovators from commodity suppliers. Cost-down pressure on amphetamine salts accelerates because Indian and Chinese API import tariffs compress formulator margins. Pediatric Medicaid segments exhibit highest price sensitivity; employer-sponsored commercial plans covering adult ADHD demonstrate lowest sensitivity due to prior authorization protection.
Supply Chain Analysis
Workforce availability constraints in DEA-registered Pennsylvania and North Carolina formulation sites limit extended-release production scaling. Active pharmaceutical ingredient synthesis concentrates in China and India, with chiral resolution chemistry drawing from Sichuan and Gujarat chemical manufacturing clusters. Single-source vulnerability in lisdexamfetamine prodrug precursor supply exposes formulators to export license disruptions. Distribution runs through specialty pharmacy networks with biometric verification, displacing traditional retail channels in United States commercial insurance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained system where DEA production quotas prop pricing power regardless of prescription demand expansion. Capacity bottlenecks in Schedule II manufacturing licenses sustain incumbent margin capture.
For Market Incumbents: To counter generic erosion in Medicaid formularies, secure additional DEA quota through trading agreements with quota-underutilized manufacturers, and deepen backward integration into abuse-deterrent polymer matrix production to sustain branded differentiation against immediate-release substitutes.
For New Entrants and Emerging Players: Begin with digital therapeutics bundling opportunities in employer-sponsored wellness programs, where FDA-cleared cognitive training software paired with dose-optimization apps creates reimbursement-advantaged entry points outside DEA quota constraints. Target narcolepsy penetration in German and French sleep medicine clinics as the most penetrable geography.
For Investors and Strategic Acquirers: DEA quota reallocation hearings are the leading indicator that supply elasticity constraints may loosen, warranting repositioning away from pure quota-dependent assets. Five-to-ten-year viability favors prodrug specialists with intrinsic abuse deterrence and specialty pharmacy distributors with vertical integration. Monitor state-level telehealth prescribing rule expansions as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Trading Agreement | Quota reallocation between manufacturers unlocks volume expansion without new facility investment. |
| Abuse-Deterrent Formulation Patent Extension | Prodrug architecture patents sustain branded pricing power against immediate-release generic substitution. |
| Digital Therapeutics FDA Clearance | Cognitive training software bundling creates reimbursement-advantaged combination product positioning. |
| Specialty Pharmacy Network Acquisition | Biometric verification infrastructure captures channel margin from traditional retail displacement. |
| Narcolepsy Indication Expansion | Sleep disorder recognition in France and Germany opens addressable patient base beyond ADHD saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this prescription stimulants analysis. Primary interviews with DEA registration compliance officers, formulary directors at commercial payers, specialty pharmacy operations executives, and psychiatrists with Schedule II prescribing authority combined with FDA enforcement actions, DEA quota allocation notices, and state prescription drug monitoring program regulations. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation validated segment-level estimates.
Data-stream reconciliation across DEA production quota allocations, IMS prescription audit data, and manufacturer revenue disclosures structured the analytical framework. Segmentation dimensions spanned molecule class, formulation release profile, therapy area indication, patient age cohort, and regional regulatory cluster. CAGRs derived from quota-constrained supply elasticity modeling and demand-side diagnostic expansion trends. Forecast inputs incorporated telehealth prescribing rule evolution and employer mental health program adoption curves.
Underlying measurement precision varies by segment; extended-release branded formulations carry tighter precision than immediate-release generic substitution rates. Forecasts reflect documented assumptions regarding DEA quota continuity and state-level prescribing accommodation permanence. Material deviation in DEA reallocation policy or federal telehealth controlled substance restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
HPV Vaccines Market