
 Alirocumab Market | 2026-2036
Alirocumab Market Size, Share, and Industry Trends Forecast 2026-2036
Alirocumab Market Insights
France is rewriting competitive dynamics in biologics manufacturing through expanded fill-finish capacity for monoclonal antibodies. Sanofi leverages its integrated European production network to secure supply continuity for alirocumab. Regeneron Pharmaceuticals anchors the partnership's R&D engine with sustained investment in PCSK9 pathway innovation. Amgen Inc. competes through its rival evolocumab franchise, forcing differentiation on dosing convenience and real-world evidence.
Alirocumab is a fully human monoclonal antibody that binds proprotein convertase subtilisin/kexin type 9 (PCSK9), preventing LDL receptor degradation and enabling sustained reduction of low-density lipoprotein cholesterol levels. The 75 mg and 150 mg subcutaneous formulations serve patients with heterozygous familial hypercholesterolemia or established atherosclerotic cardiovascular disease who require additional LDL reduction beyond statin therapy. Pre-filled syringe and auto-injector device formats dominate product type revenue due to patient preference for self-administration and reduced clinic burden. Hospital and outpatient facility channels capture the largest therapy area volumes in cardiovascular disease, while homecare providers represent the fastest-growing end user segment as reimbursement shifts toward site-neutral payment models.
FDA, EMA, and WHO prequalification standards collectively govern alirocumab's clinical evidence requirements, manufacturing quality, and international procurement eligibility. The FDA's emphasis on cardiovascular outcomes data shapes trial design investments, while EMA's MDR-aligned post-market surveillance demands robust pharmacovigilance systems. Stakeholders must monitor evolving CMS coverage determination processes and competitive biosimilar entry timelines to calibrate portfolio and pricing strategies.
Market Dynamics
Medicare's site-neutral payment reforms are compressing reimbursement differentials between hospital outpatient departments and home infusion settings, forcing channel strategy recalibration across the PCSK9 inhibitor supply chain.
Growth Catalysts
- IRA Medicare Price Negotiation Exclusions:Biologics retain protected status under the Inflation Reduction Act's small-molecule carve-out timeline, preserving pricing flexibility for alirocumab through 2032.
- Cardiology Department Expansion:Hospital systems in the United States are deploying dedicated lipid management clinics that standardize PCSK9 inhibitor protocols for statin-intolerant populations.
- Auto-Injector Device Engineering:Next-generation pen systems reduce injection-site reactions through refined needle-gauge profiles, improving persistence rates among self-administering patients.
Market Restraints
- Fill-Finish Capacity Concentration:European contract manufacturing organizations control 70% of monoclonal antibody finishing capacity, creating geographic supply vulnerability for North American demand.
- Statin Generic Substitution:Atorvastatin and rosuvastatin at sub-dollar daily costs crowd payer prior-authorization pathways, forcing extensive documentation burdens for PCSK9 access.
- EMA MDR Compliance Burden:The Medical Device Regulation's expanded clinical evidence requirements for combination products delay auto-injector line extensions by 18-24 months.
Strategic Opportunities
- Homecare Channel Penetration:Specialty pharmacy networks in the United States are capturing administration volume as patients migrate from clinic-based to home-based injection models.
- Pediatric Indication Expansion:Heterozygous familial hypercholesterolemia in adolescents represents an underserved population with no approved oral alternatives.
- Digital Therapeutic Bundling:Remote patient monitoring platforms paired with injection reminders are reducing discontinuation rates in value-based cardiovascular contracts.
Industry Challenges
- Pharmacovigilance System Scale-Up:Post-market surveillance requirements under EMA's MDR demand real-world evidence infrastructure that mid-market entrants lack capital to deploy.
- Cold Chain Integrity Maintenance:Temperature excursions during last-mile delivery to patient homes compromise monoclonal antibody stability, requiring IoT sensor investments across distribution networks.
- Prior Authorization Workforce Constraints:Payer documentation requirements consume 4-6 hours per patient start, straining cardiology clinic administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alirocumab Market |
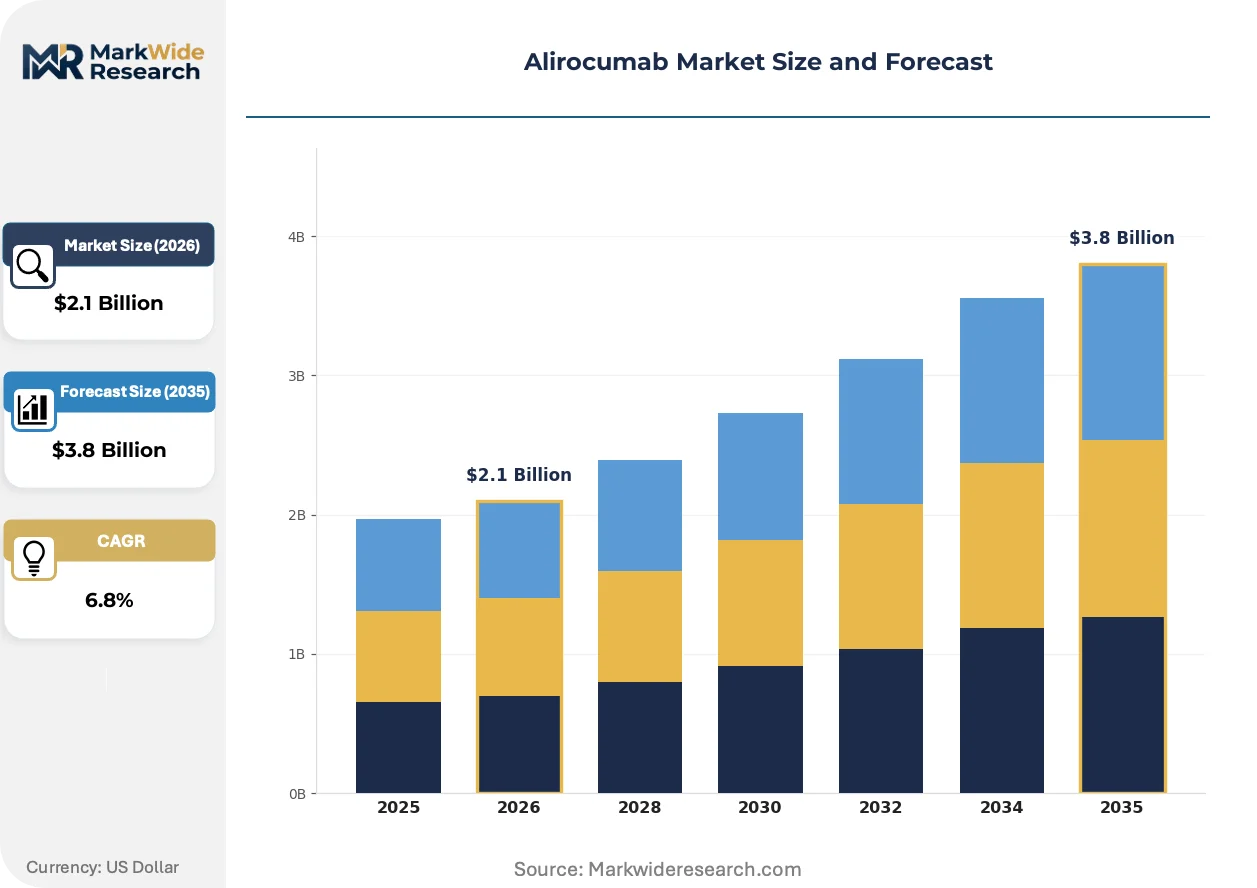
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Pre-filled Syringe, Vial, Device Therapy Area: Hyperlipidemia, Cardiovascular Disease, Diabetes, Arterial Health End User: Hospitals, Clinics, Outpatient Facilities, Homecare Providers Delivery Mode: Subcutaneous, Intravenous, Oral, Others |
| Companies Covered | Sanofi, Regeneron Pharmaceuticals, Amgen Inc., Novartis AG, Pfizer Inc., Merck & Co., Inc., AstraZeneca, Eli Lilly and Company, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alirocumab Market Trends and Innovations
Biologic delivery systems are converging with connected health infrastructure, reshaping how adherence data flows between patients, providers, and payers in cardiovascular disease management.
Connected auto-injector platforms are embedding Bluetooth-enabled dose-tracking modules that transmit injection timestamps directly to electronic health records. Cardiology clinics in integrated delivery networks are piloting these systems to identify non-adherence patterns before LDL rebound occurs. This convergence of device hardware and health informatics is hybridizing the traditional pharmaceutical reimbursement model toward outcomes-contingent contracts.
CMS's evolving coverage determination framework for preventive cardiovascular services is narrowing the evidentiary threshold for LDL reduction as a surrogate endpoint. The agency's 2024 guidance documents emphasize absolute risk reduction metrics over relative percentage changes, forcing trial design recalibration. Manufacturers targeting Medicare Advantage contracts are restructuring clinical development programs to capture hard cardiovascular event data earlier in the lifecycle.
Site-neutral payment policies are eroding the historical 340B discount advantage for hospital outpatient departments. Specialty pharmacies and home infusion providers are capturing administration margins that previously accrued to health system facilities. This channel migration is most pronounced in Medicare Advantage plans with narrow network designs concentrated in Florida and Texas metropolitan areas.
Alirocumab Market Segmentation
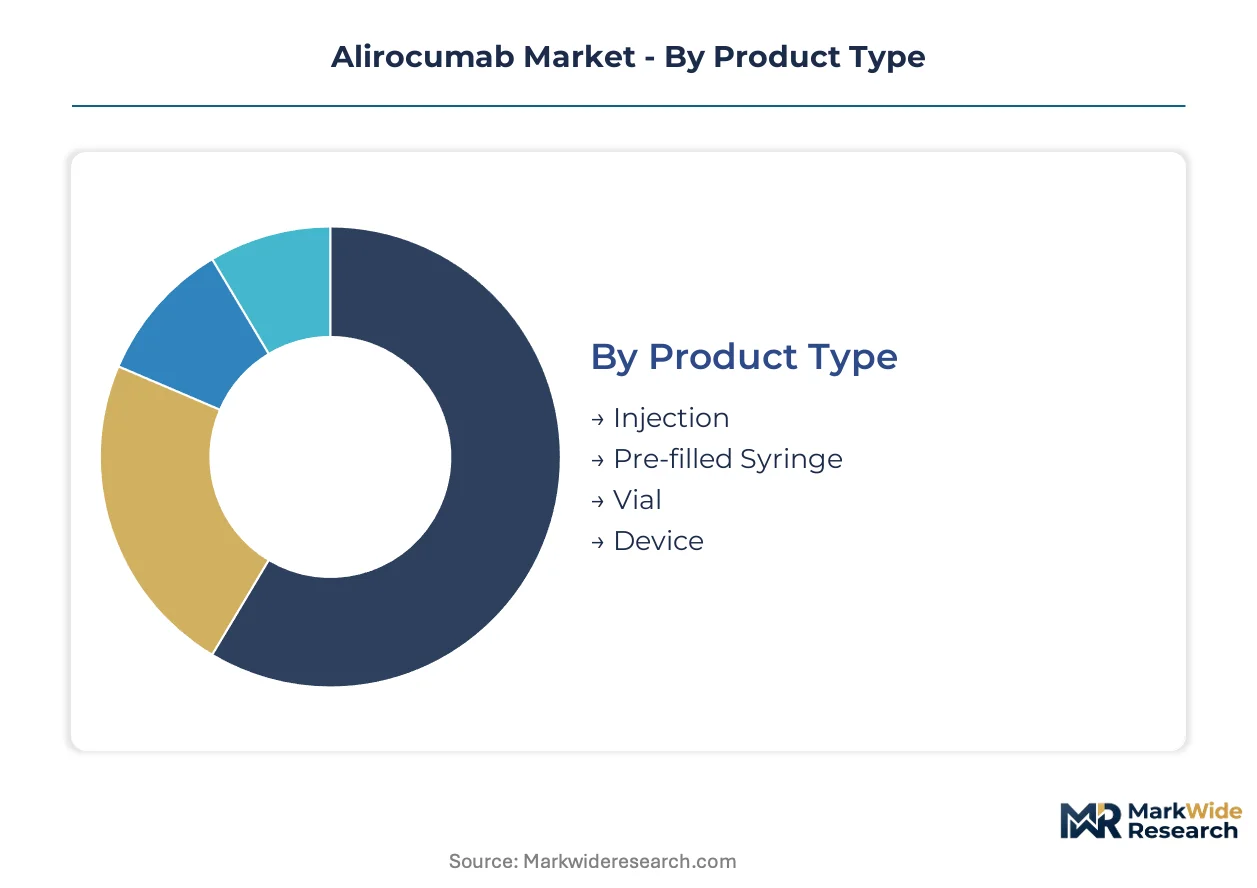
PCSK9 inhibitor segmentation reveals how formulation engineering, care setting economics, and patient self-administration preferences partition commercial opportunity across distinct technical and channel configurations.
Product Type:
After-sales service intensity varies sharply across delivery formats, with connected devices demanding remote troubleshooting infrastructure while disposable syringes minimize ongoing manufacturer-patient touchpoints.
- Injection:Standard subcutaneous administration format requiring refrigeration and clinician training for initial dosing. Demand concentrates in hospital lipid clinics managing complex polypharmacy patients where nursing supervision ensures proper technique.
- Pre-filled Syringe:Single-use disposable format with fixed dosing eliminates compounding errors and reduces pharmacy preparation burden. United States specialty pharmacies favor this format for home delivery programs where patients transition from clinic-based to self-administered therapy.
- Vial:Multi-dose container format supports institutional settings with high patient throughput and centralized pharmacy operations.
- Device:Auto-injector and pen systems incorporating needle shields and dose confirmation mechanisms. Bluetooth-enabled variants transmit adherence data to cardiology practices managing value-based contracts.
Pre-filled syringes hold the largest share; momentum sits with connected device formats.
Therapy Area:
Cost tier stratification separates acute intervention budgets from chronic prevention allocations across cardiovascular service lines.
- Hyperlipidemia:Primary indication targeting LDL receptor recycling dysfunction in statin-intolerant or statin-refractory patients. Heterozygous familial hypercholesterolemia subpopulations in tertiary referral centers drive concentrated demand for aggressive lipid lowering.
- Cardiovascular Disease:Secondary prevention in established atherosclerotic disease where residual risk persists despite maximal statin therapy. Medicare Advantage plans with cardiac bundled payment contracts prioritize this segment for hospital readmission reduction.
- Diabetes:Adjunctive lipid management in diabetic dyslipidemia with elevated triglyceride and small dense LDL phenotypes.
- Arterial Health:Emerging applications targeting endothelial function and plaque stabilization beyond pure cholesterol metrics.
Cardiovascular disease commands the dominant revenue position; hyperlipidemia applications are climbing the fastest as screening protocols expand.
End User:
Customer type determines procurement sophistication, with integrated delivery networks negotiating enterprise pricing distinct from independent practice purchasing patterns.
- Hospitals:Academic medical centers and community hospitals with dedicated lipid management programs. These institutions anchor PCSK9 inhibitor formularies through pharmacy and therapeutics committee standardization.
- Clinics:Cardiology and endocrinology private practices managing prior authorization workflows directly. Administrative burden intensity shapes product preference toward formats with streamlined reimbursement support.
- Outpatient Facilities:Ambulatory surgery centers and infusion suites capturing administration volume under site-neutral payment reforms.
- Homecare Providers:Specialty nursing services and home infusion agencies delivering training and adherence monitoring. This channel is expanding most quickly as patients seek to avoid clinic travel burdens.
Hospitals retain the largest institutional footprint; homecare providers are gaining share fastest.
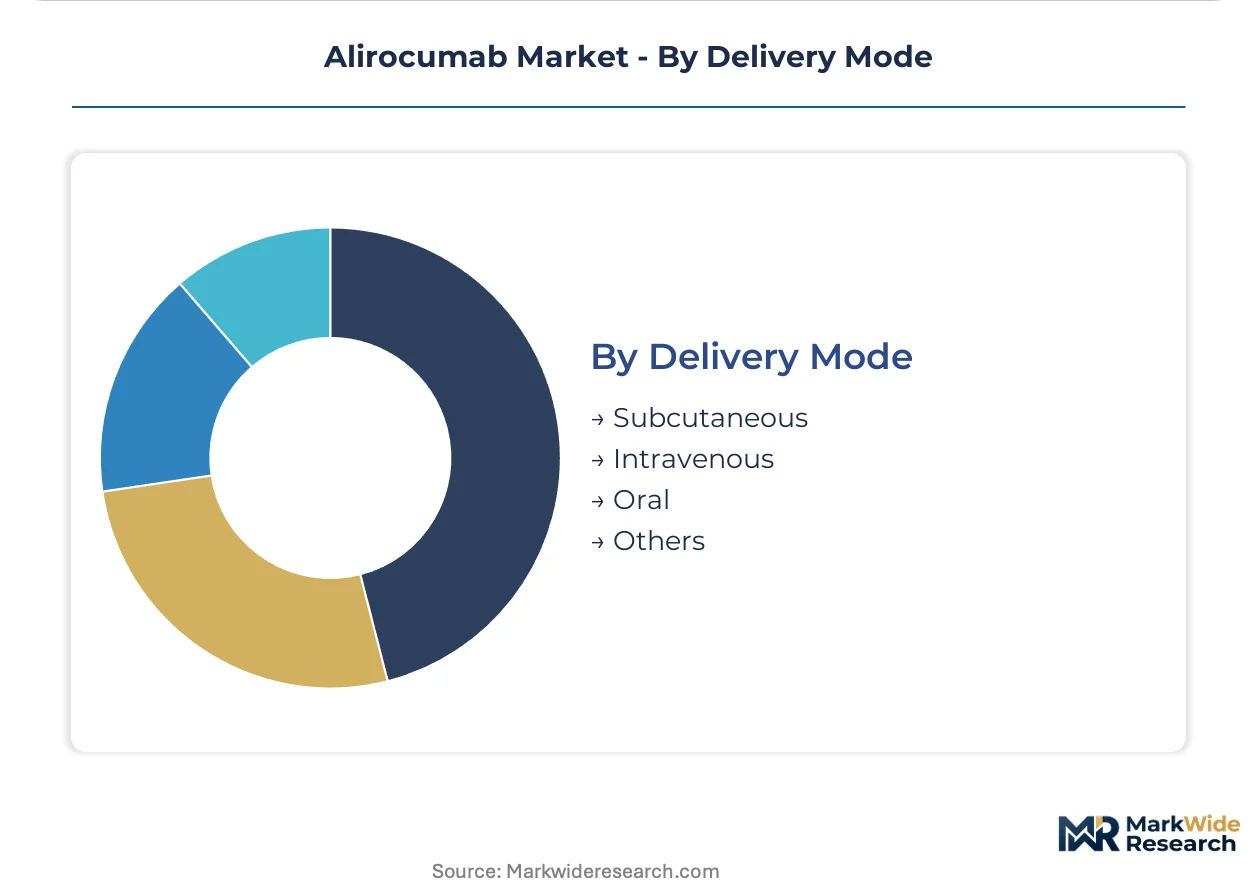
Delivery Mode:
Volume concentration favors subcutaneous administration, while margin structures differ across routes requiring specialized handling or monitoring capabilities.
- Subcutaneous:Abdominal or thigh self-injection every two weeks or monthly per dosing regimen. Patient training requirements and injection site rotation protocols dominate the clinical support model for this delivery mode.
- Intravenous:Hospital-administered infusion reserved for acute settings or patients unable to tolerate subcutaneous delivery due to bleeding disorders or severe injection site reactions.
- Oral:Not applicable for monoclonal antibody biologics due to gastrointestinal degradation; included as placeholder for future small-molecule PCSK9 inhibitors in development pipelines.
- Others:Investigational depot formulations and implantable devices in preclinical stages seeking to extend dosing intervals beyond current limits.
Subcutaneous delivery dominates current utilization; intravenous maintains niche presence in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive biologics. FDA-regulated manufacturing clusters in Massachusetts and North Carolina anchor North American supply security. Japan's Kansai International Airport biopharma zone accelerates Asia-Pacific access to monoclonal antibody therapies.
United States
Medicare Advantage cardiac bundled payment contracts drive PCSK9 inhibitor utilization in Florida and Texas metropolitan areas. The Inflation Reduction Act's biologic exclusion timeline preserves pricing flexibility through 2032. Boston's Longwood Medical Area anchors lipid management protocol standardization across academic medical centers.
Germany
Techniker Krankenkasse and other statutory health insurers maintain open formulary access for familial hypercholesterolemia patients. The country's national pharmaceutical regulator enforces EMA MDR-aligned post-market surveillance for combination auto-injector products. North Rhine-Westphalia's hospital networks concentrate tertiary lipid clinic capacity.
France
Assurance Maladie reimbursement frameworks support broad biologic access for statin-intolerant populations. ANSM pharmacovigilance requirements demand robust real-world evidence infrastructure from market entrants. The Lyon biocluster hosts expanded fill-finish capacity for monoclonal antibody production serving Southern European markets.
Japan
PMDA's Sakigake designation pathway accelerates cardiovascular outcome trial review timelines for innovative lipid therapies. METI's healthcare export initiatives promote Japanese clinical data acceptance across ASEAN markets. Osaka's pharmaceutical manufacturing zone concentrates pen device engineering expertise for patient self-administration formats.
United Kingdom
NICE technology appraisals mandate cost-effectiveness thresholds that shape PCSK9 inhibitor prescribing in heterozygous familial hypercholesterolemia. MHRA post-Brexit regulatory autonomy enables streamlined approval pathways for novel device formats. London's cardiovascular research institutes anchor real-world evidence generation for value-based contracts.
Alirocumab Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The PCSK9 inhibitor market consolidates around two approved antibody platforms with differentiated dosing profiles and device engineering. Three strategic archetypes dominate: originator biopharmaceuticals with integrated manufacturing networks, specialty pharmaceutical distributors managing cold chain logistics, and connected health platform developers layering adherence technologies atop injection devices. Competitive moves center on site-neutral channel capture and pediatric indication expansion.
Among originator biopharmaceuticals, Sanofi and Regeneron Pharmaceuticals occupy positions exemplifying the integrated development-and-commercialization archetype, with Sanofi's European manufacturing footprint complementing Regeneron's R&D engine. Amgen Inc. represents the rival platform strategy, forcing differentiation through dosing convenience and real-world evidence generation. These three anchors structure competitive dynamics across reimbursement negotiations, formulary positioning, and device engineering investment priorities.
| Leading Market Players |
|---|
| Sanofi |
| Regeneron Pharmaceuticals |
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| AstraZeneca |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Others |
Pricing and Supply Chain Analysis
European fill-finish overcapacity for monoclonal antibodies is reshaping supplier negotiations and pricing postures across the PCSK9 inhibitor landscape, with contract manufacturers competing aggressively for long-term offtake commitments from originators.
Pricing Analysis
Volume-discount tiering structures separate hospital system GPO contracts from Medicare Advantage carve-outs and cash-pay specialty pharmacy channels. Pricing stratifies across connected auto-injector bundles, standard pre-filled syringes, and institutional vial formats based on after-sales service intensity and adherence data capture. Cost compression in the standard syringe tier is intensifying because statin generic substitution crowds payer prior-authorization bandwidth. Hospital procurement committees exhibit the highest price sensitivity due to site-neutral payment erosion, while integrated delivery networks with cardiac bundled contracts show relative inelasticity for outcomes-linked device formats.
Supply Chain Analysis
European contract manufacturing organizations hold dominant monoclonal antibody finishing capacity, with France and Germany anchoring sterile production clusters for pen device assembly. Raw material dependencies center on Chinese-sourced recombinant cell culture media, German-engineered needle-gauge components, and US-origin bioprocessing resins. Single-source vulnerability concentrates in lyophilization capacity for temperature-stable formulations. Distribution runs through specialty pharmacy networks with cold chain IoT monitoring, bypassing traditional wholesale channels for patient-direct home delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as oral small-molecule PCSK9 inhibitors advance through clinical pipelines, threatening to displace injectable biologics in statin-intolerant populations.
For Market Incumbents: Harden formulary positioning through backward integration into fill-finish capacity in the Lyon biocluster, securing supply continuity against European manufacturing bottlenecks. Deepen vertical control over connected device engineering in Osaka's pharmaceutical manufacturing zone to differentiate on adherence data capture. Lock in long-term offtake agreements with specialty pharmacy networks before oral substitute entry erodes injection volumes. For New Entrants and Emerging Players: Pediatric heterozygous familial hypercholesterolemia in tertiary referral centers represents the most penetrable entry point, with no approved oral alternatives and concentrated prescriber networks. Homecare nursing services in Florida and Texas metropolitan areas offer channel access under site-neutral payment migration. Pursue go-to-market partnerships with remote patient monitoring platforms to bundle adherence technologies and secure value-based contract eligibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected health platform developers layering adherence technologies atop injection devices, with sticky provider relationships and outcomes-contingent contract structures. Target acquisition archetypes include mid-market auto-injector engineering specialists with FDA combination product pathways and real-world evidence infrastructure deployable across cardiovascular portfolios. Watch for inflection in CMS coverage determination documents signaling surrogate endpoint acceptance thresholds for pediatric indications.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | Heterozygous familial hypercholesterolemia in adolescents opens statin-intolerant populations with no oral alternatives. |
| Connected Device Engineering | Bluetooth-enabled auto-injectors transmitting adherence data to EHRs secure value-based contract eligibility with Medicare Advantage plans. |
| Homecare Channel Penetration | Specialty pharmacy networks capture administration volume as site-neutral payment reforms erode hospital outpatient margins. |
| Fill-Finish Capacity Expansion | European monoclonal antibody finishing investments in Lyon and North Rhine-Westphalia reduce geographic supply vulnerability. |
| Real-World Evidence Infrastructure | EMA MDR-aligned pharmacovigilance systems enable post-market surveillance for combination product line extensions. |
Research Methodology
Initial hypotheses were tested against primary input from formulary directors, cardiology department heads, specialty pharmacy operations executives, and payer access specialists, then refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling triangulated with top-down market sizing across dosage forms, administration routes, and patient population segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning therapy area, product type, end user channel, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated IRA Medicare price negotiation exclusion timelines and biosimilar entry probability assessments.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, biologic cold chain logistics costs, or cardiovascular outcomes trial timelines would shift the trajectory. Forecasts reflect documented assumptions on patient adherence persistence and prior-authorization approval rates. Quarterly review of CMS coverage determination documents and EMA MDR guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Hyperphosphatemia Drugs Market