
 Middle East and Africa Pharmaceutical Glass Packaging Market | 2026-2036
Middle East and Africa Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Glass Packaging Market Insights
ISO 15378 certification for primary packaging materials is redrawing the competitive map across the Middle East and Africa pharmaceutical glass sector. Arab Pharmaceutical Glass Company S.A.E. leverages its Egyptian manufacturing base to serve North African injectable demand, while Schott AG sustains premium borosilicate supply relationships with Gulf-based biopharma customers. Gerresheimer AG differentiates through molded glass capacity positioned for vaccine packaging tenders.
Pharmaceutical glass packaging denotes containers fabricated from borosilicate or soda-lime glass, engineered to meet chemical durability standards USP Type I through III and thermal shock resistance parameters exceeding 42°C for autoclave sterilization cycles, serving as barrier systems for moisture-sensitive and oxygen-sensitive drug formulations. Vials occupy the dominant volume position in injectables distribution across the region, while sterile single-use packaging configurations capture expanding margin pools as aseptic fill-finish outsourcing accelerates in the Gulf. Vaccine packaging applications demonstrate the steepest trajectory, driven by regional immunization program expansion and cold-chain infrastructure investment.
Saudi Arabia's SFDA serialization requirements and South Africa's SAHPRA good manufacturing practice enforcement are elevating barrier-performance specifications for imported and locally produced glass containers. Egypt's national drug authority applies harmonized standards with WHO prequalification pathways, tightening market access for uncertified suppliers. Stakeholders must monitor regulatory convergence between Gulf national authorities and the African Medicines Agency as this alignment will determine which manufacturing qualifications transfer across jurisdictions.
Market Dynamics
Serialization mandates from Saudi Arabia's SFDA and Egypt's harmonized WHO prequalification pathways are compressing supplier qualification timelines while elevating barrier-performance specifications for borosilicate and soda-lime containers across the region.
Growth Catalysts
- Vaccine cold-chain expansion:Regional immunization program scale-up is accelerating demand for thermally resistant glass vials capable of withstanding autoclave sterilization cycles exceeding 42°C temperature differentials.
- SFDA serialization enforcement:Saudi Arabia's tightened track-and-trace mandates for parenteral drugs are forcing injectable biologics manufacturers to upgrade primary packaging materials to ISO 15378-certified glass containers.
- Aseptic fill-finish outsourcing:Gulf-based contract manufacturing organizations are scaling sterile single-use packaging procurement as biopharma companies divest in-house finishing capabilities.
Market Restraints
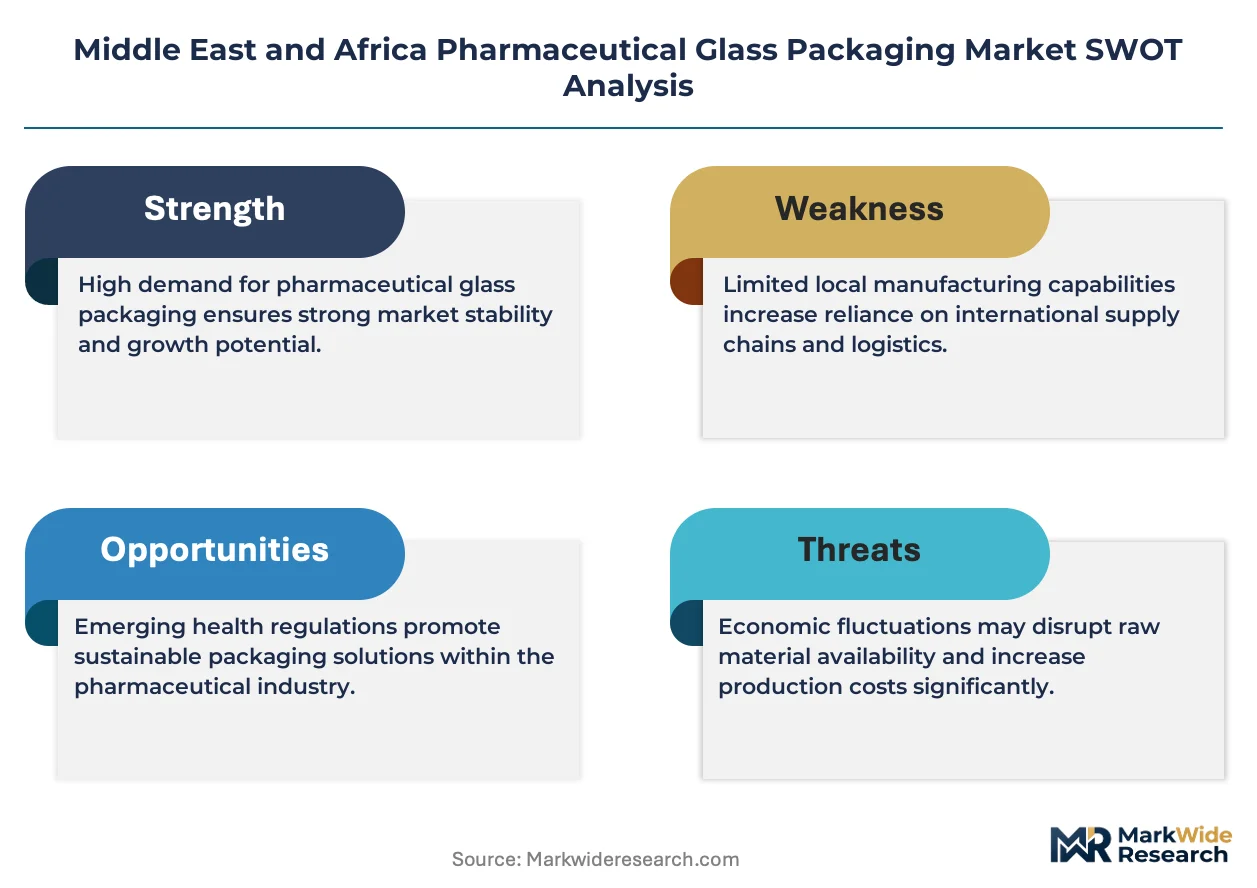
- Borosilicate raw material concentration:Premium-grade tubing supply concentrates among European and Asian specialty glass manufacturers, exposing regional converters to currency volatility and extended lead times.
- Energy cost intensity:Soda-lime glass production requires sustained high-temperature furnace operations, rendering Egyptian and Gulf-based manufacturers vulnerable to natural gas price fluctuations.
- Plastic polymer substitution:Cyclic olefin polymers and advanced polypropylene resins are capturing share in non-parenteral applications where moisture barrier requirements permit flexible primary packaging.
Strategic Opportunities
- North African contract packaging corridor:Egypt's Arab Pharmaceutical Glass Company manufacturing base positions suppliers to serve unmet sterile container demand across Libya, Sudan, and East African Community markets.
- African Medicines Agency convergence:Regulatory alignment between Gulf national authorities and the AMA creates pathway for ISO 15378 certification reciprocity, reducing re-qualification costs for multi-jurisdiction suppliers.
- Sterile single-use configuration innovation:Pre-sterilized ready-to-fill vial systems combining borosilicate glass with polymer closure components address aseptic processing bottlenecks in Gulf biopharma fill-finish operations.
Industry Challenges
- ISO 15378 certification timelines:Primary packaging material qualification cycles extend 18-24 months, delaying market entry for new regional glass converters seeking WHO prequalification pathway access.
- Autoclave thermal shock engineering:Container design must reconcile USP Type I chemical durability with rapid temperature transition performance, requiring specialized furnace process control expertise scarce in regional labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Glass Packaging Market |
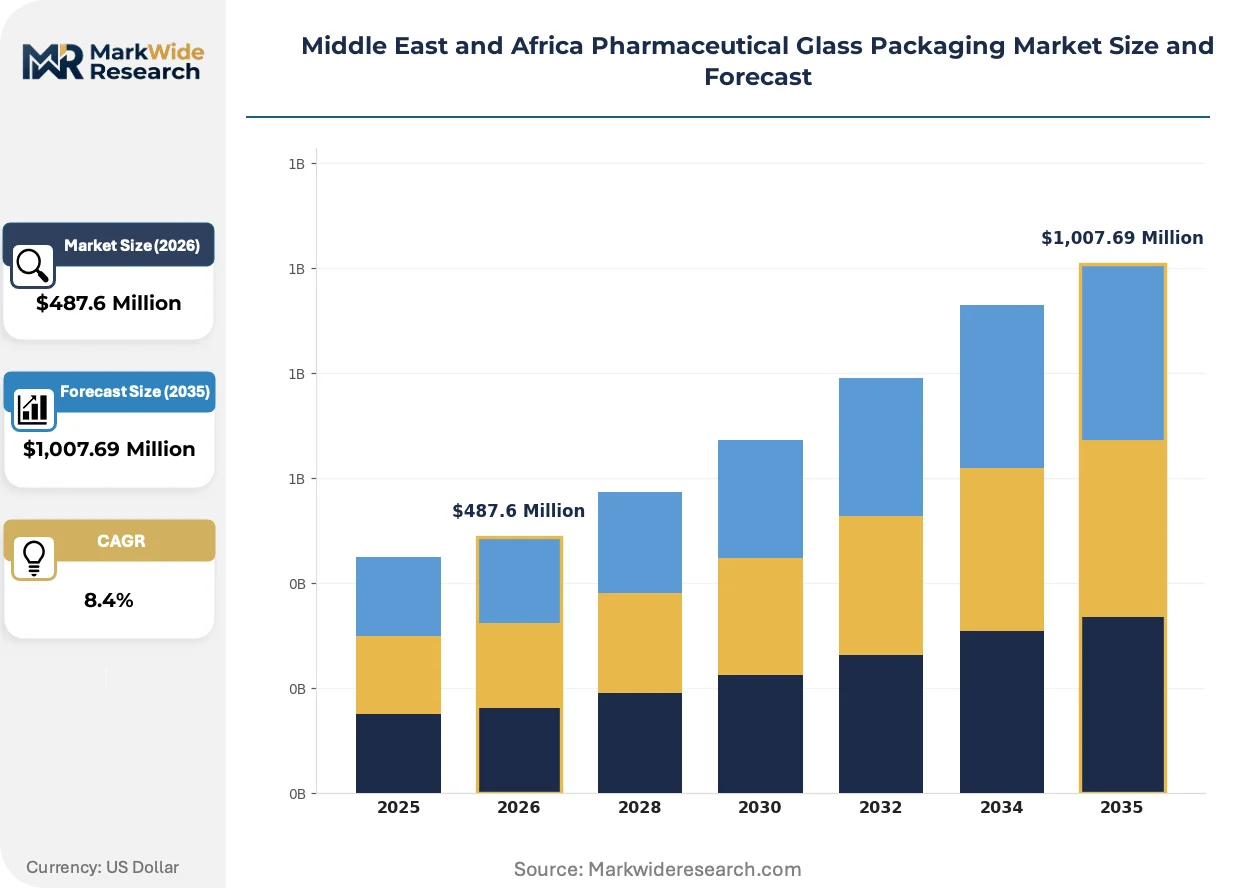
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Bottles, Jars Application: Injectables, Oral Solutions, Ocular Products, Vaccine Packaging End User: Pharmaceutical Manufacturers, Contract Packaging, Research Laboratories, Hospitals Packaging Type: Reusable, Single-Use, Sterile, Non-Sterile |
| Companies Covered | Arab Pharmaceutical Glass Company S.A.E. (APG), Middle East Glass Manufacturing Company SAE, Ardagh Group, RAK Ghani Glass LLC, Pharmaceutical Solutions Industry Ltd, Schott AG, Gerresheimer AG, SGD Pharma, Bormioli Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Glass Packaging Market Trends and Innovations
Container miniaturization, regulatory serialization integration, and procurement consolidation around certified suppliers are compressing the competitive set while elevating technical performance thresholds for market participation.
Ready-to-use nested vial systems combining pre-sterilized borosilicate glass with integrated closure components are miniaturizing aseptic fill-finish line changeover requirements. Gulf-based biologics contract manufacturers are adopting these configurations to reduce line clearance validation burdens. The technology is compressing batch setup timelines from hours to minutes, enabling higher utilization rates on high-value parenteral filling equipment.
SAHPRA's good manufacturing practice enforcement in South Africa is mandating barrier-performance documentation for imported glass containers equivalent to domestic production standards. This regulatory friction is disqualifying uncertified Asian suppliers from tender participation. Injectable drug manufacturers are responding by consolidating procurement around Schott AG and Gerresheimer AG relationships with established SAHPRA master file documentation.
Biopharma procurement functions are consolidating supplier panels from fragmented regional converters toward dual-source arrangements with ISO 15378-certified manufacturers. Egypt's contract packaging corridor is capturing volume as European suppliers face capacity constraints. This concentration is most visible in Saudi Arabia, where SFDA serialization deadlines have compressed qualification windows below the threshold for uncertified market entrants.
Middle East and Africa Pharmaceutical Glass Packaging Market Segmentation
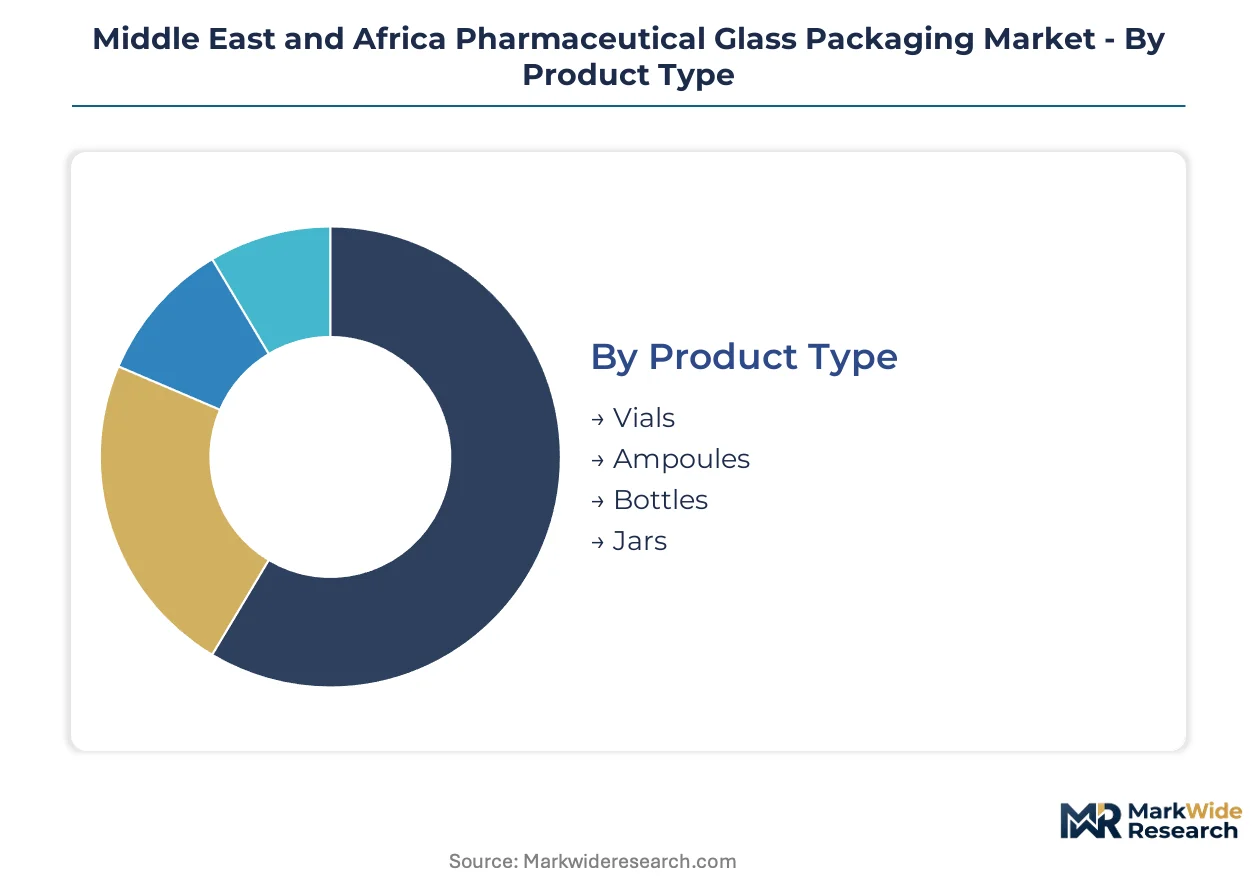
Pharmaceutical glass packaging segmentation in the Middle East and Africa reflects divergent supply chain economics across sterile parenteral applications versus non-sterile oral formats. Channel configuration varies sharply between Gulf-based biologics manufacturers demanding ISO 15378-certified primary packaging and North African oral solid dose producers sourcing commoditized soda-lime containers.
Product Type:
Glass container geometries flow through distinct procurement channels—vials and ampoules route through specialized sterile distributors serving injectable manufacturers, while bottles and jars move through general pharmaceutical packaging wholesalers supplying oral dosage form producers.
- Vials:Cylindrical borosilicate or soda-lime containers engineered for parenteral drug stability, typically 2ml to 100ml nominal capacity. Demand concentrates in Saudi Arabia's injectable biologics corridor, where SFDA serialization mandates are forcing upgrades to USP Type I chemically resistant glass. Gulf contract manufacturers now specify nested ready-to-fill vial systems to compress aseptic line changeover timelines.
- Ampoules:Single-dose glass containers formed by flame-sealing tubular glass at both ends, designed for immediate use without additional closure components. Egypt's Arab Pharmaceutical Glass Company manufacturing base is scaling ampoule furnace capacity to serve unmet North African demand for generic injectable packaging, though autoclave thermal shock engineering expertise remains concentrated among European suppliers.
- Bottles:Wide-mouth soda-lime containers for oral liquid and solid dosage forms, typically 30ml to 500ml capacity with screw-neck finishes. These move through established pharmaceutical packaging distribution networks serving Egypt's domestic formulation sector.
- Jars:Large-format glass containers for bulk pharmaceutical ingredients and semi-solid preparations. Procurement runs through industrial chemical packaging channels rather than dedicated pharmaceutical distributors.
Vials dominate installed base across the region's parenteral manufacturing footprint. Ampoules are where expansion concentrates as Egyptian and Gulf-based generic injectable producers seek cost-competitive single-dose alternatives to multi-dose vial systems.
Application:
Application segmentation tracks the regulatory intensity gradient—injectables and vaccines face the strictest barrier-performance documentation requirements, while oral solutions and ocular products operate under comparatively lighter primary packaging scrutiny.
- Injectables:Parenteral drug formulations requiring absolute container integrity against moisture and oxygen ingress. Demand clusters in Saudi Arabia's biologics manufacturing zones and South Africa's generic sterile production corridor, with SAHPRA enforcement disqualifying uncertified Asian suppliers from tender participation.
- Vaccine Packaging:Thermally resistant borosilicate containers capable of withstanding autoclave sterilization cycles with temperature differentials exceeding 42°C. Regional immunization program expansion across the Gulf and East African Community is accelerating procurement of pre-sterilized ready-to-fill configurations.
- Oral Solutions:Liquid dosage forms packaged in amber or flint soda-lime bottles for light-sensitive and non-sensitive formulations respectively. Egyptian contract packaging corridors serve this segment with lower certification barriers than parenteral applications.
- Ocular Products:Sterile ophthalmic preparations requiring container closure integrity against microbial contamination. Volume remains constrained by limited regional ophthalmic manufacturing capacity outside South Africa and Egypt.
Injectables command the premium pricing tier through ISO 15378 certification requirements. Vaccine packaging is gaining share fastest as cold-chain infrastructure investment unlocks regional immunization manufacturing capabilities.
End User:
End user segmentation reveals procurement consolidation patterns—pharmaceutical manufacturers are consolidating supplier panels while contract packaging organizations capture outsourcing volume from divested in-house finishing operations.
- Pharmaceutical Manufacturers:Integrated drug developers and generic producers sourcing primary packaging for captive fill-finish operations. Saudi Arabia's SFDA serialization deadlines have compressed their qualification windows below thresholds for uncertified regional converters.
- Contract Packaging:Third-party sterile fill-finish providers scaling procurement on behalf of biopharma clients divesting internal capabilities. Egypt's contract packaging corridor is capturing disproportionate volume as European suppliers face capacity constraints.
- Research Laboratories:Clinical trial material packaging demand from academic and commercial R&D operations. Procurement volumes remain fragmented across numerous small-batch requirements.
- Hospitals:Institutional pharmacy compounding operations requiring small-lot sterile container supply. Channel access limited by distributor minimum order quantities.
Pharmaceutical manufacturers anchor procurement volume through established direct supplier relationships. Contract packaging is where supplier switching concentrates as outsourcing accelerates across the Gulf.
Packaging Type:
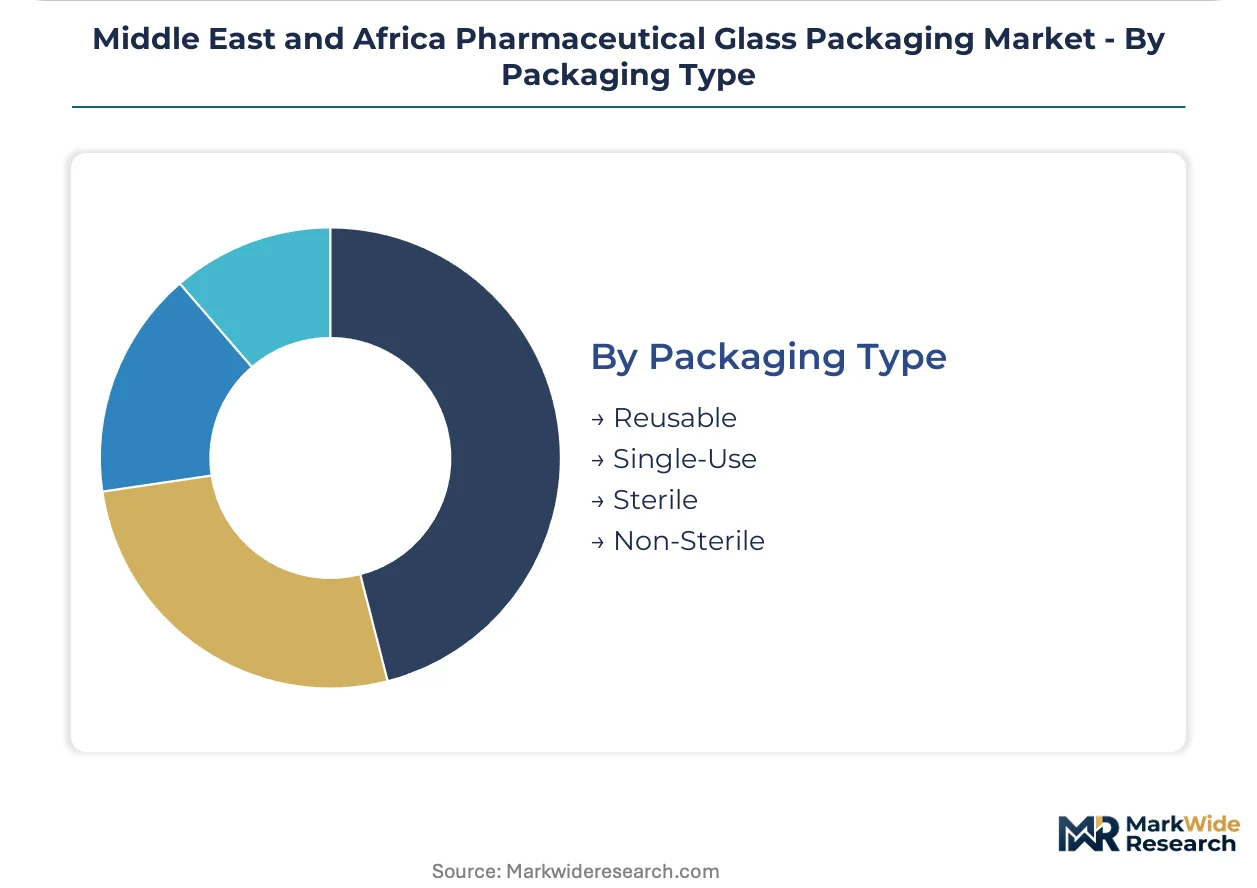
Packaging type segmentation maps to sterilization responsibility allocation—sterile and single-use configurations shift validation burden upstream to glass converters, while reusable and non-sterile formats retain downstream processing requirements with end users.
- Sterile:Pre-sterilized containers delivered with documented barrier-performance certification per ISO 15378. Gulf-based biologics manufacturers are mandating this configuration to eliminate in-house sterilization validation costs.
- Single-Use:Disposable containers designed for one-time drug contact without reclamation or reprocessing. Ready-to-use nested vial systems combining borosilicate glass with integrated polymer closures are miniaturizing aseptic fill-finish line changeover requirements from hours to minutes.
- Reusable:Multi-trip glass containers for bulk pharmaceutical ingredient storage and transport. Demand concentrates in active pharmaceutical ingredient manufacturing clusters outside the region's core pharmaceutical packaging demand centers.
- Non-Sterile:Containers requiring terminal sterilization or aseptic processing by the end user. Oral solid dose manufacturers in Egypt and North Africa favor this cost-minimized configuration where regulatory pathways permit.
Non-sterile configurations dominate installed base across oral dosage manufacturing. Sterile single-use is climbing the fastest as aseptic fill-finish outsourcing accelerates and Gulf regulators tighten barrier-performance documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable biologics manufacturers across the Gulf Cooperation Council and North African contract packaging corridors anchor procurement volume. SFDA serialization mandates and WHO prequalification pathways compress supplier qualification timelines while elevating barrier-performance specifications.
Saudi Arabia
SFDA track-and-trace enforcement for parenteral drugs forces upgrades to ISO 15378-certified borosilicate containers. Riyadh's biologics manufacturing zone concentrates demand for pre-sterilized ready-to-fill vial systems. Local injectable producers are consolidating procurement around established European supplier relationships with documented master files.
Egypt
Generic injectable expansion and contract packaging outsourcing drive ampoule and vial demand across North Africa. The national drug authority applies harmonized WHO prequalification standards, tightening market access. Arab Pharmaceutical Glass Company's manufacturing base in Cairo serves unmet sterile container demand across Libya, Sudan, and East African Community markets.
United Arab Emirates
Dubai's pharmaceutical logistics hub and Jebel Ali free zone operations position the emirate as a re-export gateway for Gulf biopharma packaging. MOHAP alignment with international GMP standards elevates import documentation requirements. Contract manufacturers in the Dubai Science Park cluster are scaling sterile single-use packaging procurement as biopharma clients divest in-house finishing capabilities.
South Africa
SAHPRA good manufacturing practice enforcement mandates barrier-performance documentation equivalent to domestic production standards for imported glass containers. Cape Town and Johannesburg pharmaceutical manufacturing corridors disqualify uncertified Asian suppliers from tender participation. Injectable drug manufacturers consolidate procurement around suppliers with established SAHPRA master file documentation.
Israel
Advanced therapeutics manufacturing and biotech R&D operations generate specialized clinical trial material packaging demand. The national pharmaceutical regulator applies stringent container closure integrity standards for parenteral formulations. Tel Aviv-area biopharma clusters source nested ready-to-use vial systems to minimize aseptic processing validation burdens.
Middle East and Africa Pharmaceutical Glass Packaging Market Competitive Landscape
Player mix skews toward European specialty glass manufacturers with established certification credentials alongside regional converters leveraging geographic proximity to North African and Gulf demand centers. Market structure concentrates around ISO 15378-certified suppliers capable of documenting barrier-performance for SFDA and SAHPRA compliance. Three archetypes dominate: European premium borosilicate tubing suppliers, North African integrated glass converters, and Gulf-based distribution-focused intermediaries. Competitive moves center on capacity expansion in Egyptian manufacturing corridors and strategic partnerships bridging European technical expertise with regional market access.
Among European specialty glass manufacturers, Schott AG and Gerresheimer AG exemplify the certification-driven premium tier. Schott AG represents the established borosilicate tubing supplier archetype with documented master files across multiple Gulf and African regulatory jurisdictions. Gerresheimer AG occupies a position emphasizing molded glass capacity and vaccine packaging configurations. Arab Pharmaceutical Glass Company S.A.E. anchors the regional converter archetype, leveraging Egyptian manufacturing proximity to serve North African and East African Community markets with reduced logistics lead times compared to European competitors.
| Leading Market Players |
|---|
| Arab Pharmaceutical Glass Company S.A.E. (APG) |
| Middle East Glass Manufacturing Company SAE |
| Ardagh Group |
| RAK Ghani Glass LLC |
| Pharmaceutical Solutions Industry Ltd |
| Schott AG |
| Gerresheimer AG |
| SGD Pharma |
| Bormioli Pharma |
| Others |
Pricing and Supply Chain Analysis
Furnace capacity utilization above 85% at Egyptian and Gulf-based converters compresses marginal cost curves and elevates price floors for ISO 15378-certified borosilicate containers. SFDA serialization mandates and SAHPRA barrier-performance enforcement concentrate procurement power among certified suppliers, amplifying their pricing leverage over uncertified regional competitors.
Pricing Analysis
Cost-plus contracts indexed to natural gas futures and specialty glass tubing spot markets dominate procurement arrangements between Gulf biologics manufacturers and European suppliers. Price differentiation hinges on ISO 15378 certification tier and autoclave thermal shock performance grade, with premium USP Type I borosilicate commanding substantial spreads over soda-lime alternatives. Cost compression in standard-grade segments is intensifying as Egyptian converters expand furnace capacity and European suppliers face margin pressure from energy hedging costs. Contract packaging organizations exhibit highest price sensitivity due to pass-through pricing constraints with biopharma clients, while innovator biologics manufacturers prioritize barrier-performance documentation over unit cost.
Supply Chain Analysis
Germany and the Czech Republic anchor premium borosilicate tubing fabrication for Gulf and African pharmaceutical markets. Regional converters in Egypt and Saudi Arabia draw from European tubing feedstock while adding value through forming, annealing, and surface treatment operations. Single-source vulnerability concentrates in specialty glass furnace operations, where technical expertise scarcity limits qualified supplier expansion. Distribution runs through sterile packaging distributors serving injectable manufacturers and general pharmaceutical wholesalers supplying oral dosage producers, with logistics networks clustering around Dubai's Jebel Ali free zone and Cairo's contract packaging corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 15378 certification enforcement across Gulf and African regulatory jurisdictions is compressing supplier qualification timelines below 18-month thresholds, creating structural disruption for uncertified converters while elevating certified incumbents. This regulatory inflection concentrates procurement power and reconfigures competitive positioning across the Middle East and Africa pharmaceutical glass packaging landscape.
For Market Incumbents: Secure master file documentation across SFDA, SAHPRA, and WHO prequalification pathways to preempt regulatory fragmentation. Expand furnace capacity in Egypt's contract packaging corridor to capture volume from European suppliers facing energy cost headwinds. Defensive consolidation around sterile single-use configuration innovation addresses the threat of aseptic fill-finish outsourcing acceleration among Gulf biopharma clients. For New Entrants and Emerging Players: Anchor in North African generic injectable manufacturing clusters where WHO prequalification pathway access unlocks East African Community market expansion. Target ampoule production segments where autoclave thermal shock engineering expertise scarcity has constrained regional supply response. Pursue strategic licensing arrangements with European tubing suppliers to compress ISO 15378 certification timelines below independent qualification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated converters with captive borosilicate forming capabilities and established regulatory master files. Long-term viability over the next decade rests on certification reciprocity expansion between Gulf national authorities and the African Medicines Agency. Monitor regulatory convergence signals as the primary inflection indicator for multi-jurisdiction qualification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Expansion | SFDA serialization mandates disqualify uncertified suppliers from Saudi tender participation. |
| Egyptian Manufacturing Scale-Up | Cairo-based furnace capacity captures volume from European suppliers facing energy hedging costs. |
| Ready-to-Use Vial System Launch | Pre-sterilized nested configurations compress Gulf biopharma line changeover timelines from hours to minutes. |
| Backward Integration into Tubing | Captive borosilicate feedstock supply reduces currency volatility exposure for regional converters. |
| African Medicines Agency Partnership | Regulatory alignment creates pathway for ISO 15378 certification reciprocity across 55 member states. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging procurement managers, sterile fill-finish operations directors, regulatory affairs leads at Gulf biologics manufacturers, and glass converter plant managers across Egypt and Saudi Arabia. Secondary validation drew from SFDA serialization guidance documents, SAHPRA good manufacturing practice circulars, WHO prequalification pathway standards, and trade flow data through Dubai's Jebel Ali free zone. Bottom-up volume modeling triangulated against top-down market sizing derived from pharmaceutical production statistics across the Gulf Cooperation Council and African Union member states.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application intensity, end-user procurement consolidation patterns, and sterilization responsibility allocation. Segmentation dimensions included vial geometry specifications, barrier-performance certification tiers, and regional regulatory cluster alignment. CAGRs were derived from regression analysis against pharmaceutical production growth, immunization program expansion rates, and aseptic fill-finish outsourcing penetration. Industry-specific inputs incorporated autoclave sterilization cycle frequency requirements and cold-chain infrastructure investment pipelines.
Material uncertainties — regulatory timeline slippage, natural gas price volatility, and polymer substitution acceleration in non-parenteral segments — sit outside the modeled envelope. Forecasts reflect assumptions about certification reciprocity expansion and furnace capacity commissioning schedules. Recalibration cycles align with material shifts in SFDA enforcement intensity and African Medicines Agency operationalization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Hermetic Jars Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market