
 Guatemala Container Glass Market | 2026-2036
Guatemala Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Guatemala Container Glass Market Insights
Plastic is pivoting out of premium beverage packaging as aluminum and returnable glass reclaim shelf economics. Vidriera Guatemalteca S.A. anchors production capacity through captive sand reserves near the Pacific coast. Grupo VICAL differentiates via decorative and colored glass capabilities for spirits exporters. Owens-Illinois Central America Operations leverages regional furnace networks to sustain cross-border supply reliability.
Container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow molding, then annealed at 500-600°C to relieve thermal stress for mechanical durability in carbonated filling lines. The bottles segment dominates volume as beer and soft-drink bottlers standardize returnable formats to cut per-use costs. Jars compete in food preservation where hermetic sealing and thermal stability matter. The 500ml-1L capacity band captures the fastest expansion as single-serve beverage formats multiply in urban retail.
Guatemala's Ministry of Environment and Natural Resources enforces solid waste regulations that penalize single-use plastics in municipal jurisdictions, redirecting food-service demand toward glass. The country's national standards body applies BIS-aligned mechanical testing protocols for pressure-rated beverage containers. The central bank's trade finance frameworks influence import timelines for boron and soda ash. Stakeholders must monitor how municipal recycling infrastructure investments alter the cost calculus between returnable glass loops and one-way alternatives.
Market Dynamics
Plastic taxation regimes enforced by Guatemala's Ministry of Environment and Natural Resources are compressing demand for single-use alternatives and forcing beverage bottlers toward returnable glass loops. This regulatory pressure intersects with captive silica sand reserves along the Pacific corridor to reshape procurement economics.
Growth Catalysts
- Escuintla Manufacturing Corridor Concentration:Domestic silica sand beneficiation investments are tightening supply chains and reducing import dependency for soda-lime batch materials. Glass producers now source critical inputs within 150 kilometers of furnace operations.
- Single-Use Plastic Penalties:Municipal solid waste regulations penalizing disposable plastics in Guatemala City and Quetzaltenango redirect food-service demand toward reusable glass vessels. Food retailers face escalating compliance costs for polymer packaging.
- Returnable Format Standardization:Blow-and-blow molding lines optimized for 500ml-1L capacity bands enable beer and soft-drink bottlers to cut per-use packaging costs through multi-trip glass loops.
Market Restraints
- Soda Ash Import Concentration:Guatemala lacks domestic trona or synthetic soda ash production, forcing reliance on US and Mexican suppliers subject to freight rate volatility and customs clearance delays.
- Natural Gas Price Exposure:Furnace operations depend on imported LNG and pipeline gas from Mexico, exposing melting costs to regional energy market fluctuations beyond local control.
- Aluminum Can Substitution:Lightweight metal packaging gains traction in premium beverage segments where logistics efficiency outweighs returnable glass economics.
Strategic Opportunities
- Spirits Export Packaging Differentiation:Decorative and colored glass capabilities address demand from Guatemalan rum and aguardiente exporters seeking premium shelf differentiation in North American and European duty-free channels.
- Quetzaltenango Regional Expansion:Western highland bottling clusters remain underpenetrated by returnable glass infrastructure, presenting greenfield furnace or warehousing investment potential.
- Hermetic Food Preservation Jars:Thermal stability requirements in tropical food processing create pull for widemouth glass containers with vacuum-seal compatibility.
Industry Challenges
- Skilled Furnace Operations Talent:Specialized expertise in combustion optimization and glass conditioning remains scarce in Central American labor markets, constraining capacity utilization rates.
- Cross-Border Boron Logistics:Import timelines for boron-based flux materials fluctuate with central bank trade finance framework adjustments, compressing raw material planning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guatemala Container Glass Market |
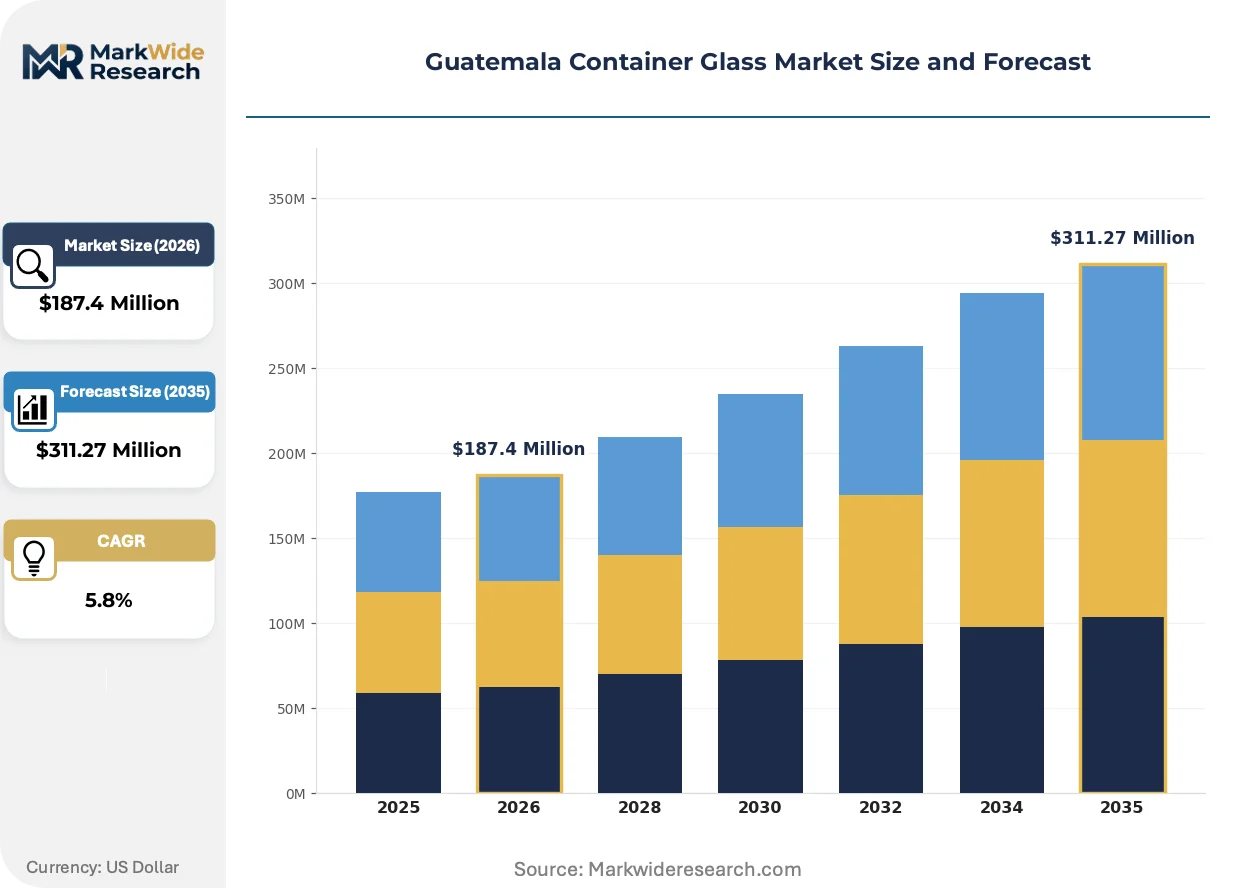
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Capacity: Less than 100ml, 100ml-500ml, 500ml-1L, More than 1L Manufacturing Stage: Raw Material Processing, Molding, Annealing, Quality Inspection |
| Companies Covered | Vidriera Guatemalteca S.A., Grupo VICAL, Owens-Illinois Central America Operations, Empresas Comegua S.A., New High Glass Guatemala S.A., Feemio Group Co., Ltd., Changsha Kotto Glass Industrial Co Ltd, LSS Africa, Grupo Vidriero Centroamericano, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guatemala Container Glass Market Trends and Innovations
Electrification of melting operations and digital process control are converging with regulatory pressure to transform how Guatemalan producers manage thermal energy and quality consistency.
Hybrid electric boosting technology is decentralizing furnace energy profiles by supplementing natural gas combustion with resistive heating elements. Mid-scale producers in the Escuintla corridor adopt this retrofit approach to dampen fuel price volatility. The technology is decentralizing capital requirements for energy efficiency upgrades across smaller production lines previously excluded from major infrastructure investments.
Guatemala's Ministry of Environment and Natural Resources enforces municipal solid waste regulations that penalize single-use plastics in food-service applications. These rules compress polymer packaging viability in urban retail and redirect procurement toward returnable glass formats. Beverage bottlers in Guatemala City respond by extending deposit-return infrastructure and standardizing bottle designs to maximize loop efficiency.
Consolidated purchasing by multinational beverage bottlers is compressing supplier margins and forcing glass producers toward long-term volume contracts with indexed raw material clauses. This procurement concentration shifts negotiation leverage toward buyers with cross-border supply alternatives. The pattern is most visible in carbonated soft-drink bottling where regional furnace networks enable supply redundancy.
Guatemala Container Glass Market Segmentation
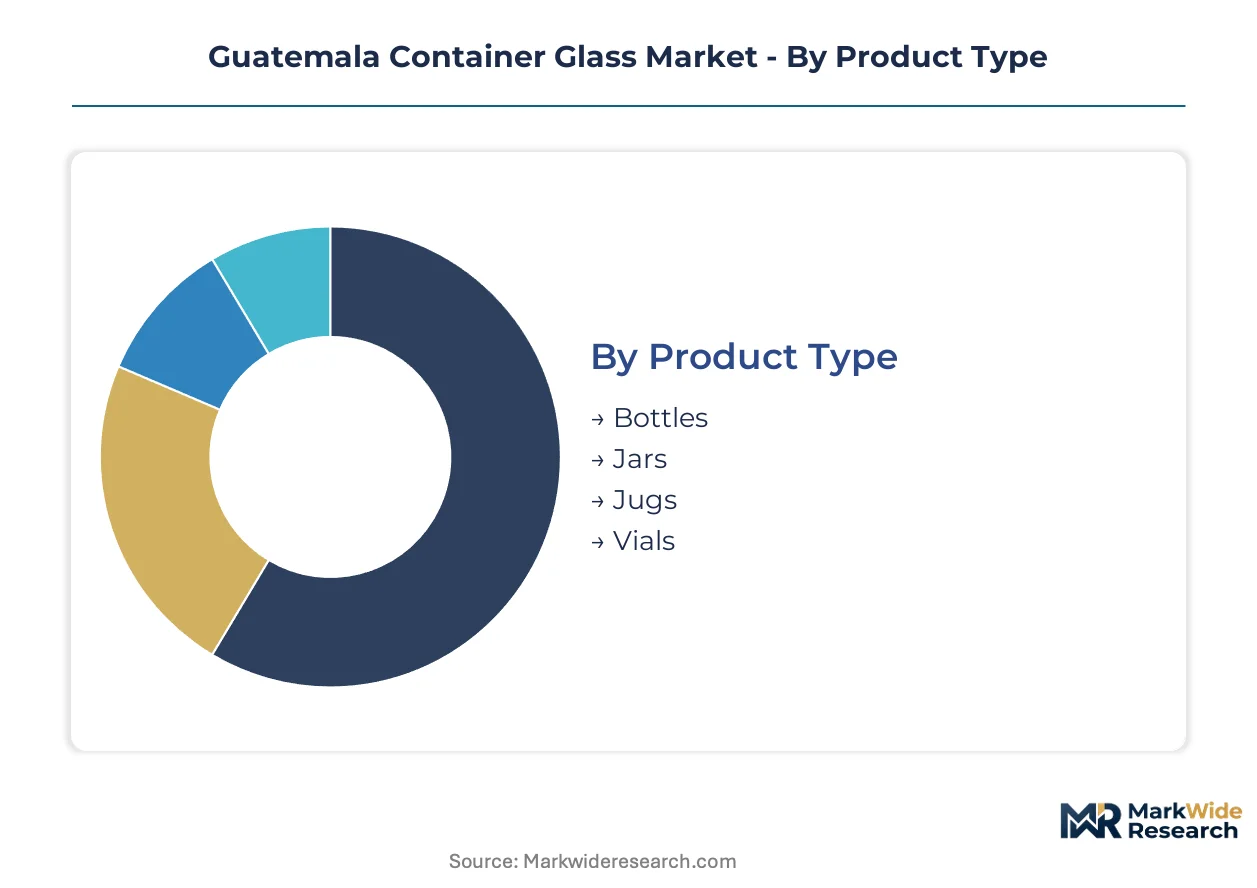
Segmentation in Guatemala's container glass market reveals how supply chain investments concentrate around specific product formats and capacity bands. Procurement patterns diverge sharply between beverage bottlers optimizing returnable loops and food processors requiring hermetic sealing performance.
Product Type:
Escuintla corridor furnaces dedicate melting capacity disproportionately toward formats serving Guatemala's beverage export and domestic bottling clusters.
- Bottles:Soda-lime silica vessels formed through blow-and-blow molding dominate furnace output, with 500ml-1L formats capturing demand from Guatemala City and Quetzaltenango beer and soft-drink bottlers standardizing returnable loops to cut per-use costs under plastic tax pressure.
- Jars:Press-and-blow molded containers with widemouth designs address thermal stability requirements in tropical food processing, where hermetic vacuum-seal compatibility preserves shelf life for Escuintla-region fruit and vegetable processors.
- Jugs:Large-format vessels serve bulk liquid distribution channels with limited returnable infrastructure penetration.
- Vials:Small-diameter pharmaceutical containers require tighter dimensional tolerances than food-grade production lines typically achieve.
Bottles absorb the bulk of installed capacity; jars are expanding most quickly as food preservation demand climbs.
End User:
Cost tier stratification separates multinational beverage bottlers with volume-indexed contracts from smaller food processors purchasing on spot terms.
- Food & Beverage:Carbonated bottlers and tropical food processors generate the majority of order volume, with plastic taxation redirecting food-service procurement toward returnable glass alternatives.
- Pharmaceuticals:Drug manufacturers demand Type III borosilicate-compatible soda-lime containers with chemical durability for liquid formulations, subject to the country's national standards body mechanical testing protocols.
- Cosmetics:Premium spirits exporters in Guatemala seek decorative and colored glass capabilities for rum and aguardiente shelf differentiation in North American duty-free channels.
- Household:General merchandise retailers source standard containers with minimal customization requirements.
Food & Beverage commands the dominant share of furnace scheduling; Cosmetics exhibits the steepest expansion trajectory as export packaging differentiation intensifies.
Capacity:
Volume concentration in the mid-range reflects urban retail single-serve format proliferation and logistics optimization for returnable collection systems.
- Less than 100ml:Miniature formats serve pharmaceutical dosing and cosmetic sampling applications with limited domestic production scale.
- 100ml-500ml:Compact bottles address premium beverage and condiment segments where portability outweighs per-unit packaging economics.
- 500ml-1L:The dominant capacity band captures fastest growth as blow-and-blow molding lines optimize for beer and soft-drink standardization, enabling multi-trip loop efficiency in Guatemala City municipal collection zones.
- More than 1L:Large formats serve family-size beverages and institutional food service with weaker returnable infrastructure economics.
500ml-1L formats lock up the majority of molding line reconfigurations; sub-100ml capacities gain share fastest as pharmaceutical demand diversifies.
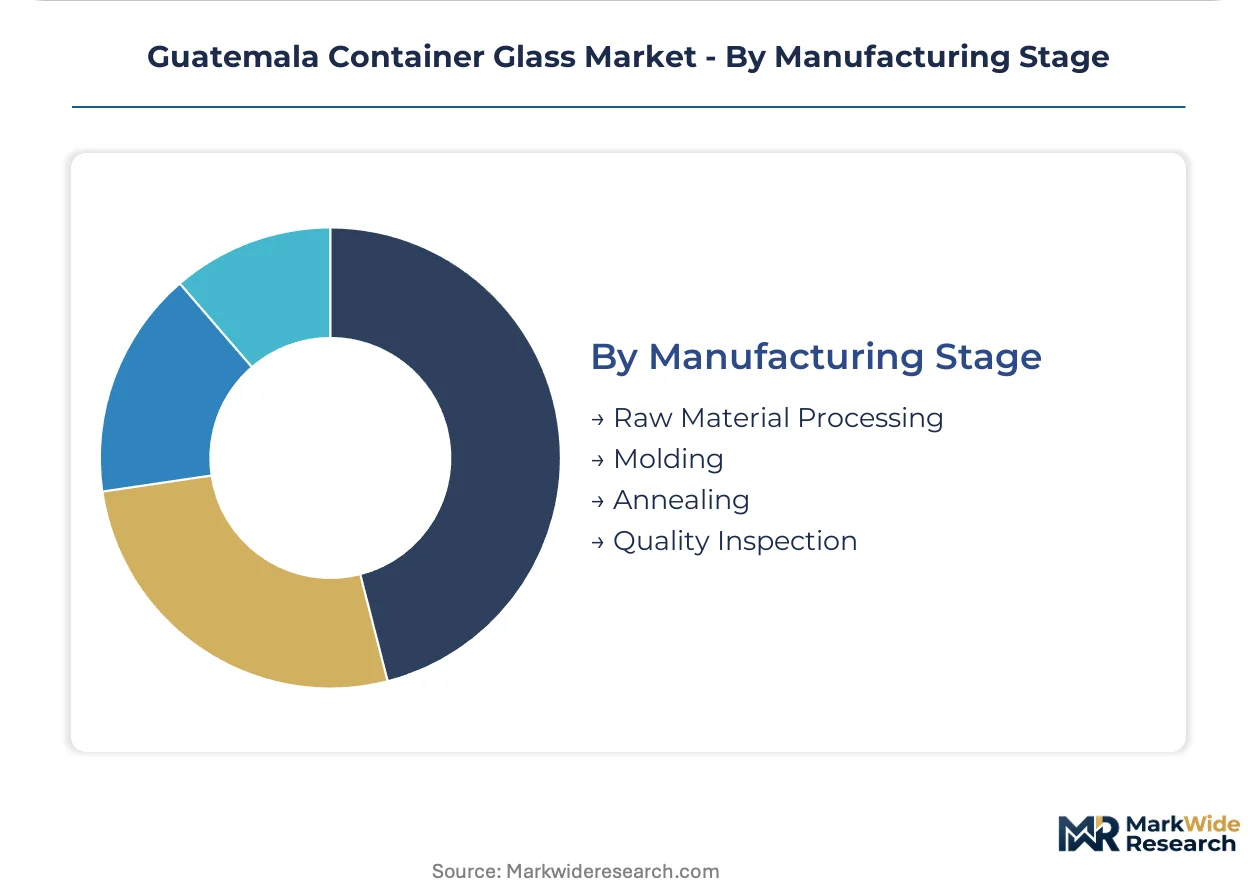
Manufacturing Stage:
Margin capture concentrates upstream where captive silica sand beneficiation tightens supply chains, versus downstream quality inspection where labor arbitrage offers limited differentiation.
- Raw Material Processing:Domestic silica sand beneficiation near the Pacific coast reduces import dependency for soda-lime batch materials, though soda ash and boron flux remain concentrated in US and Mexican supply sources.
- Molding:Blow-and-blow and press-and-blow forming operations determine final vessel geometry, with hybrid electric boosting technology retrofitting mid-scale Escuintla lines to dampen natural gas price exposure.
- Annealing:Controlled cooling between 500-600°C relieves thermal stress to achieve mechanical durability for carbonated filling line pressure ratings.
- Quality Inspection:Automated vision systems and manual checking stations enforce BIS-aligned protocols for pressure-rated beverage containers.
Raw Material Processing anchors capital deployment; Molding is climbing the fastest as electrification retrofits spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for container glass concentrates in Guatemala's Pacific corridor and highland bottling clusters, where silica sand reserves and municipal plastic regulations reshape procurement economics.
Guatemala City Metro
Carbonated beverage bottlers and food-service distributors drive order volume as municipal solid waste regulations penalize single-use plastics. The Ministry of Environment and Natural Resources enforces compliance costs that redirect procurement toward returnable glass loops. Urban collection infrastructure in Guatemala City enables multi-trip bottle standardization across 500ml-1L formats.
Escuintla Department
Silica sand beneficiation investments tighten supply chains for soda-lime batch materials within 150 kilometers of furnace operations. Domestic processing capacity reduces import dependency for critical raw materials. The Pacific coast manufacturing corridor anchors Vidriera Guatemalteca's captive sand reserves and hybrid electric boosting retrofits.
Quetzaltenango
Western highland bottling clusters remain underpenetrated by returnable glass infrastructure, presenting greenfield investment potential for furnace or warehousing operations. Regional beverage distributors face higher logistics costs from distant supply sources. Municipal plastic taxation in Quetzaltenango city limits accelerates food-service demand shifts.
Petén Department
Tourism-driven food-service operations in Flores and Tikal corridor create dispersed demand for hermetic glass food preservation. Weak returnable collection infrastructure favors one-way packaging despite higher per-use costs. The national standards body's BIS-aligned testing protocols apply to all pressure-rated containers regardless of sub-region.
Izabal Caribbean Coast
Port logistics at Santo Tomás de Castilla influence import timelines for boron flux and soda ash from US and Mexican suppliers. Maritime freight rates expose melting cost volatility to regional energy market fluctuations. Limited domestic glass production capacity forces reliance on cross-border supply from Escuintla corridor furnaces.
Guatemala Container Glass Market Competitive Landscape
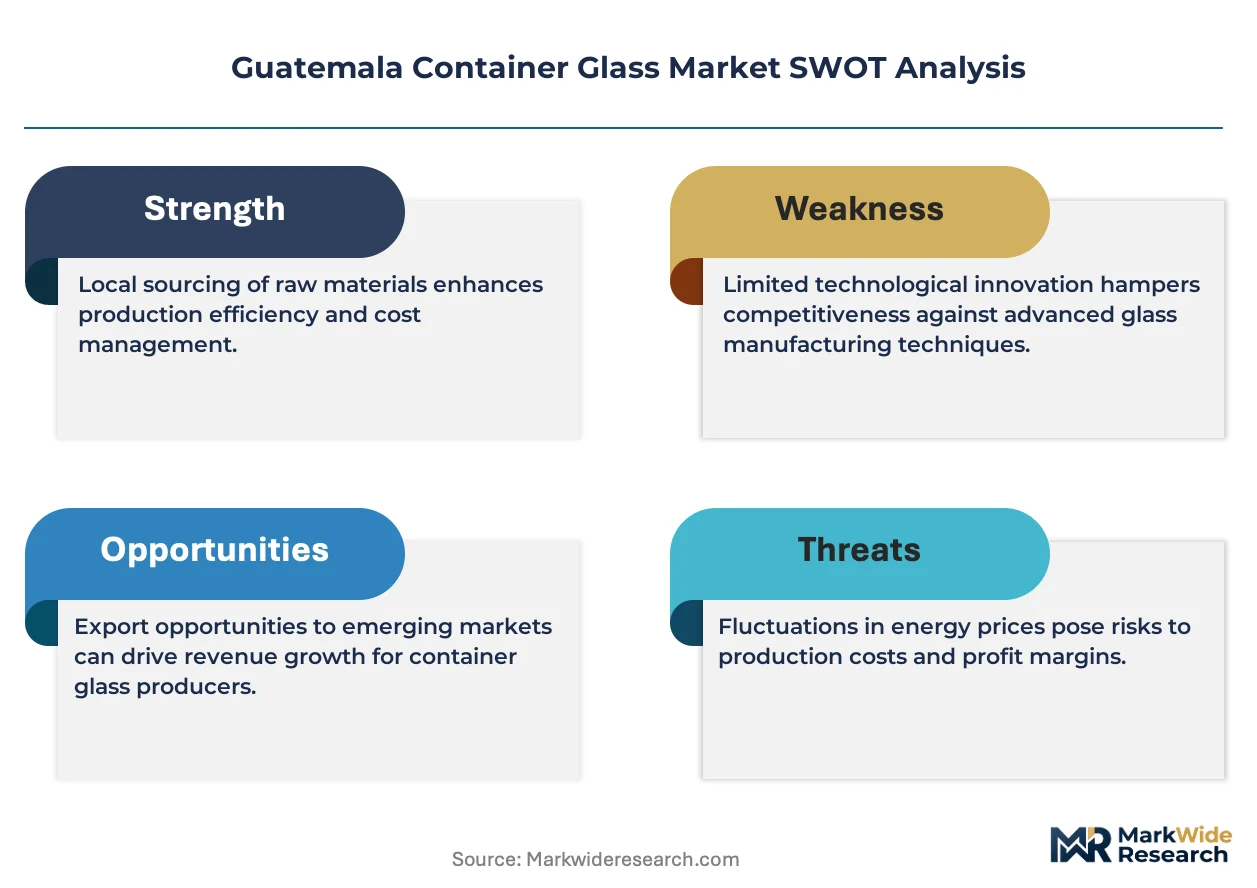
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding raw material advantages and decorative specialists capturing premium export packaging. The market exhibits moderate consolidation around captive silica sand reserves and regional furnace networks. Three archetypes dominate: vertically integrated producers with upstream mineral control, decorative capability specialists serving spirits exporters, and regional network operators leveraging cross-border supply redundancy. Competitive moves center on hybrid electric furnace retrofits and long-term volume contracts with indexed raw material clauses.
Among Guatemala-based producers, Vidriera Guatemalteca S.A. exemplifies the integrated archetype through Pacific coast sand reserves, while Grupo VICAL occupies a position in decorative and colored glass differentiation for export markets. Owens-Illinois Central America Operations represents regional network leverage across Central American furnace infrastructure. These three anchors illustrate how supply chain configuration and capability specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Vidriera Guatemalteca S.A. |
| Grupo VICAL |
| Owens-Illinois Central America Operations |
| Empresas Comegua S.A. |
| New High Glass Guatemala S.A. |
| Feemio Group Co., Ltd. |
| Changsha Kotto Glass Industrial Co Ltd |
| LSS Africa |
| Grupo Vidriero Centroamericano |
| Others |
Pricing and Supply Chain Analysis
Hybrid electric boosting retrofits across Escuintla corridor furnaces are compressing energy cost differentials while redistributing capital efficiency advantages toward mid-scale producers previously locked out of major infrastructure investments. This production-method transition tightens the link between melting technology choices and procurement economics for soda-lime batch materials.
Pricing Analysis
Volume-indexed contracts separate multinational beverage bottlers from spot-purchasing food processors. Three-tier pricing stratifies across premium decorative glass for spirits exporters, standard returnable formats for carbonated bottlers, and economy bulk containers with minimal customization. Cost compression in standard tiers intensifies as consolidated buyer power forces indexed raw material clauses. Food processors exhibit highest price sensitivity due to fragmented purchasing and weak volume leverage.
Supply Chain Analysis
Soda ash supply rests on US and Mexican trona producers, with boron flux drawing from Turkish and South American specialty mineral operations. Silica sand beneficiation localizes around Pacific coast captive reserves, while natural gas feeds from Mexican pipeline networks and LNG import terminals. Single-source vulnerability concentrates in soda ash, where customs clearance delays compress raw material planning windows. Distribution runs through Escuintla-based furnace networks with cross-border redundancy into Quetzaltenango and Caribbean port zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guatemala's container glass sector sits in a furnace electrification transition, where hybrid electric boosting replaces legacy natural gas-dependent melting as the dominant cost-control technology.
For Market Incumbents: Hedge energy price exposure by accelerating hybrid electric retrofits across Escuintla corridor capacity before LNG volatility intensifies. Secure long-term soda ash offtake agreements with US suppliers to buffer customs clearance risk. Lock in multi-year volume contracts with indexed clauses to defend margin position against consolidated beverage bottler procurement leverage. For New Entrants and Emerging Players: The mid-tier price gap between premium decorative exports and economy food-service containers offers white-space entry. Quetzaltenango's underpenetrated returnable infrastructure presents the most penetrable geography. Target hermetic food preservation jars for tropical processors as the go-to-market angle, leveraging weaker incumbent focus on non-beverage segments. For Investors and Strategic Acquirers: Exit pathways concentrate in regional network rollup plays by multinational packaging conglomerates seeking Central American furnace footprints. Long-term viability favors producers with captive silica sand reserves and electrification retrofit completion. Watch municipal plastic taxation enforcement intensity as the inflection signal for returnable glass demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Electric Furnace Retrofit | Resistive heating elements dampen natural gas price volatility for Escuintla corridor producers. |
| Captive Silica Sand Beneficiation | Pacific coast mineral processing tightens supply chains within 150 kilometers of furnace operations. |
| Returnable Format Standardization | 500ml-1L bottle uniformity maximizes multi-trip loop efficiency in Guatemala City collection zones. |
| Decorative Glass Capability Investment | Colored and embossed vessels address premium shelf differentiation for rum and aguardiente exporters. |
| Quetzaltenango Warehousing Expansion | Western highland distribution nodes reduce logistics costs for regional beverage bottlers. |
Research Methodology
Trade statistics from Guatemala's central bank, customs shipment records, and national standards body certification filings formed the secondary backbone. Primary interviews with furnace operations managers, beverage bottler procurement leads, silica sand processing executives, and tropical food processor packaging directors validated demand assumptions. Bottom-up capacity utilization estimates triangulated against top-down trade flow analysis.
Historical trendline analysis tracked installed furnace capacity, raw material import volumes, and returnable bottle circulation rates across the projection horizon. Segmentation modeling spanned product format, capacity band, end-use industry, and regional production cluster. CAGRs derived from weighted average of demand elasticity coefficients and capacity expansion schedules, with natural gas price scenarios and plastic tax enforcement timelines as key forecast inputs.
Underlying measurement precision varies by segment; beverage bottler contract volumes carry tighter precision than dispersed food-service procurement estimates. Forecasts reflect assumptions about municipal regulation enforcement continuity and energy price trajectory stability. Supply disruption in soda ash logistics, unexpected furnace downtime, or aluminum can substitution acceleration in premium segments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
United States Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
India Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Turkey Container Glass Market