
 Turkey Container Glass Market | 2026-2036
Turkey Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Container Glass Market Insights
ISO 9001 quality management certification is unwinding the competitive landscape for smaller molders unable to meet audit cycles. Şişecam Group leverages integrated soda ash mining and furnace operations to dominate domestic float and container output. Ciner Glass sustains cost advantages through captive trona deposits in Anatolia. Gürok Cam Ambalaj specializes in narrow-neck pharmaceutical and cosmetic formats that command premium positioning.
Turkey container glass denotes silica-based amorphous solids formed at temperatures exceeding 1,500°C, typically comprising 70-74% silicon dioxide, 12-16% sodium oxide, and 10-13% calcium oxide, engineered for chemical inertness and impermeability in liquid and solid storage. The material serves primary functions in preserving flavor integrity, blocking UV degradation, and enabling infinite recyclability without quality loss. Beverage bottles anchor volume demand as carbonated soft drink and mineral water brands shift from PET amid consumer preference for perceived purity. Pharmaceutical vials capture margin concentration due to stringent USP Type I borosilicate requirements and limited qualified domestic supply. Food containers occupy a mature trajectory where standardization limits differentiation but scale economics protect incumbent positions.
Turkish Standards Institution (TSE) glass packaging norms and the Ministry of Environment's packaging waste regulation shape compliance costs for domestic producers while aligning export-bound output with EU REACH and CE marking prerequisites. BIS-equivalent conformity assessments for pharmaceutical glass imports from India create asymmetric compliance burdens that local molders exploit. Stakeholders must monitor furnace fuel economics amid volatile natural gas pricing and assess whether hybrid oxy-fuel conversions justify capital deployment against carbon border adjustment risks.
Market Dynamics
Extended producer responsibility mandates from the Turkish Ministry of Environment are compressing recovery timelines and forcing furnace operators to reconfigure batch chemistry for higher cullet ratios. This regulatory pressure is reshaping capital allocation across the Marmara production corridor.
Growth Catalysts
- Carbonated beverage brand migration:Mineral water and soft drink bottlers in Anatolia are expanding amber and flint glass orders as consumer preference shifts from PET toward perceived purity.
- TSE packaging waste regulation alignment:Domestic conformity assessments now streamline EU REACH and CE marking prerequisites for export-bound output, reducing technical barriers to Balkan and Middle Eastern markets.
- Captive trona and soda ash deposits:Integrated raw material control across central Anatolia insulates major producers from imported flux price volatility.
Market Restraints
- Natural gas furnace economics:Volatile pipeline pricing from Russia and Azerbaijan compresses margin visibility for batch-operated furnaces running 24/7 melt cycles.
- BIS-equivalent pharmaceutical assessments:Import conformity requirements for Indian borosilicate vials create asymmetric compliance burdens that limit domestic premium positioning.
- PET substitution in lightweight formats:Polyethylene terephthalate retains cost advantage in sub-500ml beverage applications where transport economics dominate.
Strategic Opportunities
- Aegean coastal export corridor expansion:Izmir port infrastructure investments enable direct Mediterranean shipping routes to North African beverage bottlers seeking European-standard packaging.
- Hybrid oxy-fuel furnace conversion:Oxygen-enriched combustion technology reduces natural gas intensity by 15-20% while positioning operators for prospective EU carbon border adjustment mechanisms.
- Narrow-neck cosmetic and pharmaceutical formats:USP Type I borosilicate demand from Istanbul-based contract manufacturers outstrips qualified domestic supply.
Industry Challenges
- ISO 9001 audit cycle compliance:Smaller molders face exclusion from beverage bottler approved vendor lists as quality management certification becomes a non-negotiable procurement filter.
- Furnace rebuild capex intensity:10-15 year refractory lifecycles demand 50-80 million dollar capital commitments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Container Glass Market |
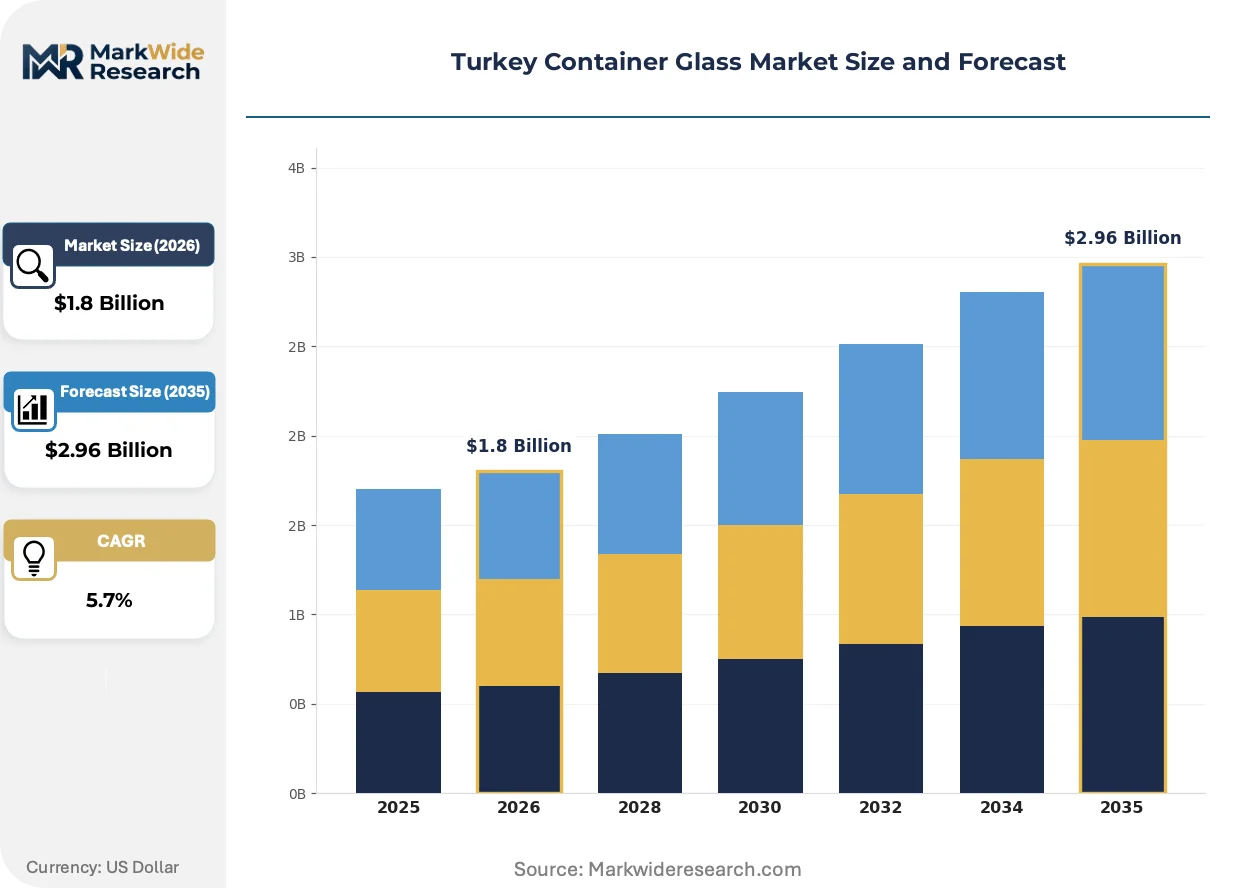
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Containers, Beverage Bottles, Pharmaceutical Vials, Cosmetic Jars End User: Food & Beverage, Healthcare, Cosmetics, Household Technology: Blow Molding, Press & Blow, Stretch Blow Molding, Glass Forming Packaging Type: Reusable Containers, Single-Use Bottles, Jars, Closures |
| Companies Covered | Şişecam Group, Ciner Glass, Gürok Cam Ambalaj, Marmara Cam Sanayi, Baştürk Cam, Arslan Cam Ambalaj, LAV, Solmazer Ev Gereçleri, Pasabahce, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Container Glass Market Trends and Innovations
Container glass production in Turkey is splitting between commodity beverage volume and specialized pharmaceutical-cosmetic premium formats. This divergence is forcing technology investments in opposite directions.
Lightweighting technology is bifurcating the equipment supply base. Thin-wall forming machines from European vendors now enable 280-gram wine bottles that match 380-gram structural performance. Anatolian wine exporters are adopting these formats for German and UK private label contracts. The technology is compressing margin pools for standard-weight molders while creating equipment financing demand.
The Turkish Ministry of Environment's 2024 packaging waste regulation amendments tighten post-consumer glass recovery targets to 65% by weight. Furnace operators must now certify cullet sourcing from licensed waste management consortia. Pharmaceutical glass producers face the steepest compliance costs due to batch purity requirements that limit recycled content ratios.
Beverage bottler procurement consolidation is reshaping supplier relationships. Multi-brand distributors in Istanbul and Ankara are centralizing glass purchasing through framework agreements that demand 18-month price locks and dedicated furnace capacity. This behavior is most visible in the carbonated soft drink segment, where three bottlers now account for the majority of flint glass volume. Smaller molders are responding through cooperative production pooling to meet minimum order thresholds.
Turkey Container Glass Market Segmentation
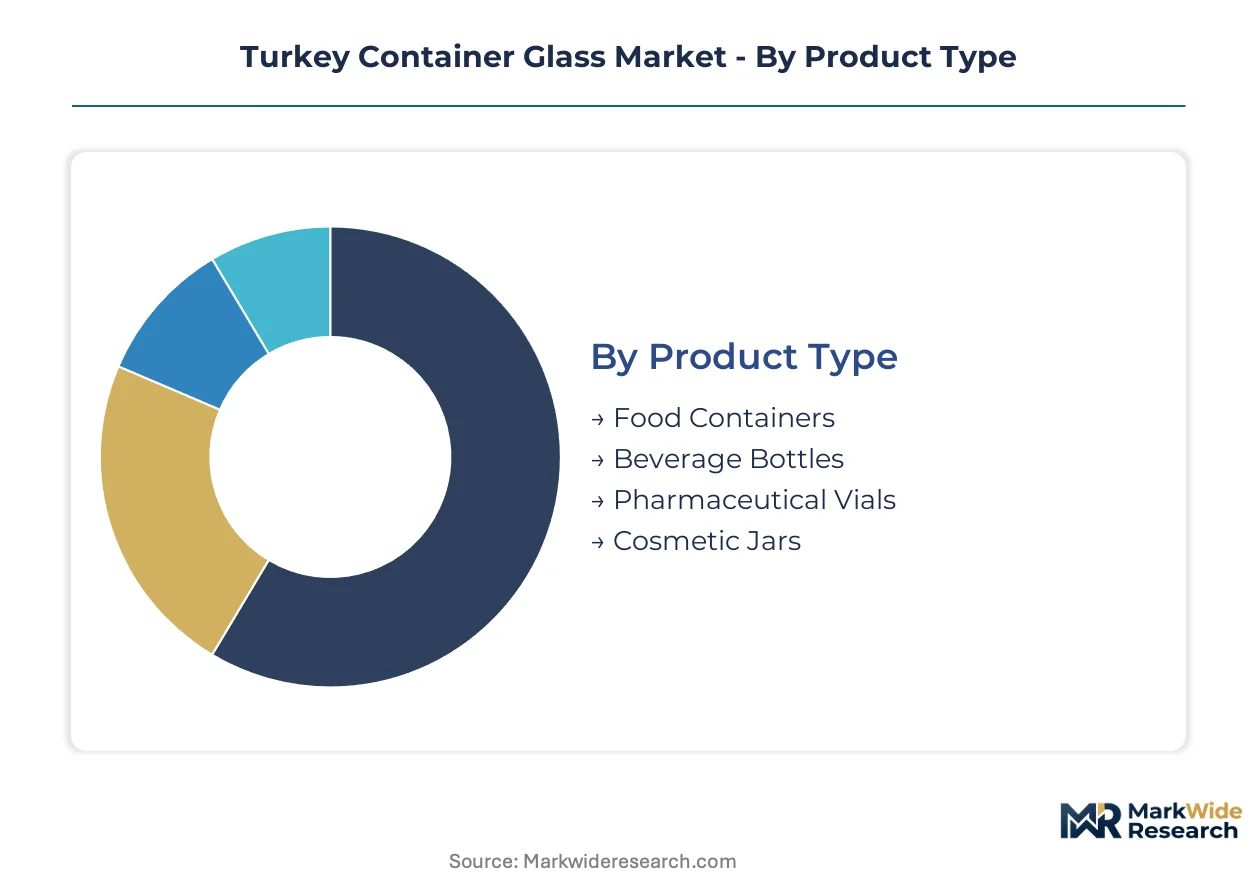
Container glass demand across Turkey fragments along product functionality and customer compliance requirements. Each segment carries distinct furnace chemistry specifications and end-user certification burdens that reshape supplier economics.
Product Type:
Domestic consumption dominates food and beverage formats, while pharmaceutical and cosmetic output feeds export corridors into the Middle East and Balkans.
- Beverage Bottles:Flint and amber soda-lime compositions serve carbonated soft drink and mineral water bottlers across Anatolia. Istanbul-based distributors now consolidate procurement through 18-month framework agreements that demand dedicated furnace capacity.
- Pharmaceutical Vials:USP Type I borosilicate glass meets chemical inertness standards for parenteral drug storage. Demand from Istanbul contract manufacturers outstrips qualified domestic supply, creating margin concentration for certified molders.
- Food Containers:Standardized jar formats for preserves and sauces occupy mature demand curves where scale economics protect incumbent positions.
- Cosmetic Jars:Wide-mouth amber and cobalt blue containers serve skincare brands targeting Middle Eastern export markets.
Beverage bottles hold the largest share; momentum sits with pharmaceutical vials.
End User:
Cost tiers separate commodity volume buyers from premium segment purchasers with stringent quality management requirements.
- Food & Beverage:Carbonated soft drink bottlers anchor volume demand as PET substitution reverses amid consumer preference shifts. Marmara region logistics corridors enable just-in-time delivery to Anatolian production facilities.
- Healthcare:Pharmaceutical manufacturers demand batch documentation and ISO 9001 certification that excludes smaller molders from approved vendor lists. TSE alignment with EU REACH streamlines export qualification.
- Cosmetics:Istanbul-based contract manufacturers source narrow-neck formats for premium positioning in Gulf markets.
- Household:Standard storage containers face price pressure from imported alternatives.
Food and beverage commands the volume base; healthcare delivers the steepest margin expansion trajectory.
Technology:
Application requirements dictate forming method selection, with lightweighting investments concentrating in wine and premium beverage segments.
- Press & Blow:Wide-mouth jar production for food and cosmetic applications permits thicker wall sections where structural integrity outweighs weight reduction.
- Blow Molding:Narrow-neck bottle formats dominate beverage volume, with European thin-wall equipment enabling 280-gram wine bottles that match 380-gram performance.
- Stretch Blow Molding:Limited adoption in container glass due to thermal expansion constraints; primarily serves hybrid PET-glass comparison studies.
- Glass Forming:Traditional pressed glass for cosmetic jars and specialty closures.
Press and blow retains the installed base; blow molding captures capital deployment for lightweighting.
Packaging Type:
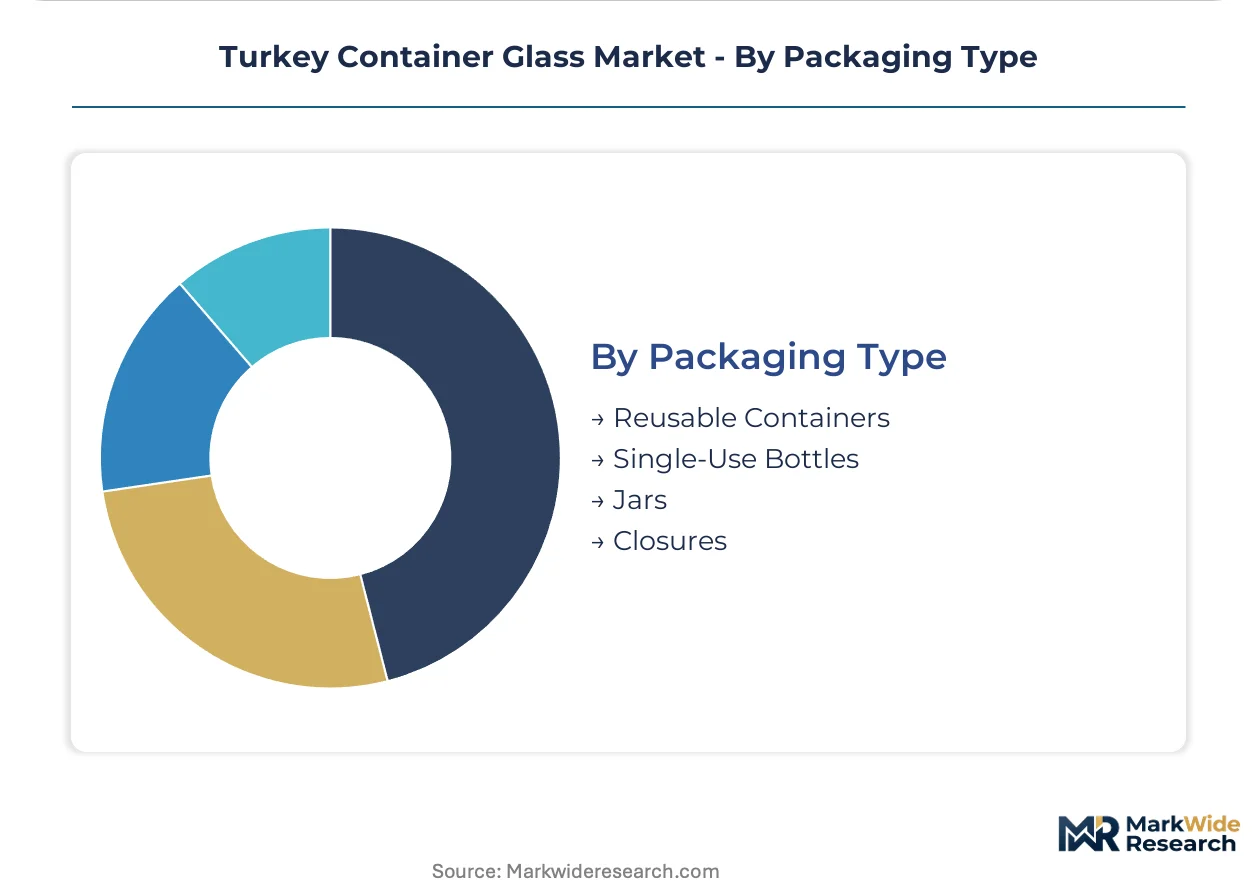
Regulatory pressure from the Turkish Ministry of Environment's extended producer responsibility mandates is bifurcating recovery economics between reusable and single-use formats.
- Single-Use Bottles:Flint and amber beverage containers face 65% post-consumer recovery targets under amended packaging waste regulations. Furnace operators must certify cullet sourcing from licensed waste management consortia.
- Reusable Containers:Returnable bottle systems for mineral water and beer retain cost advantage in closed-loop distribution networks around Istanbul and Izmir.
- Jars:Food container standardization limits differentiation but protects scale positions for incumbent molders.
- Closures:Secondary packaging components with distinct aluminum and plastic substitution dynamics.
Single-use bottles represent the volume core; reusable formats are gaining share fastest in beverage logistics networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and pharmaceutical contract manufacturers cluster in Turkey's Marmara region, with Anatolian mining corridors and Aegean port infrastructure creating distinct sub-regional specializations.
Marmara Region
Istanbul-based distributors consolidate glass procurement through framework agreements demanding dedicated furnace capacity. The Turkish Ministry of Environment's extended producer responsibility mandates enforce 65% post-consumer recovery targets. TSE packaging waste regulation alignment streamlines EU REACH prerequisites for export-bound output through the city's logistics corridors.
Central Anatolia
Captive trona and soda ash deposits insulate major producers from imported flux price volatility. The country's national mining regulator oversees extraction licensing across the Konya and Ankara basins. Şişecam Group leverages integrated soda ash mining and furnace operations to dominate domestic float and container output from this belt.
Aegean Region
Izmir port infrastructure investments enable direct Mediterranean shipping routes to North African beverage bottlers. The Turkish Ministry of Environment's 2024 packaging waste regulation amendments tighten cullet sourcing certification requirements. Lightweighting technology investments concentrate here for Anatolian wine exporters serving German and UK private label contracts.
Black Sea Region
Mineral water bottlers in Rize and Trabzon anchor regional demand for returnable bottle systems in closed-loop distribution networks. Provincial environmental authorities enforce licensed waste management consortium participation. Smaller molders face ISO 9001 audit cycle compliance pressures that exclude them from beverage bottler approved vendor lists.
Turkey Container Glass Market Competitive Landscape
Player mix skews toward integrated mining-to-furnace operators and specialized narrow-neck format molders. The competitive structure concentrates around three strategic archetypes: captive raw material players, premium pharmaceutical specialists, and cooperative production pools. Dominant competitive moves include hybrid oxy-fuel furnace conversions and backward integration into soda ash supply.
Within the integrated raw material tier, Şişecam Group exemplifies the mining-to-furnace archetype through its Anatolian soda ash operations. Ciner Glass occupies a parallel position anchored by captive trona deposits. Among specialized format players, Gürok Cam Ambalaj represents the narrow-neck pharmaceutical and cosmetic segment. These three companies collectively illustrate how Turkish container glass competition splits between commodity scale and premium certification.
| Leading Market Players |
|---|
| Şişecam Group |
| Ciner Glass |
| Gürok Cam Ambalaj |
| Marmara Cam Sanayi |
| Baştürk Cam |
| Arslan Cam Ambalaj |
| LAV |
| Solmazer Ev Gereçleri |
| Pasabahce |
| Others |
Pricing and Supply Chain Analysis
Turkish Standards Institution certification gates both supply qualification and price differentiation, excluding uncertified molders from beverage bottler procurement lists while enabling ISO 9001 holders to command 15-20% premiums over commodity tiers. This regulatory filter concentrates pricing power among furnace operators with audit-compliant quality management systems.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate procurement between Marmara-region bottlers and furnace operators, passing through 60-70% of fuel cost swings via quarterly adjustments. Three-tier pricing structure across premium pharmaceutical, standard beverage, and economy food-container levels separates USP Type I borosilicate vials from soda-lime commodity output. Pricing pressure stems from volatile Azeri-Russian pipeline tariffs that compress margin visibility for batch-operated furnaces. Carbonated soft drink bottlers exhibit highest price sensitivity due to PET substitution threats in sub-500ml formats, while pharmaceutical contract manufacturers accept premium positioning for qualified domestic borosilicate supply.
Supply Chain Analysis
Bosphorus Strait transit underwrites soda ash import flows from Solvay's Bulgarian operations and American Natural Soda Ash Corporation Wyoming mines, creating a logistics chokepoint that feeds furnace batch chemistry across the Marmara production corridor. Captive trona deposits in central Anatolia and imported Wyoming soda ash constitute the dual-source flux foundation, with silica sand drawn from Balikesir and Mersin quarries. Single-source vulnerability concentrates in specialty boron oxide for pharmaceutical glass, where Etibor's Kestelek mine supplies 80% of domestic demand. Distribution runs through Istanbul-based consolidators operating 18-month framework agreements that lock dedicated furnace capacity for multi-brand bottler portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkish container glass is entering a high-growth disruption as extended producer responsibility mandates force 65% post-consumer recovery targets that reconfigure furnace economics and batch chemistry across the Marmara corridor.
For Market Incumbents: Consolidate approved vendor list positions by accelerating hybrid oxy-fuel furnace conversions ahead of prospective EU carbon border adjustment mechanisms, while deepening backward integration into Anatolian soda ash mining to insulate margin structures from imported flux volatility. Şişecam and Ciner Glass archetypes should lock multi-year trona extraction licenses before national mining regulator policy shifts. For New Entrants and Emerging Players: Narrow-neck cosmetic and pharmaceutical format shortages present white-space entry points where USP Type I borosilicate demand from Istanbul contract manufacturers outstrips qualified domestic supply. Target Aegean coastal production with lightweighting equipment financing to capture Anatolian wine exporter contracts for German and UK private label channels, leveraging Izmir port infrastructure for direct Mediterranean shipping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-cosmetic premium segments as USP Type I certification requirements and hybrid furnace conversions demand 50-80 million dollar refractory rebuild commitments. Five-to-ten year viability favors acquisition targets with captive raw material positions and existing ISO 9001 audit cycles rather than greenfield furnace deployment. Monitor Turkish Ministry of Environment packaging waste regulation enforcement intensity as the signal for cullet-sourcing compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Oxy-Fuel Furnace Conversion | Oxygen-enriched combustion reduces natural gas intensity 15-20% while positioning operators for EU carbon border adjustments. |
| Backward Integration into Soda Ash Mining | Captive trona deposits in Anatolia insulate Şişecam and Ciner Glass from imported flux price volatility. |
| USP Type I Borosilicate Certification | Pharmaceutical glass producers capture margin concentration as Istanbul contract manufacturer demand outstrips qualified supply. |
| Lightweighting Equipment Deployment | Thin-wall forming machines enable 280-gram wine bottles matching 380-gram performance for Anatolian export contracts. |
| Licensed Waste Management Consortium Partnership | Furnace operators must certify 65% cullet sourcing under Turkish Ministry of Environment amended regulations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Turkish Standards Institution regulatory filings, Ministry of Environment packaging waste amendments, and EU REACH alignment documentation, with furnace operator interviews, beverage bottler procurement leads, and pharmaceutical contract manufacturer quality directors supplying operational ground-truth. Customs export data, soda ash mining license records, and natural gas pipeline tariff disclosures provided volume and cost validation. Bottom-up furnace capacity modeling and top-down regional demand aggregation triangulated market sizing across the analysis window.
Segmentation dimensions modeled include product type (beverage bottle, pharmaceutical vial, food container, cosmetic jar), end-user industry (food and beverage, healthcare, cosmetics, household), forming technology (press and blow, blow molding), and packaging format (single-use, reusable). CAGRs derived from installed furnace capacity expansion plans, cullet recovery rate trajectories, and export corridor volume growth assumptions. Forecast inputs incorporated natural gas price volatility scenarios and EU carbon border adjustment mechanism implementation probability.
Underlying assumptions cover regulatory enforcement continuity, refractory lifecycle replacement schedules, and export demand stability for Balkan and Middle Eastern corridors, with deviation risk concentrated in Azeri-Russian pipeline pricing negotiations and pharmaceutical import conformity assessment reciprocity changes. Practitioners should keep alternative scenarios live as Turkish Ministry of Environment extended producer responsibility implementation intensity and EU carbon border adjustment mechanism scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Spain Packaging Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market