
 North America Potato Chips Market | 2026-2036
North America Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potato Chips Market Intelligence
Capital-intensity divergence between automated fry lines and artisan kettle operations is reorganizing competitive tiers in North American snack manufacturing. PepsiCo Inc. leverages its integrated potato procurement network across Idaho and Wisconsin to sustain raw material cost advantages. Utz Brands Inc. anchors its position through regional manufacturing density in Pennsylvania and the Carolinas, while Herr Foods Inc. competes via brand loyalty in Mid-Atlantic convenience channels.
North America potato chips comprise thin-sliced potatoes fried in vegetable oils at temperatures between 350°F and 375°F, then seasoned and packaged for shelf-stable retail distribution; the product serves as a core impulse-purchase item across grocery, convenience, and foodservice channels. Traditional thin-cut variants still occupy the largest volume share, though kettle-cooked formats command premium shelf positioning and higher per-unit margins. Specialty segments incorporating alternative oils or reduced-sodium profiles are capturing health-conscious consumers, while single-serve packaging dominates vending and convenience store velocity.
FDA nutrition labeling mandates, Health Canada front-of-package sodium warnings, and USDA organic certification standards collectively elevate reformulation costs and restrict market entry for unverified claims. The USDA's school nutrition guidelines further constrain permissible fat and sodium levels in products targeting institutional channels. Stakeholders must monitor evolving state-level sugar and sodium taxes in California and New York while calibrating portfolio allocation between indulgence and better-for-you positioning.
Market Dynamics
Convenience store velocity and quick-service restaurant integration are compressing traditional grocery dominance in North American potato chip distribution. FDA nutrition labeling mandates and Health Canada sodium reduction frameworks are forcing simultaneous reformulation across multiple product lines.
Growth Catalysts
- Quick-Service Restaurant Partnerships:Fast-food chains are embedding potato chips as combo-meal defaults, expanding consumption frequency beyond traditional snack occasions.
- FDA Nutrition Labeling Modernization:Updated serving-size definitions and added-sugar disclosures are prompting portfolio rationalization that favors cleaner-label variants with longer shelf life.
- Midwest Processing Cluster Density:Concentrated fry-line capacity across Idaho and Wisconsin enables just-in-time raw potato sourcing that reduces spoilage rates and transportation overhead.
Market Restraints
- Vegetable Oil Price Volatility:Sunflower and canola oil input costs fluctuate with commodity crop yields, compressing margin predictability for mid-tier producers lacking forward-contract coverage.
- Single-Region Potato Sourcing Concentration:Overreliance on Pacific Northwest tuber supply exposes processors to climate-driven yield shocks and irrigation policy shifts.
- Mechanical Shear Limitations:Conventional slicing blades cannot achieve sub-1.5mm consistency required for ultra-thin premium formats without unacceptable breakage rates.
Strategic Opportunities
- Southeast Convenience Corridor Expansion:Underpenetrated rural Georgia and Alabama markets present whitespace for regional brands to establish dedicated distribution before national players consolidate shelf space.
- USDA Organic Certification Tailwind:Federal procurement preference for certified organic snacks in institutional channels creates a mandated demand pool with limited qualified suppliers.
- Air-Frying Technology Convergence:Hybrid thermal processing combining radiant heat with forced convection enables oil-reduced formulations that meet school nutrition guidelines without texture degradation.
Industry Challenges
- Retrofitting Legacy Fry Lines:Converting continuous fryers to accommodate alternative oils requires stainless-steel tank replacement and exhaust system upgrades that extend downtime windows.
- Reduced-Sodium Certification Timelines:Health Canada front-of-package warning exemption protocols demand multi-year stability testing that delays product launches and ties up R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potato Chips Market |
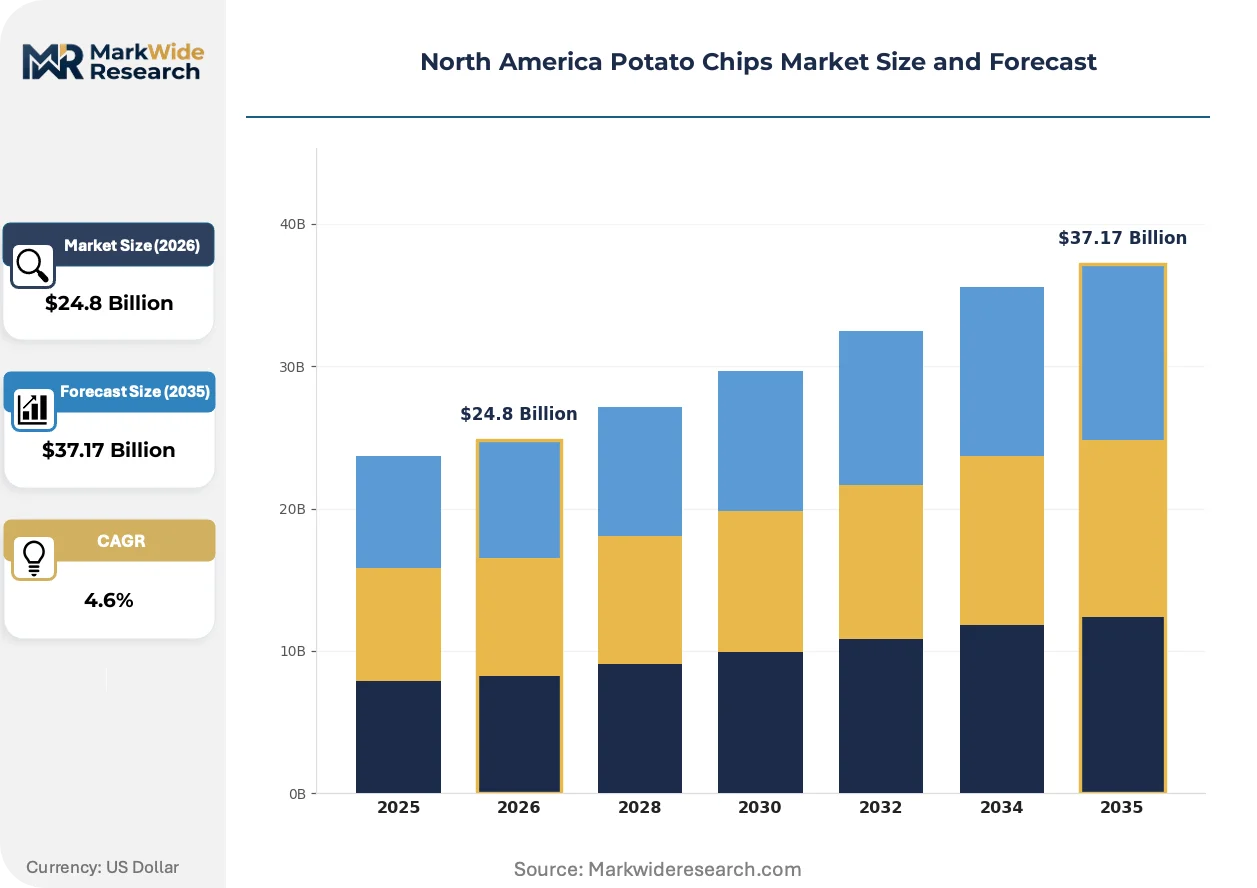
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Baked, Kettle-Cooked, Specialty Flavor Profile: Sea Salt, Barbecue, Sour Cream & Onion, Cheddar Packaging Type: Bags, Canisters, Bulk, Single Serve Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines |
| Companies Covered | The Campbell's Company, Old Dutch Foods Inc., PepsiCo Inc., Zapp's, Kettle Brand, Utz Brands Inc., Herr Foods Inc., Burts Snacks Ltd., General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potato Chips Market Strategic Shifts & Innovations
Pulse-based coatings and modified-atmosphere packaging are disrupting conventional oil-absorption physics and shelf-life assumptions. These shifts compress the gap between kettle-cooked texture and conventional production economics.
High-pressure processing is decomposing the traditional trade-off between pathogen elimination and acrylamide formation. Mid-Atlantic co-manufacturers are adopting batch HPP systems to enable clean-label claims without frying temperature reductions. This technology is decomposing the premium tier's reliance on small-batch kettle operations by delivering comparable texture at continuous-line throughput.
Health Canada front-of-package sodium warning regulations are triggering reformulation sprints across Ontario and Quebec manufacturing facilities. Processors must hit 15% sodium reduction targets to avoid mandatory warning symbols that depress convenience store velocity. Kettle-cooked and specialty segments face disproportionate compliance costs due to salt-heavy seasoning adhesion requirements.
Single-serve pouch specifications are fragmenting procurement patterns across vending and micro-market channels. Distributors are consolidating supplier relationships around manufacturers offering 1-3 ounce format flexibility without minimum order penalties. This shift is most visible in Texas and Florida, where workplace breakroom automation is displacing traditional route-delivered bulk boxes.
North America Potato Chips Market Segmentation
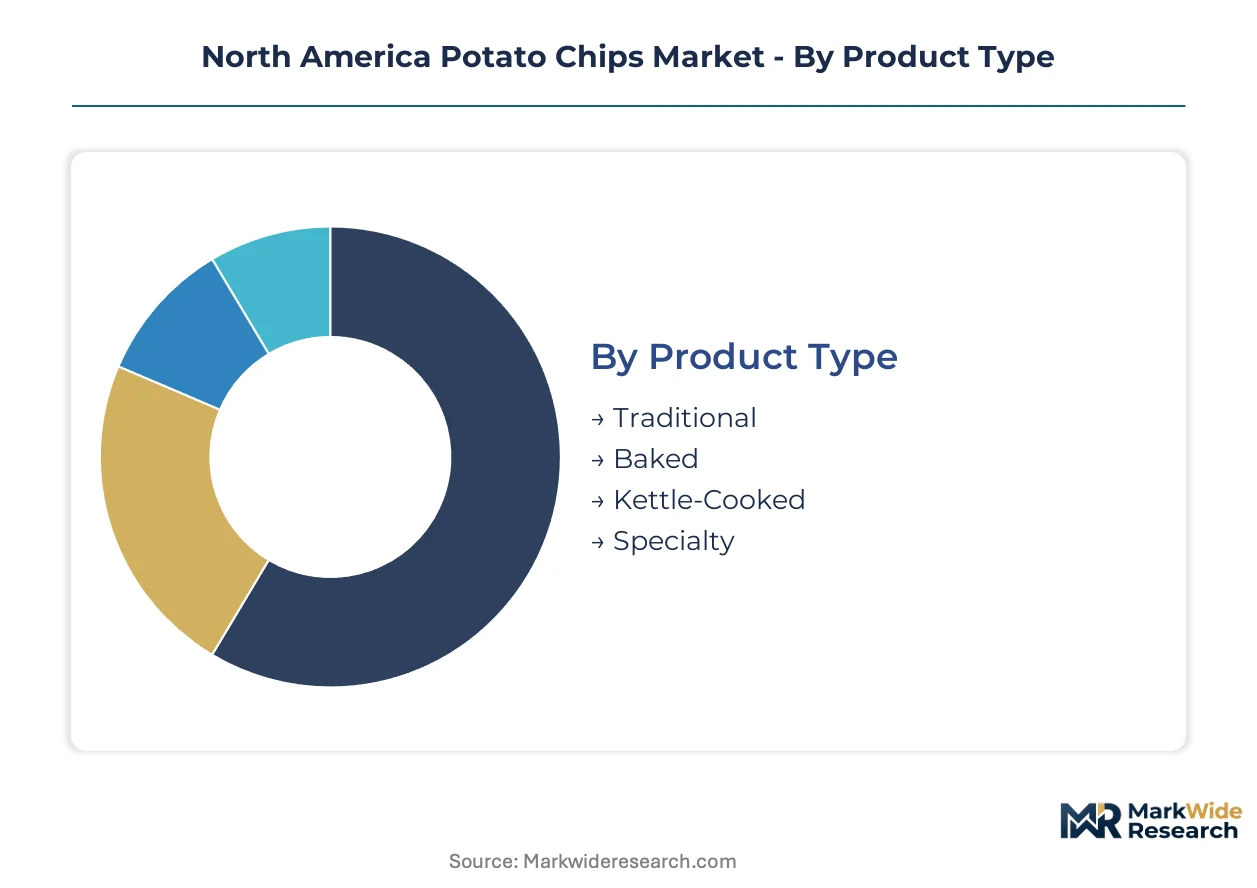
Potato chip manufacturers calibrate portfolio allocation across four intersecting dimensions where margin concentration diverges sharply. Product format and packaging specifications determine fry-line capital requirements, while flavor complexity and channel placement dictate working capital intensity and velocity economics.
Product Type:
Margin pools concentrate in premium-positioned formats where oil specification and slice thickness command price premiums over commodity thin-cut alternatives.
- Traditional:Thin-sliced potatoes fried in standard vegetable oils at 350°F to 375°F deliver the highest volume throughput per fry-line hour. Midwest grocery channels and Southeast convenience corridors sustain demand concentration for this format, though per-unit margins compress under commodity pricing pressure.
- Kettle-Cooked:Batch-fried at lower temperatures with thicker slice profiles, this format achieves 40% higher shelf price positioning through texture differentiation. Health Canada sodium warning compliance costs hit this segment disproportionately due to salt-heavy seasoning adhesion requirements.
- Baked:Radiant heat processing reduces oil absorption for institutional channel qualification under USDA school nutrition guidelines.
- Specialty:Alternative oil formulations and reduced-sodium profiles target health-conscious consumers in California and New York metro markets.
The dominant share belongs to Traditional, while Kettle-Cooked is closing the gap fastest.
Flavor Profile:
Application context determines flavor velocity, with combo-meal defaults and standalone snack occasions requiring distinct seasoning investment profiles.
- Sea Salt:Minimal seasoning complexity supports clean-label positioning and lowest per-batch ingredient cost. Quick-service restaurant partnerships embed this profile as default side options, driving volume concentration in Texas and Florida foodservice corridors.
- Barbecue:Tomato-based and vinegar-forward regional variants command loyal repeat purchase in Mid-Atlantic and Carolinas markets. FDA added-sugar disclosure requirements are forcing reformulation of high-fructose corn syrup dependencies in this profile.
- Sour Cream & Onion:Dairy powder and dehydrated allium specifications require allergen-controlled production lines.
- Cheddar:Cheese powder adhesion demands specialized tumbling equipment for uniform coating distribution.
Sea Salt maintains volume leadership, though Barbecue is expanding most quickly through regional brand penetration.
Packaging Type:
Customer type stratification across institutional, retail, and immediate-consumption occasions creates distinct procurement minimums and shelf-life engineering requirements.
- Single Serve:One- to three-ounce pouches dominate vending and micro-market velocity with highest per-ounce price realization. Workplace breakroom automation across Texas and Florida is displacing traditional route-delivered bulk boxes for this format.
- Bags:Standard flexible packaging for retail shelf placement with modified-atmosphere sealing for 120-day shelf stability.
- Canisters:Rigid container formats protect chip integrity for club store and pantry-stock occasions.
- Bulk:Foodservice poly-lined cases for institutional and concession channel delivery.
Bags retain the dominant position, while Single Serve is gaining share fastest through convenience channel automation.
Distribution Channel:
Geography of demand concentration shifts channel investment priorities, with rural whitespace and urban density requiring divergent distribution economics.
- Convenience Stores:Impulse-purchase velocity with highest margin per square foot in rural Georgia and Alabama markets where national players remain underpenetrated. Health Canada front-of-package warning symbols depress velocity in Ontario and Quebec unless sodium targets are met.
- Supermarkets:Planned-purchase destination with slotting fee barriers and planogram competition.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment with shipping-damage constraints.
- Vending Machines:Automated retail with coin-op and cashless payment integration requirements.
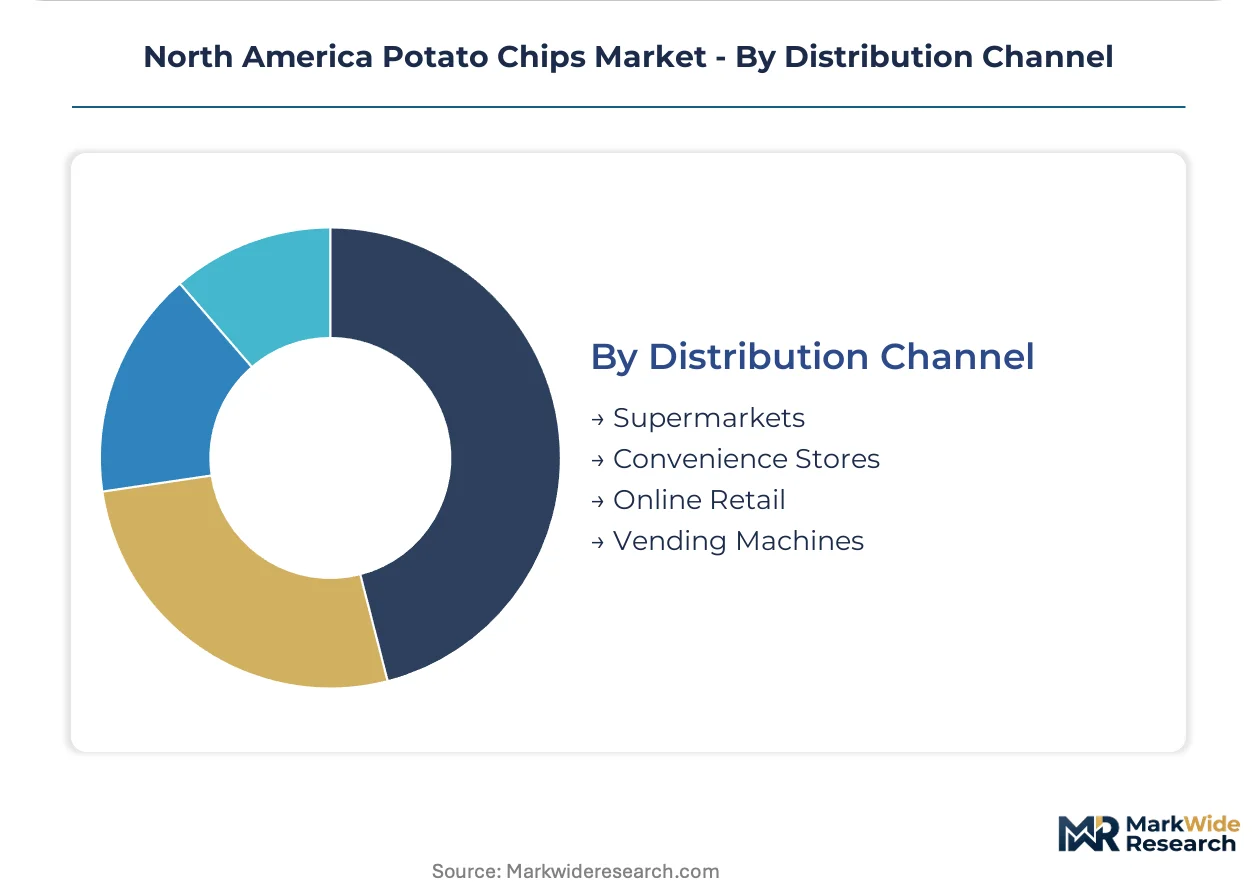
Supermarkets hold the dominant share, while Convenience Stores are climbing the fastest through quick-service restaurant spillover demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American markets, with price-sensitive volume buyers concentrated in the Southeast convenience corridor and premium-positioned consumers driving value growth in California and the Northeast.
United States
Midwest grocery channels and Texas workplace breakroom automation sustain the highest per-capita consumption velocity. FDA nutrition labeling modernization mandates simultaneous reformulation across multiple product lines. Idaho and Wisconsin processing clusters enable just-in-time raw potato sourcing that reduces spoilage rates.
Canada
Ontario and Quebec manufacturing facilities face disproportionate compliance costs from Health Canada front-of-package sodium warning regulations. Kettle-cooked segments require 15% sodium reduction to avoid mandatory warning symbols that depress convenience store velocity. Toronto-based processors are retrofitting legacy fry lines to accommodate alternative oil formulations.
Mexico
Rapid quick-service restaurant expansion across Mexico City Metro and Nuevo León is embedding potato chips as combo-meal defaults. The country's national food safety regulator enforces labeling standards that align with US FDA frameworks for cross-border manufacturing. Guadalajara-area distribution hubs are consolidating supplier relationships around single-serve format flexibility.
Southeast United States
Rural Georgia and Alabama markets present whitespace for regional brands to establish dedicated distribution before national players consolidate shelf space. State-level sugar and sodium tax proposals in adjacent jurisdictions create regulatory uncertainty. Carolina-based manufacturing density anchors regional supply chain efficiency.
California
Health-conscious consumers in Los Angeles and San Francisco metro markets drive specialty segment demand for alternative oil and reduced-sodium profiles. Proposition 65 chemical warning requirements elevate reformulation costs for products targeting institutional channels. Sacramento-area foodservice distributors are consolidating procurement around certified organic suppliers.
North America Potato Chips Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with automated fry-line scale specialists competing against artisan kettle-batch operators for distinct margin pools. The market structure consolidates around three tiers: integrated agricultural-processor conglomerates, regional manufacturing-density specialists, and niche premium-positioned brands. Dominant competitive moves include backward integration into potato procurement networks and strategic partnerships with quick-service restaurant chains for combo-meal placement.
Within the integrated agricultural-processor tier, PepsiCo Inc. and General Mills occupy positions exemplifying scale-driven raw material cost advantages. Among regional manufacturing-density specialists, Utz Brands Inc. and Herr Foods Inc. represent archetypes anchored in Mid-Atlantic and Pennsylvania production clusters. The Campbell's Company and Old Dutch Foods Inc. sit within the diversified snack portfolio tier, leveraging cross-category distribution infrastructure.
| Leading Market Players |
|---|
| The Campbell's Company |
| Old Dutch Foods Inc. |
| PepsiCo Inc. |
| Zapp's |
| Kettle Brand |
| Utz Brands Inc. |
| Herr Foods Inc. |
| Burts Snacks Ltd. |
| General Mills |
| Others |
Cost & Logistics Intelligence
Long-term potato procurement contracts with Idaho and Wisconsin growers lock in both supply access and price visibility for processors operating continuous fry lines, insulating them from spot-market tuber volatility while compressing margin flexibility for kettle-batch operators lacking comparable scale.
Pricing Analysis
After-sales foodservice equipment service contracts and extended maintenance agreements drive lifetime value for fry-line manufacturers serving the installed base. Three-tier pricing structure across premium kettle-cooked, standard traditional, and economy private-label levels stratifies by oil specification and slice thickness. Cost compression in mid-tier traditional segments is intensifying because vegetable oil futures fluctuate with commodity crop yields. Quick-service restaurant chains exhibit highest price sensitivity due to combo-meal margin constraints, while specialty retailers in California and New York demonstrate lowest sensitivity for certified organic and reduced-sodium profiles.
Supply Chain Analysis
Raw potato inventory cycles of 14-21 days from harvest to fry-line intake compress planning windows for processors managing perishability exposure. Supply concentrates in Idaho, Wisconsin, and the Pacific Northwest for tuber sourcing, with sunflower and canola oil feedstocks drawing from Canadian prairie provinces and US Great Plains growers. Single-region concentration in Pacific Northwest irrigation-dependent acreage creates vulnerability to drought-driven yield shocks. Distribution runs through direct-store-delivery networks for convenience store velocity and foodservice redistribution centers for institutional channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against alternative snack formats including popped chips, extruded puffs, and plant-based crisps that capture health-conscious consumers in California and Northeast corridor retail channels.
For Market Incumbents: Shield core grocery shelf space through exclusive quick-service restaurant partnership renewals that embed potato chips as combo-meal defaults, while accelerating air-frying technology convergence to meet USDA school nutrition guidelines and defend against baked-format substitutes. Backward integration into captive potato procurement networks in Idaho and Wisconsin sustains raw material cost advantages against regional kettle-cooked challengers. For New Entrants and Emerging Players: USDA Organic certification fast-track programs unlock mandated federal procurement preference in institutional channels with limited qualified supplier pools. Target underpenetrated rural Georgia and Alabama convenience corridors where national players lack dedicated distribution density, leveraging single-serve format flexibility without minimum order penalties to secure micro-market and workplace breakroom automation contracts. For Investors and Strategic Acquirers: Regional manufacturing-density specialists with concentrated fry-line capacity in Pennsylvania and the Carolinas represent acquisition targets offering distribution infrastructure and brand loyalty in Mid-Atlantic channels. Watch Health Canada sodium warning exemption timelines as inflection indicator for reformulation cost burdens that may force portfolio divestitures from kettle-cooked segments.| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Service Restaurant Partnership Renewal | Locks in combo-meal default placement against substitute snack encroachment. |
| Air-Frying Technology Convergence | Enables oil-reduced formulations meeting USDA school nutrition guidelines. |
| USDA Organic Certification Investment | Qualifies processors for federal institutional procurement preference pools. |
| Southeast Convenience Corridor Expansion | Captures whitespace in rural Georgia and Alabama before national consolidation. |
| Legacy Fry Line Retrofit for Alternative Oils | Accommodates sunflower and canola substitutions amid commodity price volatility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance documents, Health Canada front-of-package warning protocols, USDA school nutrition standards, and Nielsen retail audit data covering grocery and convenience channel velocity. Primary interviews with potato chip brand managers, category buyers at supermarket chains, foodservice distribution procurement leads, and quick-service restaurant menu development executives informed demand-side assumptions. Bottom-up fry-line capacity modeling triangulated against top-down retail dollar flow analysis across the analysis window.
Segmentation dimensions modeled include product format, flavor profile, packaging specification, and distribution channel, with additional granularity on oil type and sodium certification status. CAGRs were derived through trend extrapolation of historical velocity data adjusted for regulatory phase-in schedules and quick-service restaurant partnership expansion trajectories. Forecast inputs incorporated vegetable oil futures pricing patterns, Pacific Northwest irrigation policy developments, and workplace breakroom automation penetration rates.
The analysis sits within stated boundaries; outcomes outside Health Canada sodium warning compliance timelines, FDA labeling modernization implementation, or sustained quick-service restaurant partnership structures would require recalibration. Forecasts reflect documented assumptions regarding raw material cost trajectories and channel shift velocities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
United States Children's Snack Bar Market
Snacks
Super Low Calorie Snacks Market
Snacks
Low Calorie Dip Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Pretzel Salts Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Australia Snack Bar Market
Snacks
Plant-Based Snacks Market
Snacks
Qatar Potato Chips Market
Snacks
Thailand Snack Bar Market
Snacks
Fat Free Snacks Market
Snacks
Popcorn Market
Snacks
Savory Snack Products Market
Snacks
Low Fat Granola Market
Snacks
Crackers Market
Snacks
United Arab Emirates Energy Bar Market