
 Spain Snack Bar Market | 2026-2036
Spain Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Snack Bar Market Analytics
Fitness center memberships and corporate wellness programs are rebalancing the end-use vertical mix toward performance-oriented consumption. General Mills Inc. sustains broad retail penetration through its Nature Valley portfolio across Spanish supermarkets. Nestlé S.A. dominates the premium protein segment with specialized formulations targeting athletes. Kellanov competes aggressively on price tier accessibility for budget-conscious students in urban convenience channels.
A snack bar is a shelf-stable, individually wrapped food product typically composed of cereals, nuts, dried fruits, protein isolates, or chocolate coatings, formed through extrusion or cold-press manufacturing and designed for portable, between-meal consumption. Protein bars command the highest margin pools as consumers prioritize whey and plant-based protein fortification. Granola bars occupy mature volume leadership but face gradual displacement by nut bars, which benefit from Mediterranean diet alignment and clean-label positioning. The distribution channel structure concentrates leverage in supermarkets, though online retailers represent the fastest-growing access point for subscription-based replenishment.
Spain's national food safety agency enforces EU Regulation 1169/2011 on food information to consumers, while BSI-equivalent standards govern nutritional claim substantiation under EFSA guidelines. These frameworks compel reformulation away from high sugar content and mandate transparent protein source disclosure on front-of-pack labels. Stakeholders must monitor pending EU-wide restrictions on nutrient profiling models that could recalibrate permissible health claims across the product portfolio.
Market Dynamics
Spain's snack bar market is restructuring around EU-wide nutrition transparency mandates, with Nutri-Score labeling forcing manufacturers to reformulate sugar-dense portfolios while protein fortification creates premium tier separation.
Growth Catalysts
- Fitness center proliferation:Madrid and Barcelona's boutique gym density drives performance-oriented consumption, with post-workout replenishment becoming a ritualized purchase occasion.
- EU Regulation 1169/2011 enforcement:Spain's national food safety agency mandates clear protein source disclosure, accelerating clean-label product development and consumer trust.
- Mediterranean diet alignment:Nut bar formats leveraging regional ingredient familiarity—almonds, hazelnuts, olive oil—capture health-conscious urban households seeking portable nutrition.
Market Restraints
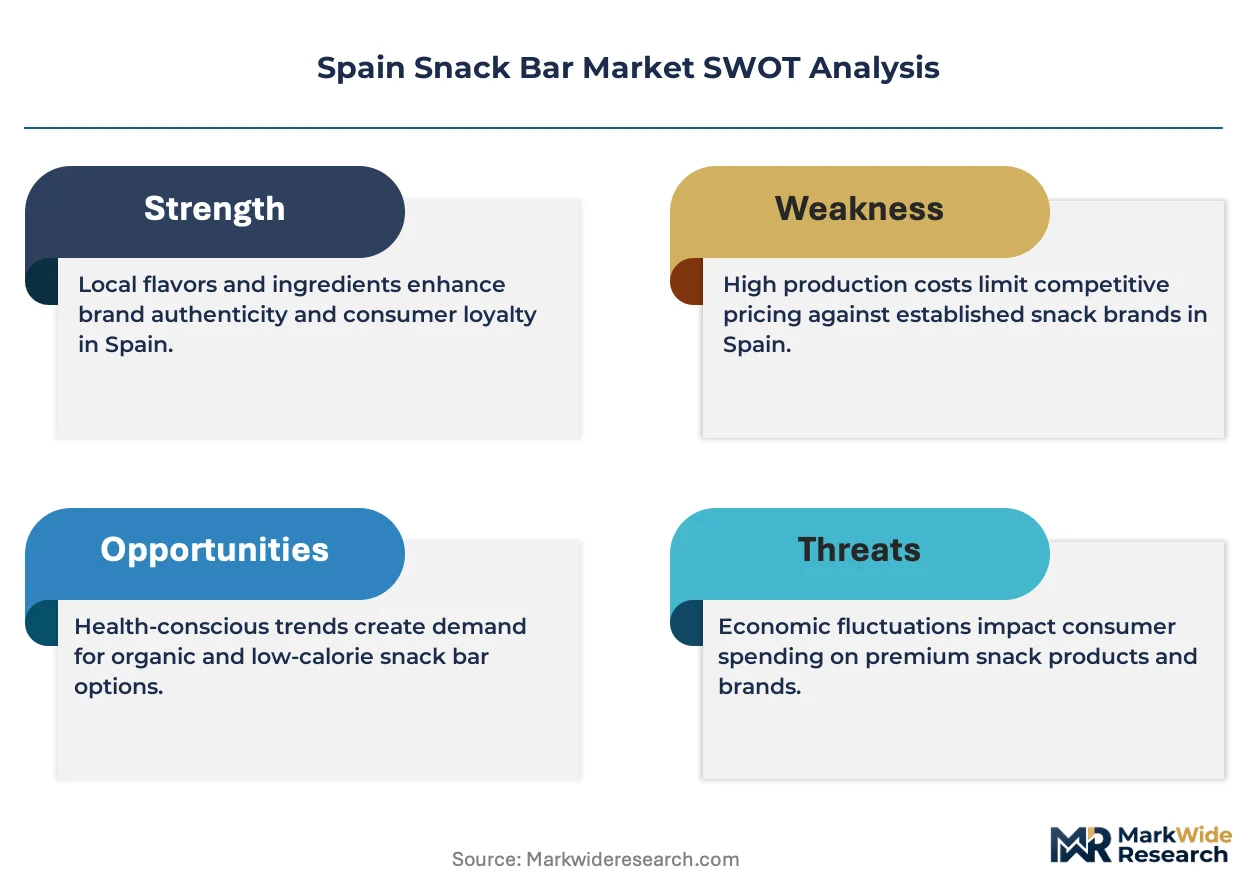
- Whey protein import dependency:Spain lacks domestic dairy protein isolate capacity, exposing margins to EU dairy commodity volatility and euro-dollar fluctuations.
- Supermarket buyer consolidation:Mercadona and Carrefour España control shelf access, compressing supplier negotiating power and slotting fee structures.
- Fresh food substitution:Prepared fruit and yogurt parfait counters in convenience stores capture overlapping on-the-go consumption occasions.
Strategic Opportunities
- Andalusian coastal corridor expansion:Underdeveloped snack bar penetration in Málaga and Cádiz fitness markets offers first-mover positioning before competitor saturation.
- Subscription direct-to-consumer channels:Monthly replenishment models bypass retail margin stacking while capturing recurring revenue from CrossFit and triathlon communities.
- Plant protein fermentation advances:Fava bean and lentil protein isolates from Spanish legume growers enable cost-competitive vegan positioning against imported whey.
Industry Challenges
- EFSA health claim substantiation timelines:Protein benefit approvals require 12-18 month clinical documentation, delaying product launches and marketing claims.
- Cold-chain extrusion equipment capex:Clean-label bar manufacturing demands specialized forming technology that mid-tier Spanish co-packers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Snack Bar Market |
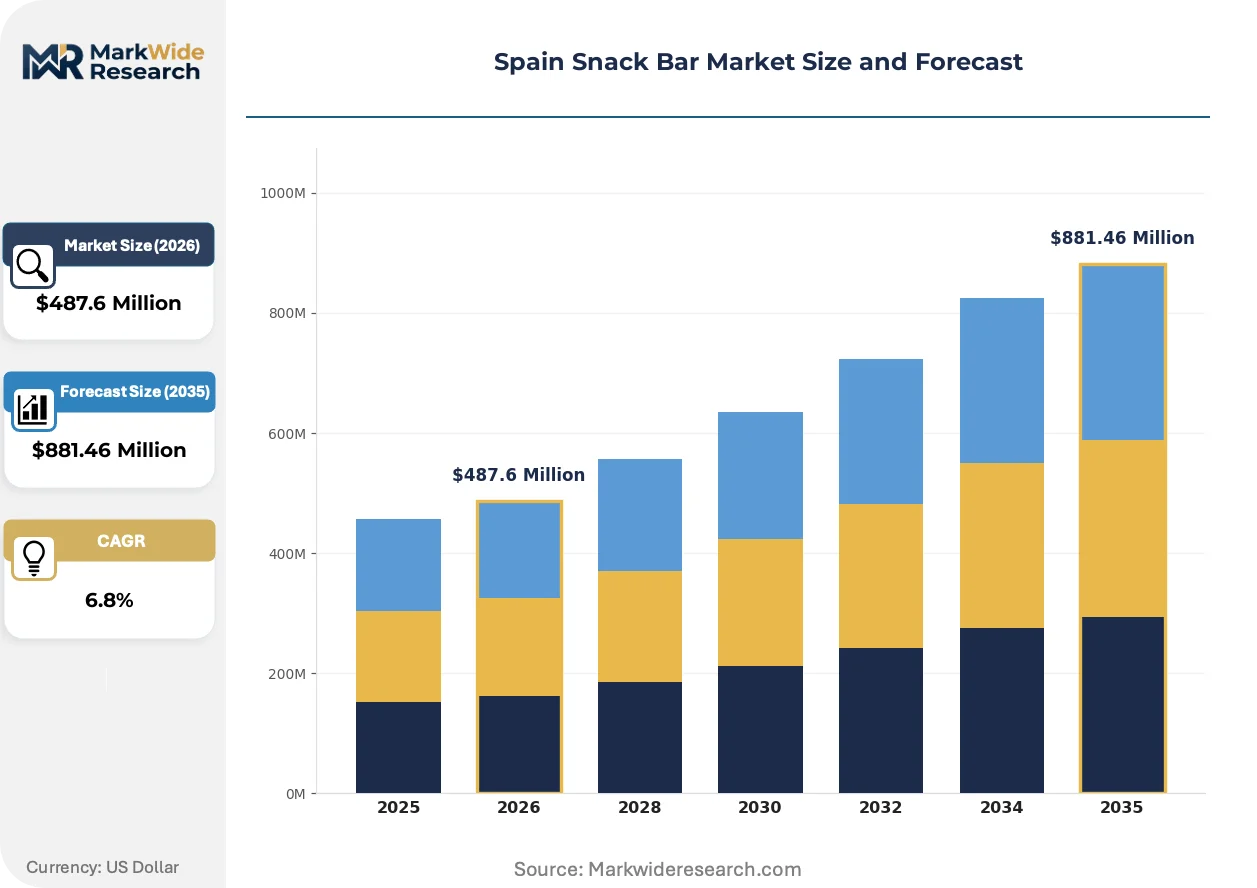
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Fruit Bars Customer Type: Health-Conscious Consumers, Students, Office Workers, Athletes Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Fitness Centers Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | General Mills Inc., Kellanov, Nestlé S.A., Abbott Nutrition Manufacturing Inc., Clif Bar & Company, PepsiCo Inc., Associated British Foods PLC, Post Holdings Inc., Mars, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Snack Bar Market Evolving Landscape
Reformulation chemistry and distribution architecture are converging to reshape how Spanish consumers access portable nutrition, with transparency mandates and digital replenishment models rewriting competitive rules.
Pea protein isolate and fava protein concentrate are integrating into Spanish manufacturing lines as viable whey alternatives. Barcelona-based contract manufacturers are adopting these ingredients at accelerating rates to serve vegan-positioned brands. This protein source diversification is integrating new domestic supply relationships while reducing eurozone dairy commodity exposure.
Spain's implementation of Nutri-Score front-of-pack labeling under EU-wide harmonization creates formulation pressure. Manufacturers must reduce sugar and salt to achieve favorable color ratings or face retail delisting risk. Protein bars targeting athletic segments are responding fastest, reformulating with stevia and monk fruit to maintain palatability.
Corporate wellness programs in Madrid's financial district and Barcelona's tech corridor are consolidating snack procurement. Facilities managers now negotiate annual supply contracts with direct delivery rather than relying on cafeteria vending. This buyer concentration is compressing vendor counts while rewarding brands with nutritionist certification and customizable portion formats.
Spain Snack Bar Market Segmentation
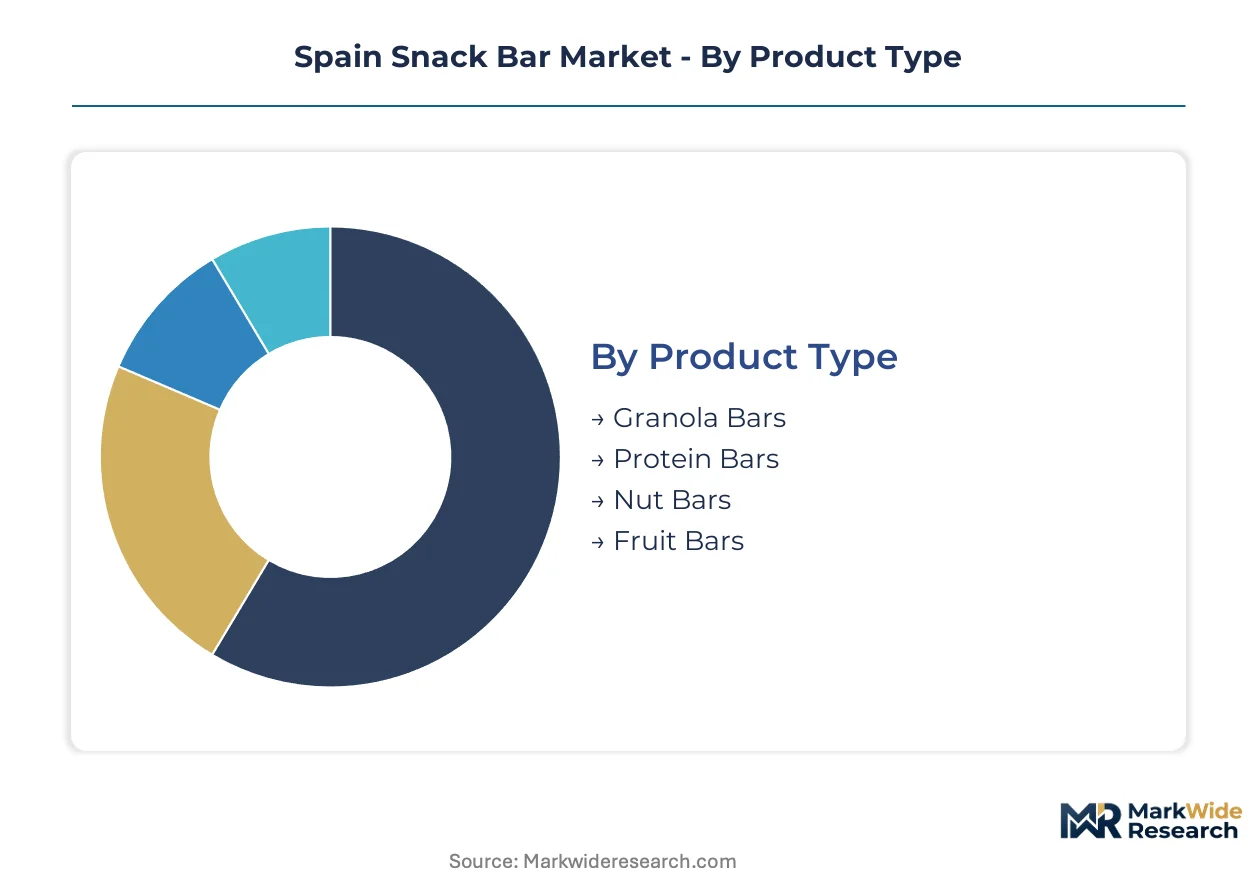
Snack bar segmentation in Spain reveals divergent growth mechanics across product formats and purchase contexts. Understanding these divides helps manufacturers allocate R&D and distribution investments against distinct margin profiles and consumer rituals.
Product Type:
Volume leadership and premium pricing pull in opposite directions across the four product formats, with maturity curves creating strategic windows for repositioning.
- Protein Bars:Whey and plant-isolate formulations dominate Madrid and Barcelona fitness center replenishment, where post-workout consumption has ritualized around 20-30g protein targets. EFSA substantiation requirements for health claims force 12-18 month development cycles, advantaging established players with clinical documentation capabilities.
- Nut Bars:Almond, hazelnut, and olive oil formulations align with Mediterranean diet familiarity among urban households seeking clean-label portability. Coastal corridor demand from Málaga to Cádiz is accelerating as regional ingredient sourcing reduces eurozone dairy commodity exposure.
- Granola Bars:Oat and cereal-based formats retain supermarket volume leadership through Mercadona and Carrefour España shelf presence, though Nutri-Score pressure on sugar content erodes margin sustainability.
- Fruit Bars:Date and dried fruit compositions serve school lunchbox occasions and student convenience channels with lower price elasticity than performance-oriented alternatives.
Mature deployment sits with Granola Bars. Newer deployment is concentrated in Nut Bars.
Customer Type:
Consumption occasion fragmentation separates ritualized replenishment from impulse-driven trial, with procurement authority shifting toward institutional buyers in corporate settings.
- Athletes:CrossFit and triathlon communities in Barcelona's Eixample and Madrid's Salamanca district drive subscription-based direct-to-consumer replenishment, bypassing retail margin stacking entirely.
- Health-Conscious Consumers:Nutri-Score literacy among urban professionals creates preference for A-rated products, with front-of-pack color coding now influencing Mercadona purchase decisions.
- Office Workers:Corporate wellness programs in Madrid's financial district consolidate annual supply contracts with nutritionist-certified brands, compressing vendor counts while rewarding customizable portion formats.
- Students:Budget price tier accessibility through urban convenience channels sustains trial volumes, though brand loyalty remains minimal without subscription lock-in.
Procurement authority is concentrating fastest with Office Workers through facilities management consolidation.
Distribution Channel:
Channel leverage determines margin capture, with buyer concentration in supermarkets clashing against subscription models that eliminate slotting fee burdens.
- Supermarkets:Mercadona and Carrefour España control shelf access through centralized category management, with Nutri-Score compliance now a non-negotiable listing criterion.
- Online Retailers:Monthly replenishment models capture recurring revenue from fitness communities, with Barcelona-based contract manufacturers serving vegan-positioned brands through direct fulfillment.
- Fitness Centers:Boutique gym density in Madrid and Barcelona creates post-workout ritualized purchase occasions, though inventory carrying costs favor branded cooler programs over broad SKU distribution.
- Convenience Stores:Prepared fruit and yogurt parfait counters capture overlapping on-the-go occasions, forcing snack bar placement at checkout to intercept impulse demand.
Margin compression sits with Supermarkets. Margin expansion is concentrating in Online Retailers.
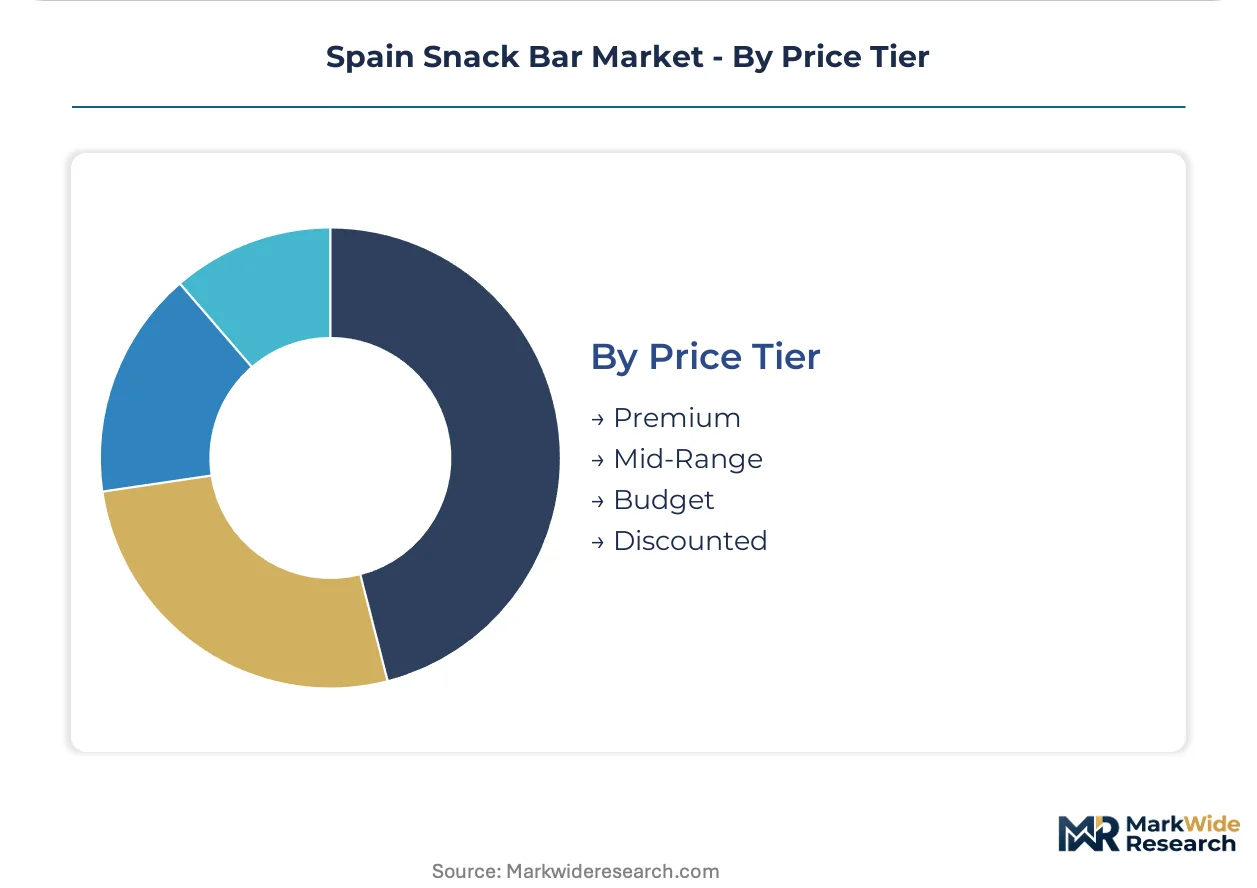
Price Tier:
Three-tier stratification separates clinically validated formulations from commodity alternatives, with mid-range positioning facing squeeze from both directions.
- Premium:Specialized protein formulations with EFSA-approved health claims command shelf space in fitness centers and corporate wellness programs, where procurement prioritizes nutritionist certification over unit cost.
- Mid-Range:Reformulated granola and nut bars with improved Nutri-Score ratings occupy supermarket middle shelves, though differentiation from private label alternatives remains challenging.
- Budget:Price accessibility for students through urban convenience channels sustains volume without loyalty, with Kellanov competing aggressively on this tier.
- Discounted:Promotional depth in supermarket circulars drives trial conversion for new entrants, though margin sustainability requires scale economies absent from mid-tier Spanish co-packers.
Volume concentration sits with Budget. Value capture is climbing the fastest in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish snack bar consumption concentrates in urban coastal corridors while manufacturing capacity clusters near Barcelona and Madrid logistics hubs. This geographic split shapes distribution economics and regional competitive dynamics across the Iberian Peninsula.
Madrid
Boutique fitness center density in Salamanca and Chamberí districts drives protein bar replenishment rituals among affluent professionals. Spain's national food safety agency enforces EU Regulation 1169/2011 on food information transparency, compelling reformulation of sugar-dense portfolios. Corporate wellness programs in the financial district consolidate annual supply contracts with nutritionist-certified brands, compressing vendor counts while rewarding customizable portion formats.
Catalonia
Barcelona's Eixample district anchors CrossFit and triathlon community demand for subscription-based direct-to-consumer replenishment. EFSA guidelines govern nutritional claim substantiation, requiring 12-18 month clinical documentation timelines that advantage established players. Contract manufacturers in the metropolitan area adopt pea and fava protein isolates to serve vegan-positioned brands through direct fulfillment channels.
Andalusia
Underdeveloped snack bar penetration in Málaga and Cádiz fitness markets offers first-mover positioning before competitor saturation. Nutri-Score front-of-pack labeling implementation creates formulation pressure for favorable color ratings. The Mediterranean coastal corridor aligns nut bar demand with regional ingredient familiarity—almonds, hazelnuts, olive oil—among health-conscious households.
Basque Country
San Sebastián and Bilbao demonstrate strong alignment between Mediterranean diet adherence and clean-label portable nutrition preferences. BSI-equivalent standards complement EU-wide frameworks on nutritional claim verification. Industrial food processing heritage in the region supports specialized co-packing capacity for cold-press bar manufacturing.
Valencia
Tourism-dependent consumption patterns in the metropolitan area create seasonal demand volatility for on-the-go snack formats. Mercadona's headquarters proximity influences regional retail buyer consolidation and slotting fee structures. The port logistics infrastructure facilitates import of whey protein isolates given Spain's domestic dairy protein capacity constraints.
Spain Snack Bar Market Competitive Landscape
Top-tier vendors anchor premium protein and clean-label segments, while mid-tier Spanish co-packers struggle with cold-chain extrusion equipment capex requirements. The vendor base stratifies across three capability tiers: multinational CPG conglomerates with clinical documentation resources, regional specialists leveraging Mediterranean ingredient sourcing, and price-competitive private label suppliers. Strategic archetypes include EFSA-certified health claim holders, plant-protein fermentation innovators, and subscription direct-to-consumer operators. Dominant competitive moves center on portfolio diversification into vegan-positioned formats and backward integration into Spanish legume protein sourcing.
Among multinational CPG conglomerates, General Mills Inc., Nestlé S.A., and Kellanov occupy positions that exemplify distinct competitive archetypes. General Mills Inc. represents broad retail penetration capabilities through supermarket shelf presence. Nestlé S.A. anchors premium-tier positioning with specialized formulations targeting athletic segments. Kellanov exemplifies price-tier accessibility strategies for budget-conscious urban convenience channels. These three entities collectively illustrate how vendor scale and geographic origin shape strategic optionality within Spain's Nutri-Score compliance environment.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellanov |
| Nestlé S.A. |
| Abbott Nutrition Manufacturing Inc. |
| Clif Bar & Company |
| PepsiCo Inc. |
| Associated British Foods PLC |
| Post Holdings Inc. |
| Mars, Incorporated |
| Others |
Value Network & Pricing Analysis
EU dairy commodity price volatility cascades through Spain's snack bar supply chain, compressing margins on whey-dependent protein formulations while rewarding manufacturers with backward integration into domestic legume protein sourcing. Nutri-Score compliance costs and Mercadona buyer consolidation reshape pricing power across premium, mid-range, and budget tiers.
Pricing Analysis
Margin tightening in the mid-range tier reflects private label encroachment and Nutri-Score reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified athletic formulations from supermarket granola staples and convenience channel budget bars. Cost-down pressure on standard-tier products accelerates because Mercadona and Carrefour España centralize procurement authority. Students demonstrate highest price sensitivity through urban convenience trial purchases, while corporate wellness programs show lowest sensitivity to unit cost.
Supply Chain Analysis
Reverse logistics for expired or delisted SKUs concentrates in Barcelona and Madrid co-packing hubs, where cold-press equipment limitations constrain refurbishment economics. Raw material sourcing draws from the Netherlands for whey protein isolates, France for hazelnut and almond inputs, and domestic Spanish legume growers for emerging fava and pea protein alternatives. Single-source vulnerability sits with whey import dependency given Spain's absent dairy protein isolate capacity. Distribution runs through Mercadona and Carrefour España's centralized category management, with direct-to-consumer subscription channels bypassing slotting fee structures entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's snack bar market operates as a cost-of-compliance arena where EU Regulation 1169/2011 and EFSA health claim substantiation create regulatory moats favoring incumbents with clinical documentation resources.
For Market Incumbents: To counter private label erosion and Nutri-Score margin compression, Nestlé and General Mills should deepen backward integration into Andalusian fava bean protein sourcing while consolidating shelf access through nutritionist-certified corporate wellness contracts. Certification investment in EFSA-approved health claims maintains premium tier separation.
For New Entrants and Emerging Players: Capture underdeveloped fitness center penetration in Málaga and Cádiz before incumbent saturation, leveraging direct-to-consumer subscription models to bypass supermarket slotting fees. Plant-protein fermentation positioning against imported whey creates differentiated go-to-market entry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Spanish co-packers with cold-press extrusion capability gaps in the Basque Country industrial corridor. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Monitor EFSA protein benefit approval timelines as inflection signal for portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Legume Protein | Fava and pea protein sourcing from Spanish growers reduces eurozone dairy commodity exposure. |
| EFSA Health Claim Certification Investment | Clinical documentation capabilities create 12-18 month barriers against competitor formulation copying. |
| Direct-to-Consumer Subscription Launch | Monthly replenishment models bypass Mercadona slotting fees while capturing CrossFit community recurring revenue. |
| Nutri-Score Reformulation Program | Stevia and monk fruit substitution achieves A-rated front-of-pack positioning for supermarket listing retention. |
| Andalusian Coastal Corridor Distribution Expansion | First-mover positioning in Málaga and Cádiz fitness markets precedes competitor saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with category buyers at Mercadona and Carrefour España, R&D directors at Barcelona contract manufacturers, and facilities managers at Madrid financial district corporate wellness programs. EFSA guidance documents, EU Regulation 1169/2011 implementation notices, and Spanish national food safety agency enforcement records provided regulatory boundary conditions. Bottom-up volume builds from product-type and channel segmentation triangulated against top-down macroeconomic demand indicators.
Data-stream reconciliation across the projection horizon incorporated protein bar, nut bar, granola bar, and fruit bar format splits alongside distribution channel dynamics. Customer type segmentation modeled athletes, health-conscious consumers, office workers, and students with distinct procurement authority patterns. CAGRs derived from regression analysis of historical consumption trends against fitness center density and Nutri-Score implementation timelines. Forecast inputs included whey protein import price indices and boutique gym membership growth trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU-wide nutrient profiling model restrictions and plant-protein fermentation cost curves. Practitioners should monitor EFSA health claim approval pipelines and Mercadona private label expansion for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Snack Products Market
Snacks
Europe Snack Pellets Market
Snacks
UK Snack Market
Snacks
Low Calorie Snack Foods Market
Snacks
Nutritional Bar Market
Snacks
North America Pretzel Market
Snacks
Europe Snack Bar Market
Snacks
Low-Fat Tortillas Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Italy Snack Bar Market
Snacks
Pretzel Salts Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Low Calorie Snacks Market
Snacks
Global Rice Snacks Market
Snacks
Saudi Arabia Snacks Industry Market