
 Austria Snack Bar Market | 2026-2036
Austria Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Snack Bar Market Outlook
Urban commuter snacking is restructuring Austria's snack bar demand profile as rail and transit-oriented consumption expands. Nestle leverages its European supply network to sustain shelf presence across Austrian supermarket chains. General Mills anchors its position through R&D intensity in better-for-you formulations. Atomic Burger competes with localized flavor profiles tailored to Austrian palates.
A snack bar denotes a pre-portioned, shelf-stable food item typically combining cereals, nuts, dried fruits, or savory bases with binding agents, formed through extrusion or cold-press processing and packaged for individual retail sale. These products serve as convenient meal replacements or between-meal energy sources for mobile consumers. Granola bars command the premium tier as protein-fortified variants attract health-seeking professionals, while chips and nuts occupy mature volume positions in family-oriented retail. Vending machines and convenience stores represent the fastest-growing distribution vector as transit hubs modernize their foodservice infrastructure.
Austria's Ministry of Social Affairs enforces food labeling standards through its national consumer protection framework, compelling manufacturers to substantiate nutritional and health claims with verified compositional data. The EU Green Deal's packaging waste directives pressure producers toward recyclable or biodegradable wrapper materials, reshaping supplier selection criteria. Stakeholders must monitor how Austria's transposition of EU single-use plastics regulations will alter cost structures for individually wrapped snack formats.
Market Dynamics
EU Green Deal packaging waste directives are forcing Austrian snack bar producers to reconfigure wrapper material specifications and supplier relationships ahead of compliance deadlines.
Growth Catalysts
- Protein fortification technology:Cold-press extrusion methods now embed whey and plant isolates without texture degradation, expanding formulation possibilities for Vienna-based R&D labs.
- Railway station modernization:ÖBB's transit hub foodservice upgrades across Lower Austria and Styria create dedicated refrigerated and ambient snack bar retail space.
- EFSA nutritional claim pathways:Streamlined substantiation procedures for high-protein and fiber claims accelerate product launch timelines for compliant manufacturers.
Market Restraints
- Oat and nut input volatility:Austrian muesli bar producers face margin pressure from Baltic region oat supply fluctuations and California almond price swings.
- Single-use plastics transposition:Austria's implementation of EU directive 2019/904 imposes biodegradable wrapper mandates that raise unit costs 15-25% versus conventional films.
- Concentrated retail buyer power:REWE and Spar chains command slotting fee structures that compress margins for mid-tier domestic brands.
Strategic Opportunities
- Tyrol alpine tourism corridor:Underdeveloped vending and convenience presence in Innsbruck-Salzburg transit routes offers first-mover positioning for sports nutrition formats.
- CSRD-aligned packaging:Early adoption of cradle-to-cradle certified wrappers opens preferential listing terms with Austrian supermarket sustainability procurement programs.
- Pharmacy channel expansion:Reformulated low-glycemic bars targeting diabetic consumers access Austria's 1,200+ Apotheke locations with distinct regulatory positioning.
Industry Challenges
- Food technologist scarcity:Vienna and Salzburg employers compete for formulation specialists versed in clean-label binding systems and shelf-life extension.
- Dual certification timelines:Parallel EU organic and Austrian AMA Biosiegel approvals extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Snack Bar Market |
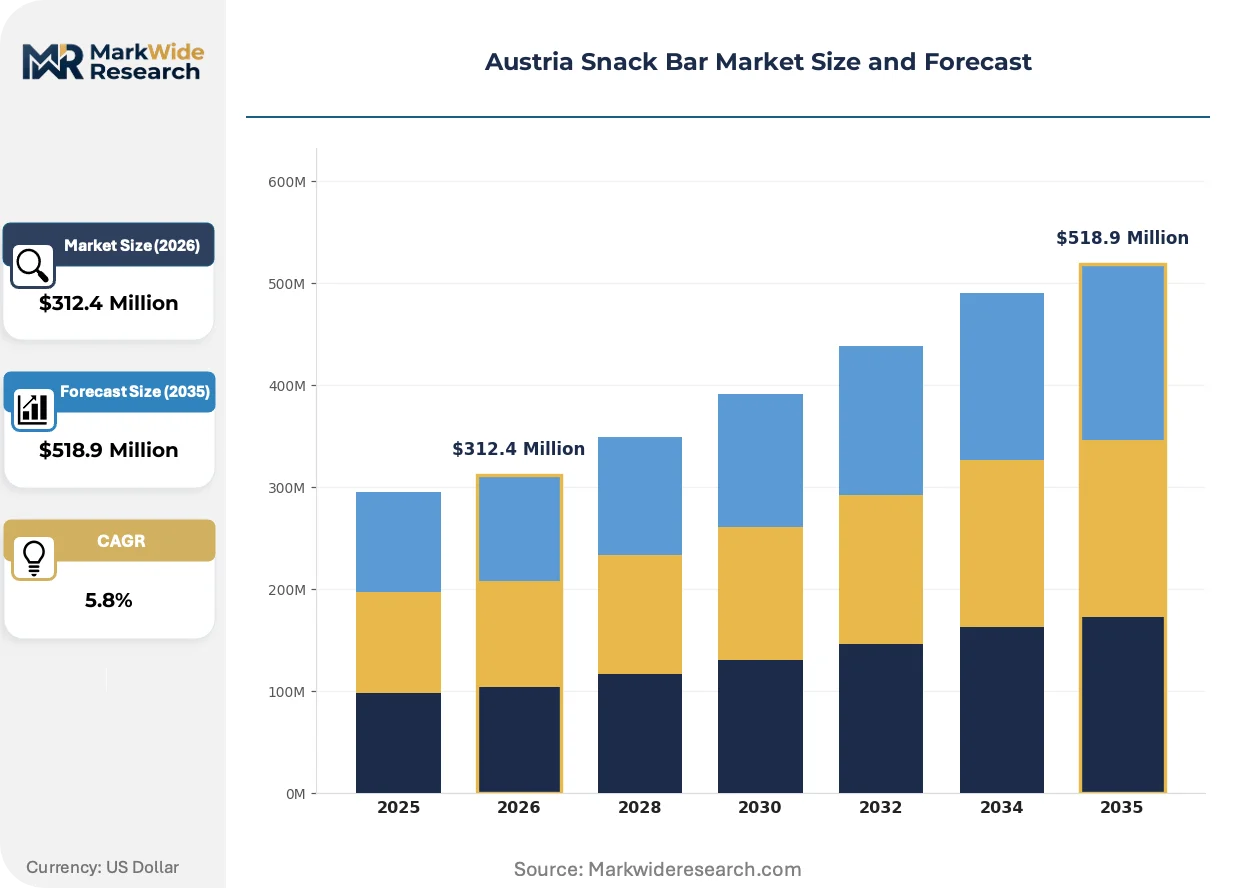
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Granola Bars, Popcorn Price Tier: Premium, Mid-Range, Economy, Discount Distribution Channel: Supermarkets, Convenience Stores, Online, Vending Machines Customer Type: Students, Professionals, Families, Tourists |
| Companies Covered | Nordsee GmbH, Atomic Burger, Wie Ein Wiener, Buffet Koch, Trzesniewski, Norbert Zeilinger GmbH, Sandwich Club, General Mills, Nestle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Snack Bar Market Strategic Shifts
Active packaging materials and cold-press processing advances are compressing traditional thermal extrusion methods while regulatory pressure on wrapper sustainability intensifies supplier selection criteria.
Edible coating technology derived from alginate and pectin composites is absorbing moisture migration control functions previously handled by synthetic barriers. Salzburg-area producers pilot these coatings on nut-dense bars destined for alpine sports retail. The shift is absorbing capital from conventional film lamination equipment and redirecting it toward biopolymer deposition lines.
Austria's transposition of EU Single-Use Plastics Directive 2019/904 mandates biodegradable or recyclable wrapper materials for individually portioned snacks by 2025. Domestic producers face reformulation costs and supplier requalification cycles. Granola and protein bar segments with premium price elasticity absorb these transitions faster than value-tier cereal bars.
Commuter consumption patterns now prioritize grab-and-portion formats over family-size sharing packs. Vienna Hauptbahnhof and Salzburg Hauptbahnhof convenience operators expand ambient snack bar facings at checkout zones. Tyrol's ski resort shuttle networks replicate this transit-oriented merchandising, shifting volume from hypermarket bulk aisles toward impulse-oriented single-serve displays.
Austria Snack Bar Market Segmentation
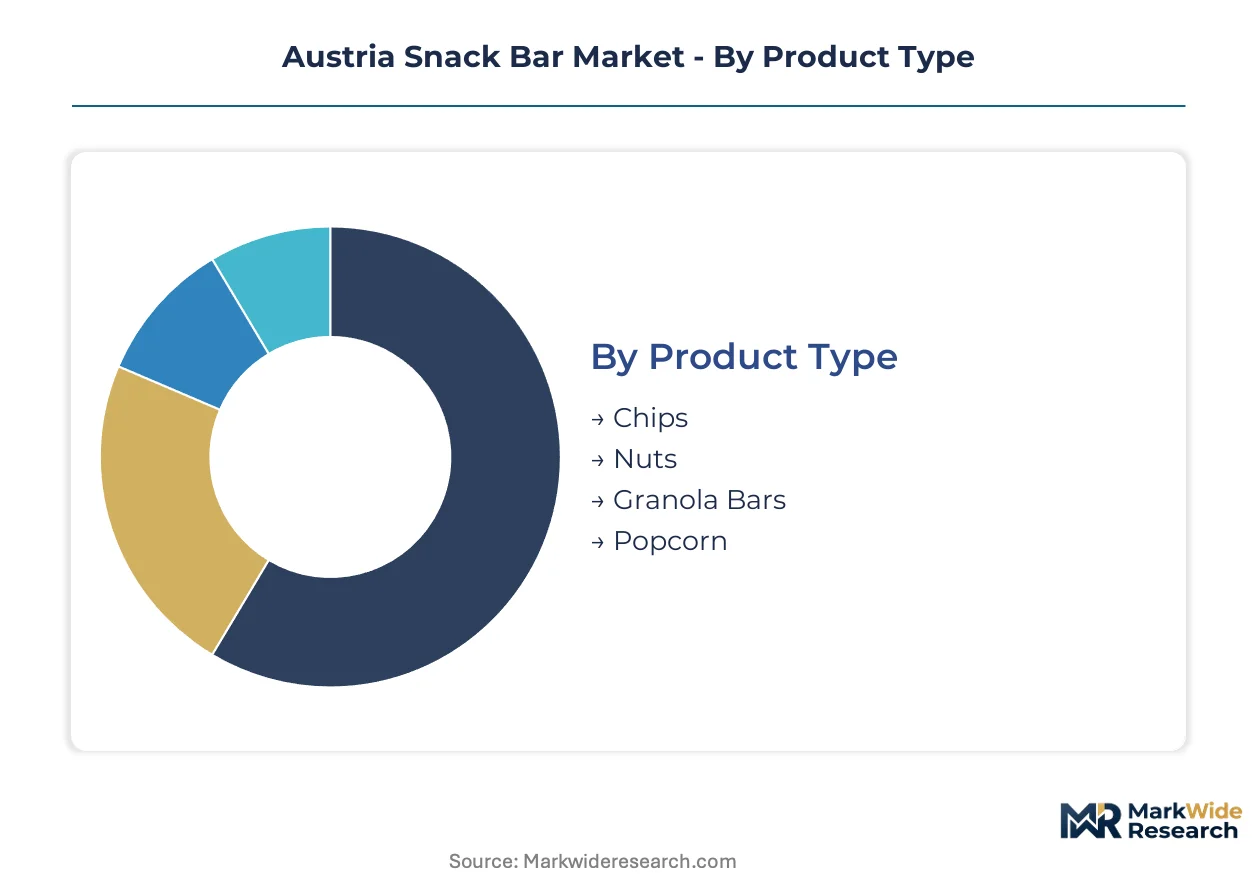
Austrian snack bar producers configure product portfolios across four intersecting dimensions. Each segmentation layer reveals distinct margin structures and channel access requirements that shape competitive positioning in Vienna's concentrated retail environment.
Product Type:
Standalone consumption formats dominate rail and transit channels, while embedded meal-replacement applications expand in professional segments.
- Granola Bars:Cold-pressed oat and nut formulations with protein isolates command shelf space in REWE and Spar premium aisles. Vienna-based professionals drive demand for low-glycemic variants as desk-side meal replacements, with Salzburg health food stores expanding facings for organic-certified lines.
- Chips:Extruded potato and vegetable crisp formats occupy high-velocity positions in family-oriented hypermarkets. Styrian producers face margin compression from Baltic potato input volatility and concentrated buyer power at Billa and Hofer chains.
- Nuts:Roasted and seasoned nut mixes serve trail and alpine sports applications through Tyrol vending networks. AMA Biosiegel certification requirements extend development timelines for value-added flavored variants.
- Popcorn:Air-popped and kettle-corn formats target cinema and entertainment venues in Lower Austria urban corridors. Limited cold-chain requirements suit ambient vending placement at ÖBB station kiosks.
Volume placements concentrate in Chips; the faster expansion belongs to Granola Bars.
Price Tier:
Cost stratification aligns with certification intensity and wrapper material specifications under EU Green Deal compliance timelines.
- Premium:Organic and protein-fortified bars with cradle-to-cradle certified packaging access pharmacy and bio-specialty channels. EFSA substantiation pathways for nutritional claims support price positioning.
- Mid-Range:Conventional granola and nut bars with standard recyclable wrappers dominate Spar and Billa core aisles. Biodegradable film transitions add 15-25% unit cost pressure.
- Economy:Private-label cereal bars at Hofer and Lidl capture price-sensitive family demand. Slotting fee structures compress margins for domestic mid-tier brands.
- Discount:Bulk-format nut and chip assortments serve institutional and foodservice procurement in Styria industrial zones. Minimal packaging investment defends absolute price points.
Mid-Range SKUs generate the broadest channel coverage; Premium tiers are climbing the fastest as sustainability procurement programs expand.
Distribution Channel:
Channel selection determines temperature requirements, facing allocation, and impulse versus planned purchase dynamics.
- Supermarkets:REWE, Spar, and Billa chains command national footprint with dedicated snack bar planograms. Category managers prioritize suppliers with CSRD-aligned packaging documentation.
- Convenience Stores:Railway station and urban corridor formats at Wien Mitte and Salzburg Hauptbahnhof expand ambient snack facings. ÖBB foodservice upgrades create dedicated retail space.
- Online:Direct-to-consumer subscription models for protein bars gain traction among Vienna health-conscious professionals. Cold-chain requirements limit nut and chocolate-coated variant expansion.
- Vending Machines:Tyrol ski resort shuttle networks and alpine transit routes replicate transit-oriented merchandising. Biodegradable wrapper mandates reshape equipment supplier selection.
Supermarkets anchor absolute volume; Vending Machines are gaining share fastest through transit hub modernization.
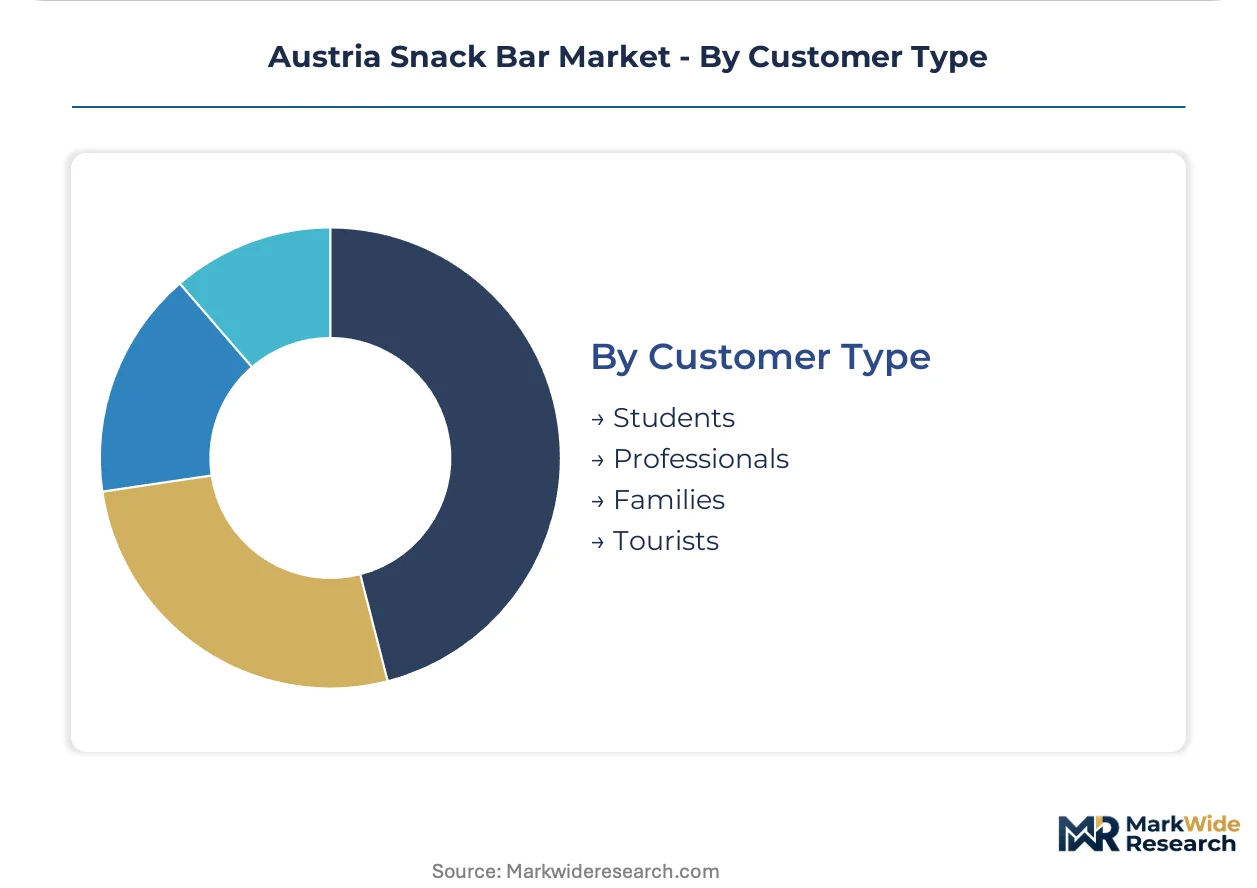
Customer Type:
End-user segmentation maps to occasion-based consumption patterns and nutritional claim sensitivity.
- Professionals:Vienna and Salzburg office workers prioritize protein-enriched bars with EFSA-compliant health claims. Grab-and-portion formats displace family-size sharing packs in commuter channels.
- Families:Multi-pack cereal bars and nut assortments dominate weekly shopping baskets at Lower Austria hypermarkets. Price elasticity concentrates demand in Economy and Discount tiers.
- Students:University corridor vending at Graz and Innsbruck campuses favors impulse-priced single-serve formats. Limited brand loyalty creates entry opportunity for private-label suppliers.
- Tourists:Alpine sports visitors in Tyrol and Salzburg drive demand for trail-ready nut and protein bar formats. Seasonal volume spikes require flexible production scheduling.
Family segments provide baseline volume stability; Professional demand is expanding most quickly through transit channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria's snack bar production concentrates in Vienna and Salzburg manufacturing corridors, while consumption spreads across Lower Austria, Styria, and Tyrol transit corridors. This geographic split shapes regional investment priorities.
Vienna
Vienna's urban professional workforce drives demand for protein-fortified granola bars as desk-side meal replacements. The Ministry of Social Affairs enforces food labeling standards through its national consumer protection framework, compelling manufacturers to substantiate nutritional claims. REWE and Spar headquarters in Vienna command slotting fee structures that compress margins for mid-tier domestic brands.
Salzburg
Salzburg health food stores expand facings for organic-certified snack bar lines targeting health-conscious consumers. EFSA nutritional claim pathways streamline substantiation procedures for high-protein and fiber claims, accelerating product launch timelines. Salzburg-area producers pilot edible coating technology on nut-dense bars destined for alpine sports retail.
Lower Austria
Lower Austria's urban retail corridors anchor family-oriented consumption of multi-pack cereal bars and nut assortments. ÖBB railway station modernization creates dedicated refrigerated and ambient snack bar retail space across transit hubs. Vienna Hauptbahnhof convenience operators expand ambient snack bar facings at checkout zones.
Styria
Styrian producers face margin compression from Baltic potato input volatility and concentrated buyer power at Billa and Hofer chains. EU Green Deal packaging waste directives force reconfiguration of wrapper material specifications ahead of compliance deadlines. Graz university corridor vending favors impulse-priced single-serve formats with limited brand loyalty.
Tyrol
Tyrol's alpine tourism corridor offers underdeveloped vending and convenience presence in Innsbruck-Salzburg transit routes for sports nutrition formats. Ski resort shuttle networks replicate transit-oriented merchandising, shifting volume from hypermarket bulk aisles toward impulse-oriented single-serve displays. Seasonal volume spikes from alpine sports visitors require flexible production scheduling.
Austria Snack Bar Market Competitive Environment
Top-tier vendors anchor premium protein-fortified and organic-certified segments, while regional specialists and private-label suppliers occupy mid-range and economy tiers. The market exhibits tiered concentration with multinational food conglomerates controlling supermarket shelf space through R&D intensity and supply network scale. Three strategic archetypes dominate: global nutrition platforms with European supply integration, localized flavor specialists tailoring formulations to Austrian palates, and private-label contract manufacturers serving discount chains. Competitive moves center on sustainable packaging certification alignment and transit channel expansion through railway station convenience formats.
Among Austria-based specialists, Atomic Burger and Trzesniewski exemplify the localized flavor archetype, occupying positions defined by regional palate adaptation rather than scale economies. General Mills and Nestle represent the global nutrition platform tier, leveraging trans-European supply networks to sustain shelf presence across Austrian supermarket chains. These four companies illustrate the market's bifurcation between scale-driven multinational coverage and niche positioning through cultural specificity.
| Leading Market Players |
|---|
| Nordsee GmbH |
| Atomic Burger |
| Wie Ein Wiener |
| Buffet Koch |
| Trzesniewski |
| Norbert Zeilinger GmbH |
| Sandwich Club |
| General Mills |
| Nestle |
| Others |
Value Chain & Pricing Dynamics
REWE and Spar headquarters in Vienna command slotting fee structures that compress margins for mid-tier domestic brands, forcing producers toward premium-mid-economy pricing differentiation across certification tiers. This buyer concentration shapes how Austrian manufacturers absorb EU Green Deal wrapper compliance costs and defend position against private-label encroachment at Hofer and Lidl.
Pricing Analysis
Margin tightening in mid-range tiers reflects biodegradable wrapper mandates that raise unit costs versus conventional films. Three-tier pricing structure across premium, standard, and economy levels stratifies by AMA Biosiegel certification and cradle-to-cradle packaging credentials. Price differentiation hinges on EFSA-substantiated nutritional claims and cold-press processing premiums. Economy-tier private-label cereal bars at discount chains exhibit highest price sensitivity; pharmacy-channel protein bars with diabetic positioning show lowest elasticity.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale demand from REWE, Spar, and Billa chains, while ÖBB transit hub foodservice upgrades create dedicated ambient snack retail space. Raw material dependencies rest on Baltic region oat supply, California almond inputs, and whey isolate sourcing from European dairy processors. Geographic supply concentration centers on Vienna and Salzburg manufacturing corridors with Styrian potato processing for chip formats. Single-source vulnerability in biodegradable film suppliers reshapes procurement criteria under EU directive 2019/904 transposition deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's snack bar market is consolidating around sustainable packaging compliance and transit channel control, with EU Green Deal wrapper mandates forcing sub-scale domestic brands toward exit or acquisition.
For Market Incumbents: Hedge margin exposure by securing backward integration into cold-press extrusion capacity and locking multi-year biodegradable film supply agreements before 2025 compliance deadlines. Nestle and General Mills should preemptively acquire Vienna-area formulation specialists to capture scarce food technologist talent and accelerate clean-label binding system development. For New Entrants and Emerging Players: Railway station convenience operators at Wien Mitte and Salzburg Hauptbahnhof represent the most penetrable channel white-space, with ÖBB foodservice upgrades creating dedicated retail infrastructure for sports nutrition formats. First-mover positioning in Tyrol's Innsbruck-Salzburg alpine transit corridor offers seasonal volume capture with limited incumbent vending presence. Direct-to-professional subscription models bypass concentrated retail buyer power entirely. For Investors and Strategic Acquirers: The window for entry favors mid-tier domestic brands with AMA Biosiegel certification pipelines and established Spar/Billa listings but insufficient capital for wrapper transition costs. Long-term viability hinges on CSRD-aligned packaging documentation and pharmacy channel access. Watch for EFSA claim substantiation backlogs as inflection indicator for compliant manufacturer scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cradle-to-Cradle Packaging Certification | Opens preferential listing terms with REWE and Spar sustainability procurement programs. |
| Pharmacy Channel Expansion | Reformulated low-glycemic bars access Austria's 1,200+ Apotheke locations with distinct regulatory positioning. |
| Railway Station Convenience Partnership | ÖBB transit hub upgrades create dedicated ambient snack retail space across Lower Austria and Styria. |
| Protein Fortification R&D Investment | Cold-press extrusion methods embed whey and plant isolates without texture degradation for Vienna professionals. |
| Edible Coating Technology Pilot | Salzburg-area producers deploy alginate-pectin composites to replace synthetic moisture barriers in alpine sports formats. |
Study Parameters
Multi-period observation of ÖBB transit hub foodservice investments, AMA Biosiegel certification timelines, and EFSA nutritional claim pathways anchored the trend analysis, supplemented by interviews with category buyers at REWE and Spar, formulation directors at Vienna-based R&D labs, supply planners at Baltic oat processors, and ÖBB foodservice procurement leads. Secondary validation drew from EU packaging waste directive transposition documents, Austrian Ministry of Social Affairs labeling enforcement records, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-weighting across product type, price tier, distribution channel, and customer type dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from trend extrapolation of commuter consumption patterns, protein fortification adoption curves, and biodegradable wrapper cost absorption rates. Industry-specific inputs included ÖBB station modernization capex disclosures and EFSA claim substantiation queue lengths.
Several conditions sit outside the modeled scope, including abrupt EU Green Deal enforcement acceleration, Baltic oat crop failures, and REWE/Spar merger activity. Forecasts reflect assumptions about biodegradable film cost curves and transit channel shelf space allocation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spain Snack Bar Market
Snacks
United States Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Spain Energy Bar Market
Snacks
Jerky Snacks Market
Snacks
Roasted Corn Market
Snacks
Allergy-Free Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
Europe Popcorn Market
Snacks
Cereal Bars Market
Snacks
UAE Snack Bar Market
Snacks
Refrigerated Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Organic Snack Food Market
Snacks
Indonesia Snack Bar Market
Snacks
Crispy Fruit Chips Market