
 Meat Snacks Market | 2026-2036
Meat Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Snacks Market Analysis
Single-serve pouch bundling is pivoting toward variety packs and multi-flavor assortments that let buyers sample across protein types without committing to full-size bags. Jack Link's Protein Snacks leverages its direct-store-delivery network to dominate impulse locations near checkout counters. Tyson Foods anchors its position through captive supply chains that source cattle and poultry for jerky production at scale.
Meat snacks are shelf-stable protein products manufactured through dehydration, smoking, or curing of muscle tissues to achieve moisture levels below water activity thresholds that inhibit microbial growth; they serve as portable nutrition alternatives to carbohydrate-heavy conventional snacks. Beef jerky occupies the mature volume core with established margin pools, while meat sticks capture faster growth among commuter and fitness segments seeking one-handed consumption formats. Whole cuts sustain premium positioning in specialty shops, whereas bites accelerate in online retail channels targeting trial-oriented health-conscious consumers.
The USDA enforces pathogen reduction and labeling standards for meat snacks sold across state lines, while FDA oversight applies to certain dried meat products crossing into dietary supplement positioning. State-level cottage food laws in Texas and California create fragmented compliance thresholds for small-batch producers entering regional convenience store channels. Stakeholders must monitor how evolving sodium reduction mandates and alternative protein labeling disputes reshape formulation roadmaps and channel access requirements.
Market Dynamics
Clean-label preservation technologies and reduced-sodium curing methods are compressing formulation timelines while forcing producers to rebuild their ingredient sourcing networks around natural antimicrobials and alternative curing agents.
Growth Catalysts
- Convenience store channel expansion:Retailers in the United States are dedicating incremental shelf space to protein-forward snacking options near checkout counters, capturing commuter traffic and workplace consumption patterns.
- FDA labeling clarity:Updated guidance on dried meat product classification reduces regulatory ambiguity for producers positioning items between conventional food and dietary supplement categories.
- High-pressure processing:This non-thermal pasteurization technology extends shelf life without chemical preservatives, enabling cleaner ingredient decks that resonate with health-conscious buyers.
Market Restraints
- Beef input cost volatility:Cattle price fluctuations directly compress margin pools for jerky producers dependent on whole-muscle cuts rather than trim-based formulations.
- Supply concentration in Midwest processing:A limited number of USDA-inspected facilities handle the majority of raw material conversion, creating bottleneck risk during peak demand periods.
- Sodium reduction technical limits:Current curing science requires minimum salt levels for pathogen inhibition, constraining how far formulations can respond to cardiovascular health mandates.
Strategic Opportunities
- Direct-to-consumer subscription channels:Monthly variety box models bypass traditional retail slotting fees while building predictable revenue streams for emerging brands.
- Cell-cultured protein integration:Hybrid products blending conventional and lab-grown meat tissues could reshape premium positioning as cultivated technology scales.
- Texas cottage food law expansion:State-level exemptions for small-batch producers lower barrier-to-entry for regional players testing localized flavor profiles before national rollout.
Industry Challenges
- Food safety certification timelines:Obtaining USDA process authority approval for novel preservation methods requires 12-18 month validation cycles that delay product launches.
- Legacy ERP integration with traceability systems:Batch-level tracking mandates for supply chain transparency force mid-size producers to overhaul inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Snacks Market |
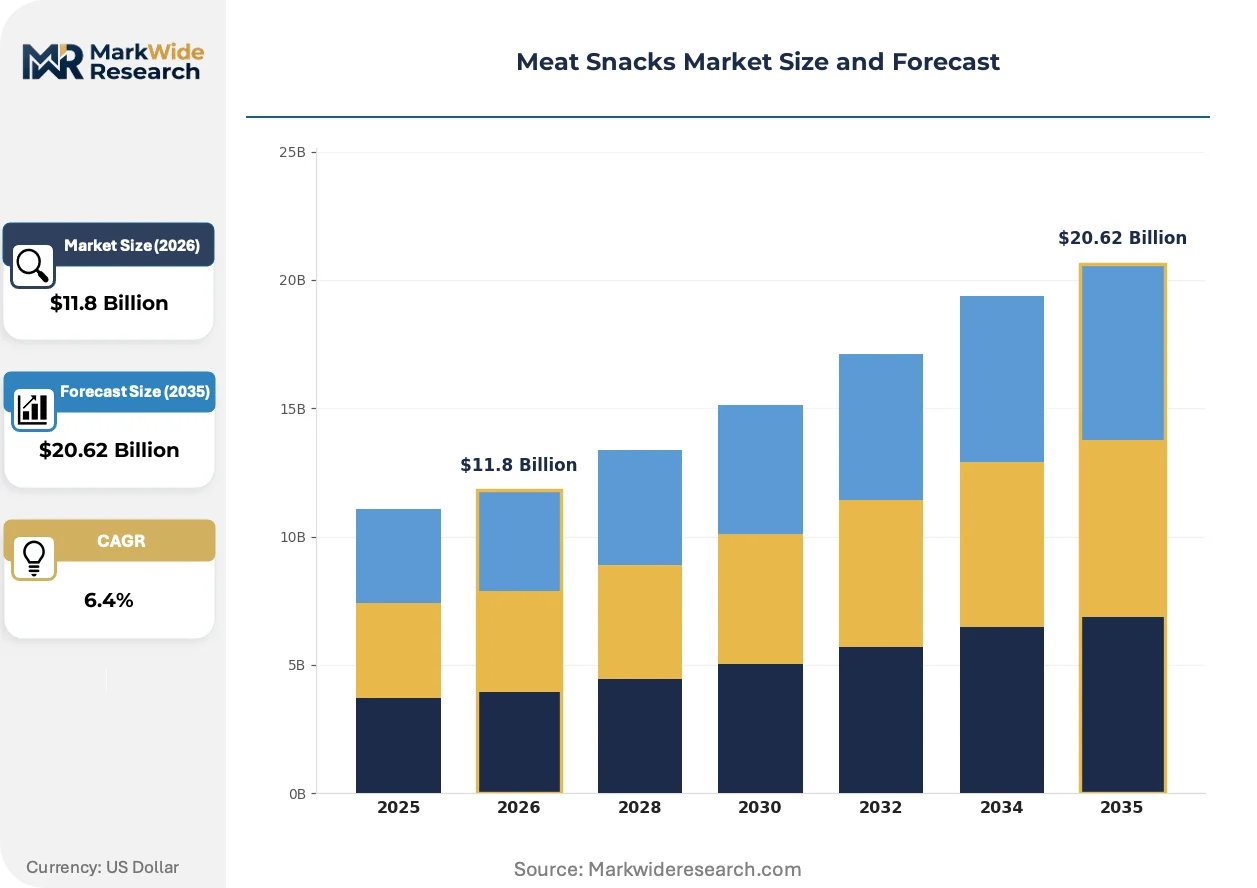
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef Jerky, Turkey Jerky, Pork Rinds, Meat Sticks Form: Whole Cuts, Strips, Bites, Sticks Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Customer Type: Health-Conscious Consumers, Athletes, Busy Professionals, Snack Enthusiasts |
| Companies Covered | Tyson Foods, Inc., Smithfield Foods, Inc., Jack Link's Protein Snacks, LLC, Country Archer Natural Meats, LLC, Oberto Sausage Company, LLC, Conagra Brands, Inc., JBS S.A., Krave Jerky, LLC, Hormel Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Snacks Market Emerging Trajectories
Formulation science and distribution architecture are converging to create portable protein formats that satisfy both sensory expectations and clean-label requirements without sacrificing shelf stability.
High-pressure processing equipment is modularizing across mid-size co-manufacturing facilities, enabling regional brands to access pathogen reduction capabilities previously limited to national players with captive capital investments. Smaller producers in the fitness and specialty segments are adopting this technology at accelerating rates. This capability diffusion is compressing the scale advantages that historically separated mass-market jerky from artisan alternatives.
USDA pathogen reduction standards are tightening verification protocols for Salmonella and Listeria in ready-to-eat meat products, forcing processors to implement environmental monitoring programs with increased sampling frequency. Compliance costs are rising disproportionately for facilities lacking in-house microbiology laboratories. The ready-to-eat jerky segment is responding by consolidating production into fewer, larger facilities with dedicated food safety staff.
Workplace snacking patterns are fragmenting traditional three-meal consumption into continuous micro-eating occasions throughout the day. Single-serve pouches are displacing multi-serving bags in office pantry channels and vending machine networks. This behavioral shift is most visible in United States metropolitan corridors where hybrid work schedules have normalized desk-based protein consumption between video calls.
Meat Snacks Market Segmentation
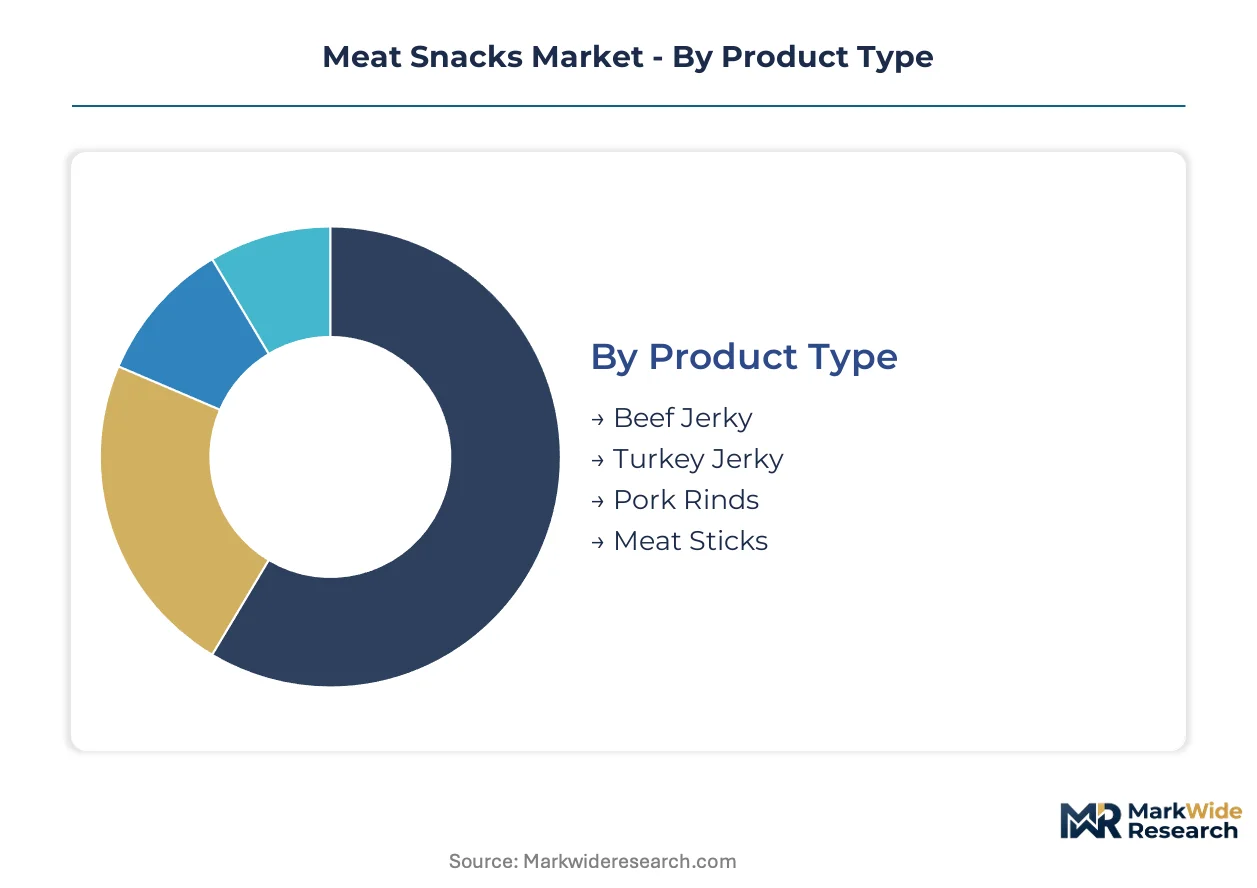
Segmentation in the meat snacks market reveals how protein format, consumption occasion, and channel access determine margin capture. Manufacturers configure product architecture around commuter convenience, fitness routines, and impulse purchase dynamics rather than traditional meal replacement logic.
Product Type:
Volume concentration favors established formats with proven shelf stability, while premium positioning migrates toward novel protein sources and cleaner ingredient decks.
- Beef Jerky:Whole-muscle cuts undergo low-temperature dehydration to achieve water activity below 0.85 for pathogen inhibition. Demand concentrates in United States commuter corridors where single-serve pouches dominate gas station and convenience store checkout placement, constrained by cattle input cost volatility that compresses margin pools for whole-cut formulations.
- Meat Sticks:Emulsified and extruded protein blends enable one-handed consumption formats with uniform texture profiles. Growth concentrates among fitness segments and workplace micro-eating occasions in metropolitan United States markets, driven by portable nutrition needs during hybrid work schedules.
- Turkey Jerky:Lean poultry muscle offers reduced saturated fat positioning for cardiovascular-conscious buyers.
- Pork Rinds:Rendered skin and fat tissue creates crunchy texture alternatives to muscle-based proteins.
Mature deployment sits with Beef Jerky. Newer deployment is concentrated in Meat Sticks.
Form:
Physical configuration dictates consumption occasion compatibility and manufacturing complexity, with whole-cut formats requiring more precise raw material grading than restructured alternatives.
- Whole Cuts:Intact muscle sections maintain fiber alignment and chew resistance that signals premium quality to specialty shop buyers. Demand anchors United States premium retail channels where consumers pay tariff premiums for visible grain structure, constrained by limited USDA-inspected facility capacity for artisan-scale processing.
- Bites:Uniform cubed portions standardize portion control and enable variety pack bundling across protein types. Growth accelerates in online retail channels targeting trial-oriented health-conscious consumers, driven by subscription box models that bypass traditional slotting fees.
- Strips:Sliced muscle with consistent thickness enables predictable dehydration cycles.
- Sticks:Extruded formats accommodate trim-based raw material utilization.
Scale concentration favors Bites for emerging brands. Margin protection sits with Whole Cuts.
Distribution Channel:
Channel selection determines regulatory exposure and working capital requirements, with direct-to-consumer models offering data capture advantages over retail intermediaries.
- Convenience Stores:Impulse-oriented placement near checkout counters captures commuter traffic and workplace consumption patterns across United States metropolitan corridors. Shelf space expansion for protein-forward options drives volume, constrained by direct-store-delivery network requirements that favor established players with captive logistics infrastructure.
- Online Retail:Digital-native channels enable monthly subscription models and flavor variety testing without retail slotting fee burdens. Growth concentrates among emerging brands building predictable revenue streams, driven by traceability demands that favor batch-level inventory management systems.
- Supermarkets:Mass retail placement requires compliance with centralized procurement specifications.
- Specialty Shops:Curated retail environments sustain premium positioning for whole-cut formats.
Volume gravity centers on Convenience Stores. Fastest channel expansion is occurring in Online Retail.
Customer Type:
Protein occasion segmentation separates sustained-energy seekers from impulse-driven buyers, with formulation and packaging architecture tuned to each group's consumption context.
- Busy Professionals:Desk-based micro-eating between video calls creates demand for single-serve, quiet-opening packaging that minimizes disruption. Concentration in United States hybrid work environments drives format innovation, constrained by sodium reduction technical limits that challenge clean-label positioning for cardiovascular-conscious segments.
- Health-Conscious Consumers:Ingredient label scrutiny prioritizes natural antimicrobials and alternative curing agents over conventional preservatives. Demand concentrates in specialty and online channels, driven by high-pressure processing adoption that extends shelf life without chemical additives.
- Athletes:Post-workout protein timing requirements favor rapid-absorption formats.
- Snack Enthusiasts:Flavor novelty seeking supports variety pack and limited-release strategies.
Established demand sits with Busy Professionals. Steepest expansion trajectory is visible among Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of packaged meat snacks while Brazil and Australia supply raw cattle inputs. Processing capacity concentrates in Midwestern US states with USDA-inspected facilities. European demand centers on clean-label cured products with reduced sodium positioning.
United States
Commuter corridor convenience stores and workplace micro-eating patterns drive single-serve pouch demand. The USDA enforces pathogen reduction standards for interstate commerce while FDA oversees products crossing into dietary supplement categories. Chicago and Omaha processing clusters handle bulk conversion for national distribution networks.
Germany
Cardiovascular-conscious buyers favor reduced-sodium cured meats with natural antimicrobial preservation. EFSA guidelines on clean-label additives shape formulation standards across Bavaria and North Rhine-Westphalia. Munich specialty retailers sustain premium positioning for whole-cut artisan products with visible grain structure.
Brazil
Cattle ranching in São Paulo and Minas Gerais states supplies raw material for jerky production exported to North American processors. ANVISA regulates meat product labeling and additive thresholds for domestic consumption. Southern processing corridors near Porto Alegre concentrate trim-based formulations for cost-competitive export markets.
China
Urban professionals in Shanghai and Beijing seek portable protein formats for desk-based consumption between meetings. SAMR enforces GB standards for cured meat safety and labeling requirements. Yangtze River Delta manufacturing clusters experiment with high-pressure processing for extended shelf life without chemical preservatives.
Australia
Grass-fed beef positioning attracts premium export demand from health-conscious Asian markets. FSANZ mandates strict microbiological standards for ready-to-eat meat products. Queensland processing facilities near Brisbane specialize in whole-muscle jerky for specialty retail channels in Japan and South Korea.
Meat Snacks Market Vendor Landscape
The competitive structure tilts toward diversified protein conglomerates with captive supply chains and direct-store-delivery networks. Consolidation pressure favors players controlling cattle and poultry sourcing through backward integration. Three archetypes dominate: vertically integrated meatpackers, specialty jerky brands with regional flavor portfolios, and co-manufacturing platforms serving private-label retailers. M&A activity targets regional brands with authentic positioning, while capacity expansion concentrates in USDA-inspected facilities with dedicated food safety infrastructure.
Among US-based protein conglomerates, Tyson Foods, Inc. and Hormel Foods Corporation exemplify scale-driven archetypes with in-house livestock sourcing. Jack Link's Protein Snacks, LLC anchors the specialty branded tier through impulse-channel dominance near checkout counters. JBS S.A. represents the Brazilian multinational processor archetype with global cattle procurement networks feeding jerky production lines.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Smithfield Foods, Inc. |
| Jack Link's Protein Snacks, LLC |
| Country Archer Natural Meats, LLC |
| Oberto Sausage Company, LLC |
| Conagra Brands, Inc. |
| JBS S.A. |
| Krave Jerky, LLC |
| Hormel Foods Corporation |
| Others |
Supply Flow & Price Mechanics
Single-serve pouch procurement specifications from United States convenience store chains are forcing jerky producers to reconfigure batch sizing and packaging lines, compressing unit economics for whole-muscle formulations while favoring trim-based extruded products with lower input cost sensitivity.
Pricing Analysis
Margin tightening in premium whole-cut tiers reflects cattle price volatility that compresses formulations dependent on USDA Choice grading. Three-tier pricing structure across premium, standard, and economy levels separates visible-grain artisan products from private-label commodity jerky and value-positioned meat sticks. Cost-down pressure on mid-tier SKUs accelerates because retailer slotting fees consume disproportionate working capital. Health-conscious subscription buyers show lowest price sensitivity; gas station impulse purchasers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major retailers mandate USDA-inspected facility qualification across at least two Midwest processing clusters, forcing mid-size brands to split production between Nebraska and Wisconsin co-manufacturers. Raw material flows draw from Brazilian cattle ranching regions, domestic Midwest feedlot operations, and Australian grass-fed export channels. Single-source vulnerability concentrates in high-pressure processing equipment supply, where European and Japanese OEMs control modular system availability. Distribution runs through direct-store-delivery networks anchored by captive logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive cattle supply and in-house pathogen validation laboratories determine who captures shelf space expansion.
For Market Incumbents: Hedge against beef input volatility through backward integration into feedlot partnerships or long-term cattle supply agreements. Secure dedicated food safety staff and in-house microbiology capabilities before USDA tightens environmental monitoring protocols for Salmonella and Listeria. Channel control through direct-store-delivery network density protects impulse placement against emerging brands.
For New Entrants and Emerging Players: High-pressure processing technology adoption offers a technology-first wedge to access shelf-stable production without legacy chemical preservative infrastructure. White-space targets include online subscription channels with monthly variety box models and Texas cottage food law exemptions for regional flavor testing. The most penetrable segment sits with health-conscious consumers seeking clean-label alternatives in specialty retail.
For Investors and Strategic Acquirers: The window for entry favors regional artisan brands with authentic positioning and established USDA process authority approvals. Long-term viability hinges on consolidation into facilities with dedicated food safety infrastructure and traceability system integration. The signal to watch is sodium reduction mandate progression in cardiovascular health policy.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Supply | Captive sourcing from Brazilian and Australian ranching networks insulates margin pools from commodity volatility. |
| High-Pressure Processing Adoption | Modular non-thermal pasteurization extends shelf life without chemical preservatives for clean-label positioning. |
| Direct-to-Consumer Subscription Launch | Monthly variety boxes bypass retail slotting fees while building predictable revenue streams. |
| USDA Process Authority Investment | Dedicated food safety staff and in-house microbiology laboratories accelerate novel preservation validation cycles. |
| Regional Flavor Portfolio Expansion | Texas cottage food law exemptions enable small-batch testing before national rollout. |
Methodological Framework
USDA inspection databases, FDA guidance documents, and customs trade records formed the secondary backbone, cross-referenced with primary interviews involving jerky production facility managers, convenience store category buyers, co-manufacturing procurement leads, and food safety compliance officers. Bottom-up volume estimates derived from SKU-level retail audit data triangulated against top-down protein consumption trend analysis.
Historical trendline analysis established baseline growth patterns across beef jerky, meat sticks, and alternative protein formats. The projection framework modeled segmentation dimensions including product type, physical form, distribution channel, and customer occasion type. CAGRs were derived from elasticity-adjusted demand curves incorporating cattle price cycle inputs and clean-label preference shift parameters.
Several conditions sit outside the modeled scope, including cell-cultured protein regulatory approval timelines and alternative protein labeling dispute resolutions. Forecasts reflect documented assumptions about sodium reduction technical limits and high-pressure processing equipment diffusion rates. Deviation in USDA pathogen reduction standard tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Vegetable Chips Market
Snacks
Savory Snack Products Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Europe Frozen Snacks Market
Snacks
Low Calorie Biscuits Market
Snacks
South America Cereal Bar Market
Snacks
United States Popcorn Market
Snacks
Kids Snacks Market
Snacks
RTE Popcorn Market
Snacks
Sweet Potato Fries Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Snack Pellets Market
Snacks
Specialty Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Poland Snack Bar Market