
 Global Rice Snacks Market | 2026-2036
Global Rice Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Snacks Market Foresight
Premium organic specification tiers is collapsing the gap between commodity rice crackers and certified clean-label offerings. Kameda Seika Co. Ltd. anchors Japanese domestic production with heritage-scale manufacturing of traditional senbei variants. Lundberg Family Farms dominates organic rice cake supply through captive California rice cultivation. PepsiCo Inc. extends its salty snack distribution infrastructure into rice chip placement across North American convenience channels.
Rice snacks encompass processed, shelf-stable food products manufactured from milled or whole-grain rice through baking, puffing, frying, or extrusion, typically achieving moisture content below 5% for extended ambient stability. Their primary commercial purpose centers on delivering portable, gluten-free, low-allergen alternatives to wheat-based crackers and potato chips for on-premise and away-from-home consumption. Puffed rice and rice cakes command the largest volume pools due to established health-positioning and dietetic endorsement, while rice chips generate the fastest value growth as flavor innovation migrates from potato chip portfolios. Bag and multipack formats capture disproportionate margin share through impulse-channel placement and portion-controlled positioning for adult and athlete customer segments.
FDA nutrition labeling rules and USDA organic certification requirements govern product claims and ingredient transparency for North American market access, while EFSA health claim protocols and EU Green Deal packaging recyclability targets constrain formulation and material choices across European supply chains. India's FSSAI fortification guidelines and BIS food safety standards shape domestic manufacturing compliance for export-oriented producers. Stakeholders must monitor evolving clean-label enforcement intensity and carbon-accounting disclosure obligations as procurement criteria tighten across retail and foodservice channels.
Market Dynamics
The EU Green Deal's packaging recyclability mandates are forcing reformulation across rice snack supply chains, as manufacturers abandon multi-layer plastic laminates for mono-material or fiber-based alternatives that meet extended producer responsibility thresholds.
Growth Catalysts
- Clean-label migration:Health-conscious office workers in the United States and Germany are rejecting artificial flavor enhancers, pulling certified organic rice cakes into mainstream convenience retail.
- FSSAI fortification guidelines:India's mandatory micronutrient enrichment protocols for packaged foods are creating compliant product lines that qualify for government school feeding programs and export certification.
- Extrusion technology advances:Twin-screw extrusion systems now achieve texture parity with fried chips at substantially lower oil content, enabling health-positioned rice chip launches.
Market Restraints
- Input cost volatility:Japonica rice premiums in California and Japan fluctuate with water allocation disputes and currency movements, compressing margin stability for organic specialists.
- Supply concentration risk:Heritage-scale senbei production remains concentrated in Niigata Prefecture, exposing buyers to single-region climate and logistics disruptions.
- Regulatory friction:EFSA health claim protocols reject most satiety and glycemic index assertions, limiting functional positioning in European markets.
Strategic Opportunities
- Underpenetrated geography:Brazilian urban consumers lack gluten-free snack alternatives, creating first-mover potential for puffed rice formats in São Paulo and Rio de Janeiro convenience channels.
- Regulatory tailwind:USDA organic certification requirements for processed foods are tightening, advantaging early movers with established supply chain documentation.
- Channel innovation:Direct-to-subscription models for athlete-portioned multipacks bypass conventional retail slotting fees and build recurring revenue.
Industry Challenges
- Certification timeline compression:BIS food safety audits for export-oriented Indian producers now require 90-day documentation cycles that strain quality management systems.
- Packaging reconfiguration friction:Transitioning from metallized films to recyclable structures demands capital investment in sealing equipment and shelf-life validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Snacks Market |
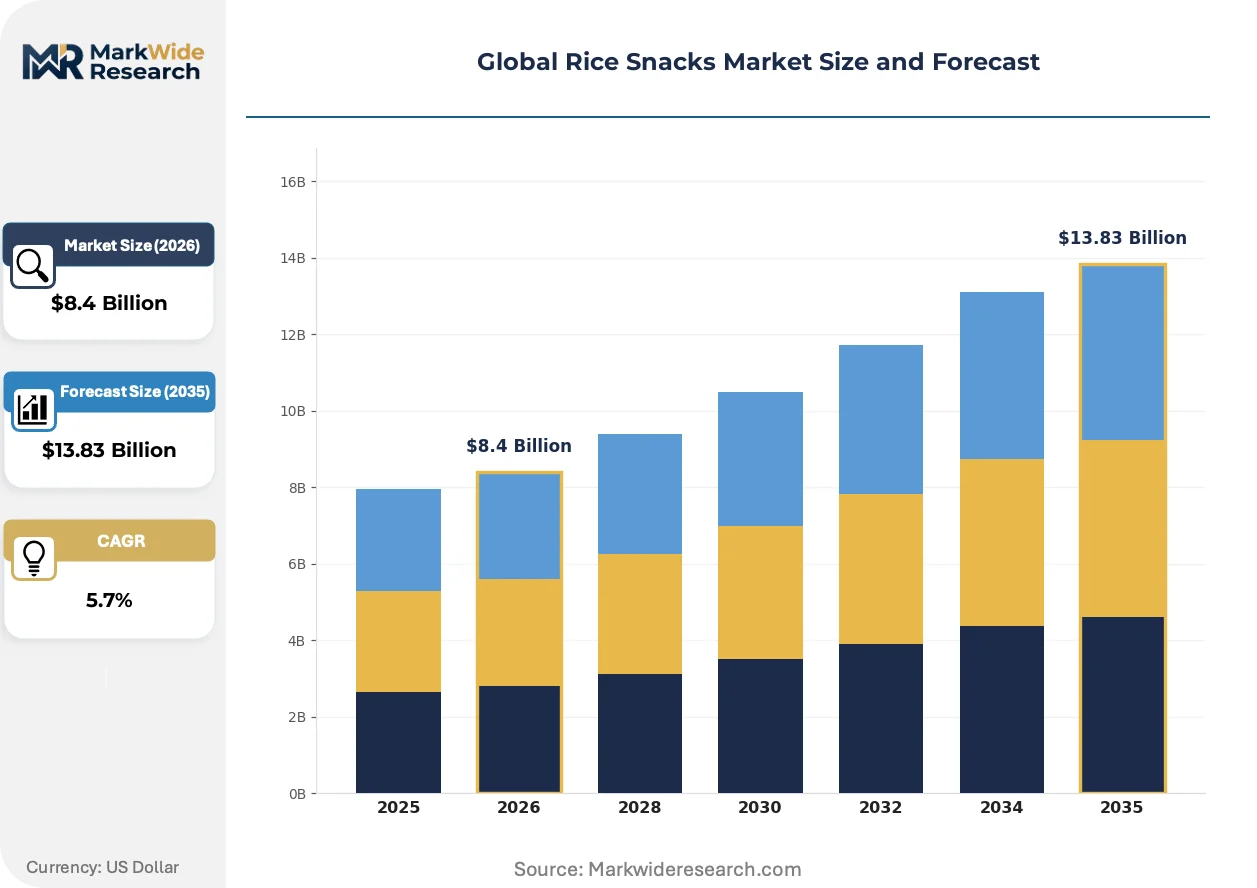
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puffed Rice, Rice Crackers, Rice Cakes, Rice Chips, Rice Thins Flavor: Salted, Barbecue, Sour Cream & Onion, Spicy, Cheese, Sweet Packaging Type: Bag, Box, Tray, Multipack, Bulk Pack Customer Type: Children, Adults, Athletes, Elderly, Office Workers |
| Companies Covered | PepsiCo Inc., General Mills Inc., Kameda Seika Co. Ltd., Nestlé S.A., Element Snacks Inc., Hunter Foods LLC, Lundberg Family Farms, Calbee Inc., Want Want Holdings Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Snacks Market Shifts & Advancements
Flavor innovation pipelines are migrating from potato chip portfolios into rice-based formats, while processing equipment suppliers retrofit legacy extrusion lines for reduced-oil output specifications.
High-pressure extrusion is displacing conventional frying as the dominant texturizing method for rice chips, with European contract manufacturers retrofitting lines to achieve the expanded cellular structure that mimics fried mouthfeel. German and Dutch snack brands are adopting these systems fastest, responding to consumer rejection of palm oil and acrylamide concerns. The technology is displacing older batch-puffing equipment in mid-scale facilities that previously lacked capital for continuous-process alternatives.
REACH chemical safety protocols are extending scrutiny to processing aids and anti-caking agents used in rice flour preparation, forcing suppliers to substitute titanium dioxide and certain lubricants with food-grade alternatives. This regulatory pressure cascades through ingredient certification requirements, with EFSA now demanding full supply chain disclosure for imported rice substrates. Organic rice cake producers in Italy and France face the steepest compliance costs, as their premium positioning requires absolute ingredient transparency.
Millennial consumers in Indian metropolitan areas are treating rice-based snacks as everyday convenience foods rather than festival-only items, collapsing the traditional seasonality that governed production planning. This consumption-pattern shift is pulling single-serve pouches into kirana stores and quick-commerce platforms that previously stocked only bulk formats. Mumbai and Bangalore exhibit the fastest channel rotation, with dark-store operators now carrying dedicated rice snack SKUs for 10-minute delivery promises.
Global Rice Snacks Market Segmentation
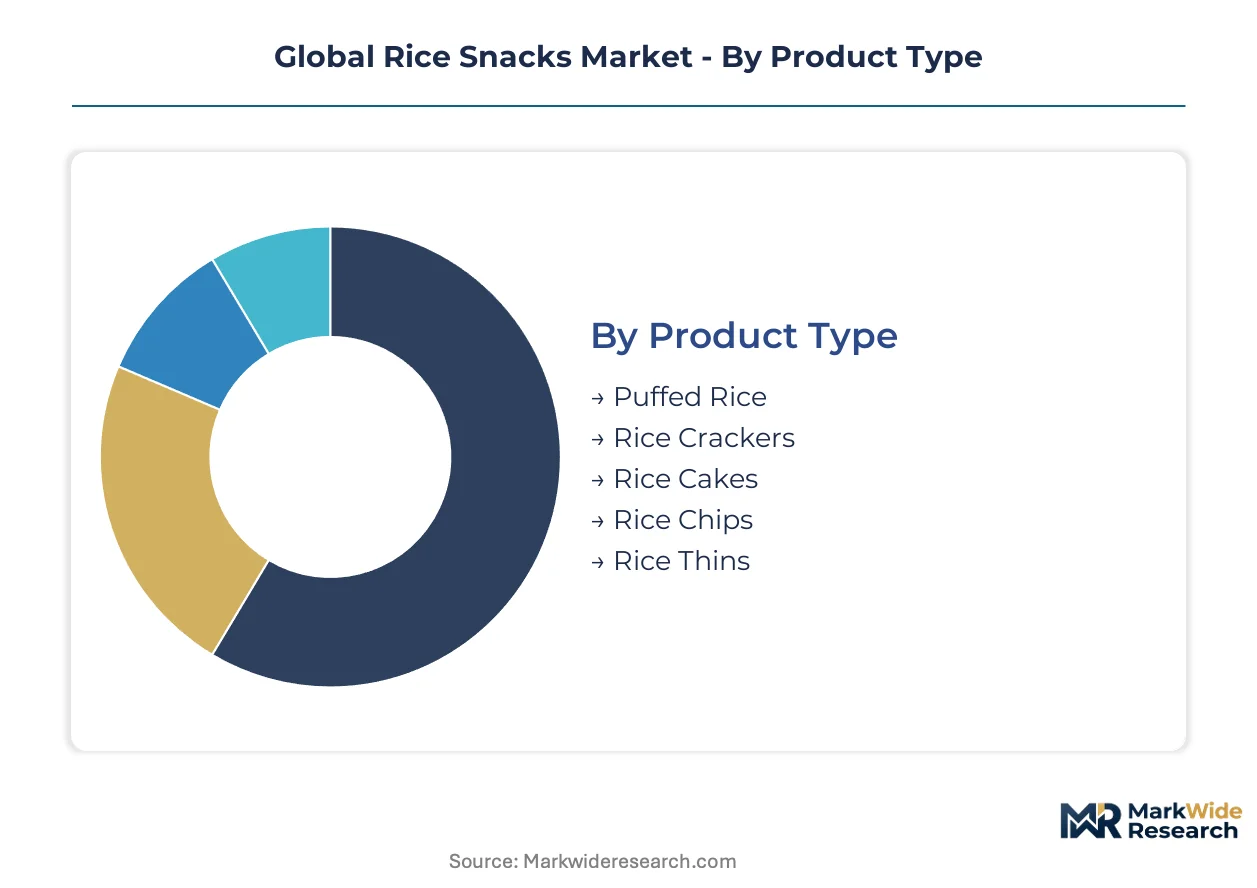
Rice snack manufacturers configure production lines around distinct consumption moments and channel requirements. Segment boundaries determine capital allocation, flavor R&D priorities, and packaging format investments across the value chain.
Product Type:
Domestic markets in India and Japan absorb heritage formats, while export-led growth concentrates in extruded rice chips and clean-label rice cakes for North American and European health-positioned retail.
- Puffed Rice:Traditional batch-puffed grains achieve cellular expansion through steam pressure release, yielding 8-12% final moisture. Indian urban households consume single-serve pouches as breakfast substitutes, while European organic specialists position heritage varieties as gluten-free cereal alternatives.
- Rice Cakes:Whole-grain brown rice cakes command premium shelf placement through dietetic endorsement and low-calorie positioning. Lundberg Family Farms anchors supply through captive California cultivation, with German and Dutch retailers expanding private-label organic ranges.
- Rice Crackers:Japanese senbei variants dominate heritage export categories, with Niigata Prefecture producers supplying ceremonial gift markets across East Asia.
- Rice Chips:Extruded and sheet-formed alternatives to potato chips achieve fastest value expansion through flavor innovation migration.
- Rice Thins:Ultra-thin baked formats target cracker replacement occasions with reduced oil content specifications.
Puffed rice and rice cakes hold the largest share; momentum sits with rice chips.
Flavor:
Flavor development costs stratify sharply, with clean-label natural extracts commanding 3-4x synthetic enhancer expenses and determining margin tier entry.
- Salted:Minimal ingredient declarations satisfy clean-label purists but limit differentiation in crowded European organic aisles where sodium reduction targets intensify.
- Spicy:Chili and masala profiles dominate Indian domestic consumption, with Mumbai and Bangalore quick-commerce platforms reporting fastest SKU rotation for heat-indexed variants.
- Barbecue:Smoke and molasses notes migrate from potato chip portfolios into rice-based formats through natural flavor house partnerships.
- Sour Cream & Onion:Dairy-derived and vegan alternatives split the category, with EFSA health claim constraints limiting functional positioning.
- Cheese:Nutritional yeast and fermented rice protein substitutes address vegan and lactose-intolerant segments in German and Dutch markets.
- Sweet:Japonica rice bases support mochi-adjacent confectionery formats in Japanese export channels.
Salted variants anchor volume; sweet and spicy profiles are climbing the fastest.
Packaging Type:
Format selection determines channel access, with EU Green Deal recyclability mandates forcing mono-material transitions that eliminate metallized barrier films.
- Bag:Pillow and stand-up pouches dominate impulse channels, with German retailers now requiring mono-material or fiber-based structures meeting extended producer responsibility thresholds.
- Multipack:Portion-controlled clusters target athlete and office worker segments through subscription and convenience channel placement, bypassing conventional slotting fees.
- Box:Rigid paperboard formats support premium gift positioning in Japanese ceremonial markets and Indian festival segments.
- Tray:Thermoformed structures with resealable lidding protect fragile senbei and rice cracker assortments in export logistics.
- Bulk Pack:Foodservice and ingredient-channel formats supply European contract manufacturers and Indian school feeding programs.
Bag formats hold the largest share; multipacks show the steepest expansion trajectory.
Customer Type:
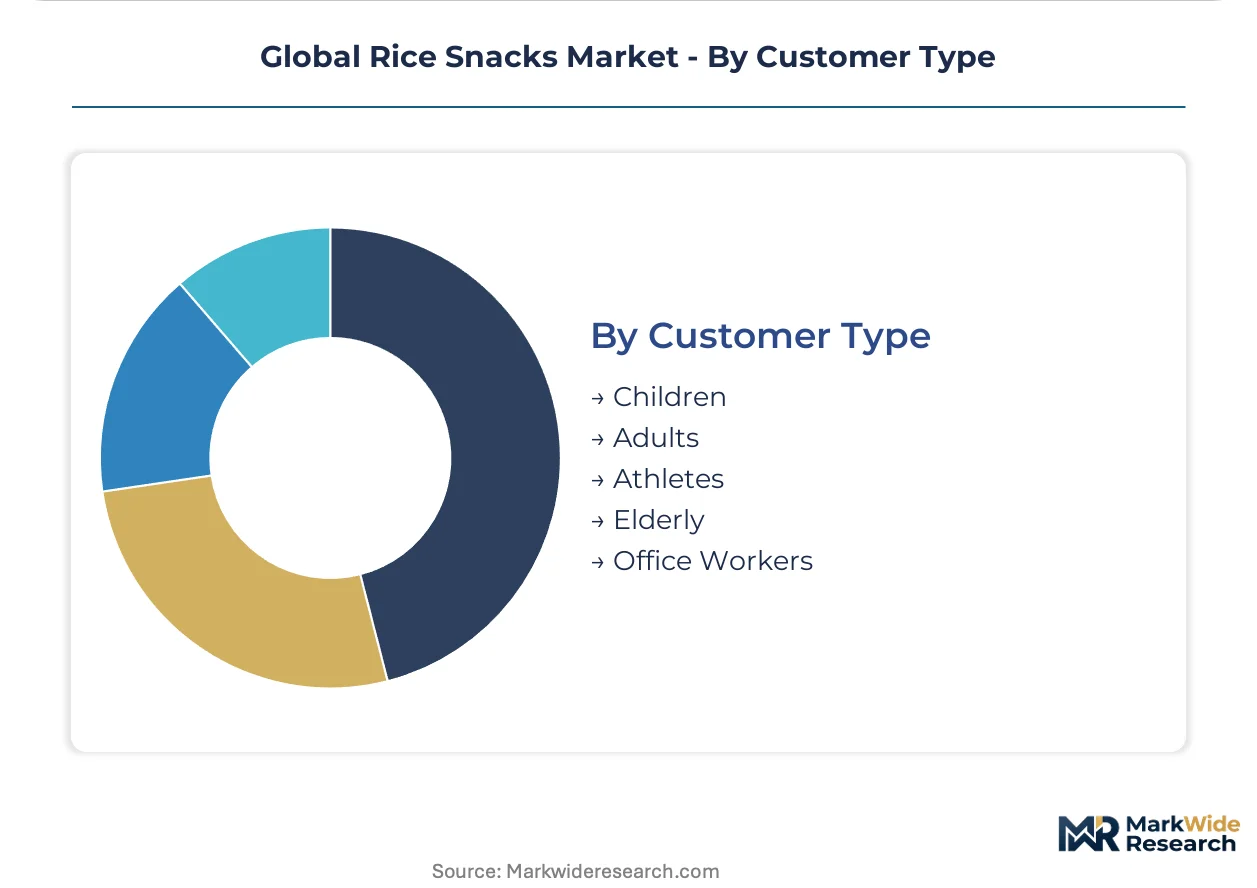
Athlete and office worker segments drive premium pricing power, while children and elderly categories face intense private-label competition and fortification compliance costs.
- Adults:Health-conscious professionals in the United States and Germany reject artificial flavor enhancers, pulling certified organic rice cakes into mainstream convenience retail through clean-label migration.
- Office Workers:Desk-based consumption occasions favor portion-controlled, low-mess formats with protein fortification claims, though EFSA protocols reject most satiety assertions.
- Athletes:Macro-balanced, high-protein rice chip variants command subscription channel premiums through direct-to-consumer models that build recurring revenue.
- Children:FSSAI fortification guidelines create compliant product lines qualifying for government school feeding programs, with shape and color novelty driving trial.
- Elderly:Texture-modified, low-sodium formats address chewing difficulty and hypertension management in Japanese and South Korean aging populations.
Adults hold the largest share; athletes and office workers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in rice snacks favor Asian heritage producers shipping traditional formats westward, while North American and European buyers import premium organic specifications and extruded innovations. Trade patterns concentrate value capture in origin-country processing rather than commodity grain export.
United States
Health-conscious office workers in California and New York Metro drive clean-label rice cake demand through convenience retail channels. FDA nutrition labeling rules and USDA organic certification requirements govern product claims and ingredient transparency for market access. Lundberg Family Farms anchors supply through captive California rice cultivation, while extruded rice chip startups populate Austin and Denver food innovation clusters.
Japan
Ceremonial gift markets across East Asia sustain heritage senbei exports from Niigata Prefecture producers. METI standards and JIS food safety protocols shape manufacturing compliance for traditional formats. Kameda Seika Co. Ltd. anchors domestic production with heritage-scale manufacturing, while Tokyo-based distributors manage regional export logistics to Taiwan and South Korea.
Germany
Organic specialists in Bavaria and North Rhine-Westphalia position heritage puffed rice varieties as gluten-free cereal alternatives. EFSA health claim protocols and EU Green Deal packaging recyclability targets constrain formulation and material choices across supply chains. Cologne and Düsseldorf retailers now require mono-material structures meeting extended producer responsibility thresholds, forcing packaging reconfiguration.
India
Urban millennial consumers in Mumbai and Bangalore treat rice-based snacks as everyday convenience foods rather than festival-only items. FSSAI fortification guidelines and BIS food safety standards shape domestic manufacturing compliance for export-oriented producers. Dark-store operators in Maharashtra and Karnataka now carry dedicated rice snack SKUs for 10-minute delivery promises, collapsing traditional seasonality.
Brazil
Urban consumers in São Paulo and Rio de Janeiro lack gluten-free snack alternatives, creating first-mover potential for puffed rice formats in convenience channels. ANVISA food safety protocols govern imported packaged food registration and labeling requirements. Local distributors in the Southeast region are testing Asian-imported rice cracker placement in premium supermarket chains targeting health-aware middle-class segments.
Global Rice Snacks Market Competitive Landscape
Concentration sits with diversified multinational snack conglomerates controlling North American and European distribution infrastructure, while heritage Asian specialists and organic pure-plays occupy differentiated tiers. The vendor base stratifies across three archetypes: global salty snack giants leveraging existing retail relationships, traditional Japanese and Taiwanese heritage manufacturers defending ceremonial export niches, and organic-certified regional growers capturing premium pricing through supply chain transparency. Competitive moves center on portfolio diversification into adjacent better-for-you formats and geographic expansion through distributor partnerships rather than direct market entry.
Within the heritage manufacturing tier, Kameda Seika Co. Ltd. and Calbee Inc. exemplify traditional scale advantages in East Asian domestic markets, while Lundberg Family Farms occupies a position among organic pure-plays with captive agricultural integration. PepsiCo Inc. represents the diversified conglomerate archetype, extending salty snack distribution infrastructure into rice chip placement across North American convenience channels. These three patterns—heritage scale, agricultural integration, and distribution leverage—define competitive positioning across price-performance segments.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| General Mills Inc. |
| Kameda Seika Co. Ltd. |
| Nestlé S.A. |
| Element Snacks Inc. |
| Hunter Foods LLC |
| Lundberg Family Farms |
| Calbee Inc. |
| Want Want Holdings Ltd |
| Others |
Supply & Pricing Matrix
USDA organic certification requirements for processed foods gate both supply qualification and price differentiation simultaneously, forcing non-compliant producers into commodity tiers while certified operators capture premium shelf placement through transparency documentation.
Pricing Analysis
Health-conscious office workers anchor a three-tier pricing structure across premium, standard, and economy levels in North American and European retail. Price differentiation rests on certification grade and brand heritage, with Japonica rice premiums fluctuating alongside water allocation disputes in California. Cost compression in organic tiers is intensifying because input volatility and packaging reconfiguration demands strain quality management systems. Private-label buyers exhibit highest price sensitivity, while athlete-segment subscribers tolerate recurring premiums for macro-balanced formulations.
Supply Chain Analysis
Inventory cycles stretch from harvest through extended producer responsibility compliance validation, with lead times elongating for mono-material packaging transitions. Supply concentrates in India, Japan, and the United States, drawing from Japonica rice cultivation, heritage-scale senbei manufacturing, and captive organic cultivation respectively. Single-source vulnerability runs through Niigata Prefecture's climate-exposed heritage production. Distribution runs through convenience retail channels, quick-commerce platforms, and direct-to-subscription models bypassing conventional slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as interoperability between quick-commerce dark stores and heritage manufacturer ERP systems collapses traditional distribution bottlenecks.
For Market Incumbents: Fortify supply chain documentation against tightening FSSAI fortification guidelines and EU Green Deal packaging mandates. Invest in captive California rice cultivation or equivalent upstream control to defend margin position against Japonica premium volatility. Deepen channel partnerships with Mumbai and Bangalore dark-store operators before subscription models lock in athlete-segment loyalty. For New Entrants and Emerging Players: Differentiate on clean-label extrusion technology that achieves fried-chip texture parity at reduced oil content. Target Brazilian urban convenience channels in São Paulo and Rio de Janeiro, where gluten-free snack alternatives remain underpenetrated. Pursue ANVISA registration partnerships with Southeast regional distributors testing Asian-imported placement in premium supermarket chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed organic pure-plays lacking dark-store integration capabilities. Long-term viability favors operators with backward integration into heritage-scale manufacturing or captive agricultural supply. Watch for inflection when quick-commerce platforms consolidate rice snack SKUs into exclusive supply arrangements, signaling platform capture of category economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | EU Green Deal mandates force abandonment of metallized films for recyclable structures meeting extended producer responsibility thresholds. |
| Dark-Store Distribution Partnership | Mumbai and Bangalore operators now carry dedicated SKUs for 10-minute delivery promises, collapsing traditional seasonality. |
| Heritage Scale Manufacturing Acquisition | Niigata Prefecture producers supply ceremonial gift markets across East Asia with climate-exposed concentration risk. |
| Direct-to-Subscription Model Launch | Athlete-portioned multipacks bypass conventional retail slotting fees and build recurring revenue through macro-balanced positioning. |
| High-Pressure Extrusion Retrofit | German and Dutch contract manufacturers adopt continuous-process alternatives achieving texture parity with fried chips at lower oil content. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with brand managers, category buyers at retailers, channel sales heads, and supply planners; and secondary validation through Nielsen retail audit data, customs records, FSSAI fortification filings, and EU packaging compliance disclosures. Bottom-up volume modeling triangulated against top-down category sizing across product type, flavor profile, packaging format, and customer segment dimensions.
Across the analysis window, CAGRs were derived from segmented growth trajectory modeling incorporating clean-label migration velocity, extrusion technology adoption curves, and quick-commerce penetration rates. The analytical framework projected value expansion through flavor innovation pipelines migrating from potato chip portfolios and health-positioned rice chip launches displacing conventional fried alternatives.
Material uncertainties — regulatory enforcement intensity for carbon-accounting disclosure, currency movements affecting Japonica rice premiums, and climate disruption in single-region heritage production — sit outside the modeled envelope. Forecasts reflect documented assumptions about consumer rejection of artificial flavor enhancers and platform economics consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Instant Meat Marinated Snacks Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Low Fat Protein Snacks Market
Snacks
Australia Snack Bar Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Low-Fat Tortillas Market
Snacks
Snack Subscription Market
Snacks
South Korea Snack Bar Market
Snacks
North America Energy Bar Market
Snacks
Specialty Snacks Market
Snacks
Fruit Jerky Market
Snacks
Kids Snacks Market
Snacks
Oat-Based Snacks Market
Snacks
South America Protein Bar Market
Snacks
Popcorn Market