
 Solar Autoclave Market | 2026-2036
Solar Autoclave Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Autoclave Market Analytics
India is reconfiguring regional supply chains through dedicated solar manufacturing zones in Gujarat and Tamil Nadu. Getinge AB leverages its European installed base to anchor aftermarket service revenues in emerging markets. Tuttnauer competes on compact system portability for remote deployment. Shinva Medical Instrument dominates domestic Chinese production capacity for high-pressure hospital-grade units.
A solar autoclave harnesses concentrated solar thermal energy or photovoltaic-driven resistive heating to achieve saturated steam temperatures of 121–134°C at 15–30 psi for sterilization cycles. The device eliminates fuel dependency in off-grid settings while maintaining the same lethality assurance as conventional steam sterilizers against bacterial spores and enveloped viruses. Compact and mobile product types lead unit shipments due to last-mile healthcare logistics constraints, though stationary high-pressure systems capture disproportionate margin pools from centralized hospital procurement. Hybrid technology configurations pairing solar thermal pre-heating with electric backup are gaining fastest traction as reliability requirements tighten for surgical instrument applications.
FDA 510(k) clearance pathways and EPA sterilization efficacy standards govern US market access, while India's CDSCO medical device rules and BIS pressure vessel certifications shape domestic manufacturing compliance. The EU MDR and F-Gas Regulation additionally constrain refrigerant-based auxiliary cooling systems in European-bound equipment. Stakeholders must monitor evolving national sterilization assurance guidelines and solar import tariff schedules to calibrate regional production footprints.
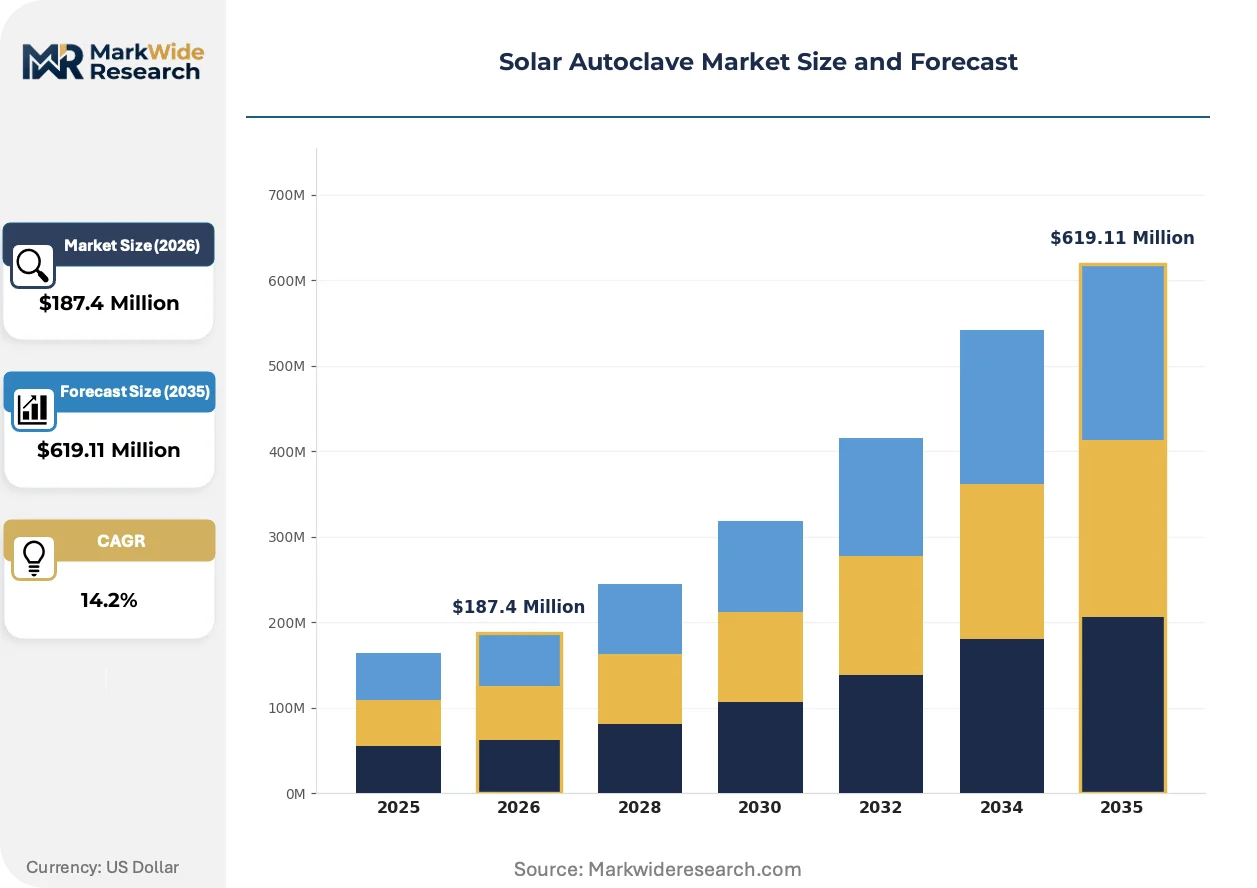
Market Dynamics
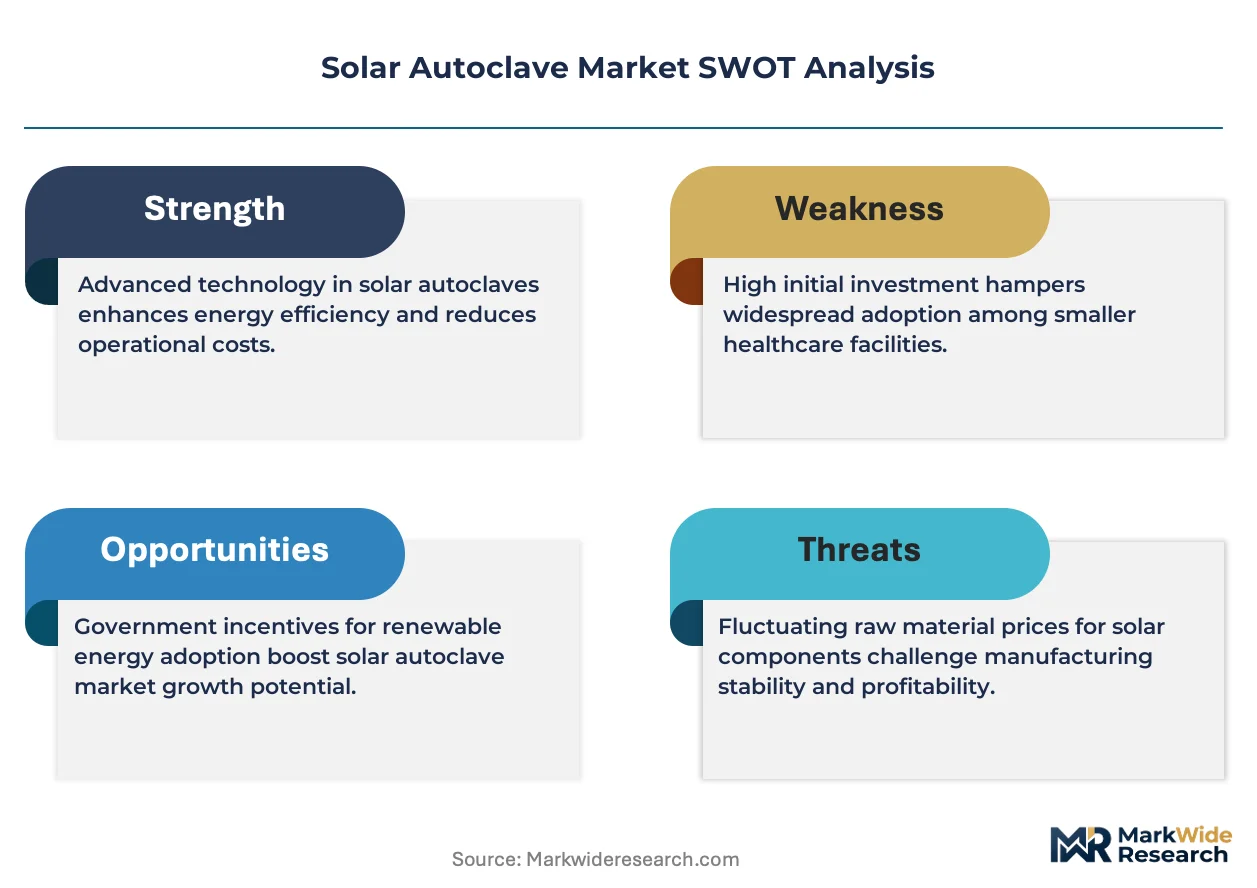
Hybrid solar-thermal-electric configurations are compressing sterilization cycle reliability gaps in off-grid surgical settings. Equipment manufacturers now face pressure to certify dual-mode systems under divergent national pressure-vessel and medical-device frameworks simultaneously.
Growth Catalysts
- India's National Rural Health Mission:Decentralized procurement mandates for primary health centers are creating dedicated budget lines for solar-powered sterilization infrastructure in sub-district facilities.
- Photovoltaic module cost trajectories:Falling crystalline silicon prices are reducing the capital threshold for clinic-grade autoclave electrification below diesel-generator parity in sun-rich latitudes.
- WHO sterilization assurance guidelines:Updated technical specifications for low-resource settings are legitimizing solar thermal as equivalent to fuel-fired steam for spore lethality validation.
Market Restraints
- Battery storage cost volatility:Lithium-ion price swings and cobalt supply concentration in the Democratic Republic of Congo are inflating hybrid system total cost of ownership.
- Pressure vessel steel tariffs:Import duties on certified boiler-grade alloys in India and Brazil are elongating domestic manufacturing lead times.
- Solar thermal collector efficiency ceilings:Flat-plate and evacuated-tube designs plateau below 70% optical efficiency, constraining steam generation rates in high-humidity monsoon zones.
Strategic Opportunities
- Kenya's off-grid healthcare electrification:County-level health budgets under devolution are unlocking capital expenditure autonomy for solar medical equipment in arid and semi-arid counties.
- Convergence with desalination:Co-located solar thermal plants are enabling dual-output configurations producing both sterile steam and purified water for surgical suites.
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon-based auxiliary cooling are accelerating demand for thermoelectric or absorption-based alternatives in European-bound equipment.
Industry Challenges
- Pressure vessel welder certification:Shortages of ASME Section IX-qualified technicians in sub-Saharan Africa are constraining localized manufacturing scale-up.
- FDA 510(k) sterilization equivalence documentation:Bioburden validation studies for solar-derived steam require 18-24 month timelines, delaying US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Autoclave Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Mobile, Stationary, High-Pressure End User: Healthcare Facilities, Research Labs, Dental Clinics, Veterinary Clinics Technology: Thermal, Solar Thermal, Hybrid, Electric Application: Surgical Instruments, Laboratory Equipment, Dental Tools, Waste Treatment |
| Companies Covered | Getinge AB, STERIS plc, Tuttnauer, Belimed AG, Astell Scientific, MELAG Medizintechnik, Shinva Medical Instrument, Panasonic Healthcare, Celitron Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Autoclave Market Evolving Landscape
Equipment architectures are bifurcating between ultra-portable field units for emergency deployment and fixed installations with integrated battery buffers. This divergence is fragmenting R&D budgets across incompatible performance specifications.
Parabolic trough concentrators with direct steam generation are collapsing the cost delta between solar thermal and resistive electric heating in high-throughput hospital settings. District hospitals in Rajasthan and Gujarat are piloting 500-liter chamber systems with 45-minute cycle times. The technology is collapsing incumbent assumptions about renewable energy's inability to match conventional autoclave thermal ramp rates.
India's CDSCO medical device rules are mandating separate registration pathways for solar-thermal versus photovoltaic sterilizers, creating compliance complexity for multi-modal product portfolios. Domestic manufacturers in Gujarat and Tamil Nadu are restructuring quality management systems to accommodate parallel technical file submissions. The regulation is most affecting exporters targeting both Indian public procurement and European CE-marked markets simultaneously.
Last-mile distributors are unbundling after-sales service contracts from equipment sales, shifting risk to third-party maintenance networks. Clinics in Ethiopia and Tanzania now purchase sterilizers through medical supply cooperatives while sourcing technical support from independent solar technicians. This pattern is most visible in East African markets where fragmented geography limits manufacturer-direct service coverage.
Solar Autoclave Market Segmentation
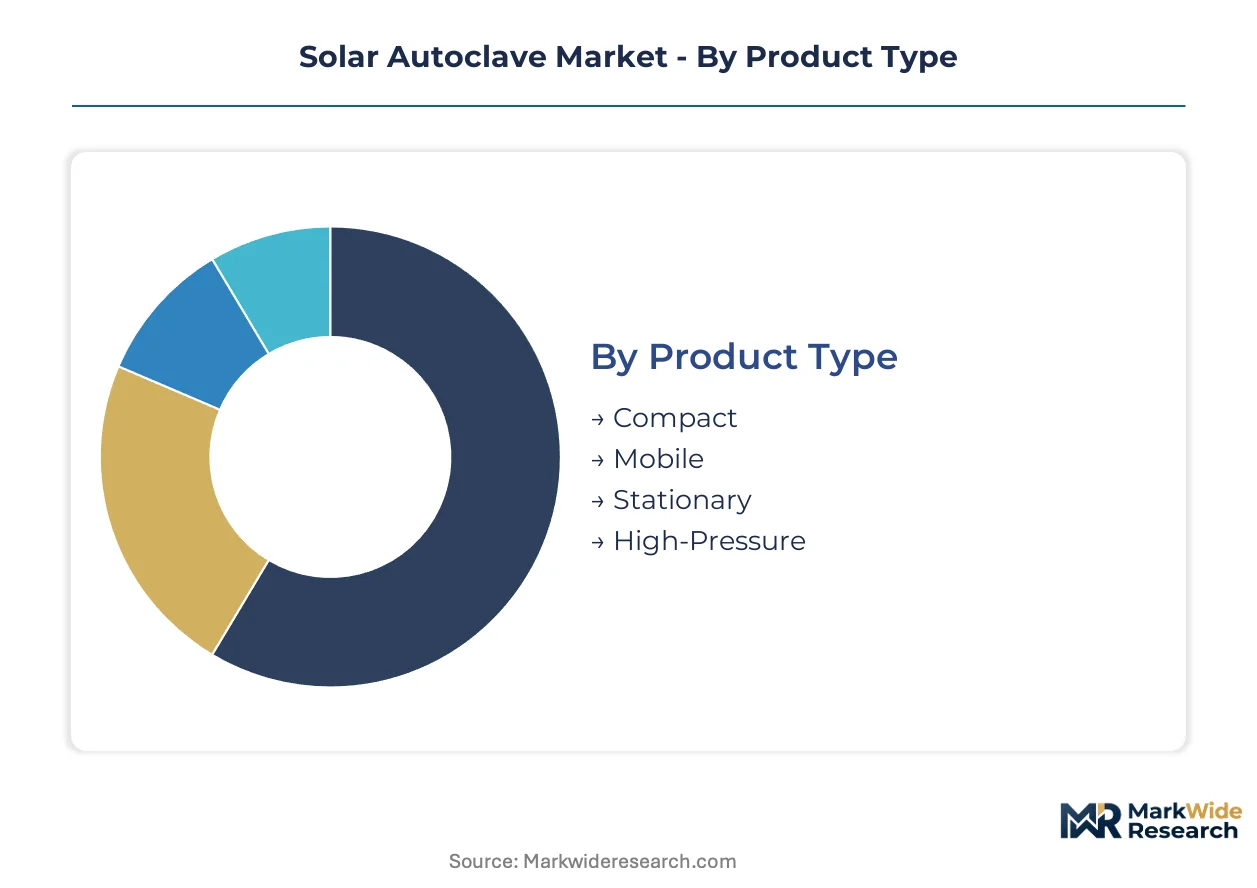
Solar autoclave market segmentation reveals divergent performance requirements across deployment contexts. Procurement patterns split sharply between last-mile portability demands and centralized hospital throughput needs, with technology choices tracking local solar irradiance and grid reliability conditions.
Product Type:
Cost tier differentiation separates field-deployable units from capital-intensive fixed installations, with chamber volume and pressure rating as the primary price determinants.
- Compact:These units feature chamber volumes under 20 liters with direct solar thermal heating elements. Primary health centers in Ethiopia and Tanzania concentrate procurement through medical supply cooperatives. WHO sterilization assurance guidelines for low-resource settings validate their spore lethality performance.
- Mobile:Trailer-mounted or vehicle-integrated systems incorporate photovoltaic arrays with battery buffers for emergency surgical deployment. County health budgets in Kenya's arid counties are unlocking capital expenditure autonomy for these configurations. The steepest expansion runs through mobile units as devolved healthcare financing spreads.
- Stationary:Fixed installations with 50–200 liter chambers serve district hospital central sterilization departments.
- High-Pressure:Hospital-grade systems achieve 30 psi saturated steam for rapid instrument turnaround in surgical suites.
Compact units command the established base. The steepest expansion runs through mobile configurations.
End User:
Customer type determines certification requirements and service contract structures, with public procurement dominating volume and private clinics driving margin capture.
- Healthcare Facilities:Public primary health centers under India's National Rural Health Mission generate the largest unit volumes through decentralized procurement mandates. BIS pressure vessel certifications and CDSCO medical device rules shape compliance costs for domestic suppliers in Gujarat and Tamil Nadu.
- Research Labs:University and institutional buyers prioritize precise temperature logging and cycle documentation for protocol validation. FDA 510(k) equivalence documentation requirements extend sales cycles to 18–24 months for US market entry. Research labs represent the fastest-growing customer type as academic medical centers expand off-grid field research capacity.
- Dental Clinics:Smaller chamber requirements and lower throughput needs characterize this segment.
- Veterinary Clinics:Agricultural extension services and private practices drive demand in livestock-intensive regions.
Healthcare facilities anchor procurement volume. The steepest expansion runs through research labs.
Technology:
Application context dictates thermal source selection, with hybrid architectures gaining traction as reliability requirements tighten for surgical instrument sterilization.
- Thermal:Direct solar thermal collection using flat-plate or evacuated-tube designs achieves 121°C saturated steam without electrical conversion losses. Monsoon humidity in South Asia constrains optical efficiency below 70%, limiting steam generation rates during wet seasons.
- Solar Thermal:Concentrated parabolic trough systems with direct steam generation collapse cost deltas against resistive heating in high-throughput settings. District hospitals in Rajasthan and Gujarat pilot 500-liter chambers with 45-minute cycle times. Solar thermal commands the established technology base.
- Hybrid:Configurations pairing solar thermal pre-heating with electric backup compress reliability gaps in off-grid surgical settings. Equipment manufacturers face simultaneous certification pressure under divergent national pressure-vessel and medical-device frameworks. Hybrid systems are expanding most quickly as surgical liability standards tighten.
- Electric:Photovoltaic-driven resistive heating eliminates thermal collector maintenance but requires battery storage for cycle completion.
Solar thermal commands the established base. The steepest expansion runs through hybrid configurations.
Application:
Volume requirements and contamination risk levels segment demand, with surgical applications commanding premium pricing for lethality assurance.
- Surgical Instruments:Reusable metal instrument sets for operating theaters demand validated spore kill assurance at 134°C. CDSCO rules in India mandate separate registration pathways for solar-thermal versus photovoltaic sterilizers, complicating multi-modal product portfolios.
- Laboratory Equipment:Glassware and media preparation require lower pressure ratings but precise temperature uniformity. Co-located solar thermal plants enable dual-output configurations producing both sterile steam and purified water for research facilities. Laboratory equipment applications are gaining share fastest as research infrastructure decentralizes.
- Dental Tools:Handpiece and bur sterilization cycles prioritize speed over chamber capacity.
- Waste Treatment:Biohazard and sharps disposal applications tolerate longer cycle times.
Surgical instruments command the established base. The steepest expansion runs through laboratory equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Gujarat and Tamil Nadu, where dedicated solar equipment zones concentrate pressure vessel fabrication and photovoltaic integration. Domestic producers leverage these hubs to serve India's National Rural Health Mission procurement while building export capacity for African markets.
India
Decentralized procurement mandates under the National Rural Health Mission create dedicated budget lines for primary health centers. CDSCO medical device rules and BIS pressure vessel certifications shape compliance frameworks for domestic suppliers. Manufacturing zones in Gujarat and Tamil Nadu host integrated solar thermal collector and autoclave assembly operations serving sub-Saharan export markets.
United States
FDA 510(k) clearance pathways govern market access for surgical-grade sterilization equipment. EPA sterilization efficacy standards validate spore lethality performance claims for solar-derived steam systems. Research institutions in California and Massachusetts pilot off-grid field deployment configurations for academic medical centers expanding rural research capacity.
Germany
EU MDR and F-Gas Regulation constrain refrigerant-based auxiliary cooling in European-bound equipment. CE marking requirements pressure manufacturers to certify hybrid thermal-electric architectures under convergent standards. Industrial clusters in Baden-Württemberg concentrate precision pressure vessel engineering for hospital-grade system exports.
Kenya
County-level health budgets under devolution unlock capital expenditure autonomy for solar medical equipment in arid and semi-arid counties. National electrification programs prioritize off-grid healthcare infrastructure in frontier regions. Distributors in Nairobi and Mombasa coordinate last-mile logistics for mobile trailer-mounted units reaching remote surgical facilities.
China
Domestic production capacity for high-pressure hospital-grade units concentrates in provincial manufacturing bases. NMPA medical device registration and GB pressure vessel standards govern domestic market access. Industrial zones in Shandong and Jiangsu integrate solar thermal component supply with autoclave system assembly for institutional procurement.
Solar Autoclave Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pressure vessels, thermal collectors, and control modules. The vendor base splits between diversified medical equipment conglomerates and dedicated sterilization technology firms. Three archetypes dominate: European aftermarket service anchors, Asian manufacturing scale players, and compact portability specialists. Competitive moves concentrate on dual-mode certification under divergent national frameworks and unbundling of after-sales service contracts to third-party maintenance networks.
Among European-based medical technology groups, Getinge AB and STERIS plc occupy positions as diversified platform integrators with established installed bases for aftermarket revenue capture. Tuttnauer represents the compact system portability archetype, while Shinva Medical Instrument anchors the Asian manufacturing scale tier. These named entities exemplify how competitive positioning fragments across geographic origin, product architecture, and service model differentiation rather than consolidating around unified technology standards.
| Leading Market Players |
|---|
| Getinge AB |
| STERIS plc |
| Tuttnauer |
| Belimed AG |
| Astell Scientific |
| MELAG Medizintechnik |
| Shinva Medical Instrument |
| Panasonic Healthcare |
| Celitron Medical Technologies |
| Others |
Value Network & Pricing Analysis
Tariff exposure on certified boiler-grade steel alloys between India and Brazil compresses margin structures across all three pricing tiers while simultaneously forcing manufacturers toward regionalized fabrication footprints. This single chokepoint determines both the spread between economy field units and premium hospital-grade systems and the geographic shape of component sourcing networks.
Pricing Analysis
CDSCO medical device rules dictate the pricing tier structure by mandating separate registration fees and technical file costs for solar-thermal versus photovoltaic sterilizers. Three-tier pricing stratifies across premium hospital-grade systems with dual-mode certification, standard fixed installations for district facilities, and economy compact units for primary health centers. Price differentiation hinges on pressure vessel certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because medical supply cooperatives in Ethiopia and Tanzania unbundle service contracts from equipment sales. Public procurement committees under India's National Rural Health Mission exhibit the highest price sensitivity, while research labs in the United States tolerate extended sales cycles for FDA 510(k) equivalence documentation.
Supply Chain Analysis
Tariff exposure between India and Brazil dominates supply chain risk calculations for pressure vessel steel inputs. Manufacturing concentration centers on Gujarat and Tamil Nadu in India, with secondary clusters in Shandong and Jiangsu in China. Raw material dependencies draw from crystalline silicon photovoltaic modules, certified ASME Section IX boiler-grade alloys, and lithium-ion battery cells. Single-source vulnerability concentrates in cobalt supply from the Democratic Republic of Congo for hybrid system energy storage. Distribution runs through medical supply cooperatives in East Africa, regional distributors in Nairobi and Mombasa, and direct procurement channels for India's National Rural Health Mission.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar autoclave penetration sits at an early-cycle expansion phase justified by WHO sterilization assurance guidelines legitimizing solar thermal equivalence to fuel-fired steam for spore lethality validation in low-resource settings.
For Market Incumbents: Entrench aftermarket service revenues by anchoring spare parts logistics in Kenya's devolved county health systems and Rajasthan's district hospital networks. Deepen backward integration into solar thermal collector production in Gujarat's dedicated manufacturing zones to offset photovoltaic module cost volatility. Defend against compact portability specialists by accelerating dual-mode certification under CDSCO and EU MDR frameworks simultaneously. For New Entrants and Emerging Players: Kenya's arid and semi-arid counties present the most penetrable geographic white space as devolved health budgets unlock capital expenditure autonomy for mobile trailer-mounted units. Laboratory equipment applications for decentralized field research infrastructure offer the fastest-growing segment entry point with lower regulatory barriers than surgical-grade systems. Pursue medical supply cooperative partnerships in Ethiopia and Tanzania as the dominant go-to-market channel, leveraging independent solar technician networks for last-mile service coverage. For Investors and Strategic Acquirers: The market sits at an infrastructure deployment phase that favors platform integrators with established pressure vessel engineering capabilities and multi-regional certification expertise. Long-term viability over the next decade hinges on consolidation of fragmented aftermarket service networks into scalable third-party maintenance platforms. Acquisition targets should prioritize firms with parallel CDSCO and CE marking technical files already submitted. The signal to watch is county-level health budget execution rates in Kenya and procurement tender awards under India's National Rural Health Mission as inflection indicators for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Certification Investment | Simultaneous CDSCO and EU MDR submissions unlock Indian public procurement and European hospital access. |
| Aftermarket Service Unbundling | Third-party solar technician networks in East Africa reduce manufacturer-direct coverage costs for mobile units. |
| Backward Integration into Thermal Collectors | In-house production of evacuated-tube components in Gujarat insulates against photovoltaic module price swings. |
| County-Level Partnership Development | Direct relationships with Kenya's devolved health administrations secure capital expenditure autonomy for arid region deployment. |
| Research Lab Application Expansion | Academic medical center procurement for off-grid field capacity bypasses FDA 510(k) sterilization equivalence timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers at district hospitals, procurement officers in India's National Rural Health Mission, solar technician network coordinators in Nairobi, and pressure vessel fabrication supervisors in Gujarat and Tamil Nadu. Secondary validation drew from CDSCO medical device registration databases, BIS pressure vessel certification records, WHO sterilization assurance guideline documentation, and county health budget execution reports from Kenya's devolved administrations. Bottom-up unit shipment estimates from manufacturing clusters were triangulated against top-down procurement budget allocations across the analysis window.
Calibration anchored volume and value outputs to disclosed tender awards under India's National Rural Health Mission, pilot installation announcements from Rajasthan and Gujarat district hospitals, and medical supply cooperative procurement records in Ethiopia and Tanzania. Segmentation dimensions modeled include product type tier, end-user category, thermal source technology, and application context. CAGRs were derived from slope analysis of procurement budget trajectories and manufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated photovoltaic module cost trajectories and lithium-ion battery price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in Indian solar import tariff schedules, Brazilian pressure vessel steel duties, or Democratic Republic of Congo cobalt supply stability would shift the trajectory. Forecasts reflect documented assumptions regarding WHO guideline adoption timelines and county-level budget execution efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Solar Farm Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market