
 Asia-Pacific Niacinamide Market | 2026-2036
Asia-Pacific Niacinamide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Niacinamide Market Insights
Ingredient-as-a-service subscription models for dermatologist-dispensed niacinamide regimens is hardening the revenue architecture beyond one-time product sales. Zhejiang NHU Co., Ltd. leverages captive feedstock capacity to anchor cost positions across pharmaceutical and cosmetic grades. BASF SE differentiates through biotechnology-derived routes that reduce solvent intensity. AMOREPACIFIC dominates premium skincare narratives in Seoul and Tokyo flagship channels.
Niacinamide, the amide form of vitamin B3 (C6H6N2O), functions as a cosmeceutical active with demonstrated inhibition of melanosome transfer and enhancement of epidermal barrier ceramide synthesis; manufacturers typically achieve pharmaceutical-grade purity above 99.5% through catalytic hydrogenation of 3-cyanopyridine followed by controlled hydrolysis. Serums command the highest margin pools in the product type architecture due to concentration flexibility and clinical positioning, while water-based formulations lead volume as K-beauty and J-beauty routines prioritize lightweight layering textures. The dermatologist end-user channel represents the fastest-expanding access point, driven by prescription-strength protocols for hyperpigmentation and acne sequelae across Asia-Pacific metropolitan clinics.
China's NMPA and SAMR enforce escalating cosmetic ingredient registration requirements that filter out non-compliant niacinamide suppliers from cross-border e-commerce channels. Japan's MHLW through PMDA maintains pharmaceutical-grade distinctions that shape pricing architecture between quasi-drug and cosmetic classifications. South Korea's MFDS clean beauty directives are accelerating preservative-system reformulations that favor niacinamide's inherent stability profile. Stakeholders must monitor regulatory divergence between pharmaceutical and cosmetic pathways as ingredient purity claims become the primary battleground for market access and consumer trust.
Market Dynamics
China's NMPA tightening of cosmetic ingredient registration requirements is forcing a bifurcation between pharmaceutical-grade and cosmetic-grade niacinamide supply chains, with purity documentation becoming the primary gating mechanism for market access across Asia-Pacific distribution channels.
Growth Catalysts
- Prestige skincare channel expansion:Japan's department store and medical spa sectors are absorbing high-concentration niacinamide serums at accelerated rates, with dermatologist co-development protocols driving premium positioning.
- MFDS clean beauty directives:South Korea's preservative-system restrictions are favoring niacinamide's inherent stability profile, accelerating reformulation cycles across K-beauty brands seeking label-friendly alternatives.
- Mass-market retail penetration:India's expanding organized retail sector is creating shelf-space competition for niacinamide-inclusive products, with private-label acceleration in tier-two cities.
Market Restraints
- 3-cyanopyridine feedstock concentration:Catalytic hydrogenation precursors remain concentrated among Zhejiang-based chemical intermediates suppliers, creating input cost transmission risks.
- Pharmaceutical-cosmetic regulatory divergence:Japan's PMDA maintains distinct quasi-drug versus cosmetic classification pathways that fragment formulation investment and extend compliance timelines.
- Niacin substitution in feed applications:Animal nutrition sectors in Southeast Asia are evaluating niacin alternatives for vitamin B3 fortification, pressuring industrial-grade demand.
Strategic Opportunities
- Dermatologist-dispensed subscription models:Seoul and Tokyo metropolitan clinics are piloting ingredient-as-a-service regimens that harden recurring revenue beyond single-product transactions.
- Biotechnology-derived production routes:Enzymatic conversion pathways are reducing solvent intensity and enabling carbon-footprint claims for sustainability-positioned cosmetic brands.
- Cross-border e-commerce compliance services:China's SAMR registration requirements are creating advisory and testing service demand for international brands seeking Tmall and Douyin market access.
Industry Challenges
- Analytical chemistry talent scarcity:Pharmaceutical-grade purity verification requires specialized high-performance liquid chromatography expertise that remains concentrated in Shanghai, Tokyo, and Singapore laboratory clusters.
- Dual-use facility certification complexity:Manufacturers serving both cosmetic and pharmaceutical end-uses face overlapping GMP and ISO 22716 audit schedules that compress operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Niacinamide Market |
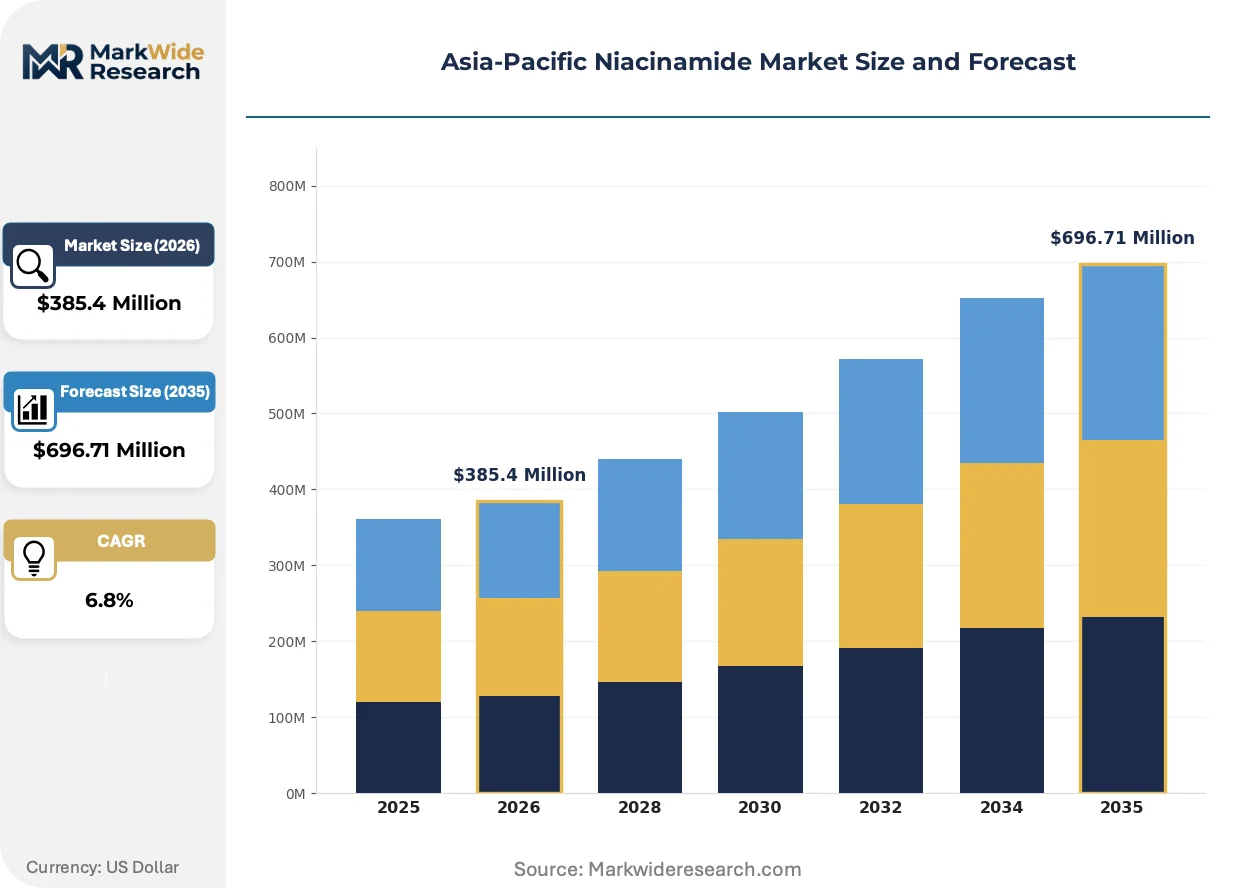
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Serums, Lotions, Masks Application: Skincare, Haircare, Cosmetics, Pharmaceuticals Formulation Type: Water-based, Oil-based, Gel-based, Powder End User: Individuals, Dermatologists, Salons, Retailers |
| Companies Covered | COSRX, Zhejiang NHU Co., Ltd., AMOREPACIFIC, Lonza Group, Brother Enterprises Holding Co., Ltd., Shiseido, JALA Group, BASF SE, Kao Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Niacinamide Market Trends and Innovations
Biotechnology-derived production methods, regulatory documentation automation, and channel-specific formulation customization are compressing development cycles and fragmenting competitive positioning across the Asia-Pacific niacinamide value chain.
Enzymatic niacinamide synthesis using immobilized nitrile hydratase biocatalysts is decentralizing production geography away from traditional petrochemical corridors. Singapore-based contract manufacturers are adopting these routes to serve ASEAN cosmetic brands seeking localized supply. The technology is decentralizing margin capture toward biotech-enabled specialists and away from legacy chemical conglomerates.
China's NMPA cosmetic ingredient registration system is mandating extended safety dossiers for niacinamide concentrations exceeding threshold limits. Domestic brands are front-loading toxicology investments to secure cross-border e-commerce eligibility. The policy is reshaping competitive access, with compliant suppliers securing preferred positioning on Tmall International and JD Worldwide platforms.
Clinical validation requirements are compressing procurement cycles for dermatology channel partnerships. Korean and Japanese skincare brands are prioritizing ingredient suppliers with published peer-reviewed efficacy data over commodity sourcing. Seoul-based medical aesthetic chains are driving this specification elevation, with formulation decisions increasingly centralized through clinic procurement committees rather than traditional brand marketing functions.
Asia-Pacific Niacinamide Market Segmentation
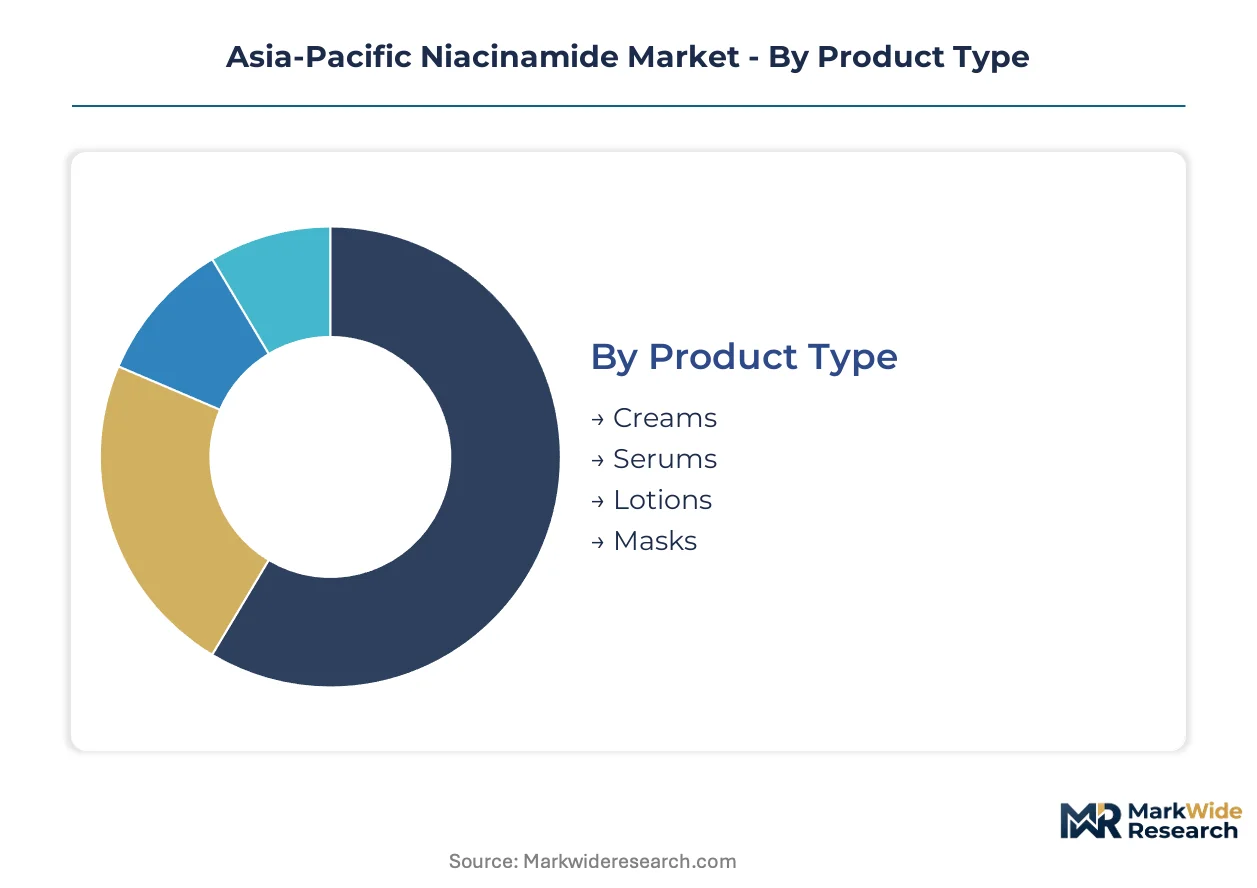
Niacinamide formulation economics vary sharply across concentration tiers and delivery systems. Capital deployment decisions in this market hinge on which segments demand pharmaceutical-grade certification versus cosmetic-grade flexibility.
Product Type:
Capital intensity peaks in segments requiring sterile manufacturing environments and stability testing infrastructure.
- Serums:High-concentration aqueous solutions (typically 5-20% niacinamide) demand precision dosing equipment and nitrogen-blanketing packaging lines to prevent oxidation. Seoul and Tokyo dermatology clinics specify these for melasma protocols, with Korean brands commanding premium shelf positioning through clinical co-development claims.
- Creams:Emulsion-based delivery systems require homogenization investment but offer formulation flexibility for barrier-repair positioning. Japanese prestige retailers absorb these at volume, though margin compression is accelerating as domestic private-label entrants expand.
- Lotions:Lightweight textures suit K-beauty and J-beauty layering routines; lower viscosity reduces mixing energy costs.
- Masks:Sheet-mask formats concentrate production in Guangdong and Gyeonggi-do contract manufacturers serving fast-fashion beauty cycles.
Serums absorb the bulk of installed capacity; masks are expanding most quickly.
Application:
Regulatory pathway divergence creates distinct margin architectures across end-use categories.
- Skincare:Facial care dominates volume, with niacinamide's ceramide synthesis mechanism driving anti-aging and brightening claims. China's SAMR registration requirements for concentrations above threshold limits are filtering supplier bases, with compliant brands securing Tmall International preferential placement.
- Pharmaceuticals:Prescription-grade niacinamide for acne sequelae and inflammatory conditions requires PMDA quasi-drug or MFDS pharmaceutical certification. Mumbai and Bangalore dermatology chains are piloting high-dose protocols, though procurement cycles extend due to clinical validation requirements.
- Haircare:Scalp health positioning is gaining traction in Japanese and Korean professional salon channels.
- Cosmetics:Color cosmetic inclusion remains niche, concentrated in BB cream and cushion foundation formats.
Skincare commands the majority of formulation investment; pharmaceuticals is gaining share fastest.
Formulation Type:
Processing technology requirements segment the competitive field between aqueous and anhydrous specialists.
- Water-based:Dominates Asia-Pacific volume due to consumer preference for lightweight, fast-absorbing textures. South Korea's MFDS clean beauty directives favor these systems as brands eliminate silicones and heavy emollients; preservative selection becomes critical given niacinamide's pH sensitivity.
- Gel-based:Hydroxyethylcellulose or carbomer-thickened systems suit men's grooming and body care extensions. Thai and Vietnamese brands are adopting these for tropical climate positioning.
- Oil-based:Lipid-delivery formats serve dry-skin and mature-skin segments; higher raw material costs limit mass-market penetration.
- Powder:Active ingredient supply to compounders and DIY beauty segments; purity documentation requirements are tightening under China's NMPA cosmetic ingredient standards.
Water-based formulations absorb the bulk of capacity expansion; gel-based is climbing the fastest.
End User:
Channel access costs and customer acquisition economics determine viable segment entry strategies.
- Dermatologists:Clinic-dispensed protocols concentrate purchasing decisions through Seoul and Tokyo metropolitan procurement committees. Subscription-based regimen models are hardening recurring revenue streams beyond single-product transactions, with validation requirements favoring suppliers with peer-reviewed efficacy data.
- Individuals:Direct-to-consumer e-commerce dominates, with Douyin and Shopee live-streaming commerce driving impulse purchase behavior. Tier-two Indian cities are emerging as volume growth poles through organized retail penetration.
- Salons:Professional treatment backbar usage concentrates in Japanese medical spa and Korean skin clinic chains.
- Retailers:Private-label acceleration by Watsons, Matsumoto Kiyoshi, and Reliance Retail is reshaping supplier negotiation leverage.
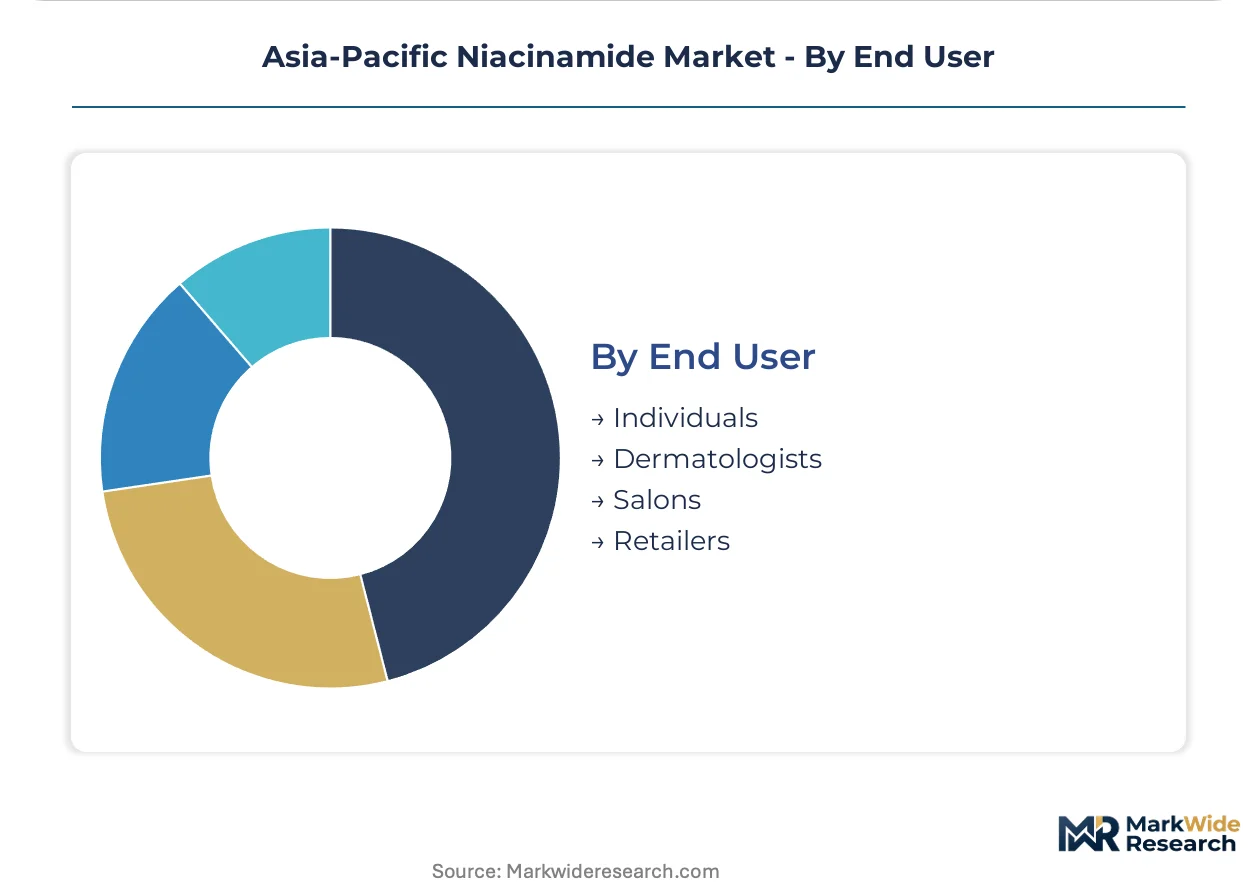
Individual consumers absorb the bulk of volume; dermatologists is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates pharmaceutical-grade niacinamide production capacity in Zhejiang province, while consumption gravitates toward Seoul and Tokyo dermatology clinics. India absorbs expanding mass-market volumes through organized retail penetration in tier-two cities.
China
NMPA cosmetic ingredient registration requirements are filtering supplier bases for cross-border e-commerce eligibility. SAMR enforcement on Tmall International and JD Worldwide platforms favors brands with complete toxicology dossiers. Zhejiang province chemical intermediates suppliers anchor catalytic hydrogenation feedstock production for both pharmaceutical and cosmetic grades.
South Korea
Seoul metropolitan dermatology clinics are piloting subscription-based niacinamide regimens that harden recurring revenue beyond single-product transactions. MFDS clean beauty directives are accelerating preservative-system reformulations that favor niacinamide's inherent stability profile. Gyeonggi-do contract manufacturers concentrate sheet-mask production for fast-fashion beauty cycles.
Japan
PMDA quasi-drug classification pathways for high-concentration serums are fragmenting formulation investment between pharmaceutical and cosmetic channels. Tokyo department store and medical spa sectors absorb premium niacinamide products at accelerated rates. Osaka-based prestige retailers are experiencing private-label acceleration that compresses margins for established brands.
India
Mumbai and Bangalore dermatology chains are piloting prescription-strength protocols for hyperpigmentation and acne sequelae. CDSCO pharmaceutical-grade certification requirements extend procurement cycles for clinic-dispensed products. Tier-two cities through organized retail penetration are emerging as volume growth poles for mass-market niacinamide-inclusive formulations.
Singapore
ASEAN cosmetic brands are sourcing from contract manufacturers adopting enzymatic synthesis routes to serve localized supply preferences. The country's regulatory alignment with both Chinese and Western standards positions it as a compliance advisory hub for cross-border e-commerce market access. Biotech-enabled production specialists are decentralizing margin capture away from legacy chemical conglomerates.
Asia-Pacific Niacinamide Market Competitive Landscape
Top-tier vendors anchor premium dermatology channel access, while mid-tier suppliers compete on feedstock integration and regional regulatory compliance. The vendor base stratifies between pharmaceutical-grade certifiers, biotechnology-derived route specialists, and K-beauty brand owners with captive formulation capabilities. Two strategic archetypes dominate: chemical conglomerates with captive 3-cyanopyridine capacity, and biotech-enabled contract manufacturers with enzymatic synthesis platforms. Capacity expansion and regulatory documentation automation represent the dominant competitive moves across the value chain.
Within the feedstock-integrated tier, Zhejiang NHU Co., Ltd. and Brother Enterprises Holding Co., Ltd. exemplify Chinese chemical intermediates suppliers with backward control over catalytic hydrogenation precursors. BASF SE occupies a position among biotechnology-derived route specialists reducing solvent intensity for sustainability-positioned cosmetic brands. AMOREPACIFIC anchors the K-beauty brand-owner archetype with premium skincare narrative control in Seoul and Tokyo flagship channels.
| Leading Market Players |
|---|
| COSRX |
| Zhejiang NHU Co., Ltd. |
| AMOREPACIFIC |
| Lonza Group |
| Brother Enterprises Holding Co., Ltd. |
| Shiseido |
| JALA Group |
| BASF SE |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
3-cyanopyridine spot price volatility cascades through catalytic hydrogenation economics into tiered pharmaceutical and cosmetic grade pricing, with Zhejiang feedstock concentration amplifying cost transmission risks across Asia-Pacific formulation channels.
Pricing Analysis
Margin tightening in cosmetic-grade niacinamide reflects private-label acceleration by Watsons and Reliance Retail compressing brand premiums. Three-tier pricing structure across pharmaceutical, premium cosmetic, and mass-market cosmetic levels segments buyers by purity documentation requirements. Pricing pressure intensifies in standard cosmetic tiers as Indian organized retail expands shelf-space competition. Dermatologist-dispensed protocols exhibit lowest price sensitivity due to clinical validation requirements and subscription bundling.
Supply Chain Analysis
Container freight rate fluctuations between Shanghai and Singapore ports directly impact ASEAN cosmetic brand sourcing economics. Feedstock production concentrates in China, South Korea, and Japan, with catalytic hydrogenation precursors anchored in Zhejiang province. Supply chains draw from 3-cyanopyridine intermediates, pharmaceutical-grade certification laboratories, and nitrogen-blanketing packaging equipment. Single-source vulnerability persists in high-purity analytical chemistry talent clustered in Shanghai, Tokyo, and Singapore. Distribution runs through cross-border e-commerce platforms, dermatology clinic procurement committees, and organized retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic synthesis platforms are displacing legacy petrochemical routes, compressing development cycles and fragmenting margin capture toward biotech-enabled specialists.
For Market Incumbents: Deepen backward integration into 3-cyanopyridine feedstock to defend cost positions against Zhejiang-based chemical intermediates suppliers. Expand pharmaceutical-grade certification capacity in response to NMPA and PMDA purity documentation requirements tightening market access. Prioritize regulatory documentation automation to compress compliance timelines for dual-use cosmetic-pharmaceutical facilities. For New Entrants and Emerging Players: Dermatology clinic procurement committees in Seoul and Tokyo represent the most penetrable channel for subscription-based regimen models. Target tier-two Indian cities through organized retail private-label partnerships as volume growth poles. Pursue enzymatic synthesis partnerships with Singapore-based contract manufacturers to establish sustainability-positioned supply credentials. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotech-enabled production specialists in Singapore and South Korea as legacy chemical conglomerates face margin compression. Long-term viability hinges on regulatory compliance automation capabilities and dermatology channel access. Monitor NMPA cosmetic ingredient registration enforcement intensity as inflection indicator for compliant supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Adoption | Immobilized nitrile hydratase biocatalysts reduce solvent intensity for sustainability-positioned ASEAN cosmetic brands. |
| Pharmaceutical-Grade Certification | PMDA quasi-drug and MFDS pharmaceutical pathways fragment formulation investment but secure premium channel access. |
| Subscription Regimen Models | Seoul and Tokyo dermatology clinics pilot ingredient-as-a-service to harden recurring revenue beyond single-product transactions. |
| Cross-Border E-Commerce Compliance | SAMR registration advisory services create service revenue streams for Tmall International and JD Worldwide market access. |
| Preservative-System Reformulation | MFDS clean beauty directives accelerate label-friendly alternatives leveraging niacinamide's inherent stability profile. |
Research Methodology
Multi-period observation of NMPA registration filings, MFDS clean beauty directive implementations, and dermatology clinic procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at Zhejiang chemical intermediates suppliers, procurement leads at Korean and Japanese skincare brands, regulatory affairs specialists navigating PMDA quasi-drug pathways, and category buyers at Watsons and Reliance Retail. Secondary validation drew from customs and trade data, NMPA cosmetic ingredient registration databases, SEC 10-K disclosures from listed chemical suppliers, and MFDS regulatory guidance documents. Bottom-up capacity and demand estimates triangulated against top-down market sizing.
Input-output matrices modeled niacinamide flow from catalytic hydrogenation feedstock through formulation tiers to end-use channels across the projection horizon. Segmentation dimensions included product type (serums, creams, lotions, masks), application (skincare, pharmaceuticals, haircare), formulation type (water-based, gel-based, oil-based, powder), and end user (dermatologists, individuals, salons, retailers). CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and channel shift velocities. Industry-specific forecast inputs incorporated NMPA enforcement intensity indices and dermatology clinic expansion rates in Seoul, Tokyo, Mumbai, and Bangalore.
Caveats apply where NMPA cosmetic ingredient registration enforcement intensity, 3-cyanopyridine feedstock price volatility, or MFDS preservative-system directive scope could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway stability and clinic procurement centralization trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market