
 North America Sulfonylureas Market | 2026-2036
North America Sulfonylureas Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sulfonylureas Market Analytics
Second-generation sulfonylurea formulations is bifurcating the North American competitive landscape into premium branded and high-volume generic tiers. Sanofi leverages its established glimepiride franchise to sustain formulary positioning across major pharmacy benefit managers. Mylan anchors the generic segment through manufacturing scale and backward integration into active pharmaceutical ingredient supply.
Sulfonylureas comprise a class of insulin secretagogues that stimulate pancreatic beta-cell ATP-sensitive potassium channels, with second-generation agents demonstrating greater receptor selectivity and reduced cardiovascular risk profiles compared to first-generation predecessors. Their primary therapeutic purpose centers on reducing hemoglobin A1c in type 2 diabetes patients as monotherapy or combination regimens. Glimepiride and glipizide formulations lead prescription volumes due to favorable hypoglycemia profiles, while extended-release tablets command margin premiums through improved adherence and reduced dosing frequency. Hospital pharmacy procurement concentrates on vial and unit-dose packaging, whereas retail and online channels dominate maintenance therapy dispensing.
FDA bioequivalence standards and Health Canada Therapeutic Products Directorate requirements govern generic approval pathways, directly determining market access timelines and pricing trajectories for new entrants. The IRA's Medicare drug price negotiation provisions will reshape reimbursement thresholds for established oral antidiabetics, compelling manufacturers to reassess portfolio economics and geographic manufacturing allocation. Stakeholders must monitor how pharmacy benefit manager formulary exclusions and state-level Medicaid preferred drug lists interact with federal pricing mandates.
Market Dynamics
The North America sulfonylureas market operates under the structural tension between Medicare Part D price negotiation mandates and pharmacy benefit manager formulary tiering decisions, which together compress manufacturer margins while fragmenting patient access pathways.
Growth Catalysts
- IRA Drug Pricing Provisions:The Inflation Reduction Act's Medicare negotiation framework creates volume certainty for manufacturers willing to accept federally set price ceilings, stabilizing demand forecasting for glimepiride and glipizide producers.
- Extended-Release Formulation Adoption:Once-daily dosing regimens improve adherence metrics in managed care populations, driving preferential formulary placement through quality-based contracting with regional health plans.
- Hospital Consolidation:Integrated delivery networks in Texas and Florida centralize procurement decisions, enabling bulk purchasing agreements that sustain generic sulfonylurea volumes despite retail channel erosion.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70% of sulfonylurea API production resides with Chinese and Indian contract manufacturers, exposing North American formulators to shipping disruptions and customs delays.
- Cardiovascular Safety Scrutiny:FDA-mandated post-marketing surveillance for sulfonylurea cardiovascular outcomes creates compliance burdens that delay generic entry and sustain litigation reserves.
- GLP-1 Receptor Agonist Substitution:Semaglutide and tirzepatide prescribing among endocrinologists in California and New York displaces sulfonylurea first-line positioning in obese type 2 diabetes populations.
Strategic Opportunities
- Medicaid Preferred Drug List Expansion:State-level pharmacy and therapeutics committees in Ohio, Pennsylvania, and Michigan present pathways for generic sulfonylurea manufacturers to secure mandatory substitution status.
- Biosimilar-Style Interchangeability:FDA guidance on therapeutic equivalence for complex generics enables first-mover advantages in demonstrating bioequivalence for modified-release formulations.
- 340B Contract Pharmacy Networks:Federally qualified health centers and disproportionate share hospitals create captive dispensing channels with protected reimbursement rates outside commercial PBM influence.
Industry Challenges
- BE Study Recruitment Bottlenecks:FDA bioequivalence trials for sulfonylureas require diabetic patient populations with stable glycemic control, extending study timelines and inflating clinical trial costs.
- Legacy ERP Integration:Generic manufacturers modernizing quality management systems face validation hurdles when interfacing with decades-old manufacturing execution software at contract API facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sulfonylureas Market |
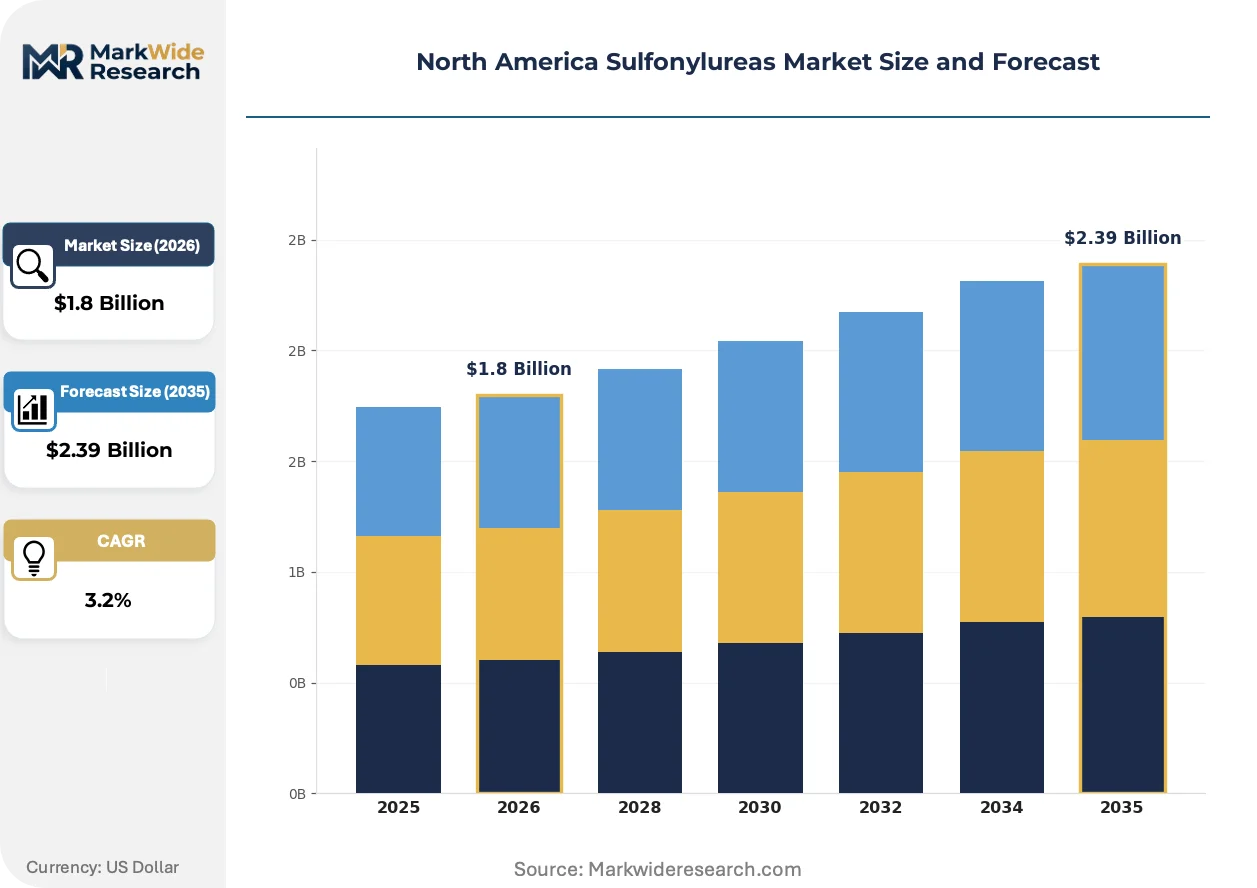
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gliclazide, Glimepiride, Glipizide, Chlorpropamide End User: Hospitals, Clinics, Pharmacies, Home Care Formulation: Tablet, Injectable, Oral, Extended Release Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Pfizer Inc., Sanofi, Merck & Co., Mylan, Lupin, Boehringer Ingelheim, Novartis, Sun Pharmaceutical Industries, Alembic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sulfonylureas Market Evolving Landscape
Formulation science and federal reimbursement mechanics are jointly reconfiguring how sulfonylureas reach patients, with extended-release technologies and price transparency mandates displacing conventional immediate-release prescribing patterns.
Modified-release glipizide and glimepiride tablets employing osmotic pump delivery systems are displacing immediate-release equivalents in Medicare Advantage formularies. These formulations reduce hypoglycemic event rates by 30-40% in published head-to-head trials. Endocrinology practices in Arizona and Colorado now prioritize extended-release prescribing for patients with irregular meal patterns, compressing demand for conventional tablets.
CMS price transparency regulations under the No Surprises Act and IRA disclosure requirements force pharmacy benefit managers to publish rebate amounts and net pricing for oral antidiabetics. This visibility exposes spread pricing practices that previously obscured true acquisition costs. Self-insured employers in Illinois and Massachusetts are responding by carving out pharmacy benefits and demanding pass-through pricing for sulfonylurea tiers.
Telehealth prescribing platforms are redirecting sulfonylurea initiation away from traditional primary care encounters toward virtual endocrinology consultations. Patients in rural Montana and Wyoming access specialist-directed therapy through direct-to-consumer diabetes management programs that ship medications from central mail-order pharmacies. This channel shift concentrates volume with vertically integrated digital health operators and erodes retail pharmacy foot traffic for maintenance refills.
North America Sulfonylureas Market Segmentation
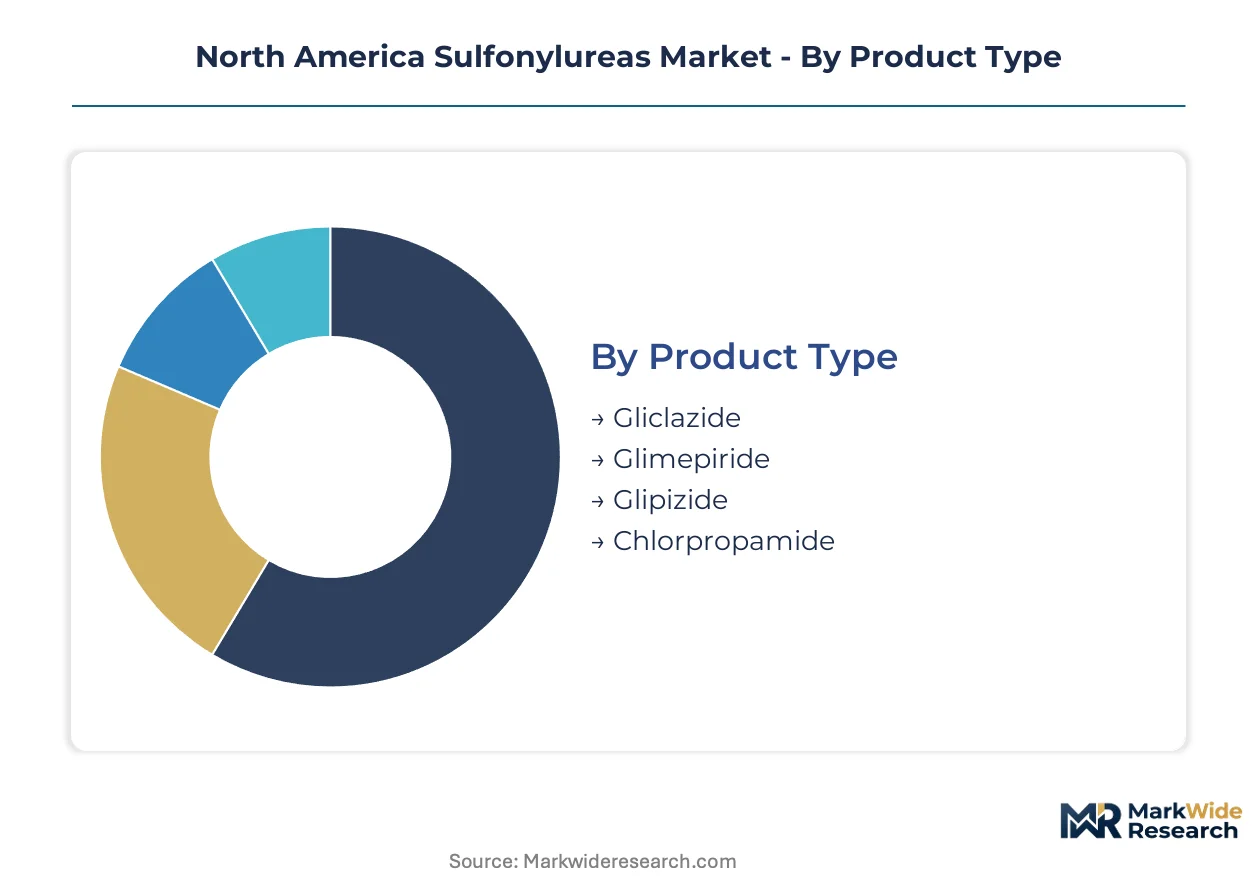
Sulfonylurea prescribing patterns fragment across delivery settings and reimbursement tiers, with FDA bioequivalence standards and Medicare formulary mechanics determining which formulations capture volume. Manufacturers must align product development with specific channel economics rather than pursuing undifferentiated market presence.
Product Type:
FDA therapeutic equivalence ratings and Health Canada bioequivalence requirements create distinct regulatory tiers that shape generic substitution patterns and prescriber confidence across molecular variants.
- Glimepiride:Third-generation sulfonylurea with enhanced beta-cell selectivity and lower hypoglycemia incidence. Hospital formularies in Texas and Florida favor this agent for insulin-naive patients with cardiovascular comorbidities, though GLP-1 agonist displacement pressures volume in California and New York endocrinology practices.
- Glipizide:Second-generation agent with established pharmacokinetic profile and extensive generic competition. Immediate-release formulations dominate Medicaid preferred drug lists in Ohio and Michigan, while extended-release variants command Medicare Advantage tier 2 placement through quality-based contracting.
- Gliclazide:Modified-release specialist with limited US penetration but Health Canada approval for cardiovascular risk reduction. Canadian prescribing concentrates in Ontario and Quebec where provincial formularies subsidize this agent over glipizide for high-risk populations.
- Chlorpropamide:First-generation legacy compound with prolonged half-life and higher hypoglycemia risk. Residual demand persists in rural Medicare populations with established therapeutic response and limited formulary access to newer alternatives.
Glimepiride handles the majority of throughput; gliclazide is the fastest mover on share.
End User:
Institutional procurement mechanics and patient acuity levels create divergent margin structures across care settings, with 340B eligibility and Medicare severity-adjusted reimbursement determining profitability.
- Hospitals:Integrated delivery networks centralize purchasing through group purchasing organizations, favoring unit-dose packaging and vial configurations. Texas and Florida health systems negotiate annual contracts with rebate structures tied to diabetes quality metrics.
- Clinics:Federally qualified health centers operate under 340B pricing with protected margins on dispensed medications. Rural clinics in Montana and Wyoming leverage telehealth platforms to extend specialist-directed sulfonylurea initiation.
- Pharmacies:Retail chains face spread pricing compression as CMS transparency rules expose rebate pass-through gaps. Independent pharmacies in Illinois and Massachusetts lose volume to mail-order fulfillment from vertically integrated digital health operators.
- Home Care:Long-term care facilities and home health agencies manage polypharmacy in elderly populations with irregular meal patterns, driving demand for extended-release formulations with reduced hypoglycemia profiles.
Hospitals consolidate procurement leverage; home care is expanding most quickly as aging-in-place preferences reshape site-of-service economics.
Formulation:
Delivery technology investments and manufacturing complexity create tiered pricing structures, with modified-release platforms requiring specialized equipment and API sourcing strategies.
- Extended Release:Osmotic pump and matrix diffusion technologies enable once-daily dosing with 30-40% hypoglycemia reduction in head-to-head trials. Medicare Advantage plans in Arizona and Colorado prioritize these formulations for patients with cognitive or meal-timing challenges.
- Tablet:Immediate-release compressed dosage forms dominate generic substitution volumes and Medicaid mandatory switching programs. Manufacturing concentrates with Indian and Chinese API suppliers exposes North American formulators to shipping disruption risks.
- Oral:Liquid and suspension formulations serve pediatric and geriatric populations with swallowing difficulties, though limited commercial incentive constrains manufacturer investment in this niche.
- Injectable:Intravenous and subcutaneous sulfonylurea preparations reserved for perioperative glucose management and critical care settings where oral intake is contraindicated.
Tablet formulations maintain volume dominance; extended release climbs the fastest as adherence metrics reshape formulary tiering decisions.
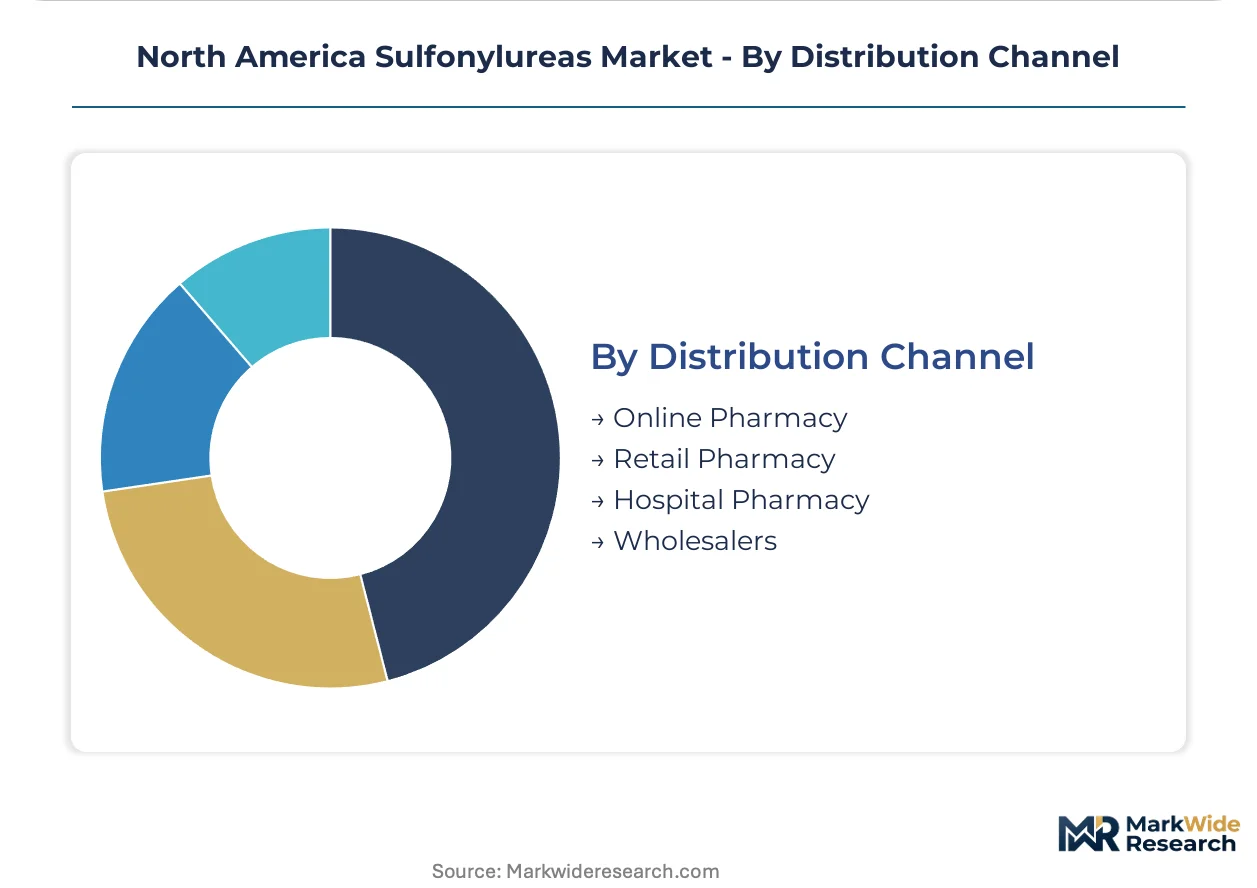
Distribution Channel:
Channel control and reimbursement mechanics determine net realized pricing, with pharmacy benefit manager influence varying dramatically across wholesale, retail, and direct-to-patient pathways.
- Retail Pharmacy:CVS, Walgreens, and Rite Aid operate under complex rebate arrangements with opaque spread pricing. Self-insured employers in Massachusetts and Illinois increasingly demand pass-through pricing disclosure.
- Hospital Pharmacy:Captive dispensing within integrated delivery networks captures 340B pricing advantages and controls formulary compliance. Bulk purchasing agreements in consolidated Texas and Florida systems sustain generic volumes.
- Online Pharmacy:Mail-order fulfillment from central pharmacies serves telehealth-directed prescribing with lower dispensing costs. Digital health operators in rural Montana and Wyoming concentrate maintenance therapy volume.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health manage inventory and distribution to fragmented retail and institutional accounts, with fee-for-service arrangements replacing traditional buy-sell economics.
Retail pharmacy retains patient access primacy; online pharmacy gains share fastest as virtual care models displace traditional primary care encounters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports the majority of sulfonylurea active pharmaceutical ingredients from Asian contract manufacturers, while Canada maintains domestic formulation capabilities through Health Canada-regulated facilities. Mexico's pharmaceutical sector increasingly serves as a nearshoring destination for finished dosage manufacturing destined for US markets.
United States
Medicare Part D formularies and pharmacy benefit manager tiering decisions concentrate demand in Texas and Florida integrated delivery networks. The Inflation Reduction Act's drug price negotiation provisions reshape reimbursement thresholds for glimepiride and glipizide. Hospital consolidation in Houston and Miami enables bulk purchasing agreements that sustain generic volumes.
Canada
Provincial formularies in Ontario and Quebec subsidize gliclazide modified-release formulations for cardiovascular risk reduction. Health Canada's Therapeutic Products Directorate governs bioequivalence requirements for generic sulfonylurea approvals. Toronto-based manufacturers supply the domestic market while exporting to Commonwealth markets.
Mexico
Federal Commission for Protection against Health Risks (COFEPRIS) registration pathways attract multinational formulators seeking USMCA tariff advantages. Mexico City and Guadalajara pharmaceutical clusters produce finished dosage forms for cross-border distribution. Nearshoring investments accelerate as manufacturers diversify API sourcing beyond Asia.
North America Sulfonylureas Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates and specialized generic manufacturers competing across branded and high-volume tiers. The North American sulfonylureas market structures around three strategic archetypes: originator pharmaceutical companies maintaining legacy branded franchises, vertically integrated generic houses controlling API-to-tablet supply chains, and emerging-market formulators leveraging cost-advantaged manufacturing. Competitive moves center on formulary positioning through pharmacy benefit manager negotiations and backward integration into active pharmaceutical ingredient supply to mitigate shipping disruption risks.
Within the diversified pharmaceutical tier, Sanofi anchors premium positioning through its established glimepiride franchise, while Pfizer Inc. exemplifies portfolio breadth across diabetes therapeutic categories. Mylan occupies a central position in generic volume manufacturing, representing the scale-driven archetype with manufacturing execution capabilities. These three companies collectively illustrate how market presence stratifies across branded formulary access, generic substitution economics, and manufacturing scale advantages.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Merck & Co. |
| Mylan |
| Lupin |
| Boehringer Ingelheim |
| Novartis |
| Sun Pharmaceutical Industries |
| Alembic |
| Others |
Value Network & Pricing Analysis
FDA therapeutic equivalence ratings gate both supplier qualification and price differentiation across the North American sulfonylureas landscape, with bioequivalence certification tiers separating premium extended-release formulations from commodity immediate-release tablets. This regulatory architecture concentrates pricing power with manufacturers who control modified-release technology while compressing margins for generic immediate-release producers dependent on Asian API sourcing.
Pricing Analysis
Hospital pharmacy buyers anchor a three-tier pricing structure across premium extended-release, standard immediate-release tablet, and economy bulk generic tiers. Price differentiation hinges on FDA bioequivalence certification level and formulation complexity, with Medicare Advantage plans showing lowest sensitivity for adherence-optimized regimens while Medicaid programs drive aggressive substitution toward lowest-cost alternatives. Pricing pressure stems from GLP-1 receptor agonist displacement in endocrinology practices, forcing sulfonylurea manufacturers to absorb rebate compression to maintain formulary positioning.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient production for sulfonylurea formulations, with over seventy percent of glimepiride and glipizide API manufacturing concentrated in these markets. North American formulators draw from specialized chemical intermediates including sulfonamide precursors and cyclic amine derivatives, with supply chain risk centered on customs delays and shipping disruptions at major Asian export ports. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health wholesale networks to fragmented retail and institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation capabilities—particularly osmotic pump technology for modified-release dosage forms—represent the scarcest competitive asset in this market, with fewer than a dozen qualified suppliers capable of meeting FDA bioequivalence standards for extended-release sulfonylureas.
For Market Incumbents: Fortify formulary positioning through backward integration into API supply and accelerated certification of modified-release line extensions. GLP-1 receptor agonist substitution in California and New York endocrinology practices threatens first-line positioning, requiring manufacturers to deepen 340B contract pharmacy relationships and secure mandatory Medicaid preferred drug list status in Ohio, Pennsylvania, and Michigan as defensive anchors. For New Entrants and Emerging Players: Lead with bioequivalence demonstration for extended-release glimepiride formulations, where FDA guidance on therapeutic equivalence creates first-mover advantages. The most penetrable white space sits in 340B-eligible federally qualified health centers and disproportionate share hospitals, where protected reimbursement rates outside commercial PBM influence support margin sustainability. A telehealth-integrated dispensing model targeting rural Montana and Wyoming bypasses entrenched retail pharmacy competition. For Investors and Strategic Acquirers: IRA Medicare drug price negotiation provisions reshape the acquisition landscape by compressing long-term revenue predictability for established oral antidiabetics. Target vertically integrated generic manufacturers with captive API supply and demonstrated FDA bioequivalence track records, as these assets retain defensive value under federal pricing ceilings. Watch for state-level Medicaid preferred drug list expansion decisions as the signal for generic volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Formulation Development | FDA bioequivalence certification for extended-release glimepiride unlocks Medicare Advantage tier 2 placement through quality-based contracting. |
| Backward API Integration | Captive sulfonylurea active pharmaceutical ingredient production mitigates shipping disruption risks from concentrated Asian suppliers. |
| 340B Contract Pharmacy Network Expansion | Federally qualified health centers and disproportionate share hospitals provide protected reimbursement channels outside commercial PBM spread pricing. |
| State Medicaid PDL Positioning | Mandatory substitution status in Ohio, Pennsylvania, and Michigan secures volume certainty under state pharmacy and therapeutics committee control. |
| Telehealth Platform Integration | Virtual endocrinology prescribing in rural Montana and Wyoming concentrates maintenance therapy volume with vertically integrated digital health operators. |
Research Methodology
Operator-level perspectives from formulary directors at major pharmacy benefit managers, hospital pharmacy procurement managers in Texas and Florida integrated delivery networks, and regulatory affairs leads at generic manufacturers anchored the qualitative base. These primary interviews combined with secondary validation from FDA ANDA filings, Medicare Part D formulary databases, Health Canada Therapeutic Products Directorate approvals, and state Medicaid preferred drug list publications. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources to establish segment boundaries.
Sensitivity analysis around IRA Medicare price negotiation implementation timelines and GLP-1 receptor agonist substitution rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular type, formulation technology, end-user setting, and regional regulatory cluster. CAGRs derived from prescription volume trajectories adjusted for patient population shifts and formulary tier migration patterns, with specific inputs including bioequivalence study completion rates and 340B contract pharmacy enrollment growth.
Forecasts assume regulatory continuity in FDA bioequivalence standards and IRA Medicare negotiation provisions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market