
 Octocrylene Market | 2026-2036
Octocrylene Market Size, Share, and Industry Trends Forecast 2026-2036
Octocrylene Market Outlook
Pharmaceutical-grade purity specifications are rotating toward the center of supplier strategy as formulators face tighter photostability mandates. BASF SE leverages its integrated aromatics chain to secure feedstock consistency for high-purity output. Croda International Plc anchors its position through lipid-specialist expertise in emulsion-compatible grades. Evonik Industries AG differentiates via silicone-integrated delivery systems that enhance octocrylene dispersion.
Octocrylene is an organic UV-B filter, chemically classified as 2-ethylhexyl 2-cyano-3,3-diphenylacrylate with peak absorption near 303 nm, synthesized through Knoevenagel condensation of diphenylacrylonitrile with 2-ethylhexanol; it primarily stabilizes avobenzone and extends sunscreen photoprotection. The cosmetics segment leads volume as prestige brands reformulate for reef-safe compatibility, while the sunscreen segment captures the fastest expansion driven by SPF inflation in tropical markets. Liquid formulations dominate manufacturing throughput, though emulsion forms command margin premiums in dermatological channels.
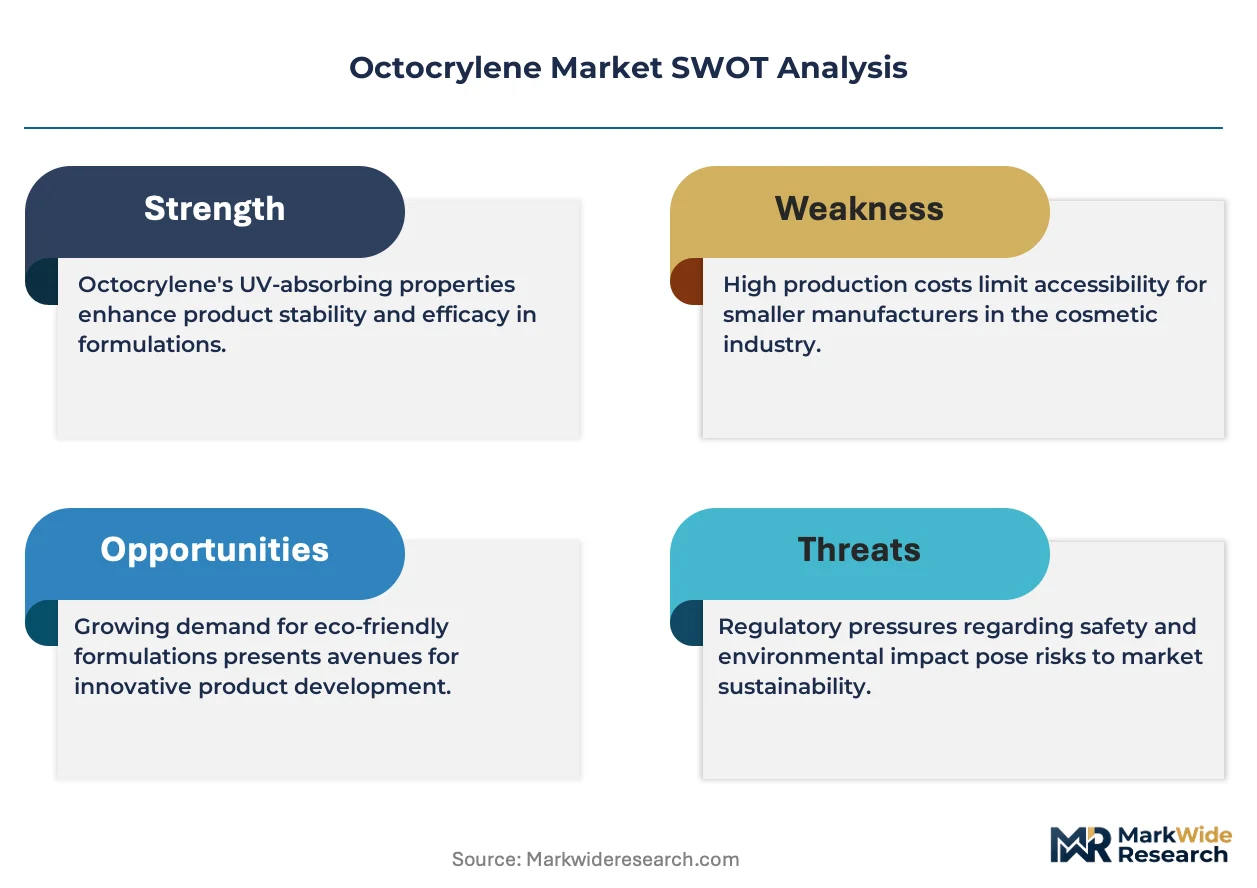
FDA sunscreen monograph revisions and REACH substance evaluation in Europe are constricting impurity thresholds, forcing raw material requalification across supply chains. ECHA's persistent, bioaccumulative and toxic screening is elevating documentation burdens for Asian exporters seeking EU market access. Stakeholders must monitor regulatory divergence between FDA photostability requirements and EU ecotoxicity criteria when allocating R&D budgets.
Market Dynamics
FDA photostability testing mandates are compressing supplier qualification timelines while REACH substance evaluation in Europe simultaneously elevates documentation burdens for UV filter manufacturers serving dual markets.
Growth Catalysts
- SPF inflation in tropical markets:Sunscreen formulators in Brazil and Southeast Asia are escalating octocrylene loadings to achieve higher protection ratings, driving volume demand for photostabilized grades.
- REACH compliance premiums:German and French cosmetics manufacturers are sourcing premium-grade octocrylene with enhanced purity documentation to satisfy ECHA persistent, bioaccumulative and toxic screening protocols.
- Avobenzone stabilization requirement:The technical necessity of octocrylene as a photostabilizer for UV-A filters is locking in formulation inclusion across broad-spectrum sunscreen development pipelines.
Market Restraints
- Feedstock volatility in aromatics:Diphenylacrylonitrile precursor costs fluctuate with benzene derivative pricing, squeezing margin predictability for Knoevenagel condensation producers.
- Reef-safe substitution pressure:Hawaii and Key West marine ecosystem regulations are restricting octocrylene concentrations, forcing reformulation toward mineral alternatives in coastal tourism markets.
- Asian export documentation burden:ECHA's elevated substance evaluation requirements are extending requalification timelines for Chinese and Indian suppliers seeking EU market access.
Strategic Opportunities
- Dermatological channel expansion:Emulsion-compatible octocrylene grades command margin premiums in prescription skincare lines addressing photosensitivity conditions.
- Silicone-integrated delivery systems:Hybrid formulations combining octocrylene with silicone carriers are penetrating prestige cosmetics segments seeking enhanced skin-feel performance.
- Indian pharmaceutical-grade demand:CDSCO tightening of topical drug photostability standards is creating new qualification pathways for high-purity octocrylene suppliers.
Industry Challenges
- Analytical method standardization:Divergent FDA and ECHA impurity threshold definitions force manufacturers to maintain dual testing protocols, complicating quality assurance workflows.
- Photostability validation capex:In-house solar simulator installation and ICH Q1B compliance infrastructure require substantial capital deployment for mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octocrylene Market |
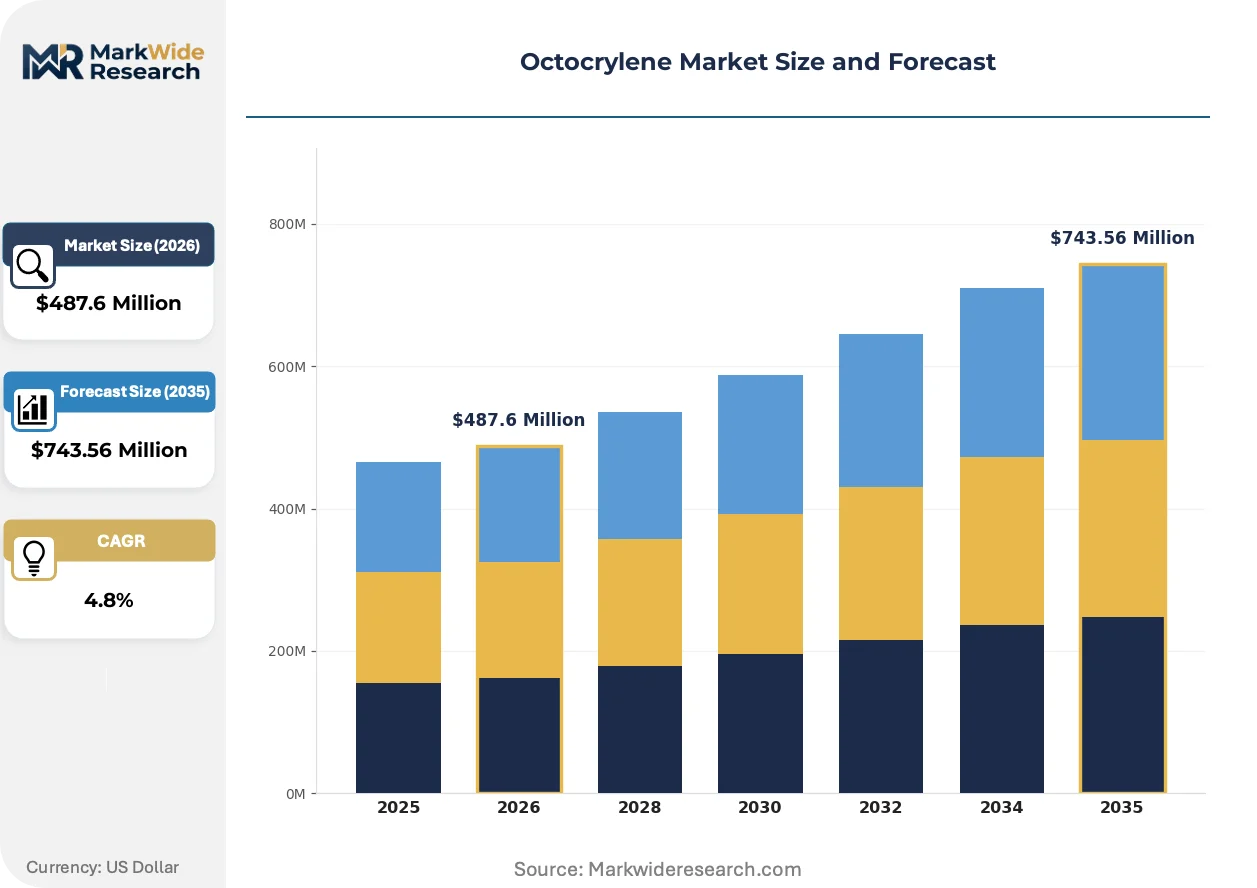
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Sunscreen, Sunblock, Pharmaceuticals Form: Liquid, Paste, Gel, Emulsion Application: Personal Care, Household Products, Industrial Coatings, Agricultural Chemicals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | BASF SE, Ashland Global Holdings Inc., Croda International Plc, Evonik Industries AG, Clariant AG, Symrise AG, AkzoNobel, Arkema, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octocrylene Market Strategic Shifts
Reef-safe formulation pressures and photostability mandates are simultaneously pulling octocrylene demand in opposing directions, forcing suppliers to innovate around concentration efficiency and delivery system compatibility.
Encapsulated octocrylene technologies using lipid or polymer shells are supplanting conventional free-form UV filters in prestige sunscreen lines. Prestige cosmetics houses in France and the United States are accelerating adoption of these systems to reduce dermal penetration concerns while maintaining SPF performance. This encapsulation shift is compressing demand for standard liquid grades while expanding specification complexity for emulsion-compatible variants.
REACH substance evaluation under ECHA's persistent, bioaccumulative and toxic screening framework is tightening impurity thresholds for organic UV filters entering European cosmetics supply chains. Manufacturers must now submit enhanced environmental fate data, extending raw material requalification cycles by several quarters. German formulators are responding by consolidating supplier bases toward integrated aromatics producers with captive analytical capabilities.
Direct-to-dermatologist sampling programs are displacing traditional retail channel marketing for photostabilized sunscreen formulations. Medical aesthetic clinics in São Paulo and Miami are becoming primary education nodes for broad-spectrum protection, shifting promotional spend toward professional sampling and clinical validation studies. This channel rotation elevates demand for documentation-heavy pharmaceutical-grade octocrylene over standard cosmetic grades.
Octocrylene Market Segmentation
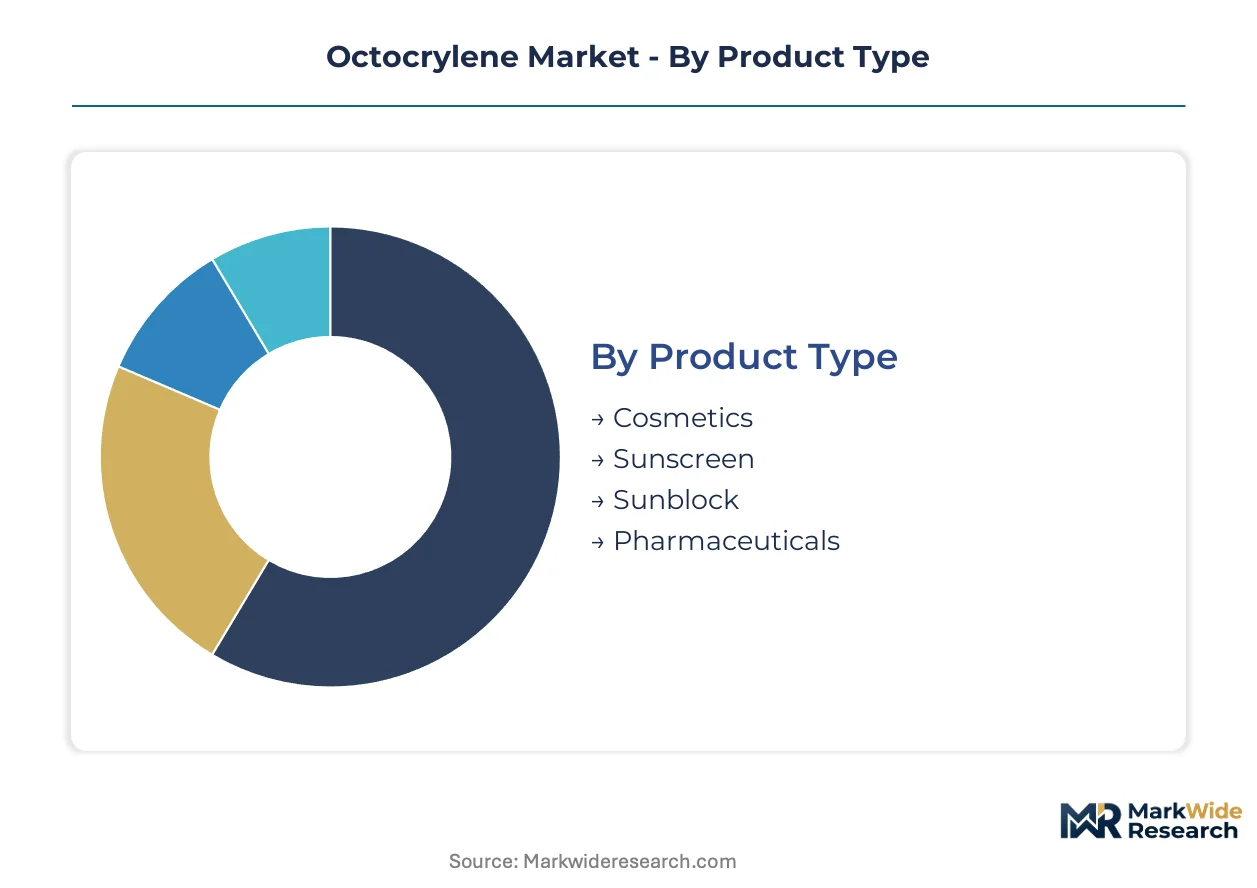
Octocrylene segmentation reflects divergent regulatory thresholds across end-use applications. FDA photostability mandates and REACH substance evaluation create distinct purity tiers that reshape supplier-customer matching.
Product Type:
FDA sunscreen monograph revisions and ECHA persistent, bioaccumulative and toxic screening impose differentiated documentation burdens across product categories.
- Cosmetics:Prestige skincare formulations incorporate octocrylene for photostabilized UV protection in color cosmetics and daily moisturizers. French and German manufacturers source premium-grade material with enhanced impurity documentation to satisfy REACH compliance premiums. Reef-safe substitution pressure in Hawaii and Key West is forcing concentration reductions in coastal-market facial products.
- Sunscreen:SPF inflation in Brazil and Southeast Asian markets escalates octocrylene loadings for higher protection ratings. Tropical-market formulators prioritize photostabilized grades that extend avobenzone efficacy in broad-spectrum beach and sport formulations. Direct-to-dermatologist sampling programs in São Paulo and Miami elevate demand for pharmaceutical-grade documentation over standard cosmetic tiers.
- Sunblock:Mineral-hybrid formulations combine octocrylene with zinc oxide for reduced dermal penetration profiles. Pediatric and sensitive-skin lines in Germany favor lower-concentration variants with enhanced purity certification.
- Pharmaceuticals:CDSCO tightening of topical drug photostability standards in India creates new qualification pathways for high-purity suppliers. Prescription photosensitivity treatments require ICH Q1B-compliant validation data.
Sunscreen handles the majority of throughput; pharmaceuticals is the fastest mover on share.
Form:
Manufacturing cost structures and emulsion compatibility requirements segment form selection across customer tiers.
- Liquid:Standard Knoevenagel condensation output dominates bulk manufacturing throughput for mass-market sunscreen production. Diphenylacrylonitrile precursor availability from integrated aromatics producers secures feedstock consistency for high-volume liquid grades.
- Paste:Concentrated solid-phase formulations serve stick and balm applications in sport and lip-care segments. Higher active loading reduces packaging volumes for travel-retail formats.
- Gel:Transparent aqueous-alcohol systems penetrate male grooming and daily-use facial categories in Southeast Asian markets. Rapid skin absorption drives preference in humid climates.
- Emulsion:Lipid-compatible grades command margin premiums in dermatological channels addressing photosensitivity conditions. Croda International Plc anchors positioning through specialist expertise in emulsion-compatible variants for prescription skincare lines.
Liquid forms handle the majority of throughput; emulsion is expanding most quickly on margin contribution.
Application:
End-use concentration requirements and environmental release profiles determine grade specification across sectors.
- Personal Care:Daily-use skincare and hair-care formulations incorporate octocrylene for incidental UV exposure protection. Brazilian and French cosmetics houses drive volume through prestige brand reformulation for reef-safe compatibility.
- Household Products:Functional coatings for plastics and textiles utilize octocrylene for polymer photostabilization. Industrial buyers prioritize cost-optimized liquid grades with standard purity documentation.
- Industrial Coatings:Exterior architectural and automotive clearcoats require UV-B absorption for substrate protection. Formulators balance octocrylene loading with yellowing resistance in alkyd and acrylic systems.
- Agricultural Chemicals:Crop protection formulations employ octocrylene as a photostabilizer for active ingredients. ECHA environmental fate data requirements extend requalification timelines for suppliers serving EU agricultural markets.
Personal care handles the majority of throughput; industrial coatings is gaining share fastest on construction sector expansion.
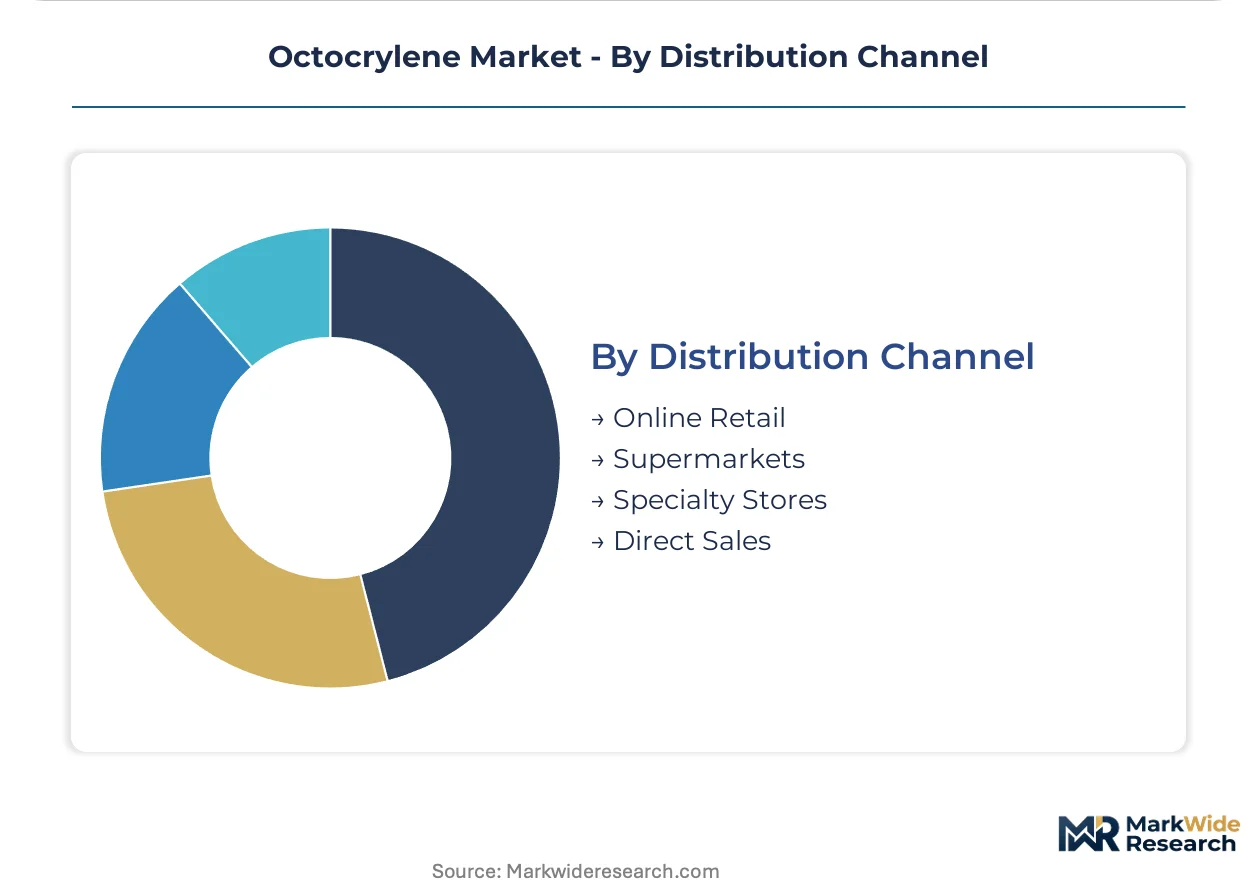
Distribution Channel:
Customer procurement scale and documentation requirements segment channel preference across buyer types.
- Online Retail:Direct-to-consumer sunscreen brands in the United States and Brazil leverage e-commerce for reef-safe formulation education. Subscription models drive recurring demand for premium encapsulated grades.
- Supermarkets:Mass-market volume concentrates in hypermarket chains across Southeast Asia and Latin America. Price-competitive liquid grades dominate shelf-space allocation.
- Specialty Stores:Prestige cosmetics boutiques in France and Germany curate photostabilized formulations with enhanced purity certification. Beauty advisors provide clinical validation narratives for dermatological-grade products.
- Direct Sales:Pharmaceutical and industrial buyers procure through supplier technical service teams for custom specification development. CDSCO and FDA compliance documentation accompanies direct contracts.
Supermarkets handle the majority of throughput; direct sales is climbing the fastest on pharmaceutical and industrial qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical exporters ship photostabilized octocrylene grades to Brazilian sunscreen formulators seeking REACH-compliant documentation for tropical-market SPF inflation.
United States
FDA photostability testing mandates compress supplier qualification timelines for domestic sunscreen manufacturers. Hawaii and Key West marine ecosystem regulations restrict octocrylene concentrations in coastal tourism markets. Miami medical aesthetic clinics anchor direct-to-dermatologist sampling programs for broad-spectrum protection formulations.
Germany
REACH substance evaluation elevates documentation burdens for UV filter manufacturers serving dual markets. ECHA persistent, bioaccumulative and toxic screening protocols drive premium-grade sourcing from integrated aromatics producers. Frankfurt-Rhine-Main chemical clusters consolidate supplier bases toward captive analytical capabilities.
Brazil
SPF inflation in tropical markets escalates octocrylene loadings for higher protection ratings. ANVISA alignment with international photostability standards tightens import documentation for Asian suppliers. São Paulo formulators prioritize photostabilized grades that extend avobenzone efficacy in beach and sport segments.
France
Prestige cosmetics houses accelerate adoption of encapsulated octocrylene technologies to reduce dermal penetration concerns. ECHA environmental fate data requirements extend raw material requalification cycles by several quarters. Paris-region beauty boutiques curate photostabilized formulations with enhanced purity certification.
India
CDSCO tightening of topical drug photostability standards creates new qualification pathways for high-purity suppliers. Pharmaceutical-grade demand concentrates in prescription photosensitivity treatments requiring ICH Q1B-compliant validation data. Maharashtra-based formulators drive volume through dermatological channel expansion.
Octocrylene Market Competitive Environment
Listed leaders compete with private specialists across feedstock integration and emulsion compatibility dimensions. The supplier base organizes around three tiers: integrated aromatics producers with captive precursor supply, lipid-specialist formulators serving dermatological channels, and silicone-integrated delivery system innovators. Consolidation pressures favor backward integration into diphenylacrylonitrile production and strategic partnerships for REACH-compliant documentation.
Among Germany-based integrated chemical producers, BASF SE and Evonik Industries AG exemplify the feedstock-integrated archetype. BASF SE leverages its aromatics chain position for high-purity output consistency. Evonik Industries AG occupies a position in silicone-integrated delivery systems. UK-based Croda International Plc represents the lipid-specialist tier anchoring emulsion-compatible grade development. These three companies illustrate how geographic clustering around regulatory expertise shapes competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Ashland Global Holdings Inc. |
| Croda International Plc |
| Evonik Industries AG |
| Clariant AG |
| Symrise AG |
| AkzoNobel |
| Arkema |
| Givaudan SA |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between integrated aromatics producers and German sunscreen formulators lock in feedstock access for photostabilized grades while anchoring price visibility against benzene derivative volatility. These contracts concentrate procurement power among REACH-compliant suppliers with captive diphenylacrylonitrile production, compressing spot-market liquidity for mid-scale buyers.
Pricing Analysis
The pricing gap between emulsion-compatible pharmaceutical grades and standard liquid cosmetic grades exceeds that between prior-generation photostabilized variants and next-generation encapsulated delivery systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification and documentation burden, with FDA photostability validation tiers commanding substantial premiums over baseline REACH compliance. Pricing pressure stems from feedstock volatility in aromatics squeezing margin predictability for Knoevenagel condensation producers. Mass-market sunscreen manufacturers in Southeast Asia exhibit highest price sensitivity, while dermatological channel buyers in Germany and France prioritize certification grade over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and French formulators facing ECHA substance evaluation delays, while just-in-time procurement persists in Brazilian tropical-market operations. Supply concentrates in Germany, China, and India, with integrated aromatics producers in Frankfurt-Rhine-Main chemical clusters anchoring high-purity output. Raw material dependencies center on diphenylacrylonitrile precursors, benzene derivatives, and 2-ethylhexanol feedstocks. Single-source vulnerability from concentrated aromatics production creates structural exposure to regulatory restriction. Distribution runs through direct technical service contracts for pharmaceutical and industrial buyers, with specialty stores and supermarkets handling downstream cosmetics volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA photostability mandates and REACH substance evaluation erect documentation barriers that favor incumbent suppliers with captive analytical capabilities and established qualification histories.
For Market Incumbents: Fortify position through backward integration into diphenylacrylonitrile production and capacity reservation for emulsion-compatible grade expansion in Maharashtra and São Paulo. The threat of reef-safe substitution pressure in coastal tourism markets demands accelerated silicone-integrated delivery system R&D. Certification investment in ICH Q1B-compliant validation infrastructure anchors dermatological channel control against emerging lipid-specialist competitors.
For New Entrants and Emerging Players: Lead with encapsulated octocrylene technologies targeting prestige cosmetics houses in France and the United States seeking reduced dermal penetration profiles. The most penetrable white space sits in Indian pharmaceutical-grade supply following CDSCO photostability tightening, where documentation-heavy qualification pathways disadvantage commodity traders. A go-to-market angle emphasizing direct-to-dermatologist sampling program partnerships in Miami and São Paulo bypasses saturated retail channel competition.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated aromatics producers with captive precursor supply and established REACH documentation workflows. Long-term viability over the projection horizon rests on regulatory entrenchment deepening rather than commodity cyclicality. The acquisition target archetype combines backward feedstock integration with emulsion-specialist formulation expertise. Watch for ECHA persistent, bioaccumulative and toxic screening threshold revisions as the inflection signal for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diphenylacrylonitrile | Captive precursor supply secures margin predictability against benzene derivative volatility for German producers. |
| Encapsulated Delivery System Development | Polymer-shell technologies penetrate prestige cosmetics segments in France seeking reduced dermal penetration profiles. |
| ICH Q1B Validation Infrastructure Investment | Compliance capability unlocks pharmaceutical-grade qualification pathways in Indian prescription photosensitivity treatments. |
| Direct-to-Dermatologist Sampling Programs | Miami and São Paulo medical aesthetic clinics displace retail channels as primary education nodes for broad-spectrum protection. |
| REACH-Compliant Documentation Consolidation | Enhanced environmental fate data submission accelerates raw material requalification cycles for ECHA substance evaluation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across sunscreen formulators, specialty chemical procurement leads, plant managers at integrated aromatics producers, and regulatory affairs directors navigating FDA and ECHA compliance. Secondary validation drew from FDA sunscreen monograph filings, ECHA substance evaluation dossiers, customs trade data for UV filter imports, and SEC disclosures from listed chemical producers. Bottom-up volume estimates from end-use application loadings were triangulated against top-down market sizing from producer capacity disclosures.
Across the analysis window, the analytical framework modeled segmentation by product type, form, application, and distribution channel, with regional regulatory cluster as an additional dimension. CAGRs were derived from regression analysis of historical volume trends against projected SPF inflation rates and formulation loading assumptions. Industry-specific forecast inputs included avobenzone stabilization demand coefficients and reef-safe substitution elasticity parameters for coastal tourism markets.
The analysis sits within stated boundaries; outcomes outside sustained FDA photostability mandate enforcement or ECHA persistent, bioaccumulative and toxic screening acceleration would require recalibration. Forecasts reflect assumptions regarding benzene derivative price stability and tropical-market SPF inflation continuity. Revision becomes warranted when reef-safe regulatory restrictions cross thresholds that trigger mass reformulation toward mineral alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Bio-Based Phenol Market