
 Keratin Products Market | 2026-2036
Keratin Products Market Size, Share, and Industry Trends Forecast 2026-2036
Keratin Products Market Foresight
Multi-step treatment kits are restructuring how consumers engage with keratin products, shifting standalone purchases toward bundled regimens that combine in-salon procedures with take-home maintenance. Croda International Plc leverages its specialty-ingredient portfolio to supply hydrolyzed keratin variants for premium hair-care brands. BASF SE anchors its position through backward integration into amino-acid-derived biopolymers that feed cosmetic-grade keratin production. Active Concepts competes by specializing in fermented keratin alternatives that appeal to clean-beauty formulators.
Keratin products comprise formulations incorporating hydrolyzed keratin proteins, typically at molecular weights between 1,000 and 10,000 daltons, designed to deposit protective films on hair cuticles or strengthen keratinized skin and nail tissues. Hair Care applications dominate volume, with salon-grade smoothing treatments commanding the thickest margin pools due to professional service markups and repeat-visit economics. Masks and Treatments within the Product Type dimension represent the fastest-expanding category, fueled by at-home alternatives to formaldehyde-based salon services. Powder and Spray forms are gaining traction in Cosmetic Formulation channels where manufacturers seek concentrated, preservative-light inputs.
FDA oversight of cosmetic safety claims and EPA scrutiny of formaldehyde-releasing preservatives constrain formulation choices in the United States, while REACH registration requirements in Europe mandate extensive toxicity documentation for imported keratin hydrolysates. The EU Green Deal's chemical-sustainability targets are pushing suppliers toward bio-sourced and enzymatically processed alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin structures.
Market Dynamics
Professional salon channels are consolidating service menus around formaldehyde-free keratin protocols, compressing demand for legacy smoothing treatments while expanding recurring revenue from maintenance regimens.
Growth Catalysts
- Brazilian post-treatment maintenance culture:Recurring home-use purchases of sulfate-free shampoos and conditioning masks create predictable revenue streams tied to in-salon procedures.
- REACH-compliant hydrolysate imports:European formulators seeking pre-registered keratin variants are pulling supply chain investment toward ECHA-documented production facilities.
- Fermented biopolymer technology:Enzymatic processing of plant-derived amino acid precursors is opening clean-label positioning for brands targeting Sephora and Ulta clean-beauty certifications.
Market Restraints
- Formaldehyde liability exposure:EPA scrutiny of methylene glycol-releasing preservatives in salon treatments has triggered professional liability insurance exclusions in California and New York.
- Sheep wool supply concentration:Over 60% of cosmetic-grade keratin hydrolysates derive from Australian and New Zealand wool processing, exposing margins to agricultural commodity cycles and drought-driven fiber shortages.
- Molecular weight standardization gaps:Absence of ISO-certified reference methods for 1,000-10,000 dalton verification forces brands to maintain redundant in-house testing protocols.
Strategic Opportunities
- Indian professional salon expansion:Tier-2 and Tier-3 cities in Maharashtra and Karnataka show underpenetrated demand for keratin smoothing services among bridal and festive occasion segments.
- Cosmetic formulation powder concentrates:Spray-dried keratin isolates with 24-month stability profiles are displacing liquid hydrolysates in contract manufacturing for indie beauty brands.
- EU Green Deal biopolymer mandates:Chemical sustainability targets are creating preferential procurement pathways for enzymatically processed keratin alternatives in German and French retail chains.
Industry Challenges
- Cosmetic chemist specialization shortage:Formulators capable of stabilizing low-molecular-weight proteins in anhydrous systems command premium compensation that mid-tier brands struggle to absorb.
- Multi-jurisdiction dossier compilation:Simultaneous FDA cosmetic notification, REACH registration, and Health Canada hotlist compliance requires dedicated regulatory affairs headcount that fragments at sub-$50M revenue scales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratin Products Market |
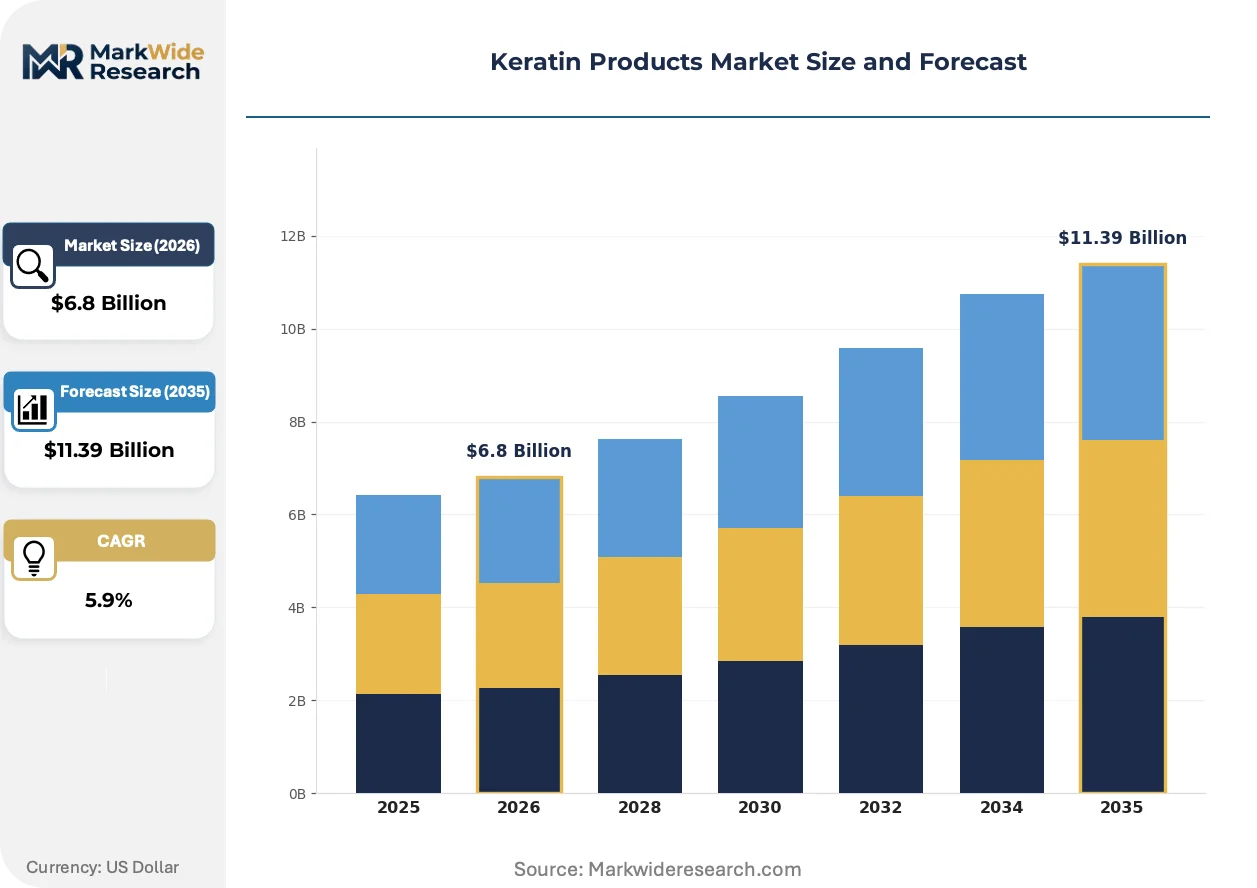
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Masks, Treatments Application: Hair Care, Skin Care, Nail Treatment, Cosmetic Formulation Form: Liquid, Cream, Powder, Spray Distribution Channel: Online Retail, Supermarkets, Salons, Specialty Stores |
| Companies Covered | Croda International Plc, BASF SE, Active Concepts, Tri K Industries, Sigma Aldrich, UMP Keraglow, Sia Fluffy Unlimited, Keraplast Technologies, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratin Products Market Shifts & Advancements
Formulation science and channel economics are restructuring how keratin products reach end-users, with biotechnology and regulatory chemistry driving the most consequential shifts in competitive positioning.
Enzymatic hydrolysis systems are converging with precision fermentation platforms to produce keratin-mimetic peptides from non-animal amino acid feedstocks. Clean-beauty formulators at Sephora and Ulta are adopting these variants at 18-24 month substitution cycles. This convergence is compressing traditional wool-derived supply chains while opening price-premium positioning for certified cruelty-free claims.
REACH registration requirements for imported protein hydrolysates are tightening documentation burdens on non-EU suppliers. ECHA's 2024 updated guidance on skin sensitization endpoints now demands extended local lymph node assay data for new keratin submissions. Salon-grade treatment manufacturers sourcing from South American and Asian hydrolysate producers are absorbing 12-18 month approval delays or pivoting to EU-registered intermediate suppliers.
Subscription-based replenishment programs are displacing single-transaction retail purchases for at-home keratin maintenance kits. Direct-to-consumer brands are bundling monthly shampoo and mask deliveries with virtual styling consultations. This shift is most visible in the United States, where Ulta's digital platform and Amazon's subscribe-and-save infrastructure have concentrated recurring revenue capture among vertically integrated beauty brands.
Keratin Products Market Segmentation
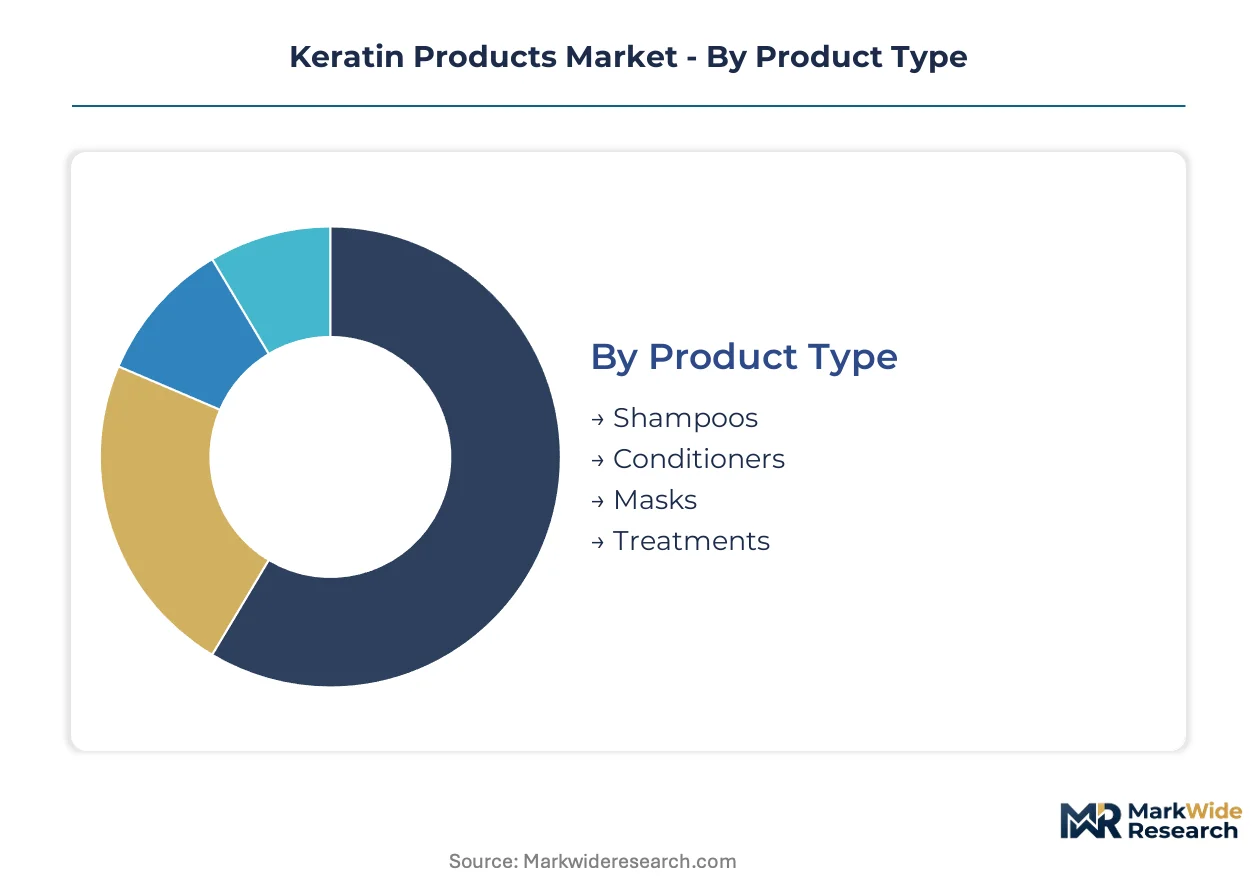
Keratin product segmentation reveals how formulation chemistry, channel economics, and regulatory exposure intersect to determine margin capture. Each dimension carries distinct certification burdens that shape supplier selection and go-to-market strategy.
Product Type:
FDA cosmetic notification requirements apply differentially across rinse-off versus leave-on formats, with leave-in treatments triggering enhanced safety substantiation.
- Shampoos:Sulfate-free cleansing bases incorporating hydrolyzed keratin at 0.5-2% concentration dominate Brazilian post-treatment maintenance regimens. Salon channels in São Paulo and Rio de Janeiro bundle these with smoothing services to lock in recurring revenue.
- Conditioners:Cationic conditioning agents stabilize low-molecular-weight keratin peptides in aqueous systems, demanding specialized cosmetic chemist expertise that mid-tier brands struggle to source.
- Masks:Intensive treatment formats with 15-30 minute contact time require REACH skin sensitization dossiers for EU import.
- Treatments:Salon-grade smoothing protocols face EPA formaldehyde scrutiny in California and New York, compressing legacy service margins.
Treatments sit at the top of the volume ranking, with Masks climbing the fastest.
Application:
End-use concentration determines whether formulations fall under cosmetic, quasi-drug, or professional-use regulatory frameworks.
- Hair Care:Professional salon services command the thickest margin pools through service markups and repeat-visit economics. Brazilian bridal and festive occasion segments drive concentrated demand in underpenetrated Tier-2 and Tier-3 cities.
- Skin Care:Keratinized tissue repair applications for barrier-compromised skin require ECHA-extended local lymph node assay data under updated REACH guidance.
- Nail Treatment:Strengthening formulations for brittle nails compete with silicone-based alternatives on price-performance metrics.
- Cosmetic Formulation:Contract manufacturers seek spray-dried keratin isolates with 24-month stability profiles to displace liquid hydrolysates.
Hair Care commands the dominant share position, while Cosmetic Formulation gains share fastest.
Form:
Physical state dictates preservative load, shipping economics, and compatibility with anhydrous or aqueous formulation systems.
- Liquid:Aqueous hydrolysates dominate salon backbar and retail shelf presence but carry heavier freight costs and shorter stability windows.
- Cream:Emulsion-based delivery systems accommodate higher oil-phase actives for intensive conditioning positioning.
- Powder:Spray-dried isolates with extended stability profiles are displacing liquid formats in contract manufacturing channels serving indie beauty brands.
- Spray:Aerosol and pump-dispersed formats require VOC compliance under EPA and CARB regulations, constraining formulation latitude.
Liquid maintains volume leadership, with Powder expanding most quickly.
Distribution Channel:
Channel selection determines margin structure, customer acquisition cost, and regulatory liability exposure for professional versus consumer positioning.
- Online Retail:Direct-to-consumer subscription programs bundle monthly replenishment with virtual styling consultations, concentrating recurring revenue capture among vertically integrated brands.
- Supermarkets:Mass-market placement demands price compression that favors commodity-grade hydrolysates over specialty biopolymer alternatives.
- Salons:Professional service integration enables formaldehyde-free protocol premiums and maintenance regimen attachment.
- Specialty Stores:Sephora and Ulta clean-beauty certifications drive 18-24 month substitution cycles toward fermented keratin alternatives.
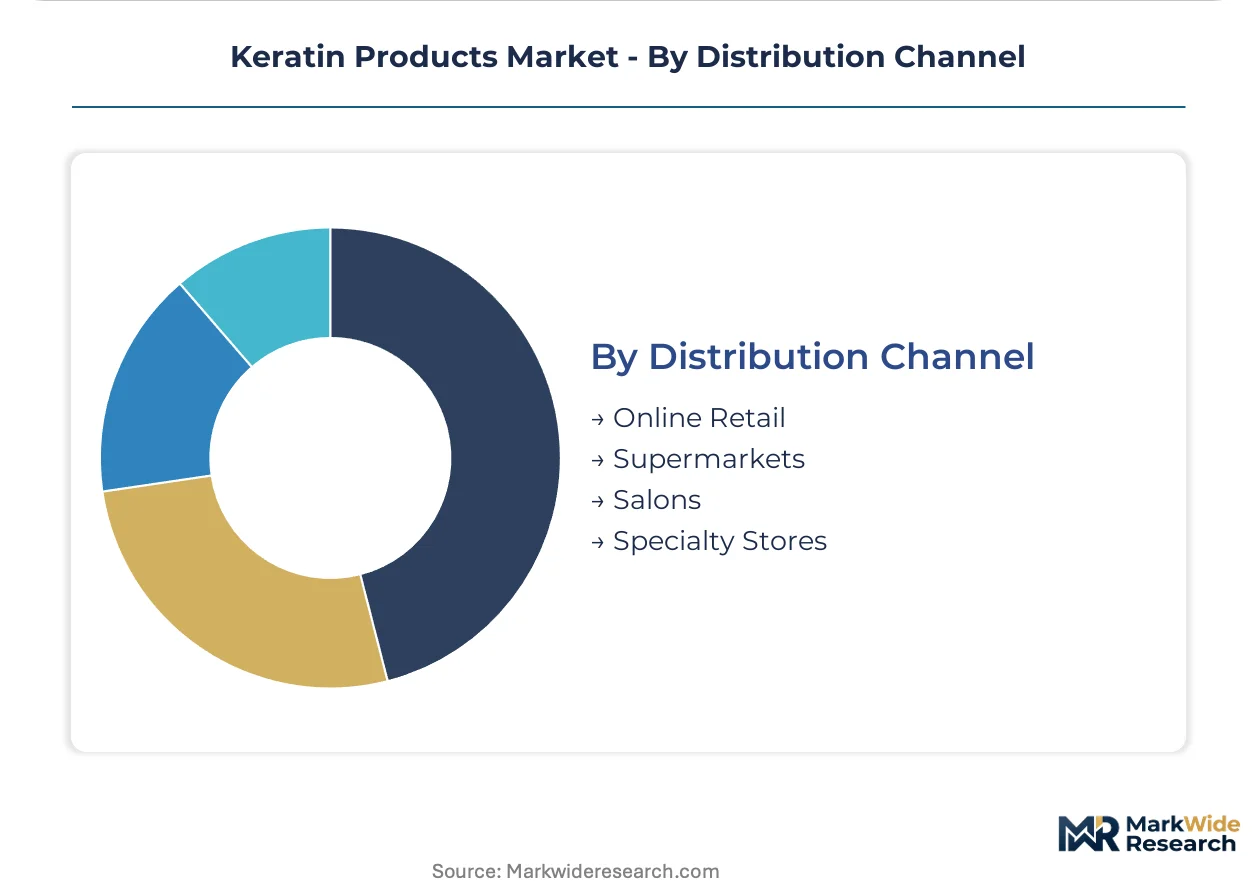
Salons anchor the volume base, with Online Retail showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered the formaldehyde-based keratin smoothing treatment in the early 2000s, establishing São Paulo as the industry's founding cluster. This heritage created a maintenance-culture template now diffusing to underpenetrated markets across multiple continents.
Brazil
Post-treatment maintenance regimens drive recurring purchases of sulfate-free shampoos and conditioning masks tied to in-salon procedures. ANVISA oversees cosmetic safety claims and restricts formaldehyde-releasing preservatives in professional treatments. São Paulo and Rio de Janeiro salons bundle home-use formulations with smoothing services to lock in repeat revenue from bridal and festive occasion segments.
United States
Direct-to-consumer subscription programs for at-home keratin maintenance kits concentrate recurring revenue capture among vertically integrated beauty brands. EPA scrutiny of methylene glycol-releasing preservatives has triggered professional liability insurance exclusions in California and New York. Ulta's digital platform and Amazon's subscribe-and-save infrastructure in Chicago and Los Angeles metro areas accelerate channel shift toward bundled replenishment.
Germany
EU Green Deal chemical-sustainability targets create preferential procurement pathways for enzymatically processed keratin alternatives in retail chains. ECHA's 2024 updated guidance on skin sensitization endpoints demands extended local lymph node assay data for new keratin submissions. Frankfurt and Munich specialty stores anchor clean-beauty certification adoption with 18-24 month substitution cycles toward fermented biopolymer variants.
India
Tier-2 and Tier-3 cities in Maharashtra and Karnataka show underpenetrated demand for keratin smoothing services among bridal and festive occasion segments. BIS standards for cosmetic safety apply to imported protein hydrolysates entering through Mumbai and Chennai ports. Bangalore's professional salon expansion targets first-time keratin service adoption outside traditional metro concentrations.
China
Contract manufacturers seek spray-dried keratin isolates with extended stability profiles to displace liquid hydrolysates in indie beauty brand production. NMPA cosmetic registration requirements govern safety substantiation for leave-on treatment formats. Shanghai and Guangzhou formulation houses drive powder concentrate adoption for preservative-light, concentrated inputs.
Keratin Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hydrolysate sourcing and certification tiers. Specialty-ingredient suppliers with REACH-registered dossiers and enzymatic processing capabilities command pricing power over wool-derived commodity hydrolysate traders. Three archetypes dominate: multinational chemical conglomerates with backward integration into amino-acid biopolymers, mid-cap specialty-ingredient houses with fermentation platforms, and regional distributors of Australian and New Zealand wool-derived hydrolysates. Competitive moves center on ECHA registration acquisition for EU market access and subscription-based bundling of salon services with home-use maintenance regimens.
Within the multinational tier, Croda International Plc and BASF SE exemplify divergent sourcing strategies. Croda leverages specialty-ingredient positioning to supply hydrolyzed keratin variants for premium hair-care brands, while BASF anchors through upstream control over amino-acid-derived biopolymers feeding cosmetic-grade production. Active Concepts occupies a position within the clean-beauty specialist tier, representing fermented keratin alternatives that appeal to Sephora and Ulta certification requirements.
| Leading Market Players |
|---|
| Croda International Plc |
| BASF SE |
| Active Concepts |
| Tri K Industries |
| Sigma Aldrich |
| UMP Keraglow |
| Sia Fluffy Unlimited |
| Keraplast Technologies |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Cosmetic chemist specialization shortages in Western Europe and North America widen spreads between premium salon-grade formulations and commodity retail alternatives. Labor-cost differentials between fermentation-platform specialists and conventional hydrolysate processors translate into pricing-tier stratification that rewards REACH-registered dossier holders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs keratin product transactions. Premium tiers command spreads based on ECHA registration status and enzymatic processing certification, while economy tiers compete on wool-derived hydrolysate volume. Cost compression in standard-tier salon backbar products is intensifying because Brazilian and Indian contract manufacturers are scaling fermentation alternatives. Professional salon channels show least price sensitivity due to service markup absorption, whereas mass-market retail buyers in supermarket channels exhibit highest elasticity.
Supply Chain Analysis
REACH-compliant hydrolysate qualification gates EU market access for non-registered suppliers. Raw material flows draw from Australian and New Zealand wool processing, Chinese enzymatic fermentation platforms, and Indian botanical amino acid feedstocks. Keratin peptide isolates, preservative-light powder concentrates, and cationic conditioning agents constitute critical input dependencies. Single-source vulnerability concentrates in Australian wool fiber supply exposed to drought-driven agricultural commodity cycles. Distribution runs through professional salon networks for service-integrated protocols, direct-to-consumer subscription platforms for maintenance regimens, and contract manufacturing channels for indie beauty brand supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The keratin products market represents a late-cycle quality story where bridal and festive occasion demand in underpenetrated Indian Tier-2 cities is shifting specifications toward formaldehyde-free, clean-beauty certified formulations.
For Market Incumbents: Anchor defensive positioning through backward integration into amino acid biopolymer production and captive supply of fermentation-platform capacity. Croda International Plc and BASF SE demonstrate how REACH-registered dossier depth insulates against emerging clean-beauty specialist threats. Prioritize certification investment in ECHA skin sensitization endpoints to maintain EU pricing power.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian professional salon channels offers white-space entry. Target Maharashtra and Karnataka Tier-2 cities for first-time keratin service adoption among bridal segments. Pursue fermented keratin alternatives with ANVISA pre-registration to bypass legacy wool supply concentration. Direct-to-consumer subscription bundling with virtual styling consultations provides differentiated go-to-market positioning against established salon networks.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with personal care ingredient portfolios are the most active acquirer in this space, seeking fermentation-platform capabilities and clean-beauty certification assets. Five-to-ten year viability hinges on substitution cycle acceleration toward plant-derived biopolymers. Acquisition target archetype: mid-cap enzymatic processing specialists with Sephora and Ulta certification relationships. Monitor ECHA registration approval velocity as inflection indicator for supply chain reconfiguration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Biopolymers | BASF SE's upstream control reduces exposure to Australian wool commodity cycles. |
| REACH Registration Acquisition | ECHA-compliant dossiers unlock preferential procurement pathways in German retail chains. |
| Fermentation Platform Scale-Up | Active Concepts' enzymatic processing captures Sephora clean-beauty certification demand. |
| Subscription-Based Replenishment Programs | Ulta's digital infrastructure concentrates recurring revenue among vertically integrated brands. |
| Formaldehyde-Free Protocol Certification | ANVISA-compliant alternatives displace legacy treatments in São Paulo salon networks. |
Research Methodology
Multiple input streams — primary interviews with cosmetic formulators and salon chain procurement directors, secondary validation through ECHA registration databases and ANVISA cosmetic safety filings, trade data reconciliation — were synthesized across the analysis window. Conversations with professional salon owners in São Paulo and Mumbai, contract manufacturing executives in Shanghai, and specialty-ingredient procurement leads at Sephora and Ulta supplied demand-side intelligence. Bottom-up volume modeling from product-type segmentation and top-down cross-checks against customs records for keratin hydrolysate imports ensured analytical consistency.
Historical shipment patterns were cross-referenced against panel input from industry stakeholders to construct projection trajectories. Segmentation dimensions spanned product type, application, form, and distribution channel, with regulatory certification tier as an industry-specific overlay. CAGRs were derived from trend extrapolation adjusted for substitution-cycle timing and channel-shift velocity. Forecast inputs included Brazilian post-treatment maintenance regimen attachment rates and Indian salon penetration curves in Tier-2 cities.
Caveats apply where ECHA guidance revisions, Australian wool supply disruptions, or clean-beauty certification standard changes could materially shift the outlook. Forecasts reflect assumptions about fermentation-platform cost curves and regulatory approval timelines. A model refresh is warranted upon material change in REACH skin sensitization endpoint requirements or ANVISA formaldehyde restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
UV/IR Blocker Market