
 Crystal Hard Wax Market | 2026-2036
Crystal Hard Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Hard Wax Market Insights
Professional salon chains are unwinding the historical dominance of individual home users as the primary volume buyers for crystal hard wax. Italwax leverages its European manufacturing base to supply private-label formulations for high-turnover spa networks. Turtle Wax competes through automotive-grade polymer expertise that it extends into cosmetic wax chemistry for cross-industry credibility.
Crystal hard wax denotes a low-viscosity, rosin-modified thermoplastic formulation that liquefies at 40–50°C and solidifies into a flexible film for non-strip hair removal. Its polymer-rich composition permits repeated application on the same skin zone without epidermal lifting, making it the preferred medium for Brazilian and facial protocols. Hard wax beads dominate the form category due to faster melt times and precise portion control in professional settings, while non-strip wax commands the highest margin pool among product types because of its premium positioning in med-spa menus. Salon end users anchor volume demand, though home-user segments are gaining traction through bead-format retail packaging.
REACH in Europe and FDA cosmetic labeling requirements in the United States both restrict allergenic colophony concentrations, pushing manufacturers toward synthetic resin substitutes. BIS certification in India adds a compliance layer for imported wax blocks entering the professional beauty channel. Stakeholders must monitor how regional dermatological testing standards reshape formulation costs and supplier qualification timelines.
Market Dynamics
Professional salon chains in Brazil are abandoning soft wax for hard wax formulations, triggering a supply-side scramble to secure polymer-modified resin capacity and reformulate legacy rosin blends for sensitive-area protocols.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on allergenic colophony are accelerating synthetic resin adoption across European manufacturing, opening premium positioning for hypoallergenic polymer blends.
- Med-spa franchise standardization:United States clinic chains are hard-coding hard wax protocols into franchise operating manuals, locking in recurring bulk procurement from approved suppliers.
- Brazilian wax protocol migration:Rio de Janeiro and São Paulo salon networks are converting treatment rooms to non-strip methods, concentrating demand for low-melt-point crystal formulations.
Market Restraints
- Gum rosin price volatility:Brazilian pine resin harvest fluctuations are squeezing margins for traditional colophony-dependent producers.
- European supply concentration:Italian and German polymer blend specialists control 70% of REACH-compliant raw material output, creating bottleneck risk for new market entrants.
- Sugar wax substitution:DIY home kits using water-soluble alternatives are capturing price-sensitive consumers in mass retail channels.
Strategic Opportunities
- Indian professional channel underpenetration:BIS certification requirements have slowed import flows, creating first-mover advantage for domestic compounders meeting bureau standards.
- Men's grooming protocol expansion:Back and chest hair removal services are adopting hard wax methods in United States urban markets, extending addressable treatment categories.
- Biodegradable bead innovation:PLA-based carrier technologies are converging with cosmetic wax chemistry to serve EU Green Deal procurement preferences.
Industry Challenges
- Thermoplastic handling certification:Salon technicians require updated training on 40–50°C melt-point management to prevent epidermal injury liability.
- Multi-jurisdiction labeling compliance:Simultaneous FDA cosmetic labeling and REACH substance registration timelines are extending product launch cycles by 8–14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Hard Wax Market |
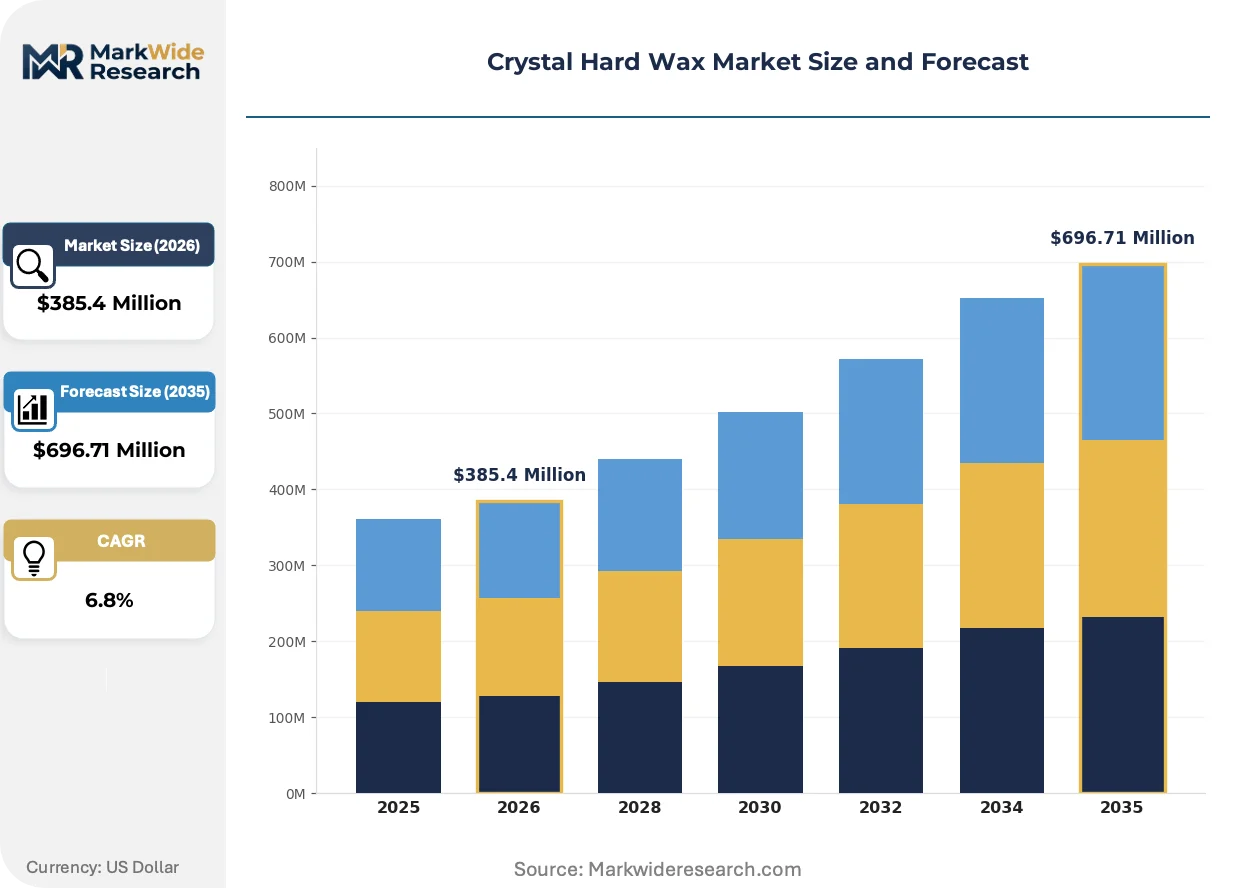
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Wax, Hard Wax, Strip Wax, Non-Strip Wax Form: Beads, Blocks, Cans, Pellets Application: Body Hair Removal, Facial Hair Removal, Eyebrow Shaping, Decorative Waxing End User: Salons, Home Users, Spa Centers, Beauty Schools |
| Companies Covered | Italwax, Waxness, Turtle Wax, Naysku, Superwax, Satin Smooth, Flamingo Car Care, Getsun, Weifang Dawn Green Valley International Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Hard Wax Market Trends and Innovations
Formulation chemistry and procurement architecture are undergoing parallel transformation. Synthetic polymer blends are capturing share from natural resins, while professional buyer consolidation is compressing supplier margins and rewiring distribution hierarchies.
Polymer-rich synthetic resin formulations are supplanting traditional rosin-modified bases in European and North American professional channels. Med-spa procurement departments are specifying these blends in franchise supply agreements to minimize liability exposure. The shift is compressing demand for Brazilian gum rosin and rewiring raw material sourcing toward petrochemical and bio-based polymer feedstocks.
REACH Annex XVII restrictions on skin-sensitizing substances are forcing reformulation of legacy hard wax lines across EU manufacturing facilities. ECHA compliance deadlines are accelerating R&D spending on synthetic substitutes before colophony concentration limits take full effect. German and Italian compounders are responding with pre-certified polymer blends that streamline downstream customer registration.
Franchise procurement officers are consolidating supplier relationships into single-source or dual-source frameworks with volume guarantees. United States med-spa chains are replacing fragmented spot-buying with multi-year supply contracts tied to protocol standardization. This concentration is disintermediating regional distributors and pushing volume directly to compounders with scale certification.
Crystal Hard Wax Market Segmentation
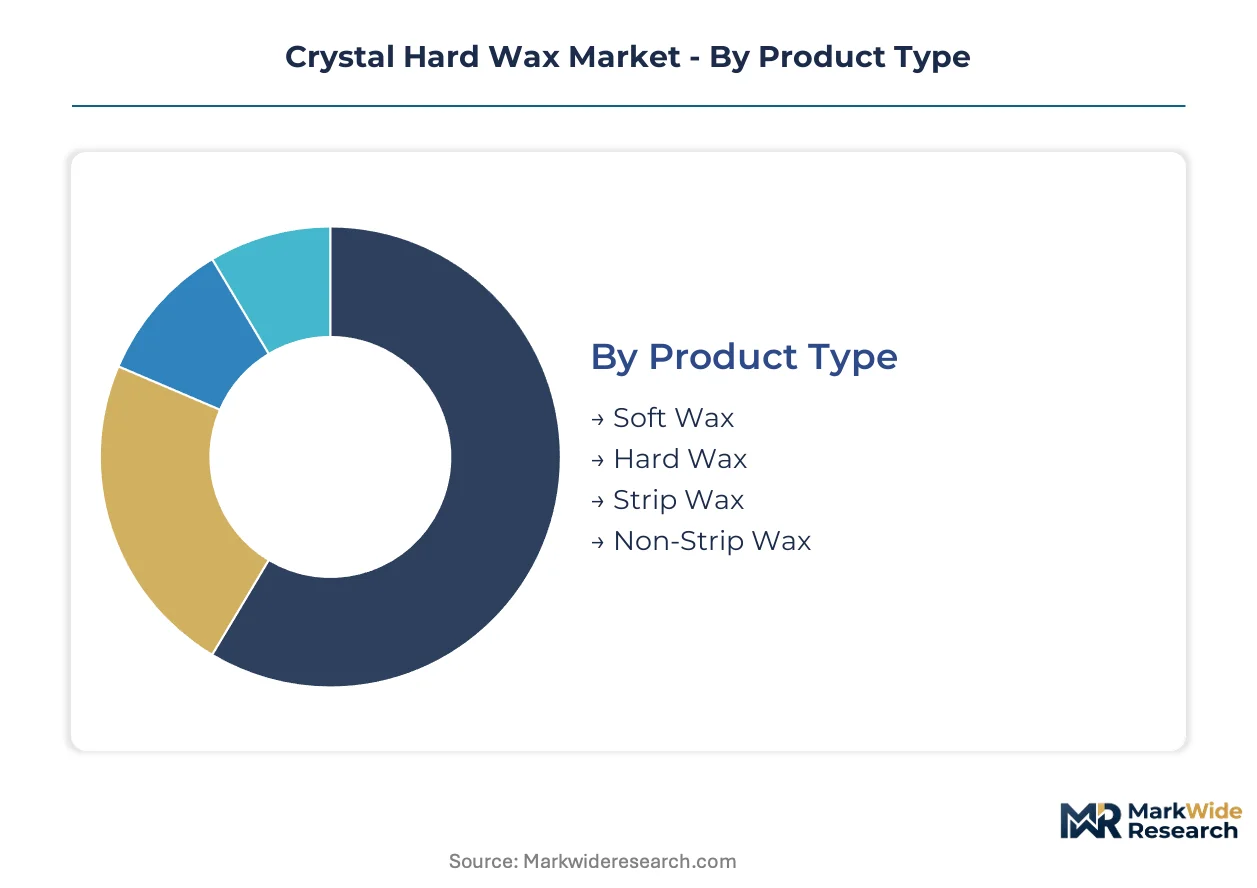
Crystal hard wax segmentation reveals divergent supply chain architectures across product categories. Formulation chemistry and packaging format determine whether segments serve fragmented domestic salon networks or consolidated export-led professional channels.
Product Type:
Hard wax formulations dominate export volumes to professional salon chains in Brazil and the United States, while soft wax retains stronger domestic manufacturing footprints in European compounding facilities.
- Hard Wax:Low-viscosity thermoplastic formulations liquefy at 40–50°C and solidify into flexible films for non-strip removal. Demand concentrates in Brazilian professional salons migrating from soft wax protocols, driven by reduced epidermal lifting liability and repeat-application efficiency on sensitive zones.
- Non-Strip Wax:Premium-positioned polymer-rich variants command the highest margin pool in med-spa franchise menus. United States clinic chains specify these formulations in standardized procurement agreements to minimize allergenic exposure and protocol variability across locations.
- Soft Wax:Traditional colophony-dependent formulations face margin compression from gum rosin price volatility.
- Strip Wax:Lower-cost removal method retains presence in price-sensitive retail channels and basic training curricula.
Hard wax commands the established base. The steepest expansion runs through non-strip wax.
Form:
Bead formats reduce melt time and enable precise portion control, aligning with high-turnover professional environments. Block and can formats serve lower-frequency home users and institutional training settings where volume efficiency matters less than storage stability.
- Beads:Spherical micro-pellets achieve faster thermal equilibrium in professional warmers. Med-spa chains in the United States specify bead-only procurement to standardize technician workflow and minimize waste across franchise locations.
- Blocks:Solid rectangular formats suit bulk institutional purchasing by beauty schools and training academies requiring extended shelf stability without specialized warming equipment.
- Cans:Pre-filled metal containers target home-user retail segments with convenience positioning.
- Pellets:Intermediate sizing serves mixed professional environments with variable treatment volumes.
Bead formats anchor professional channel volume. Block formats are gaining share fastest in educational institutional procurement.
Application:
Body hair removal protocols drive polymer-blend formulation innovation, while facial applications impose stricter dermatological testing requirements that fragment supplier qualification timelines across jurisdictions.
- Body Hair Removal:Brazilian wax protocols require low-melt-point crystal formulations permitting repeated zone application. Rio de Janeiro and São Paulo salon networks are converting treatment rooms to these methods, concentrating demand for specialized polymer-modified resins.
- Facial Hair Removal:Delicate epidermal zones mandate hypoallergenic synthetic resin substitutes. REACH Annex XVII compliance deadlines are accelerating European manufacturer reformulation toward pre-certified polymer blends.
- Eyebrow Shaping:Precision application demands fine-temperature control and specialized applicator compatibility.
- Decorative Waxing:Niche segment incorporating colorants and fragrances for festival and bridal markets.
Body hair removal commands the established base. The steepest expansion runs through facial protocols.
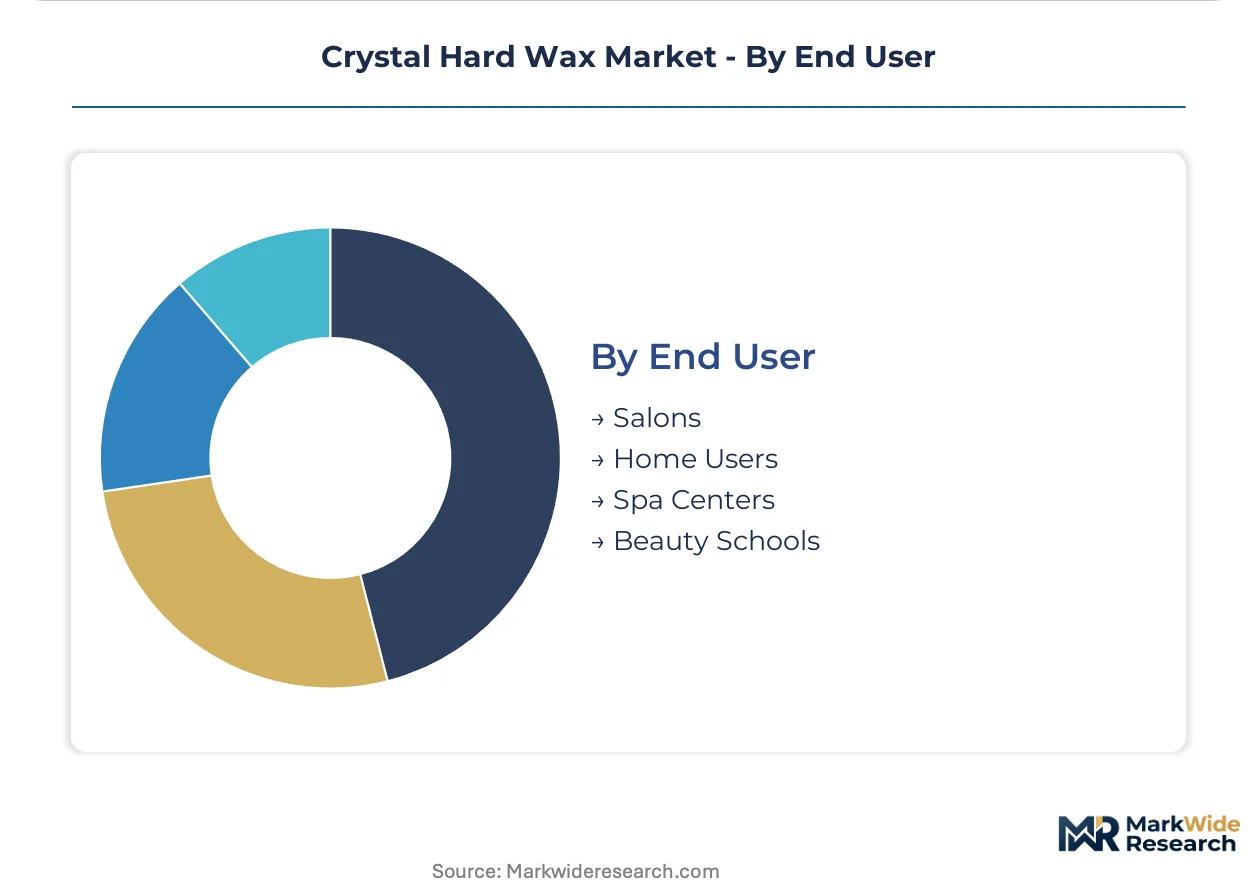
End User:
Salon and spa procurement departments are consolidating supplier relationships into volume-guaranteed frameworks, disintermediating regional distributors. Home-user segments remain fragmented through retail bead-format packaging without institutional purchasing leverage.
- Salons:Professional treatment rooms in Brazil are abandoning soft wax for hard wax formulations, triggering supply-side capacity scrambles. Franchise standardization in the United States is locking in recurring bulk procurement from approved compounders.
- Spa Centers:Med-spa chains hard-code hard wax protocols into operating manuals, replacing fragmented spot-buying with multi-year supply contracts tied to dermatological liability minimization.
- Home Users:Bead-format retail packaging is gaining traction through e-commerce channels, though sugar wax DIY kits capture price-sensitive mass retail consumers.
- Beauty Schools:Institutional training demand favors block-format bulk purchasing with extended shelf stability requirements.
Salons command the established base. Spa centers are expanding most quickly through franchise procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and German polymer blend specialists control the bulk of REACH-compliant raw material output, creating geographic chokepoints that shape procurement patterns across professional salon networks. Demand fragmentation follows regulatory jurisdiction boundaries, with formulation chemistry diverging between colophony-restricted European markets and rosin-tolerant emerging economies.
United States
Med-spa franchise chains in Florida, Texas, and California are hard-coding hard wax protocols into standardized operating manuals, locking in recurring bulk procurement from approved compounders. FDA cosmetic labeling requirements restrict allergenic colophony concentrations, pushing suppliers toward synthetic resin documentation. Miami and Los Angeles salon networks concentrate demand for low-melt-point crystal formulations serving Brazilian wax protocols.
Brazil
Rio de Janeiro and São Paulo professional salons are abandoning soft wax for hard wax formulations, triggering supply-side scrambles to secure polymer-modified resin capacity. ANVISA oversees cosmetic product registration timelines that extend import qualification periods for foreign compounders. The São Paulo metropolitan corridor anchors domestic treatment room conversion, with franchise networks standardizing non-strip methods across multiple locations.
Germany
REACH Annex XVII restrictions on skin-sensitizing substances are accelerating R&D spending on synthetic substitutes before full colophony limits take effect. ECHA compliance deadlines force reformulation of legacy hard wax lines across domestic manufacturing facilities. The Rhine-Ruhr industrial cluster hosts compounders developing pre-certified polymer blends that streamline downstream customer registration in adjacent EU markets.
India
BIS certification requirements have slowed import flows of crystal hard wax blocks entering the professional beauty channel, creating first-mover advantage for domestic compounders meeting bureau standards. Maharashtra and Gujarat industrial zones concentrate emerging manufacturing capacity targeting salon procurement departments in Mumbai and Delhi. DGFT import regulations intersect with state-level cosmetic licensing to fragment supplier qualification timelines.
Italy
Italian compounders leverage established European manufacturing bases to supply private-label formulations for high-turnover spa networks across Mediterranean export markets. EU Green Deal procurement preferences are converging with cosmetic wax chemistry to accelerate biodegradable bead innovation. The Lombardy region anchors formulation R&D, with Milan-based suppliers serving franchise standardization trends in France and Spain.
Crystal Hard Wax Market Competitive Landscape
Concentration sits with European polymer blend specialists and diversified chemical compounders that have secured REACH pre-certification for synthetic resin formulations. The vendor base separates into three strategic tiers: integrated compounders with captive raw material sourcing, contract manufacturers serving private-label spa networks, and regional distributors disintermediated by direct franchise procurement. Dominant competitive moves include backward integration into petrochemical feedstocks and geographic licensing agreements to bypass multi-jurisdiction registration barriers.
Among European manufacturing specialists, Italwax leverages its Italian base to anchor private-label supply relationships with high-turnover spa networks. Turtle Wax extends automotive-grade polymer expertise into cosmetic wax chemistry, occupying a cross-industry credibility position that distinguishes its formulation approach. Weifang Dawn Green Valley International Co., Ltd. represents the Chinese manufacturing tier, with its Weifang location situating it within Shandong Province's chemical processing corridor.
| Leading Market Players |
|---|
| Italwax |
| Waxness |
| Turtle Wax |
| Naysku |
| Superwax |
| Satin Smooth |
| Flamingo Car Care |
| Getsun |
| Weifang Dawn Green Valley International Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
REACH Annex XVII compliance deadlines gate both supply qualification and price differentiation simultaneously, as ECHA-mandated colophony restrictions force compounders to absorb reformulation costs while premium-positioning synthetic resin blends command margin premiums over legacy rosin formulations.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European and export markets, separating pre-certified polymer blends from legacy colophony-dependent formulations. Price differentiation centers on dermatological certification grade and volume scale commitments in franchise procurement agreements. Cost compression in standard-tier rosin formulations is intensifying because Brazilian pine resin harvest fluctuations squeeze traditional producers. Home-user retail segments exhibit highest price sensitivity, while United States med-spa chains demonstrate lowest sensitivity due to liability-driven specification of premium synthetic resin grades.
Supply Chain Analysis
Rhine-Ruhr industrial cluster concentration underwrites European polymer blend output, with Italian Lombardy compounders and German specialists controlling the bulk of REACH-compliant raw material production. The supply chain draws from petrochemical feedstocks, bio-based polymer alternatives, and residual gum rosin imports from Brazil. Single-source vulnerability concentrates in German and Italian pre-certified compounders, creating bottleneck risk for new market entrants. Distribution runs through direct franchise procurement contracts that disintermediate regional distributors and push volume to approved compounders with scale certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through med-spa franchise procurement consolidation in the United States and salon network standardization in Brazil, fragmenting supplier pricing leverage and rewiring distribution hierarchies toward direct compounder relationships.
For Market Incumbents: Consolidate backward integration into petrochemical feedstock sourcing to secure polymer resin supply against Brazilian gum rosin price volatility. Lock in multi-year volume guarantees with United States franchise chains before REACH compliance deadlines accelerate synthetic resin demand. Prioritize certification investment in BIS standards for Indian market entry.
For New Entrants and Emerging Players: BIS certification fast-track offers underpenetrated access to Indian professional salon channels where import flows have slowed. Target Maharashtra and Gujarat manufacturing zones for domestic compounding capacity. Pursue private-label supply relationships with Mediterranean spa networks as the most penetrable white-space segment.
For Investors and Strategic Acquirers: ECHA colophony limit implementation reshapes the acquisition landscape toward synthetic resin formulation capabilities. Long-term viability favors compounders with REACH pre-certification and captive polymer feedstock access. Watch ANVISA registration timeline acceleration in Brazil as the inflection signal for regional supply consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive resin supply insulates margins from Brazilian pine harvest volatility. |
| REACH Pre-Certification Investment | ECHA compliance streamlines downstream customer registration across EU markets. |
| Private-Label Manufacturing Partnerships | Direct spa network relationships bypass disintermediated distributor channels. |
| BIS Certification Compliance Program | Bureau standards unlock first-mover advantage in Indian professional beauty channels. |
| Biodegradable Bead R&D Initiative | PLA-based carriers align with EU Green Deal procurement preferences in Italy. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with salon procurement directors, med-spa franchise operations managers, cosmetic compounder R&D heads, and polymer resin procurement leads; and secondary validation through ECHA substance registration databases, ANVISA cosmetic product filings, BIS certification records, and customs trade data on gum rosin imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, formulation chemistry, end-user channel, and regional regulatory cluster dimensions.
Across the analysis window, the forecast framework applied segment-level growth patterning by product form, application protocol, and buyer consolidation stage. CAGRs derived from trajectory matching against analogous professional beauty chemical markets, adjusted for REACH compliance acceleration and franchise procurement standardization velocity. Key inputs included polymer resin price indices, salon treatment room conversion rates in Brazil, and med-spa chain expansion pipelines in Florida, Texas, and California.
Decision-makers should treat outputs as directional under assumptions of sustained franchise procurement consolidation and ECHA enforcement timelines; material deviation in Brazilian resin harvests or ANVISA registration delays would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal procurement preferences and biodegradable formulation economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Acetyl Isovaleryl Market