
 Fluoroethylene Carbonate (FEC) Market | 2026-2036
Fluoroethylene Carbonate (FEC) Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroethylene Carbonate (FEC) Market Foresight
GB/T 36276 certification for lithium-ion battery electrolyte materials is rotating supplier eligibility toward producers with in-house fluorination capabilities and batch-to-batch consistency. Foosung leverages captive hydrofluoric acid supply to anchor cost positions in high-purity FEC. Shenzhen Capchem Technology sustains technical dialogue with tier-one battery manufacturers through customized additive formulations. Rongcheng Qing Mu High-Tech Materials competes on integrated purification trains that reduce metallic impurities below 10 ppm.
Fluoroethylene carbonate is a fluorinated cyclic carbonate with molecular formula C3H3FO3, synthesized via fluorination of ethylene carbonate or direct reaction of ethylene carbonate with fluorinating agents, and functions primarily as a solid electrolyte interphase film-forming additive in lithium-ion cells. The electrolyte additive segment dominates volume as cell makers dose FEC at 1-5 weight percent to suppress graphite anode degradation and extend cycle life. Solid-state battery technology represents the fastest-growing technology dimension, with sulfide and oxide electrolyte developers testing FEC derivatives as interfacial wetting agents prior to full solid-state transition.
China's SAMR enforces GB standards for battery electrolyte purity that directly gate market access for domestic and imported FEC suppliers. The EU's REACH regulation and RoHS directives constrain fluorinated additive formulations entering European battery supply chains, forcing exporters to maintain dual certification portfolios. Stakeholders must monitor how solid-state battery timelines and sodium-ion commercialization reshape additive dosing requirements and qualification cycles.
Market Dynamics
China's GB/T 36276 certification tightening is compressing supplier eligibility toward producers with captive fluorination and sub-10 ppm metallic impurity controls, reshaping competitive access for electrolyte additive manufacturers serving lithium-ion battery supply chains.
Growth Catalysts
- GB Standards Escalation:China's SAMR enforcement of stricter lithium-ion battery electrolyte purity thresholds is disqualifying import-dependent suppliers and rewarding domestic producers with integrated purification infrastructure.
- Electric Vehicle Cell Densification:Battery manufacturers are scaling FEC procurement to 1-5 weight percent dosing as graphite anode degradation suppression becomes critical for extending cycle life in high-energy-density cells.
- Jiangsu-Guangdong Production Cluster Proximity:Demand concentrates in provinces where cathode and electrolyte production facilities sit adjacent to major cell makers, minimizing logistics friction and qualification timelines.
Market Restraints
- Hydrofluoric Acid Supply Concentration:Captive HF access determines cost positions in high-purity FEC synthesis, locking out non-integrated producers from margin-competitive supply to tier-one battery manufacturers.
- EU REACH and RoHS Friction:European fluorinated additive constraints force exporters to maintain dual certification portfolios, adding compliance overhead and elongating market entry timelines.
- Solid-State Battery Substitution Timeline:Sulfide and oxide electrolyte developers are testing FEC derivatives as transitional interfacial wetting agents, threatening long-term additive dosing requirements.
Strategic Opportunities
- Sodium-Ion Battery Qualification Cycles:Emerging sodium-ion commercialization is creating parallel additive formulation requirements distinct from lithium-ion chemistry, opening technical dialogue windows with early-mover cell developers.
- Solid-State Interfacial Chemistry:FEC derivative development for sulfide electrolyte wetting applications represents a technology bridge opportunity prior to full solid-state transition.
- EU Green Deal Battery Passport Requirements:Traceability mandates for fluorinated compounds in European supply chains favor suppliers with batch-level impurity documentation and carbon footprint accounting.
Industry Challenges
- Fluorination Specialist Talent Scarcity:Batch-to-batch consistency in high-purity FEC production requires rare expertise in anhydrous fluorination process control, constraining capacity expansion timelines.
- Dual Certification Capex Burden:Simultaneous compliance with China's GB standards and EU REACH necessitates redundant analytical infrastructure and separate production trains, elevating capital intensity for market access.
- Qualification Cycle Compression:Cell makers are compressing electrolyte additive validation timelines to match accelerated vehicle platform launches, straining supplier technical service bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroethylene Carbonate (FEC) Market |
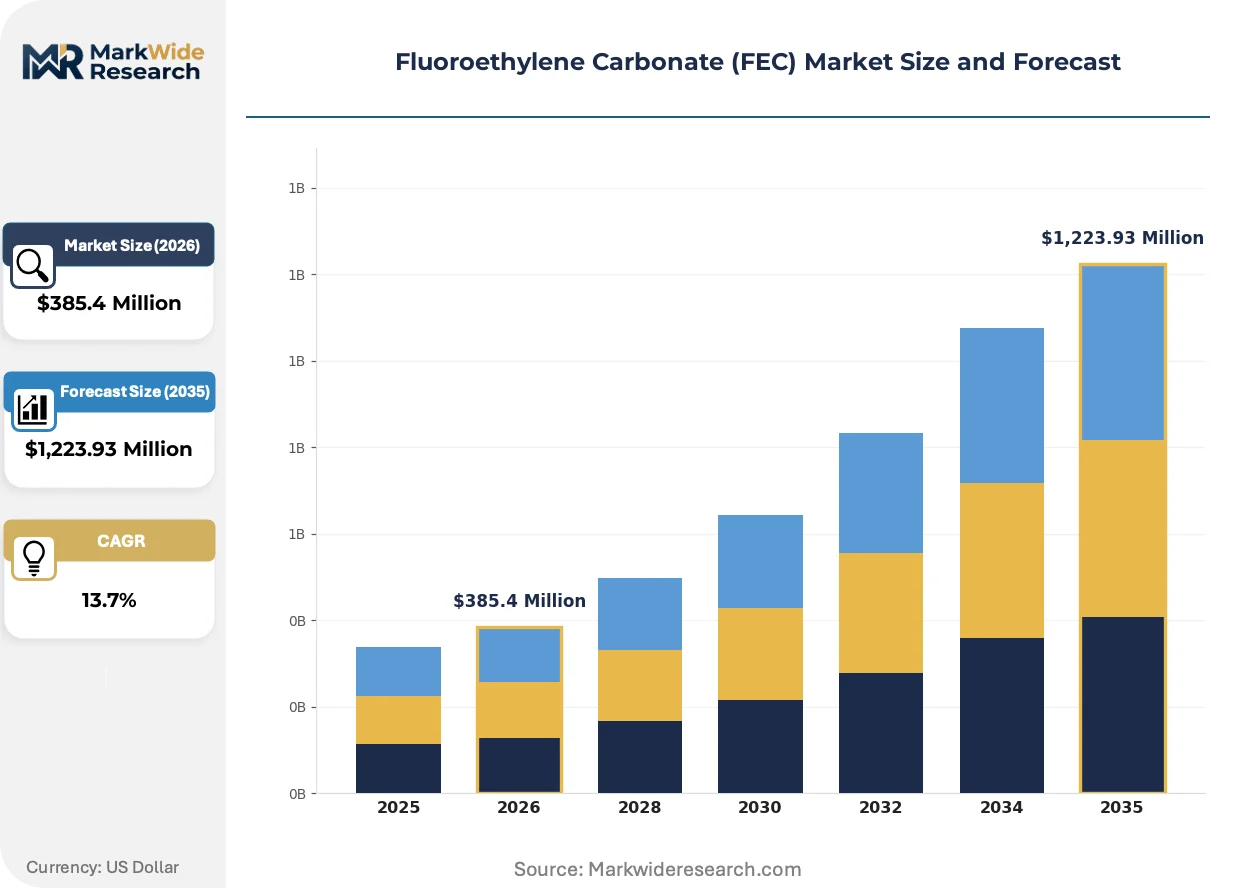
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,223.93 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Additive, Solvent, Co-Solvent, Binder, Separator Coating Technology: Lithium-Ion Batteries, Solid-State Batteries, Sodium-Ion Batteries, Lithium-Sulfur Batteries, Flow Batteries Application: Consumer Electronics, Electric Two-Wheelers, Stationary Energy Storage, Aerospace Power Systems, Marine Vessels End User: Battery Manufacturers, Energy Storage Companies, Electric Vehicle OEMs, Aerospace Component Makers, Marine Engineering Firms |
| Companies Covered | HSC Corporation, Rongcheng Qing Mu High-Tech Materials, Foosung, Shenzhen Capchem Technology, Fujian Chuangxin Science and Technology, Capchem Technology, Zhangjiagang Hankang Chemical, Guangzhou Tinci Materials Technology, Tinci Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroethylene Carbonate (FEC) Market Shifts & Advancements
Electrolyte additive chemistry is diverging along performance-optimized and cost-optimized tracks as battery manufacturers segment procurement strategies between premium cycle-life extension and standard-grade commodity supply.
Fluorinated cyclic carbonate derivatives are fragmenting the traditional FEC product architecture as cell makers demand customized formulations for specific cathode chemistries. Tier-one battery manufacturers in South Korea and Japan are qualifying proprietary additive blends at 2-3 weight percent dosing levels. This fragmentation is compressing standardized product margins while expanding technical service revenue pools for formulation partners.
REACH authorization procedures for persistent organic pollutants are constraining fluorinated compound formulations entering European battery supply chains. ECHA's evolving substance evaluation criteria are forcing additive suppliers to pre-register next-generation derivatives ahead of commercial deployment. German and French cell manufacturers are responding by dual-sourcing from REACH-compliant European distributors and certified Asian producers with EU-established only representatives.
Long-term offtake contracting is displacing spot market purchasing as cathode and electrolyte producers seek supply security for qualification-dependent additives. Cell makers in Jiangsu and Guangdong provinces are locking eighteen-to-twenty-four-month supply agreements with fixed impurity specifications. This behavioral shift is most visible among electric vehicle-dedicated cell lines where platform continuity demands batch consistency guarantees unavailable from merchant market sourcing.
Fluoroethylene Carbonate (FEC) Market Segmentation
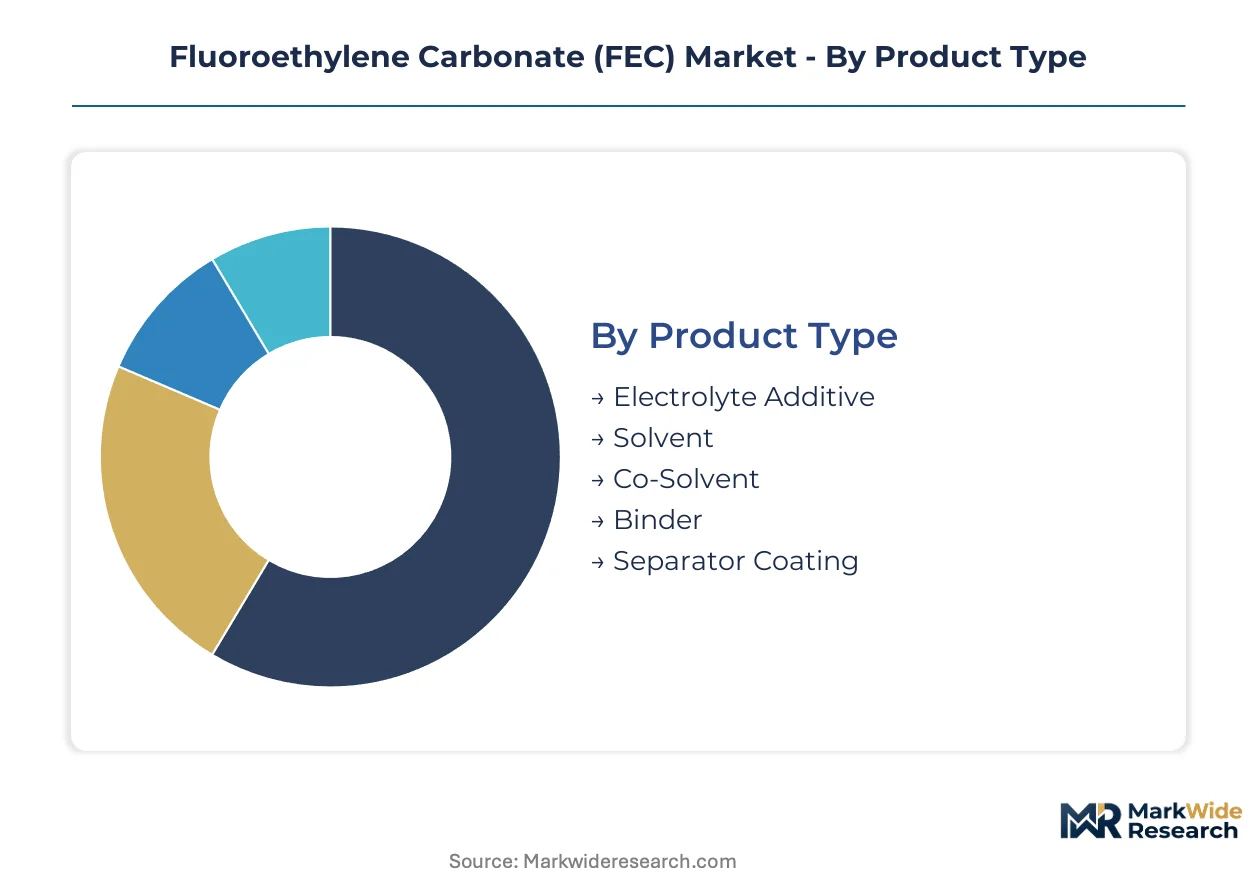
Segmentation in the Fluoroethylene Carbonate market tracks how functional roles in battery chemistry intersect with divergent qualification requirements across cell technologies. Channel dynamics vary sharply between electrolyte additive procurement and solvent-grade supply, with purity thresholds and volume scales determining supplier-customer matching.
Product Type:
Channel mix splits between high-specification additive supply bound for tier-one battery manufacturers and commodity solvent flows serving electrolyte blenders with less stringent certification demands.
- Electrolyte Additive:High-purity FEC dosed at 1-5 weight percent to form solid electrolyte interphase films on graphite anodes. Demand concentrates with lithium-ion cell makers in Jiangsu and Guangdong provinces where GB/T 36276 certification gates supplier eligibility.
- Solvent:Standard-grade FEC serving as primary electrolyte carrier with lower fluorination stringency. Procurement flows through merchant chemical distributors to mid-tier electrolyte compounders lacking captive fluorination.
- Co-Solvent:Blending component in multi-carbonate electrolyte formulations.
- Binder:Fluorinated polymer additive for electrode adhesion in high-voltage cathode systems.
- Separator Coating:Surface treatment layer for ceramic-coated polyolefin membranes.
By volume, Electrolyte Additive leads. By growth pace, Solvent is expanding most quickly as electrolyte production scales beyond tier-one cell makers.
Technology:
Cost tier stratification separates premium qualification cycles for next-generation solid-state systems from standardized supply serving incumbent lithium-ion infrastructure.
- Lithium-Ion Batteries:Dominant commercial chemistry with established FEC dosing protocols. Jiangsu and Guangdong production clusters anchor procurement concentration for cylindrical and prismatic cell formats.
- Solid-State Batteries:Sulfide and oxide electrolyte developers test FEC derivatives as interfacial wetting agents prior to full solid-state transition. South Korean and Japanese cell makers drive qualification dialogue for proprietary additive blends.
- Sodium-Ion Batteries:Emerging chemistry with distinct additive formulation requirements.
- Lithium-Sulfur Batteries:High-energy-density chemistry with polysulfide shuttle suppression needs.
- Flow Batteries:Grid-scale storage systems with limited FEC compatibility.
By volume, Lithium-Ion Batteries dominates. By margin contribution, Solid-State Batteries commands premium positioning.
Application:
Customer type fragmentation separates consumer electronics procurement with compressed qualification timelines from industrial energy storage with extended validation cycles.
- Electric Two-Wheelers:High-volume, cost-optimized cell demand concentrated in Chinese manufacturing hubs. GB standards enforcement tightens purity thresholds for domestic suppliers serving this price-sensitive segment.
- Stationary Energy Storage:Grid-scale battery deployments requiring extended cycle life guarantees. EU Green Deal battery passport mandates favor suppliers with batch-level traceability documentation.
- Consumer Electronics:Cylindrical cell demand for power tools and portable devices.
- Aerospace Power Systems:Aviation-grade certification with thermal runaway suppression priorities.
- Marine Vessels:Maritime electrification with salt corrosion resistance requirements.
By volume, Electric Two-Wheelers leads. By qualification complexity, Aerospace Power Systems sets the steepest barrier.
End User:
Supply concentration maps directly onto production geography, with battery manufacturers clustering procurement in provinces adjacent to cathode and electrolyte facilities.
- Battery Manufacturers:Tier-one cell makers in South Korea and Japan qualifying proprietary additive formulations at 2-3 weight percent dosing. Long-term offtake contracting displaces spot purchasing for qualification-dependent supply.
- Electric Vehicle OEMs:Platform continuity demands drive eighteen-to-twenty-four-month supply agreements with fixed impurity specifications. REACH and RoHS compliance requirements constrain European supply chain sourcing.
- Energy Storage Companies:Utility-scale integrators with bankability-driven supplier selection.
- Aerospace Component Makers:AS9100-certified suppliers with thermal management specifications.
- Marine Engineering Firms:Shipyard electrification projects with classification society approvals.
By procurement scale, Battery Manufacturers leads. By contract duration extension, Electric Vehicle OEMs is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforcement of stricter GB/T 36276 purity thresholds is redirecting procurement toward domestic producers with captive fluorination infrastructure. Cell makers in Jiangsu and Guangdong provinces are locking long-term supply agreements as qualification timelines compress.
China
Jiangsu and Guangdong provinces concentrate cathode and electrolyte production clusters adjacent to major cell manufacturers. GB standards tightening by SAMR is disqualifying import-dependent suppliers and rewarding producers with sub-10 ppm metallic impurity controls. Shenzhen and Zhangjiagang anchor fluorination capacity expansion serving tier-one battery supply chains.
South Korea
Seoul-based cell makers are qualifying proprietary FEC additive blends at 2-3 weight percent dosing levels for cylindrical and prismatic formats. METI-aligned technical standards influence supplier selection for export-bound production lines. Busan-Ulsan chemical complexes host electrolyte compounders sourcing high-purity fluorinated additives.
Japan
Kanto region battery manufacturers drive qualification dialogue for solid-state battery interfacial wetting applications. JIS standards for lithium-ion materials create parallel certification requirements distinct from Chinese GB frameworks. Nagoya-area chemical specialists are developing FEC derivatives for sulfide electrolyte compatibility.
Germany
Bavaria and Baden-Württemberg host automotive OEMs demanding REACH-compliant additive portfolios with batch-level traceability documentation. ECHA substance evaluation criteria are forcing pre-registration of next-generation fluorinated derivatives ahead of commercial deployment. KBA safety standards for electric vehicle batteries constrain supplier eligibility to dual-certified producers.
United States
IRA production tax credits are incentivizing domestic electrolyte material sourcing for electric vehicle supply chains. EPA chemical safety reviews intersect with state-level battery manufacturing incentives in California and Texas. Midwest cell production hubs are qualifying additive suppliers with ISO-certified impurity documentation.
Fluoroethylene Carbonate (FEC) Market Competitive Landscape
Listed leaders compete with private specialists across fluorination capability depth, with market structure consolidating around three tiers based on captive hydrofluoric acid access and purification infrastructure scale. Tier-one positions cluster with producers maintaining GB/T 36276 certification and sub-10 ppm metallic impurity controls. Strategic archetypes include integrated fluorination specialists, formulation-technical service hybrids, and merchant chemical distributors. Capacity expansion and backward integration into anhydrous HF supply dominate competitive moves.
Among China-based producers with integrated fluorination, Foosung and Shenzhen Capchem Technology exemplify the captive-supply archetype, while Rongcheng Qing Mu High-Tech Materials occupies a position emphasizing purification train specialization. These three entities anchor the supplier tier serving Jiangsu and Guangdong battery manufacturing clusters with qualification-dependent additive supply.
| Leading Market Players |
|---|
| HSC Corporation |
| Rongcheng Qing Mu High-Tech Materials |
| Foosung |
| Shenzhen Capchem Technology |
| Fujian Chuangxin Science and Technology |
| Capchem Technology |
| Zhangjiagang Hankang Chemical |
| Guangzhou Tinci Materials Technology |
| Tinci Materials Technology |
| Others |
Supply & Pricing Matrix
GB/T 36276 certification gates both supplier eligibility and price differentiation simultaneously, compressing procurement toward domestic Chinese producers with captive fluorination while forcing import-dependent competitors into margin-eroding discounting to retain access.
Pricing Analysis
Certification level creates the primary spread between premium additive-grade FEC and standard solvent supply. Three-tier pricing structure across additive-grade, technical-grade, and commodity solvent tiers reflects purity thresholds and metallic impurity controls. Cost compression in the commodity solvent tier is intensifying because merchant chemical distributors lack captive hydrofluoric acid positions. Battery manufacturers exhibit the least price sensitivity for qualification-dependent additive supply, while mid-tier electrolyte compounders drive aggressive bargaining on standard-grade volumes.
Supply Chain Analysis
Just-in-time inventory strategies dominate tier-one battery procurement, though eighteen-to-twenty-four-month offtake contracting is displacing spot purchasing for GB-certified additive supply. Production concentrates in China, South Korea, and Japan where cathode and electrolyte facilities cluster adjacent to cell manufacturing. The supply chain rests on anhydrous hydrofluoric acid, ethylene carbonate feedstock, and specialized fluorination catalysts. Single-source vulnerability in HF supply constrains capacity expansion for non-integrated producers. Distribution runs through direct technical service relationships for additive-grade supply and merchant chemical channels for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FEC market is cycling through a capacity buildout phase as solid-state battery timelines extend and lithium-ion cell densification sustains additive demand. This cyclical recovery is anchored by electric vehicle platform continuity requirements that lock in long-term qualification cycles.
For Market Incumbents: Fortify captive fluorination positions through backward integration into anhydrous HF supply and expand sub-10 ppm purification capacity in Jiangsu and Guangdong provinces. Defend against solid-state substitution threats by developing FEC derivative formulations for sulfide electrolyte wetting applications. Prioritize dual certification infrastructure for simultaneous GB/T 36276 and REACH compliance to maintain European market access. For New Entrants and Emerging Players: Differentiate on sodium-ion battery additive formulations where qualification windows remain open and incumbent positions are unsettled. Target the stationary energy storage segment where EU Green Deal battery passport requirements favor new suppliers with native traceability systems. Enter through technical service partnerships with electrolyte compounders lacking in-house fluorination expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity additive production as dual certification requirements and purification train investments elevate barrier thresholds. Five-to-ten-year viability favors integrated fluorination specialists with established tier-one battery relationships over merchant chemical distributors facing margin compression. Watch solid-state battery pilot production announcements as the critical inflection signal for long-term additive demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anhydrous HF | Captive acid supply anchors cost positions against merchant market volatility. |
| Dual Certification Infrastructure Buildout | Simultaneous GB/T 36276 and REACH compliance unlocks tier-one battery procurement. |
| Solid-State Derivative Development | FEC wetting agents for sulfide electrolytes bridge technology transition timelines. |
| Long-Term Offtake Contracting | Eighteen-to-twenty-four-month agreements secure batch consistency guarantees with EV-dedicated cell lines. |
| Sodium-Ion Formulation Qualification | Parallel additive requirements for emerging chemistry open early-mover positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing electrolyte procurement managers at tier-one battery manufacturers, fluorination plant directors at specialty chemical producers, technical R&D leads at additive suppliers, and distribution channel partners serving mid-tier electrolyte compounders. Secondary validation drew from SAMR GB standard filings, ECHA REACH pre-registration databases, customs trade data for fluorinated carbonate flows, and SEC disclosures from listed chemical producers. Bottom-up volume modeling triangulated against top-down demand projections from electric vehicle and energy storage deployment trajectories.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product grade tier, battery chemistry type, end-use application, and regional production hub. CAGRs were derived from fitted growth curves anchored to qualification cycle timelines and capacity expansion announcements. Industry-specific inputs included GB/T 36276 certification adoption rates, solid-state battery pilot production milestones, and sodium-ion commercialization trajectories.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cell densification and extended solid-state transition timelines would require recalibration. Forecasts reflect assumptions regarding SAMR enforcement continuity, REACH authorization stability, and hydrofluoric acid supply availability. Revision becomes warranted when solid-state battery commercialization accelerates beyond current pilot phases or when sodium-ion chemistry captures material share in electric vehicle applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
GLDA Market