
 Organic Spice Market | 2026-2036
Organic Spice Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Spice Market Analysis
Blockchain-enabled farm-to-retail traceability is rewriting procurement protocols across the organic spice value chain. McCormick & Company leverages its vertically integrated sourcing networks to secure premium organic volumes from certified farms in Madagascar and Indonesia. Frontier Co-op sustains cooperative partnerships with grower collectives, anchoring its supply base in transparent, fair-trade relationships. Simply Organic dominates North American retail shelf space through exclusive Whole Foods distribution agreements and rigorous USDA Organic certification standards.
Organic spices comprise dried plant materials—seeds, fruits, roots, bark, or flowers—cultivated without synthetic pesticides, genetically modified organisms, or irradiation, typically containing volatile oil concentrations between 0.5% and 5.0% by weight that deliver flavor, color, or preservative function to food systems. Ground spices occupy the largest volume share due to processing efficiency and extended shelf stability, though organic extracts command superior margins from pharmaceutical and nutraceutical buyers seeking standardized curcumin and piperine concentrations. The food service distribution channel exhibits the fastest structural expansion as restaurant chains reformulate menus around clean-label positioning and verifiable organic provenance.
The USDA National Organic Program and EU Organic Regulation enforce strict certification, traceability, and residue-limit standards that determine market access for exporters across India, Sri Lanka, and Guatemala. India's Agricultural and Processed Food Products Export Development Authority and the Spices Board operate mandatory pre-shipment inspection regimes that filter non-compliant consignments before they reach European or North American buyers. Stakeholders must monitor evolving pesticide maximum residue limits in destination markets and invest in integrated pest management training for smallholder suppliers to preserve contract eligibility.
Market Dynamics
Blockchain-enabled traceability systems are compressing certification timelines and rewiring procurement relationships across the organic spice value chain, forcing suppliers to choose between compliance investment and contract exclusion.
Growth Catalysts
- EU Organic Regulation traceability mandates:Strict farm-to-retail documentation requirements are filtering non-compliant suppliers and consolidating demand around certified cooperatives in Kerala and Karnataka.
- Clean-label restaurant reformulation:Food service chains are replacing conventional spice inventories with certified organic alternatives to meet consumer transparency expectations.
- Volatile oil standardization:Pharmaceutical buyers are driving demand for organic extracts with guaranteed curcumin and piperine concentrations, pulling premium pricing through the value chain.
Market Restraints
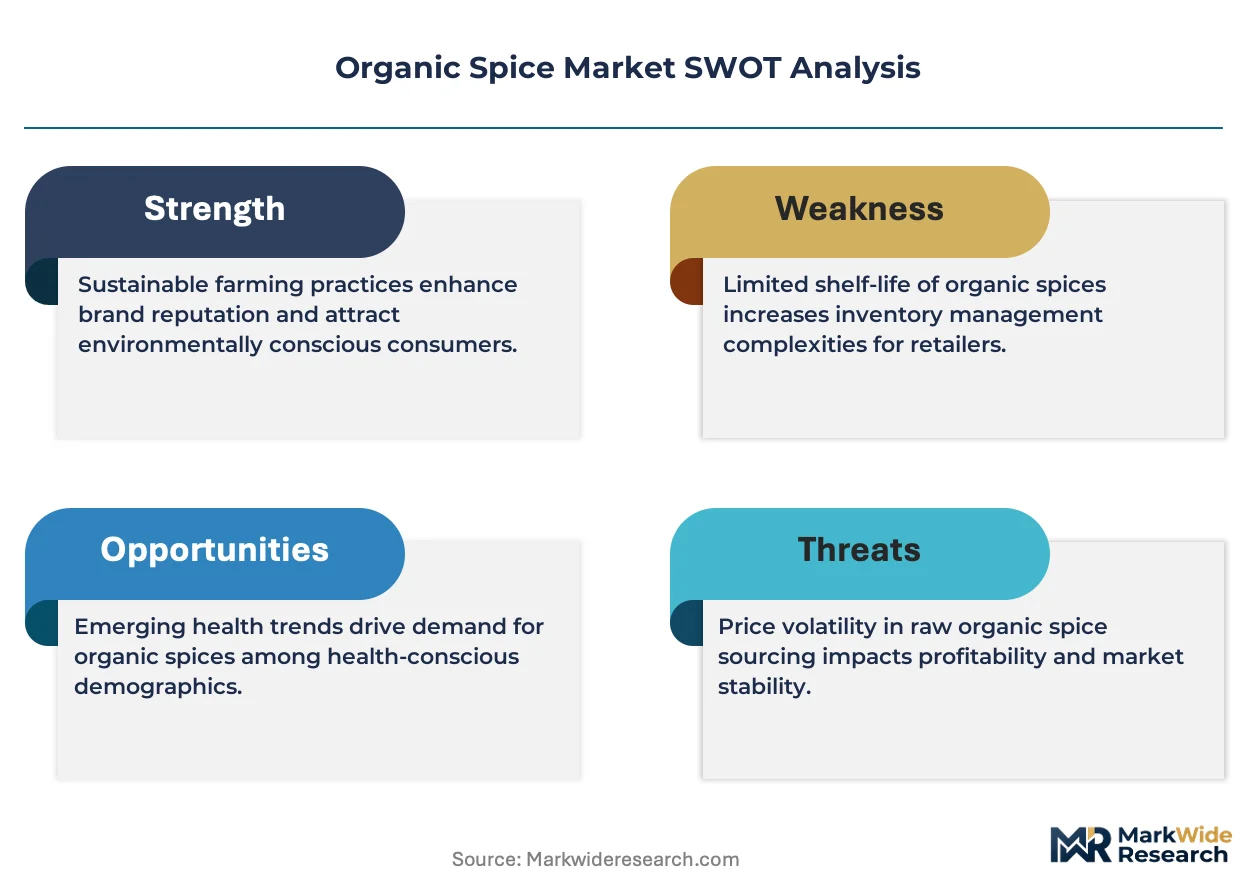
- Smallholder supply concentration:Cardamom and black pepper production clusters in India's Western Ghats create geographic vulnerability to monsoon disruption and quality inconsistency.
- Multi-jurisdiction residue limits:Divergent maximum residue limits between USDA National Organic Program and EU Organic Regulation force parallel testing regimes and inventory segmentation.
- Synthetic pesticide cost asymmetry:Conventional spice farming maintains input cost advantages that compress organic price premiums during commodity downturns.
Strategic Opportunities
- Underpenetrated German specialty manufacturing:Food processors in Bavaria and Baden-Württemberg are expanding organic turmeric and cumin procurement faster than local supply can match.
- Blockchain-AI convergence:Predictive quality algorithms layered on distributed ledgers are enabling real-time cargo release decisions and reducing port detention times.
- Direct-to-chef distribution platforms:Digital procurement channels are disintermediating traditional spice importers for high-volume restaurant accounts seeking provenance verification.
Industry Challenges
- Integrated pest management skill scarcity:Smallholder cooperatives lack trained agronomists to implement biological control methods that satisfy residue-limit protocols.
- Dual certification timeline compression:Simultaneous USDA and EU organic audits require 18-24 month preparation cycles that strain working capital for exporter SMEs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Spice Market |
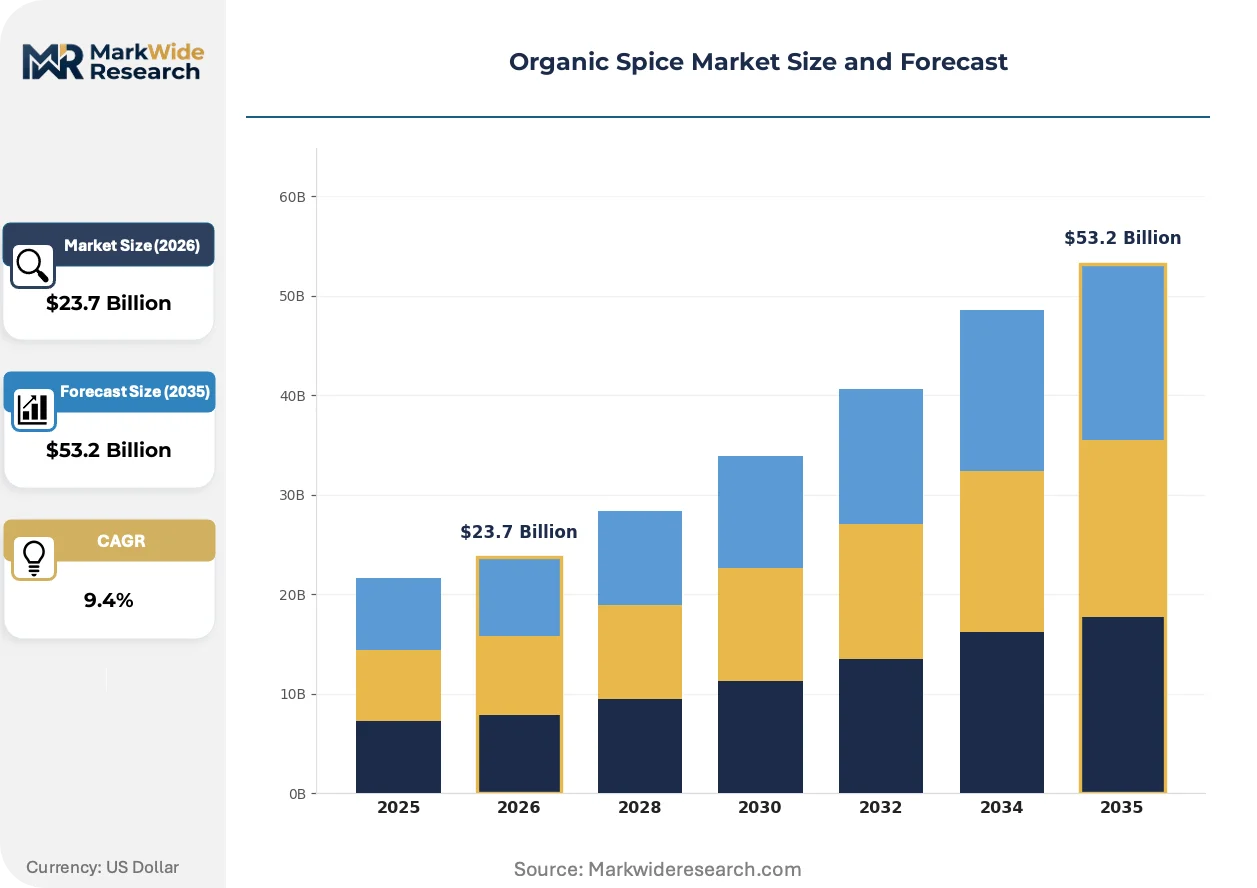
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Spices, Ground Spices, Spice Blends, Organic Extracts Packaging Type: Bottles, Pouches, Jars, Bulk Packages Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | McCormick & Company, Organic Spices Inc., Frontier Co-op, The Spice Hunter, Simply Organic, Olam Group, Starwest Botanicals, Spicely Organics, Rapid Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Spice Market Emerging Trajectories
Distributed ledger architectures and predictive analytics are converging to collapse verification cycles, while regulatory divergence between major import markets is forcing modular compliance investments.
Blockchain-based farm-to-retail traceability is digitizing custody documentation across the organic spice value chain. Indian exporter consortia are deploying shared ledger infrastructure to pre-clear shipments before vessel loading. The technology is digitizing inspection workflows that previously required 14-21 days of document reconciliation.
EU Organic Regulation residue-limit harmonization is tightening market access conditions for Indian and Sri Lankan exporters. Pre-shipment inspection regimes operated by India's Spices Board now filter consignments against both EU and USDA standards simultaneously. Ground spice shipments to Rotterdam and Hamburg face enhanced chromatographic screening that delays clearance for non-compliant lots.
Specialty food manufacturers are consolidating supplier relationships around vertically integrated processors with captive organic farm networks. German and Dutch buyers are signing multi-year offtake agreements that bypass traditional auction markets. Kerala-based cooperatives are responding by pooling harvests to meet minimum volume thresholds for direct export contracts.
Organic Spice Market Segmentation
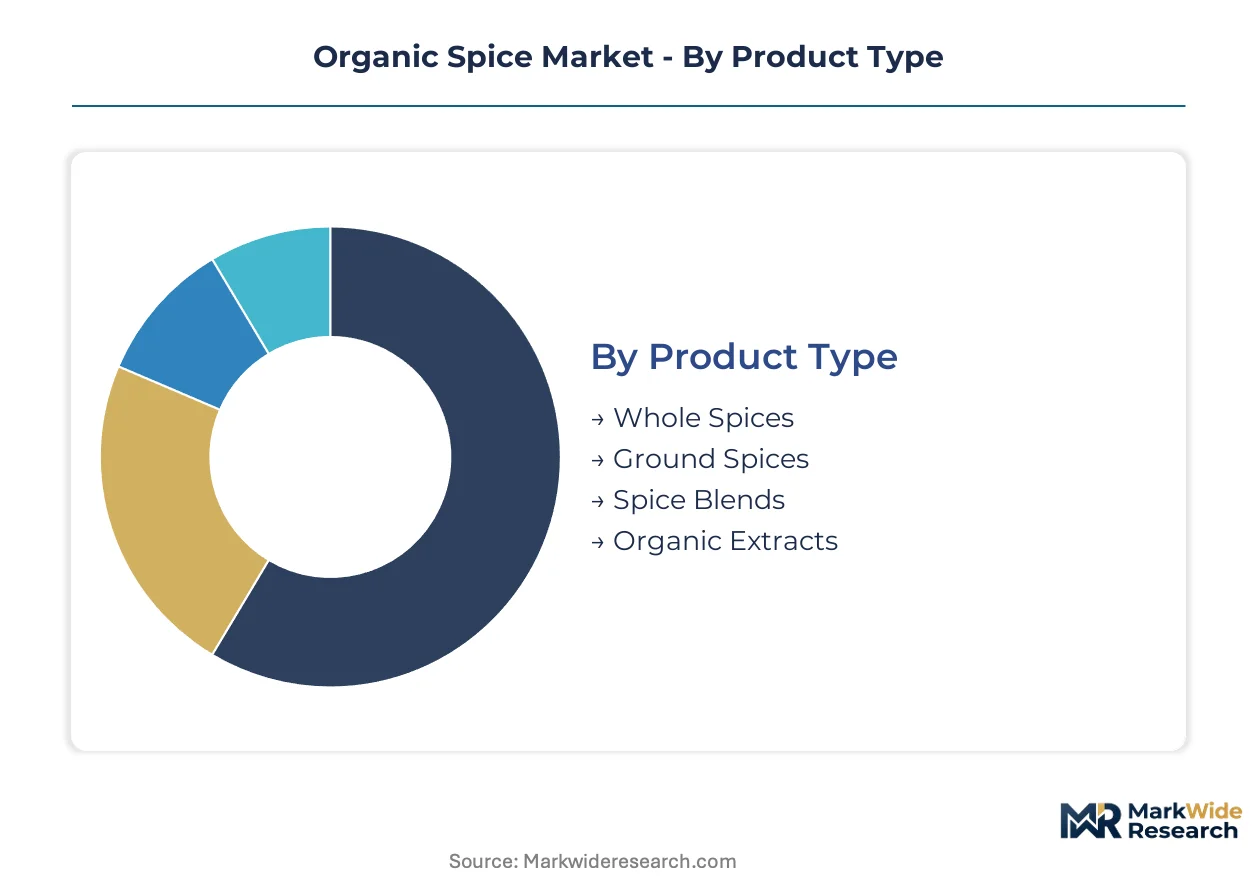
Segmentation in organic spices determines compliance burden, margin structure, and procurement channel selection. Product form dictates processing investment and residue testing protocols, while distribution channel shapes traceability documentation requirements.
Product Type:
After-sales service intensity varies sharply across product forms, with extracts demanding technical support for standardization and whole spices requiring minimal post-sale intervention.
- Ground Spices:Finely milled dried plant materials with particle sizes typically between 250-600 microns, processed to maximize surface area for flavor release. Demand concentrates in North American retail channels where convenience-oriented households prioritize ready-to-use formats, though residue testing costs per unit weight run higher due to expanded surface exposure. Ground turmeric and cumin dominate procurement volumes from German and Dutch specialty manufacturers seeking processing efficiency.
- Organic Extracts:Concentrated volatile oil or oleoresin preparations standardized to specified curcumin, piperine, or eugenol concentrations, typically 5-95% purity grades. Pharmaceutical and nutraceutical buyers in the United States drive demand for certified organic extracts with guaranteed bioactive markers, pulling premium pricing through contract manufacturing channels. These extracts require solvent-free processing certification and chromatographic batch verification.
- Whole Spices:Intact seeds, fruits, roots, or bark retaining original cellular structure and volatile oil encapsulation; shelf stability exceeds ground forms by 18-24 months. Restaurant chains and ethnic food processors favor whole cardamom and black pepper for on-site grinding and aroma control.
- Spice Blends:Pre-formulated combinations of multiple organic spices with salt, herbs, or anti-caking agents, requiring dual certification for all constituent ingredients. Retail penetration concentrates in premium supermarket chains with dedicated ethnic or wellness aisles.
Ground spices hold the largest share; momentum sits with organic extracts.
Packaging Type:
Packaging cost tiers align with customer scale and certification visibility requirements, from single-unit retail to industrial bulk.
- Bottles:Glass or PET containers with tamper-evident closures and full-label USDA Organic or EU Organic certification display, targeting premium retail shelves. North American natural product stores and conventional supermarket premium tiers drive demand for transparent bottle formats that enable visual quality assessment.
- Pouches:Flexible laminated films with high oxygen barrier properties and resealable features, balancing material cost efficiency with extended shelf life. E-commerce direct-to-consumer channels favor lightweight pouches for shipping cost optimization.
- Jars:Wide-mouth glass or plastic containers with screw-top lids, dominant in European retail where refill and reuse patterns reduce packaging waste premiums. German and Dutch consumers show strong preference for jar formats supporting pantry organization.
- Bulk Packages:Multi-kilogram woven polypropylene or paper sacks with inner liner protection, serving food manufacturers and food service distributors with high-throughput grinding or blending operations. Minimum order quantities typically start at 500 kilograms for direct import contracts.
Bulk packages generate the highest volume throughput; pouches are climbing the fastest.
Distribution Channel:
Channel selection determines traceability documentation depth and buyer consolidation patterns.
- Food Service:Direct procurement relationships between restaurant chains, contract caterers, and certified organic importers, with blockchain-verified provenance documentation. Clean-label menu reformulation by US and European restaurant groups is accelerating certified organic spice adoption in commercial kitchens.
- Supermarkets:Conventional and natural product grocery chains with dedicated organic sections, requiring slotting fees and promotional support for shelf placement. Whole Foods Market and comparable banners maintain exclusive distribution relationships with established organic spice brands.
- Online Retail:E-commerce platforms and direct-to-consumer websites enabling subscription models and bulk purchasing for household and small restaurant accounts. Digital channels reduce intermediary margins but intensify price transparency.
- Specialty Stores:Independent natural food cooperatives, ethnic grocers, and gourmet retailers with curated organic selections and staff expertise. These outlets command loyalty through community trust and sourcing story transparency.
Supermarkets retain the dominant channel position; food service shows the steepest expansion trajectory.
End User:
End-user categories reflect scale economies in procurement and formulation complexity.
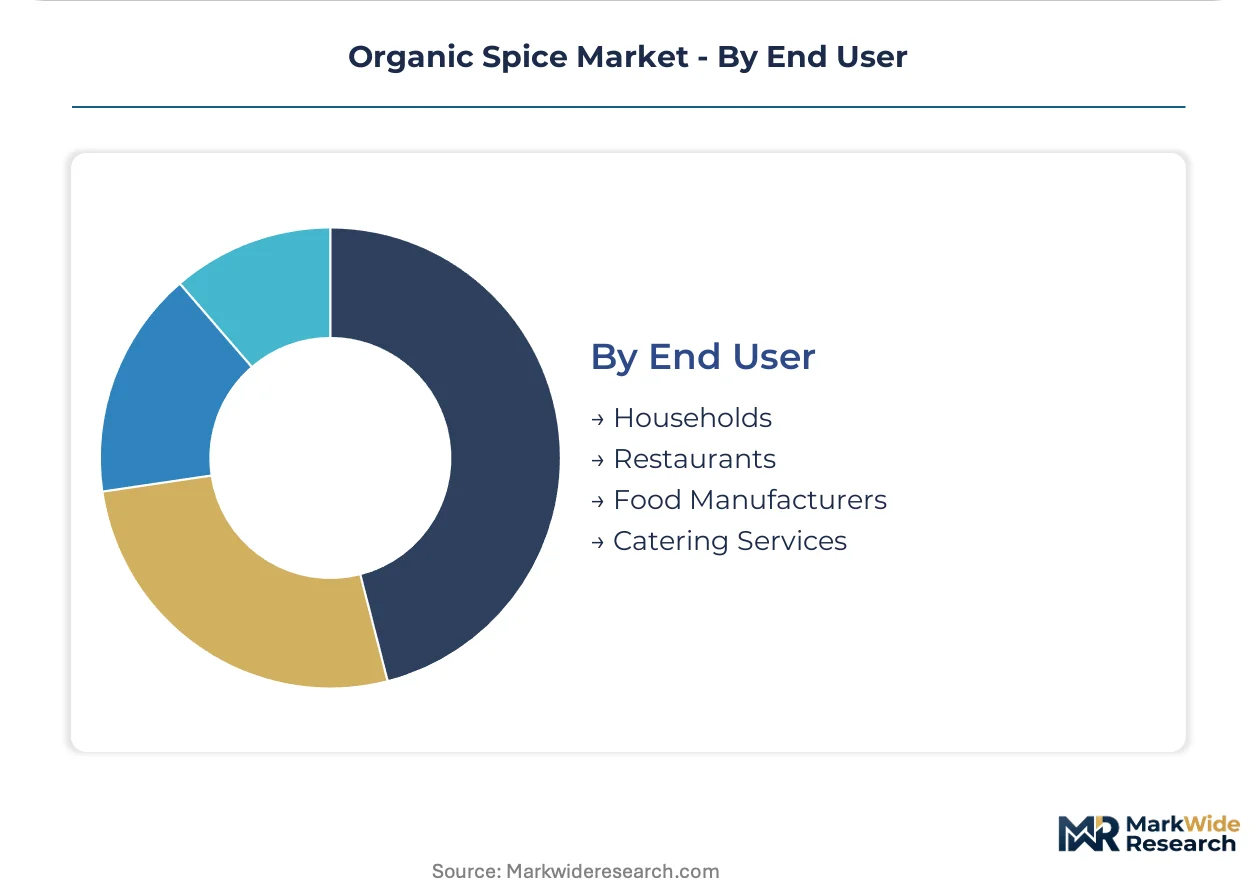
- Food Manufacturers:Industrial-scale processors of sauces, seasonings, ready meals, and baked goods requiring consistent organic certification across ingredient batches. German and Dutch specialty food manufacturers are expanding multi-year offtake agreements to secure turmeric and cumin volumes.
- Restaurants:Independent and chain food service operations reformulating menus around verifiable organic provenance for consumer transparency marketing. Direct-to-chef distribution platforms are disintermediating traditional importers for high-volume accounts.
- Households:Individual consumers purchasing through retail or e-commerce channels, with demand concentrated in urban centers with above-median disposable income and wellness-oriented consumption patterns.
- Catering Services:Institutional and event-focused food service operations with standardized menu requirements and cost-sensitive procurement, increasingly adopting organic spices for client sustainability reporting.
Food manufacturers absorb the largest volume share; restaurants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows define regional participation in organic spice trade, with India, Indonesia, and Madagascar anchoring supply while Germany, the Netherlands, and the United States absorb premium volumes. Trade balances shift as destination markets tighten residue protocols and source markets consolidate cooperative production.
India
Kerala's cardamom cooperatives and Karnataka's black pepper collectives supply the majority of global organic certified volumes. The Spices Board operates mandatory pre-shipment inspection regimes that filter consignments against EU and USDA standards before vessel loading. Kochi and Bangalore host exporter consortiums deploying shared blockchain infrastructure to compress documentation timelines.
Germany
Specialty food manufacturers in Bavaria and Baden-Württemberg are expanding procurement of organic turmeric and cumin faster than regional supply can match. The EU Organic Regulation enforces strict farm-to-retail traceability mandates that reshape supplier compliance requirements. Hamburg serves as the primary entry point for ground spice shipments facing enhanced chromatographic screening at Rotterdam-adjacent ports.
United States
Pharmaceutical and nutraceutical buyers drive demand for organic extracts with standardized curcumin and piperine concentrations. The USDA National Organic Program determines market access through certification, traceability, and residue-limit standards. Chicago and New Jersey distribution corridors channel volumes toward food service chains reformulating menus around clean-label positioning.
Indonesia
Nutmeg and clove production clusters in the Maluku Islands and North Sulawesi supply organic certified volumes to European and North American buyers. The country's national agricultural regulator coordinates with EU border inspection posts to align pre-export testing protocols. Makassar and Ambon anchor processing and export logistics for vertically integrated sourcing networks.
Madagascar
Vanilla and black pepper smallholder cooperatives dominate organic certified production for premium export segments. EU Organic Regulation residue-limit harmonization tightens market access conditions, forcing investment in integrated pest management training. Antananarivo-based exporter groups pool harvests to meet minimum volume thresholds for direct contracts with German and Dutch buyers.
Organic Spice Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated processors with captive organic farm networks and cooperative-backed smallholder aggregators. Three strategic archetypes dominate: multinational flavor houses with backward integration into certified origin farms, cooperative-owned brands leveraging fair-trade positioning, and specialty importers focused on extract standardization for pharmaceutical channels. Competitive moves center on multi-year offtake agreements that bypass auction markets and blockchain-traceability investments that pre-clear shipments before loading.
Among North American branded players, McCormick & Company and Simply Organic occupy positions within the retail premium tier, while Frontier Co-op exemplifies the cooperative-owned archetype with grower collective partnerships. These named entities anchor industry commentary on sourcing network configuration and certification depth without specifying individual strategic actions or financial performance.
| Leading Market Players |
|---|
| McCormick & Company |
| Organic Spices Inc. |
| Frontier Co-op |
| The Spice Hunter |
| Simply Organic |
| Olam Group |
| Starwest Botanicals |
| Spicely Organics |
| Rapid Organic |
| Others |
Supply Flow & Price Mechanics
Kerala's cardamom cooperatives and Karnataka's black pepper collectives anchor upstream supply concentration, feeding margin pools downstream to German specialty manufacturers and North American pharmaceutical buyers who capture value through certified organic extraction and standardized volatile oil concentrates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers. Price differentiation hinges on USDA Organic versus EU Organic certification grade and volume scale commitments exceeding 500-kilogram minimums. Cost compression in ground spice segments is intensifying because synthetic pesticide cost asymmetry in conventional farming compresses organic premiums during commodity downturns. Food service distributors exhibit highest price sensitivity, while pharmaceutical extract buyers demonstrate lowest sensitivity due to guaranteed curcumin and piperine concentration requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Dutch and German importers strain working capital for Kerala-based exporter SMEs navigating 18-24 month dual certification timelines. Geographic supply concentration rests on India, Indonesia, and Madagascar, with raw material dependencies on cardamom fruits, turmeric rhizomes, and vanilla orchid pods. Single-source vulnerability from Western Ghats monsoon disruption threatens cardamom and black pepper volumes. Distribution runs through vertically integrated processors with captive organic farm networks and cooperative-backed smallholder aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic flavor substitutes and lab-grown bioactive compounds present substitution threats that organic spice incumbents must navigate through certification depth and provenance verification.
For Market Incumbents: Harden blockchain-traceability infrastructure to pre-clear shipments against EU Organic Regulation residue limits before vessel loading. Deepen backward integration into certified origin farms in Madagascar and Indonesia to secure captive supply of vanilla and black pepper volumes. Defensive consolidation around vertically integrated processing assets mitigates threat from cooperative-backed new entrants. For New Entrants and Emerging Players: Mid-market food service distributors in German Bavaria and Baden-Württemberg represent the most penetrable entry point, where local organic turmeric and cumin supply lags demand expansion. Direct-to-chef digital procurement platforms disintermediate traditional importers for high-volume restaurant accounts seeking provenance verification. Go-to-market execution should anchor on blockchain-verified documentation that compresses port clearance timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty importers focused on extract standardization for pharmaceutical channels. Long-term viability across the projection horizon favors processors with modular compliance investments spanning USDA National Organic Program and EU Organic Regulation standards. Watch for EU residue-limit harmonization tightening as inflection signal triggering consolidation among non-compliant exporter SMEs.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Shared ledger infrastructure at Kochi and Bangalore compresses documentation timelines from 21 days to pre-clearance status. |
| Dual Certification Investment | Simultaneous USDA and EU organic audits preserve contract eligibility across North American and European destination markets. |
| Cooperative Harvest Pooling | Kerala-based collectives aggregate smallholder volumes to meet minimum thresholds for direct export contracts with Dutch buyers. |
| Integrated Pest Management Training | Biological control method implementation satisfies residue-limit protocols and filters non-compliant consignments before Rotterdam screening. |
| Extract Standardization Capacity | Solvent-free processing certification and chromatographic batch verification pull premium pricing from pharmaceutical buyers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Spices Board export databases, EU border inspection post clearance records, and USDA National Organic Program certification registries. Primary interviews engaged exporter consortium managers in Kochi, cooperative agronomists in Karnataka, procurement leads at German specialty manufacturers, and pharmaceutical buyer technical directors. Secondary validation drew from customs trade data, APEDA shipment records, and pre-shipment inspection regime documentation. Bottom-up volume aggregation across product forms and top-down trade flow triangulation anchored market sizing.
Forecast inputs span product type segmentation by ground spices, organic extracts, whole spices, and spice blends; distribution channel dynamics across food service, supermarkets, online retail, and specialty stores; and end-user categories from food manufacturers to restaurants. Modeled CAGRs derive from trade flow trajectory analysis and certification expansion patterns across the analysis window. Industry-specific inputs include volatile oil concentration standardization demand and clean-label restaurant reformulation velocity.
Practitioners should monitor EU Organic Regulation residue-limit tightening, Western Ghats monsoon variability, and synthetic flavor substitute cost curves for early signals of forecast deviation. Forecasts reflect assumptions around cooperative certification completion rates and blockchain infrastructure deployment timelines. Macroeconomic commodity downturns, regulatory divergence between USDA and EU standards, or breakthroughs in lab-grown bioactive production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Spices Market