
 Europe Nuts and Cereal Snacks Bar Market | 2026-2036
Europe Nuts and Cereal Snacks Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuts and Cereal Snacks Bar Market Foresight
A capital-intensity divergence between in-house extrusion capability and outsourced co-manufacturing is reorganizing competitive tiers in the Europe nuts and cereal snacks bar landscape. Mondelēz International leverages its integrated European bakery network to control ingredient sourcing for premium nut bars. Lotus Bakeries anchors its position through specialized Belgian production focused on clean-label granola formats.
Europe nuts and cereal snacks bars comprise compressed or baked matrices of oats, nuts, syrups, and binders, typically containing 150–300 kcal per serving with protein content ranging from 3 g to 20 g depending on formulation intent. These products serve as meal replacements, sports nutrition aids, and impulse retail purchases across supermarkets, convenience stores, and specialty health channels. Nut bars command margin pools in premium positioning where whole-almond and cashew-dominant recipes attract clean-label shoppers. Granola bars sustain volume leadership through breakfast substitution habits in northern European households. Protein bars differentiate through isolate-fortified formulations targeting gym and athletic segments where EFSA-approved claims provide retail access.
EFSA nutrition and health claims regulation, EU Packaging and Packaging Waste Directive, and national sugar reduction frameworks in France and the UK are reshaping permissible marketing language and forcing reformulation toward reduced glycemic load. EFSA's stringent substantiation requirements for protein and satiety claims limit which products qualify for front-of-pack positioning. Stakeholders must monitor evolving EU harmonized standards for novel ingredients like insect protein and mycelium-derived fibers that could alter formulation pipelines.
Market Dynamics
EFSA's tightening substantiation requirements for protein and satiety claims are forcing reformulation pipelines across European manufacturing networks, compressing permissible marketing language while elevating R&D spend for compliant label positioning.
Growth Catalysts
- Clean-label demand:German and UK health-conscious millennials are pulling protein-enriched formats through convenience retail channels, expanding premium nut bar shelf space.
- EU Green Deal alignment:Packaging waste reduction mandates under the EU Packaging and Packaging Waste Directive are accelerating recyclable film investments.
- Sports nutrition expansion:Gym and athletic segments across France are absorbing isolate-fortified formulations, validating EFSA-approved functional positioning.
Market Restraints
- Almond and cashew price volatility:Input cost swings for whole-nut recipes compress margin pools in premium positioning tiers.
- EFSA claim substantiation backlog:Regulatory friction delays front-of-pack approval timelines, freezing marketing rollouts for novel protein sources.
- Breakfast substitution saturation:Northern European granola bar penetration limits volume expansion in habitual morning consumption occasions.
Strategic Opportunities
- Insect protein regulatory pathway:Evolving EU harmonized standards for novel ingredients open formulation pipelines for sustainable protein alternatives.
- Mycelium-derived fiber integration:Technology convergence between fungal biomass processing and clean-label binding systems creates texture innovation white space.
- Specialty health channel expansion:Pharmacy and dietetic retail in the Netherlands and Belgium remain underpenetrated versus supermarket dominance.
Industry Challenges
- Extrusion technician scarcity:In-house production capability requires specialized operational expertise that co-manufacturing networks currently absorb.
- Reformulation capex cycles:Sugar reduction frameworks in France and the UK mandate equipment retooling for reduced glycemic load matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuts and Cereal Snacks Bar Market |
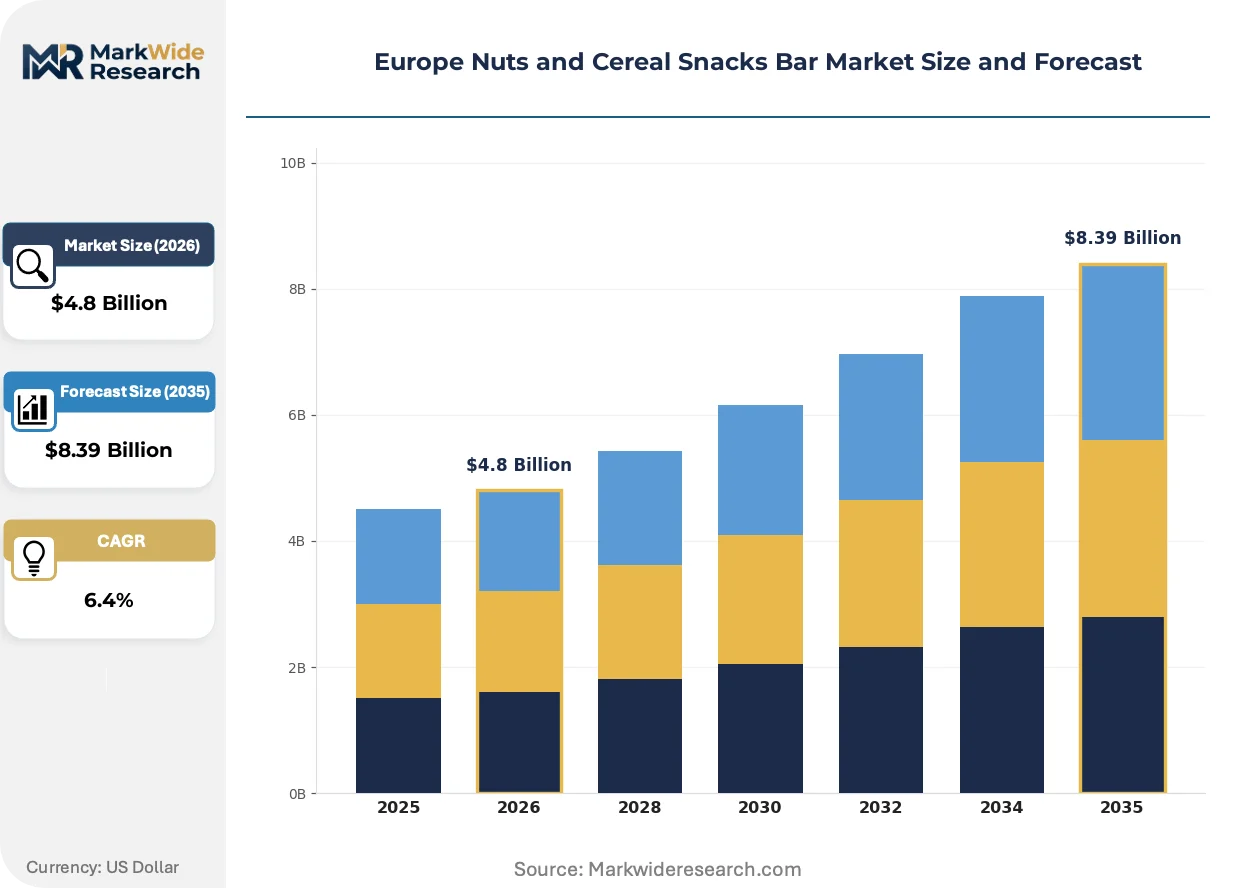
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Bars, Granola Bars, Protein Bars, Energy Bars Ingredient Type: Nuts, Cereals, Fruits, Seeds Flavor Profile: Chocolate, Vanilla, Fruit Medley, Nutty Packaging Type: Box, Pouch, Wrapper, Bulk |
| Companies Covered | Mondelēz International, Inc., Lotus Bakeries, General Mills, Inc., The Simply Good Foods Company, PepsiCo, Inc., Nestlé S.A., Hero Group, Kellogg Company, Mars, Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuts and Cereal Snacks Bar Market Shifts & Advancements
Formulation science and channel architecture are undergoing parallel transformation as manufacturers reconcile clean-label imperatives with functional performance claims and shifting retail access patterns.
Cold-pressed binding technology is supplanting traditional heat-extruded syrup matrices in premium nut bar production. Belgian and Dutch specialty manufacturers are adopting enzymatic binding at pilot scale. This shift is compressing thermal degradation of heat-sensitive micronutrients while extending shelf-stable texture claims.
EFSA nutrition and health claims regulation is tightening evidentiary thresholds for protein content declarations. Manufacturers must now commission human intervention studies for satiety positioning. Sports nutrition SKUs face the steepest compliance burden, with several German brands withdrawing non-compliant front-of-pack language.
Direct-to-gym distribution models are fragmenting traditional wholesale reliance. Athletic clubs in the UK and Germany are negotiating exclusive supply arrangements, bypassing supermarket slotting fee structures. This channel pivot concentrates volume in urban fitness clusters while eroding impulse purchase visibility in convenience retail.
Europe Nuts and Cereal Snacks Bar Market Segmentation
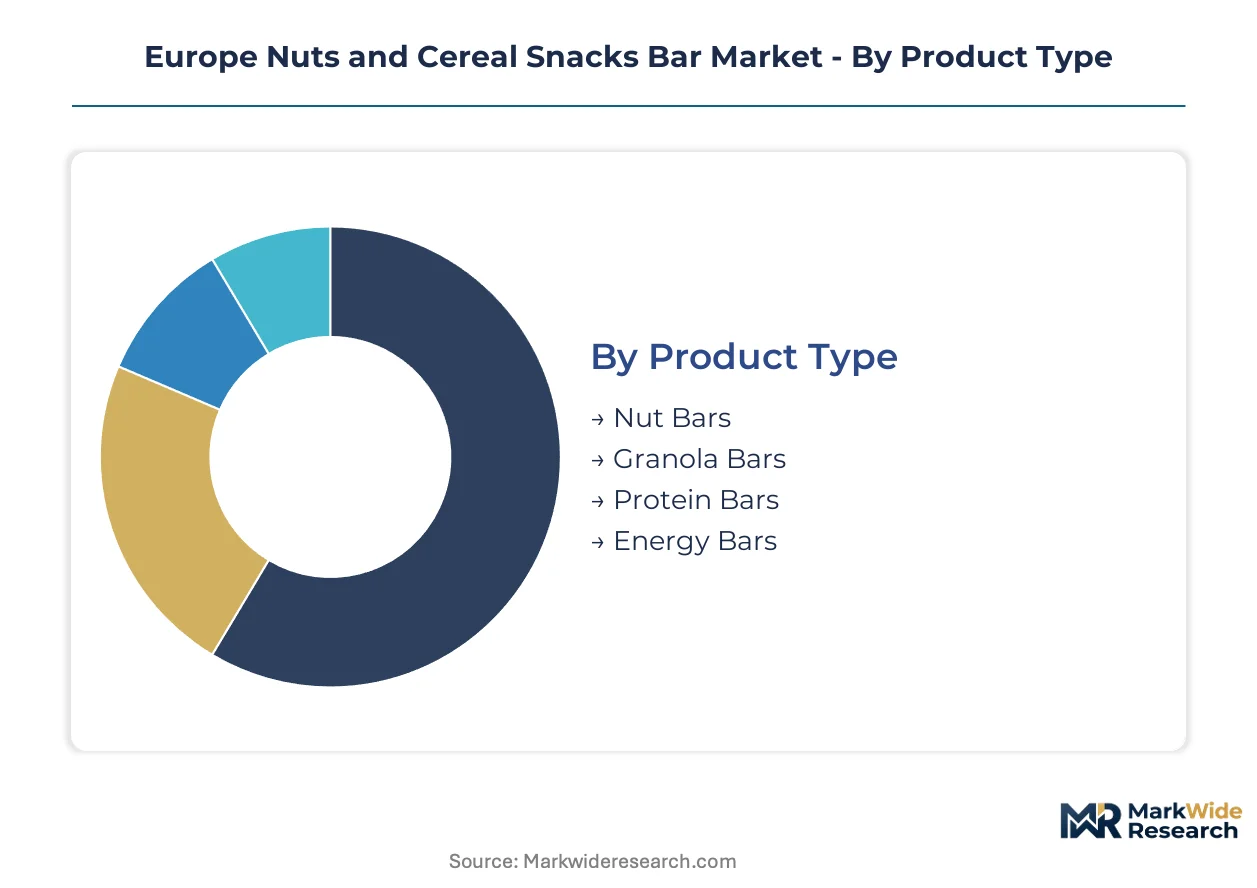
Product differentiation in Europe's nuts and cereal snacks bar market hinges on formulation architecture, ingredient sourcing, and packaging format. Each segmentation dimension carries distinct margin profiles and regulatory exposure under EFSA claims frameworks.
Product Type:
Substitution pressure from fresh food alternatives and meal-kit services intensifies across all four product categories, with breakfast-oriented formats facing the strongest displacement risk from yogurt pots and overnight oat subscriptions.
- Nut Bars:Compressed matrices of whole almonds, cashews, or mixed nuts bound with minimal syrup. German and UK health-conscious millennials drive retail demand through convenience channels for premium whole-nut positioning.
- Granola Bars:Baked oat clusters with honey or agave binding, typically 150–200 kcal per serving. Northern European breakfast substitution habits sustain volume leadership despite saturation in habitual morning consumption occasions.
- Protein Bars:Isolate-fortified formulations delivering 10–20 g protein per unit. EFSA-approved claims provide retail access in French gym and athletic segments.
- Energy Bars:Carbohydrate-dense formats targeting endurance sports with rapid glycemic delivery.
Granola bars retain volume leadership; protein bars hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity grain inputs from premium tree nut sourcing, with ingredient selection directly determining EFSA claim eligibility and clean-label positioning.
- Nuts:Whole almonds, cashews, hazelnuts, and walnuts. Almond and cashew price volatility compresses margin pools in premium positioning tiers across European manufacturing networks.
- Cereals:Oats, wheat flakes, and puffed rice providing structural bulk. Oat-dominant recipes anchor clean-label granola production in Belgian and Dutch specialty facilities.
- Fruits:Dried cranberries, apricots, and date pastes for natural sweetness binding.
- Seeds:Chia, pumpkin, and sunflower seeds delivering omega-3 and mineral fortification.
Nuts command premium shelf pricing; seeds are climbing the fastest on functional positioning.
Flavor Profile:
Application context dictates flavor selection, with sports nutrition favoring utilitarian profiles while impulse retail rewards indulgent positioning.
- Chocolate:Cocoa powder or coating integration across all product types. German consumers demonstrate strongest affinity for dark chocolate variants in premium nut bar formats.
- Vanilla:Neutral base supporting protein isolate masking in sports nutrition applications.
- Fruit Medley:Mixed berry and tropical combinations targeting younger demographics.
- Nutty:Unadorned roasted nut profiles for clean-label purists.
Chocolate dominates absolute volume; fruit medley formats gain share fastest among Gen Z purchasers.
Packaging Type:
Customer type and purchase occasion fragment packaging requirements, with convenience retail demanding single-serve portability while club channels absorb larger formats.
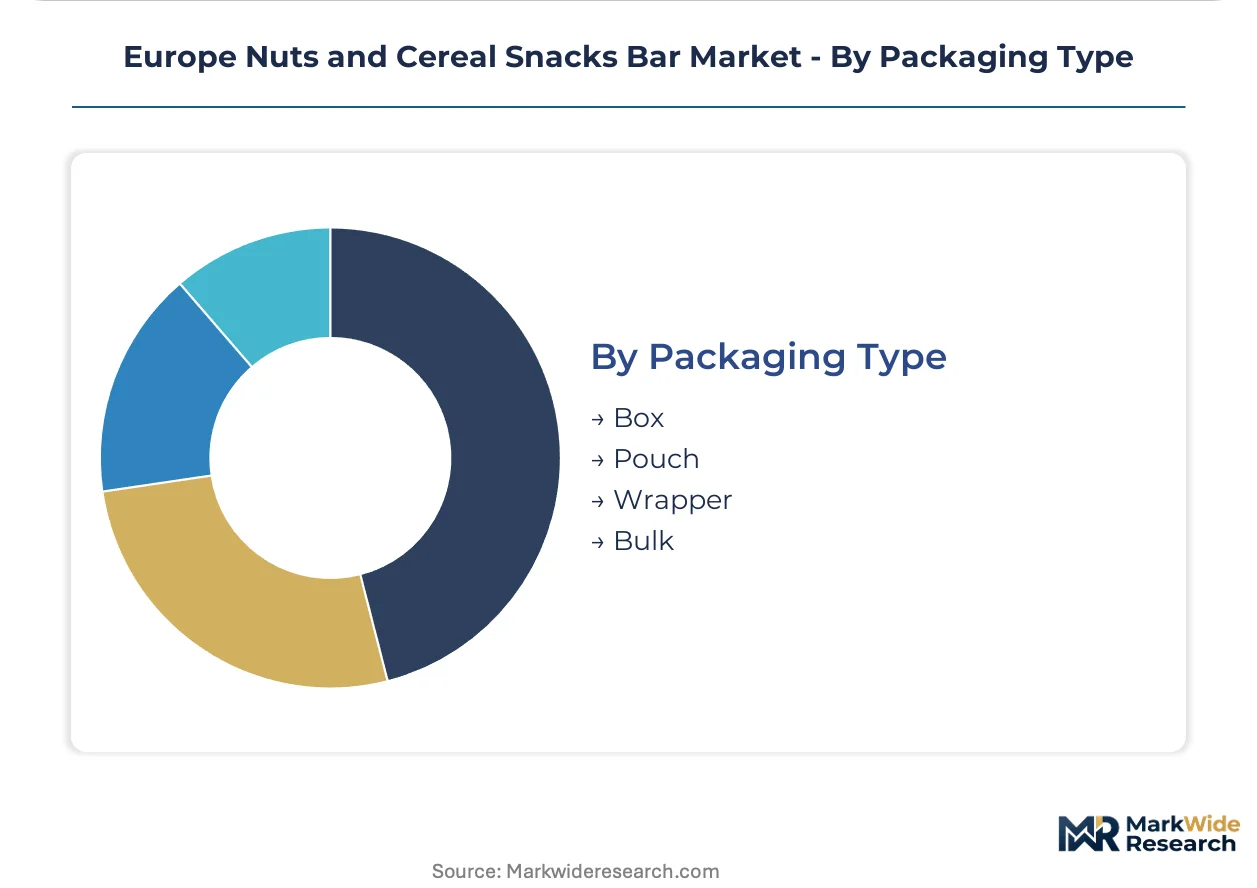
- Box:Multi-unit retail cartons containing 5–6 individual bars. UK supermarkets allocate disproportionate shelf space to boxed granola formats for household breakfast stockpiling.
- Pouch:Resealable flexible packaging for multi-serve mini-bar collections. EU Packaging and Packaging Waste Directive mandates are accelerating recyclable film investments across pouch formats.
- Wrapper:Individual flow-wrap for impulse channel single-serve distribution.
- Bulk:Unwrapped or minimal-packaging formats for foodservice and ingredient supply.
Box formats retain household penetration leadership; pouches show the steepest expansion trajectory in convenience retail resets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium nut bars command shelf pricing premiums in German convenience retail that UK mass-market granola formats cannot replicate, creating a pricing-power asymmetry across the two largest national markets.
Germany
Health-conscious millennials drive protein-enriched format demand through Rewe and Edeka convenience channels. EFSA nutrition and health claims regulation tightens label substantiation requirements for front-of-pack positioning. Munich and Hamburg anchor manufacturing clusters where Mondelēz International operates integrated extrusion facilities for premium whole-nut recipes.
United Kingdom
Breakfast substitution habits sustain granola bar volume leadership despite saturation in morning consumption occasions. UK sugar reduction frameworks mandate reformulation toward reduced glycemic load matrices. London and the Southeast concentrate direct-to-gym distribution pilots where athletic clubs negotiate exclusive supply arrangements bypassing supermarket slotting fees.
France
Gym and athletic segments in Paris and Lyon absorb isolate-fortified protein bars validating EFSA-approved functional claims. ANSM and DGCCRF enforce national nutrition labeling standards beyond baseline EU requirements. The Auvergne-Rhône-Alpes region hosts specialized production facilities focused on clean-label granola formats for export across Benelux markets.
Netherlands
Pharmacy and dietetic retail channels remain underpenetrated versus supermarket dominance, presenting white space for specialty health positioning. EU Packaging and Packaging Waste Directive mandates accelerate recyclable film investments across Dutch co-manufacturing networks. Rotterdam and Amsterdam logistics hubs facilitate cold-pressed binding technology imports from Belgian pilot-scale facilities.
Belgium
Lotus Bakeries anchors clean-label granola production through specialized facilities in the Flemish Region. EFSA claim substantiation backlogs delay marketing rollouts for novel protein sources including insect-derived ingredients. Brussels serves as regulatory intelligence hub where manufacturers monitor evolving EU harmonized standards for mycelium-derived fiber integration.
Europe Nuts and Cereal Snacks Bar Market Competitive Landscape
Concentration sits with diversified multinational food conglomerates controlling integrated European bakery networks and extrusion capabilities. Mid-tier specialists defend position through clean-label differentiation and regional co-manufacturing partnerships. Three archetypes dominate: scale-driven CPG conglomerates with captive ingredient sourcing, premium-focused specialists leveraging Belgian and Dutch production expertise, and agile co-manufacturing networks absorbing extrusion technician scarcity. Competitive moves concentrate on cold-pressed binding technology licensing and direct-to-gym channel bypass strategies.
Among scale-driven CPG conglomerates, Mondelēz International, Inc. and General Mills, Inc. exemplify integrated production architectures controlling ingredient sourcing across premium nut bar portfolios. Lotus Bakeries occupies a specialist position within the clean-label granola tier, while The Simply Good Foods Company represents the protein-focused sports nutrition archetype navigating EFSA claim substantiation requirements. These three named entities anchor competitive positioning without exhausting the full vendor base.
| Leading Market Players |
|---|
| Mondelēz International, Inc. |
| Lotus Bakeries |
| General Mills, Inc. |
| The Simply Good Foods Company |
| PepsiCo, Inc. |
| Nestlé S.A. |
| Hero Group |
| Kellogg Company |
| Mars, Incorporated |
| Others |
Supply & Pricing Matrix
EFSA nutrition and health claims regulation gates both supplier qualification and shelf-price positioning simultaneously, compressing margin pools for non-compliant formulations while elevating premium tiers that bear substantiation costs. Manufacturers face divergent cost structures between heat-extruded commodity granola and cold-pressed premium nut bars where enzymatic binding investments translate into measurable price premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order protein bar formulations from standard granola SKUs, with three-tier pricing structure across premium, standard, and economy levels anchored by EFSA claim certification, whole-nut ingredient ratios, and binding technology sophistication. Price differentiation hinges on isolate-fortification levels and clean-label certification tier, with German convenience retail buyers demonstrating lowest price sensitivity for sports nutrition positioning. Cost compression in economy granola tiers is intensifying because oat and syrup input contracts face agricultural commodity volatility.
Supply Chain Analysis
Strategic stockpiling of whole almonds and cashews dominates over just-in-time cereal inputs, reflecting tree nut price volatility exposure that Belgian and Dutch manufacturers hedge through forward contracts. Supply concentration centers on Spain and Italy for almond sourcing, Vietnam and India for cashew processing, and Germany for extrusion equipment fabrication. Raw material dependencies encompass isolated whey protein from Irish dairy networks, mycelium-derived fibers from Danish pilot facilities, and recyclable film substrates from Dutch converters. Single-source vulnerability in cold-pressed binding enzyme supply elevates risk profiles. Distribution runs through Rewe and Edeka convenience networks in Germany, Tesco and Sainsbury's supermarket channels in the UK, and emerging direct-to-gym bypass arrangements in urban fitness clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operational expertise in extrusion and cold-pressed binding represents the critical capability gap, with technician scarcity forcing strategic choices between captive production investment and co-manufacturing dependence.
For Market Incumbents: Shield margin pools in premium nut bar tiers by securing multi-year almond and cashew offtake agreements before agricultural commodity cycles tighten. Deepen backward integration into enzymatic binding technology licensing to reduce co-manufacturing reliance as extrusion technician scarcity intensifies. Fortify EFSA claim substantiation pipelines to preempt regulatory displacement of front-of-pack positioning. For New Entrants and Emerging Players: Direct-to-gym distribution service gaps in UK and German urban fitness clusters expose incumbents' wholesale channel lock-in. Pharmacy and dietetic retail in the Netherlands and Belgium presents the most penetrable white space versus supermarket-saturated granola categories. Lead with isolate-fortified protein bars bearing EFSA-approved satiety claims to bypass slotting fee barriers through exclusive athletic club supply contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed co-manufacturing networks possessing cold-pressed binding pilot capacity but lacking branded distribution reach. Five-to-ten year viability hinges on regulatory clearance timelines for insect protein and mycelium fiber integration. Watch EFSA novel ingredient approval velocity as the inflection signal distinguishing formulation leaders from compliance laggards.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Claim Substantiation Investment | Human intervention studies for satiety positioning unlock premium shelf access in French and German retail. |
| Cold-Pressed Binding Technology Licensing | Belgian and Dutch pilot-scale facilities extend shelf-stable texture claims while preserving heat-sensitive micronutrients. |
| Direct-to-Gym Distribution Bypass | Exclusive athletic club arrangements in London and Hamburg erode supermarket slotting fee structures. |
| Recyclable Film Packaging Transition | EU Packaging and Packaging Waste Directive compliance secures retail access across Rewe, Edeka, and Tesco networks. |
| Insect Protein Regulatory Pathway Development | EU harmonized standards monitoring positions manufacturers for sustainable protein alternative launch windows. |
Research Methodology
Cross-validation between primary interviews with category buyers at Rewe and Edeka, supply planners at Belgian co-manufacturing facilities, and regulatory affairs leads monitoring EFSA substantiation pipelines anchors the qualitative findings. Secondary validation draws from EU Packaging and Packaging Waste Directive implementation trackers, EFSA novel food approval databases, and Nielsen retail audit data for convenience channel SKU velocity. Bottom-up demand modeling from gym and athletic segment absorption rates triangulates against top-down market sizing from manufacturing capacity declarations.
Sensitivity analysis around almond and cashew price volatility bands, EFSA approval timeline scenarios, and direct-to-gym channel penetration rates stress-tests projection robustness across the analysis window. Segmentation dimensions encompass product type architecture, ingredient sourcing tier, flavor profile positioning, and packaging format compliance requirements. CAGRs derive from volume-weighted average of country-level convenience retail expansion, sports nutrition segment absorption, and breakfast substitution saturation curves.
Underlying assumptions cover EFSA regulatory trajectory continuity, EU Green Deal packaging mandate enforcement intensity, and northern European breakfast habit persistence, with deviation risk concentrated in novel protein source approval delays and agricultural commodity shock events. Revision becomes warranted when insect protein regulatory pathway clarity crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Better for You Snacks Market
Snacks
South Africa Savory Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
South America Snack Bar Market
Snacks
Argentina Snack Bar Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
India Energy Bar Market
Snacks
Specialty Snacks Market
Snacks
United States Popcorn Market
Snacks
Australia Snack Bar Market
Snacks
North America Pretzel Market
Snacks
Kids Snacks Market
Snacks
Latin America Extruded Snack Food Market
Snacks
South America Cereal Bar Market
Snacks
Global Snack Food Market
Snacks
Energy Balls Market