
 Europe Snack Pellets Market | 2026-2036
Europe Snack Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Snack Pellets Market Foresight
CE marking for food contact materials is redrawing competitive boundaries across the Europe snack pellets landscape. LENG-D'OR SAU leverages its Spanish manufacturing base to sustain supply continuity for Mediterranean foodservice chains. Intersnack Group GmbH & Co. KG anchors its position through deep distribution control across German retail channels. Quality Pellets AS differentiates via specialized extrusion expertise serving Nordic private-label programs.
Snack pellets are semi-finished intermediate products produced through extrusion cooking of starch-based formulations, typically containing 60-75% carbohydrate content before final expansion or frying. They serve as shelf-stable inputs that downstream processors finish into ready-to-eat snacks through thermal treatment. Potato-based formulations occupy the largest production volume across European facilities due to established supply chains and neutral flavor adaptability. The extruded form category captures disproportionate capital investment as manufacturers pursue higher throughput rates and dimensional consistency for foodservice clients.
EFSA guidelines on acrylamide mitigation and the EU Green Deal carbon accounting requirements shape formulation choices and process investments throughout the value chain. REACH compliance for processing aids and ECHA evaluations of food contact substances add layers of technical documentation burden for market entry. Stakeholders must monitor how the EU AI Act's deployment rules affect automated quality control systems in extrusion plants.
Market Dynamics
EU Green Deal carbon accounting requirements are forcing snack pellet manufacturers to reconfigure extrusion energy profiles and document supply chain emissions across starch sourcing networks.
Growth Catalysts
- Foodservice channel expansion:Industrial bakeries and QSR chains across Germany, France, and Spain are standardizing snack pellets as base inputs for proprietary menu items, reducing per-unit preparation labor.
- REACH-compliant processing aids:ECHA evaluations of food contact substances have clarified compliance pathways, enabling faster formulation approvals for potato-based and multigrain variants entering Nordic markets.
- Acrylamide mitigation protocols:EFSA guidelines on thermal process control are driving adoption of low-temperature extrusion systems that maintain expansion rates while reducing downstream frying requirements.
Market Restraints
- Input cost volatility:Potato starch and native cereal flour prices fluctuate with harvest yields across Poland and the Netherlands, compressing margin visibility for mid-scale extruders.
- Supply concentration risk:German industrial clusters control disproportionate extrusion capacity, creating geographic vulnerability for southern European foodservice clients during logistics disruptions.
- Technical limitation in clean-label expansion:Removing phosphate-based processing aids degrades dimensional consistency in high-throughput lines, constraining premium positioning for certain private-label programs.
Strategic Opportunities
- Eastern European underpenetration:Romania and Bulgaria maintain limited domestic extrusion capacity, creating white space for regional supply hubs serving Balkan retail and foodservice growth.
- EU AI Act deployment rules:Automated quality control systems in extrusion plants face new documentation requirements, favoring early movers who integrate compliant machine vision for dimensional verification.
- Cleaner label convergence:Combining enzymatic starch modification with reduced-sodium formulations addresses simultaneous EFSA sodium reduction guidance and consumer preference shifts in Benelux markets.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized process engineers capable of optimizing twin-screw configurations for novel starch blends command premium compensation, constraining R&D throughput.
- CE marking timeline compression:Food contact material certifications for new equipment designs now average 14-18 months, delaying capital deployment for capacity expansion projects.
- Legacy system integration friction:Retrofitting carbon accounting sensors into existing extrusion lines without disrupting continuous production schedules requires staged capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Snack Pellets Market |
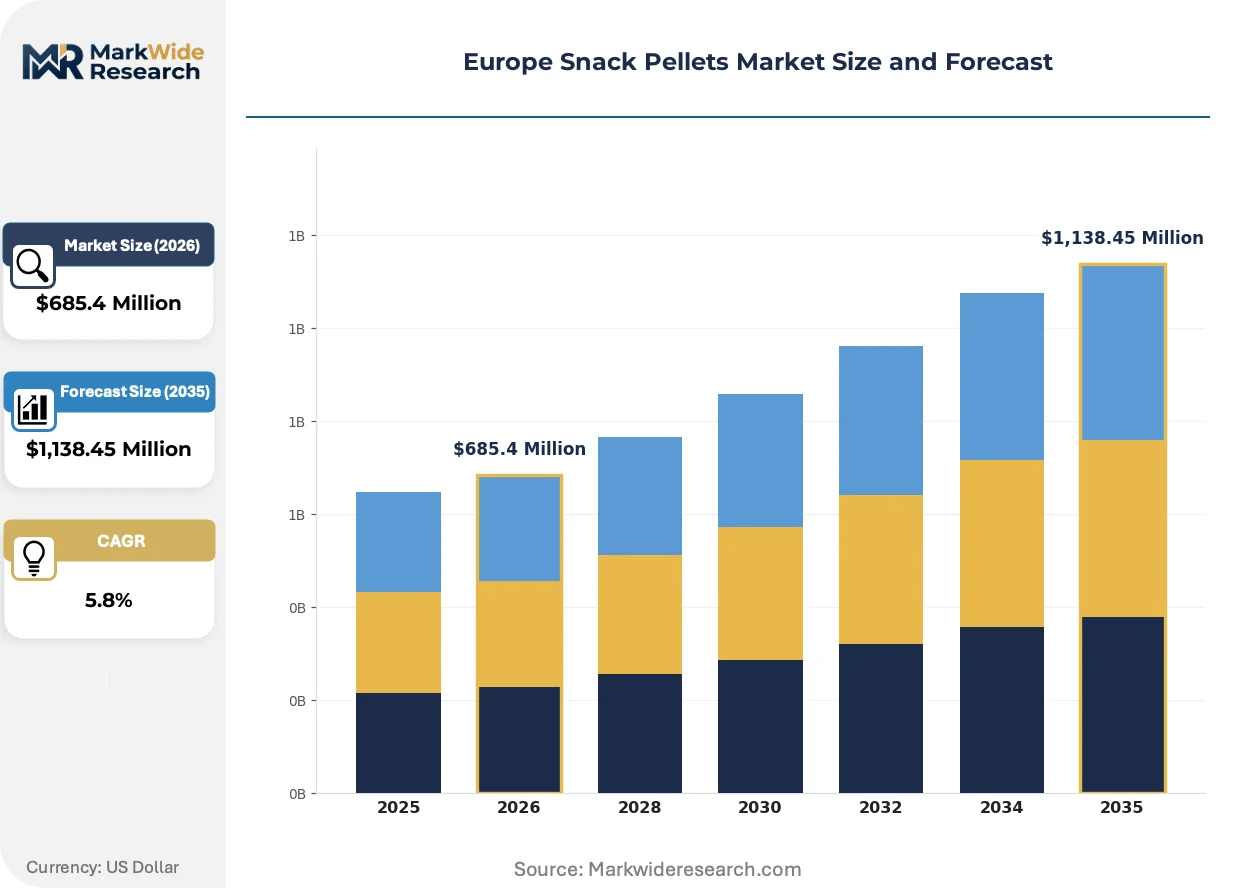
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato-based, Corn-based, Rice-based, Tapioca-based Form: Puffed, Extruded, Baked, Fried End User: Retail, Foodservice, Online, Institutional Flavor Profile: Savory, Sweet, Spicy, Smoky |
| Companies Covered | Le Caselle SpA, LENG-D'OR SAU, Mafin SRL, Quality Pellets AS, Snack Creations Ltd, Societe Cooperative Agricole Limagrain, Intersnack Group GmbH & Co. KG, ICA Foods SpA, Bag Snacks, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Snack Pellets Market Shifts & Advancements
Extrusion technology is fragmenting across multiple performance tiers as manufacturers balance throughput demands against energy intensity and formulation flexibility requirements.
Enzymatic starch modification is fragmenting traditional extrusion process boundaries by enabling lower-temperature gelatinization. Foodservice clients in France and Italy are piloting these modified bases for customized texture profiles. The technology is fragmenting equipment vendor market share as specialized biotech suppliers enter upstream formulation partnerships.
CSRD reporting mandates are compelling manufacturers to document Scope 3 emissions from agricultural sourcing through distribution. This creates audit infrastructure demands that favor larger extruders with dedicated sustainability teams. German and Dutch facilities are investing first due to earlier national transposition deadlines and existing industrial energy management capabilities.
Consolidated procurement by pan-European retail alliances is compressing supplier negotiation cycles and unbundling technical service components from base pellet pricing. Nordic buying cooperatives are leading this shift, separating recipe development support from volume contracts. The pattern is most visible in Sweden and Denmark where retail concentration supports centralized category management functions.
Europe Snack Pellets Market Segmentation
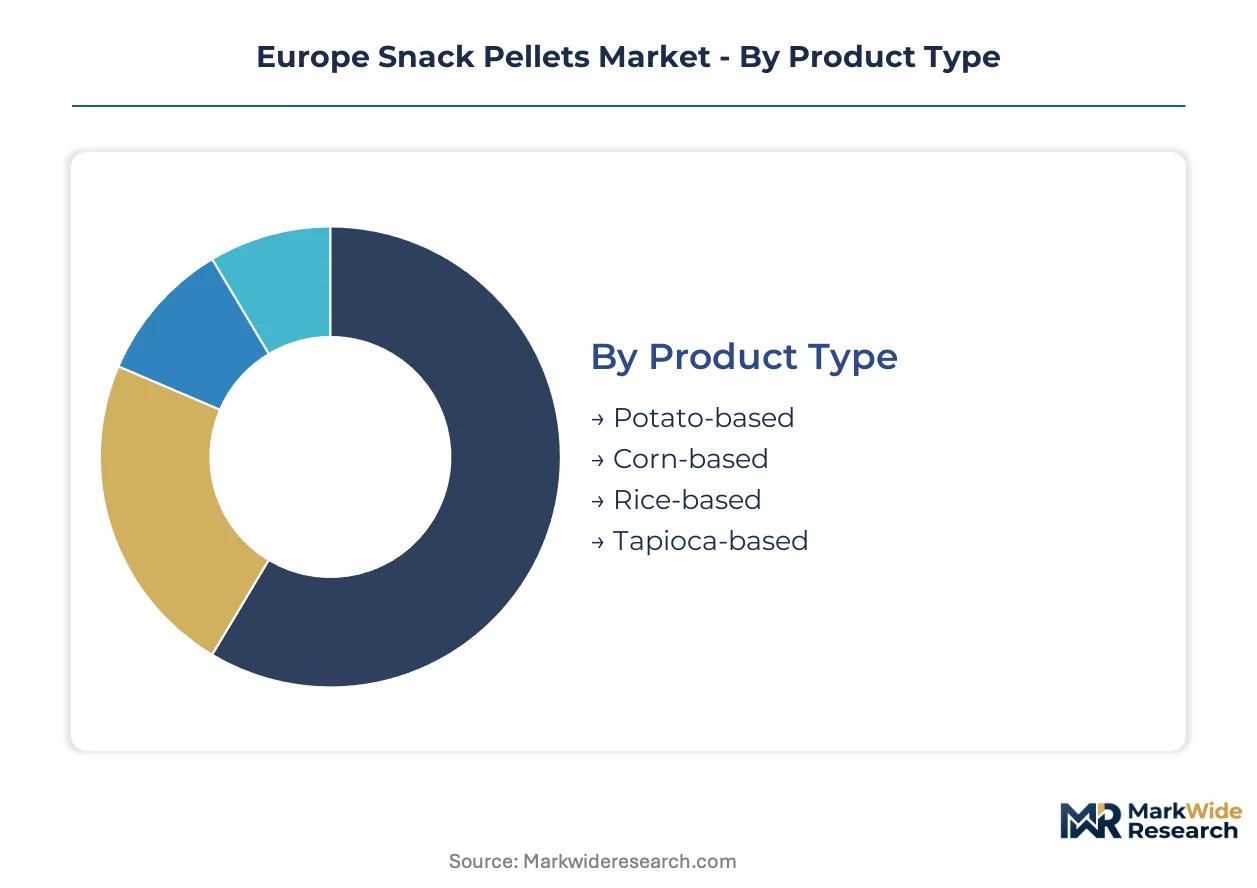
Segmentation in the Europe snack pellets market reveals how formulation choices, processing methods, and channel strategies create distinct margin profiles. Understanding these divisions helps manufacturers allocate capital between high-throughput commodity production and specialized premium outputs.
Product Type:
Premium margins concentrate in specialty starch blends that command formulation premiums from private-label programs, while commodity potato-based volumes anchor cash flow stability for large extruders.
- Potato-based:These formulations leverage established supply chains across the Netherlands and Poland, delivering neutral flavor adaptability that foodservice clients in Germany and France prioritize for proprietary seasoning applications. German industrial bakeries and QSR chains standardize these inputs for menu consistency, though harvest yield volatility in Polish growing regions creates margin compression risk during contract renegotiations.
- Corn-based:Higher gelatinization temperatures enable distinct texture profiles that appeal to Mediterranean markets seeking differentiated snack bases. Spanish and Italian foodservice operators specify corn-based pellets for regional flavor pairings, with EFSA acrylamide guidelines favoring their lower reducing sugar content in thermal processing.
- Rice-based:Clean-label positioning in Benelux markets drives demand for these gluten-free alternatives with minimal allergen declarations.
- Tapioca-based:Specialized applications in Nordic private-label programs exploit tapioca's unique expansion characteristics for premium texture differentiation.
Potato-based holds installed capacity. Corn-based is rotating up the share rankings.
Form:
Capital intensity varies dramatically across processing methods, with extruded forms demanding precision engineering while baked variants attract sustainability-focused investment under EU Green Deal carbon accounting.
- Extruded:Twin-screw extrusion systems achieve dimensional consistency critical for automated downstream finishing in high-volume foodservice operations. German facilities dominate installed capacity, with REACH-compliant processing aids enabling faster formulation approvals for multigrain variants entering Nordic markets.
- Puffed:Low-density structures reduce shipping costs per unit volume, appealing to centralized distribution models serving pan-European retail alliances. The form's energy-intensive expansion step faces scrutiny under CSRD Scope 3 reporting mandates, favoring producers with renewable energy contracts.
- Baked:Reduced oil content aligns with EFSA sodium reduction guidance and clean-label positioning in French and Italian markets.
- Fried:Traditional finish methods persist in Eastern European markets where flavor intensity outweighs health positioning.
Extruded commands the capital deployment. Baked is climbing the fastest on sustainability credentials.
End User:
Channel concentration shapes pricing power, with consolidated retail alliances extracting technical service unbundling while foodservice growth offers volume expansion with attached formulation support premiums.
- Foodservice:Industrial bakeries and QSR chains across Germany, France, and Spain standardize snack pellets as base inputs, reducing per-unit preparation labor while enabling proprietary menu differentiation. The channel's specification requirements create sticky supplier relationships that resist pure price competition.
- Retail:Pan-European buying cooperatives in Sweden and Denmark separate recipe development from volume contracts, compressing supplier margins on base pellet pricing while demanding dedicated category management support.
- Online:Direct-to-consumer channels in urban Benelux clusters enable premium positioning for specialized flavor profiles with shorter production runs.
- Institutional:Public procurement frameworks in Romania and Bulgaria create volume anchors for regional supply hub development.
Foodservice holds the margin expansion. Retail is rotating up the share rankings through buying cooperative consolidation.
Flavor Profile:
Development cost structures diverge sharply between savory commodity formulations with established seasoning partnerships and emerging spicy variants requiring novel heat-delivery engineering.
- Savory:Cheese and onion, salt and vinegar, and plain salted variants constitute the volume base across all European markets, with established seasoning houses providing formulation stability. German and British retail channels maintain disproportionate share of savory-standard demand.
- Spicy:Chili-forward and pepper-based heat profiles gain traction in Spanish and Italian foodservice pilot programs seeking menu differentiation. Capsaicin delivery systems require modified starch matrices to prevent flavor degradation during extrusion, raising technical barriers to entry.
- Sweet:Cinnamon, vanilla, and fruit-based profiles serve seasonal promotional cycles in Nordic retail.
- Smoky:Wood-smoke and charred variants attract premium positioning in French gastronomic snack segments.
Savory holds installed capacity. Spicy is gaining share fastest on foodservice menu innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice buyers and industrial bakeries concentrate procurement power in German and French metropolitan clusters, while Nordic retail cooperatives and Mediterranean QSR chains fragment demand across secondary hubs. Regulatory compliance costs from EFSA acrylamide protocols and EU Green Deal carbon accounting reshape facility location decisions. Eastern European markets remain underpenetrated by domestic extrusion capacity.
Germany
Industrial bakeries and QSR chains in the Rhine-Ruhr and Munich-Stuttgart corridors standardize potato-based pellets for proprietary menu items. EFSA sodium reduction guidance drives reformulation partnerships between extruders and seasoning houses. The Baden-Württemberg cluster hosts dense twin-screw extrusion capacity serving pan-European foodservice clients.
France
Gastronomic snack segments in Île-de-France and Auvergne-Rhône-Alpes pilot enzymatically modified bases for customized texture profiles. EU Green Deal carbon accounting mandates accelerate energy retrofit investments in extrusion plants. The Lyon industrial basin concentrates clean-label R&D collaboration between biotech suppliers and pellet manufacturers.
Spain
Mediterranean foodservice chains specify corn-based formulations for regional flavor pairings in Barcelona and Madrid metro areas. REACH-compliant processing aids enable faster approvals for multigrain variants entering export markets. The Valencia agricultural corridor anchors starch supply integration for extrusion facilities.
Netherlands
Benelux retail channels drive demand for rice-based gluten-free alternatives with minimal allergen declarations. CSRD reporting mandates compel Scope 3 documentation from agricultural sourcing through Rotterdam distribution. The Eindhoven-Tilburg industrial zone concentrates automated quality control system deployment.
Poland
Harvest yield volatility in potato growing regions creates margin compression risk for contract-dependent extruders. ECHA evaluations of food contact substances clarify compliance pathways for eastern expansion. The Łódź manufacturing belt attracts capacity investment serving underpenetrated Balkan retail growth.
Europe Snack Pellets Market Competitive Landscape
Player mix skews toward mid-scale specialists with deep formulation expertise rather than diversified conglomerates. The structure concentrates extrusion capacity in German and Spanish industrial clusters while fragmenting across Nordic and Italian niche operators. Two archetypes dominate: vertically integrated starch processors controlling upstream supply, and technology-licensed specialists serving private-label programs. Competitive moves center on capacity expansion in Eastern European white-space markets and strategic partnerships with enzymatic modification suppliers.
Among Spanish and French fabricators, LENG-D'OR SAU and Le Caselle SpA exemplify the Mediterranean foodservice-focused archetype with sustained supply continuity for regional chains. German-based Intersnack Group GmbH & Co. KG occupies a position representing deep distribution control across retail channels. Nordic specialist Quality Pellets AS anchors the private-label technology tier, while Mafin SRL and ICA Foods SpA sit within the Italian diversified-snack conglomerate structure. These five entities collectively illustrate how geographic origin and corporate suffix patterns map to strategic positioning across formulation expertise, channel control, and regional supply hub functions.
| Leading Market Players |
|---|
| Le Caselle SpA |
| LENG-D'OR SAU |
| Mafin SRL |
| Quality Pellets AS |
| Snack Creations Ltd |
| Societe Cooperative Agricole Limagrain |
| Intersnack Group GmbH & Co. KG |
| ICA Foods SpA |
| Bag Snacks |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with starch processors lock in supply access for German extruders while anchoring price visibility against Polish harvest volatility. These contracts index to regional potato starch benchmarks, transferring commodity risk upstream while securing throughput commitments for high-volume foodservice clients.
Pricing Analysis
Cost-plus contracts with EU Green Deal carbon indexation dominate procurement between extruders and industrial bakery chains. Price differentiation hinges on REACH-compliant certification tiers and volume scale, with premium positioning attaching to enzymatically modified bases. Cost compression in standard potato-based tiers is intensifying because Nordic retail cooperatives unbundle technical services from base pellet contracts. Foodservice buyers exhibit lowest price sensitivity due to specification stickiness, while pan-European retail alliances drive hardest bargain extraction.
Supply Chain Analysis
Strategic stockpiling of native cereal flours prevails among Dutch and German extruders buffering against harvest timing mismatches, while just-in-time potato starch delivery dominates southern European facilities with shorter supply lines. Geographic concentration centers on Germany, Spain, and Poland, with the latter anchoring raw agricultural input flows. The chain rests on potato starch, native wheat flour, and enzymatic processing aids as core inputs. Single-source vulnerability runs through Polish growing regions concentrated in specific climatic zones. Distribution runs through Rotterdam and Hamburg port clusters serving pan-European foodservice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon accounting mandates are disrupting established extrusion economics, creating asymmetric advantage for operators with renewable energy contracts and documented Scope 3 audit trails.
For Market Incumbents: Compound formulation expertise into adjacent clean-label segments before enzymatic modification patents consolidate among biotech suppliers. Prioritize backward integration into Polish starch processing to capture margin from harvest volatility. CE marking timeline compression threatens capacity expansion schedules; front-load equipment approvals now. For New Entrants and Emerging Players: Differentiate on localized supply hub positioning in Romania and Bulgaria where domestic extrusion capacity remains sparse. Target institutional procurement frameworks in Balkan public sectors as volume anchors with lower competitive density. Lead with automated quality control systems compliant with EU AI Act deployment rules as technical credibility builder. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foodservice-focused extruders with multi-year QSR chain contracts, offering visibility through commodity cycles. Long-term viability favors specialists with enzymatic modification partnerships over commodity potato-based volume players. Watch for EFSA acrylamide protocol tightening as signal for accelerated low-temperature extrusion system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Partnership | Biotech supplier alliances unlock lower-temperature gelatinization for EFSA-compliant clean-label positioning. |
| Eastern European Capacity Buildout | Romania and Bulgaria hubs capture Balkan retail growth while reducing logistics vulnerability for Mediterranean clients. |
| Renewable Energy Contracting | Green power agreements satisfy CSRD Scope 3 mandates and differentiate bids for EU Green Deal-compliant procurement. |
| Automated Quality Control Deployment | EU AI Act-compliant machine vision systems secure foodservice specifications requiring dimensional verification. |
| REACH-Compliant Processing Aid Reformulation | Phosphate-free alternatives enable premium private-label positioning despite technical consistency challenges. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including extrusion plant managers, foodservice procurement directors at QSR chains, retail category buyers in Nordic cooperatives, and technical R&D leads at seasoning houses. Secondary validation drew from EFSA guidance documents, ECHA food contact substance evaluations, CSRD transposition texts, EU Green Deal implementation reports, and customs trade data for starch-based intermediate products. Bottom-up capacity assessments across German and Spanish industrial clusters were triangulated against top-down demand modeling from foodservice channel expansion rates.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by formulation base, processing form, end-user channel, and flavor profile, with additional dimensioning by carbon accounting compliance tier. CAGRs were derived from trend extrapolation of foodservice penetration rates and regulatory compliance investment cycles. Key inputs included EFSA sodium reduction guidance implementation timelines and EU AI Act enforcement phase-ins affecting automated quality control adoption.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or EFSA acrylamide protocol tightening would require recalibration. Forecasts reflect documented assumptions on starch harvest yield patterns and carbon border adjustment mechanism coverage expansion. Revision becomes warranted when enzymatic modification cost curves cross threshold parity with conventional extrusion processing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Sweet Potato Chips Market
Snacks
Saudi Arabia French Fries Market
Snacks
Europe Popcorn Market
Snacks
Middle East Snack Bar Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Salty Puffed Snacks Market
Snacks
Marshmallow Market
Snacks
North America Potato Chips Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Organic Snack Food Market
Snacks
Seaweed Snacks Market
Snacks
Europe Frozen Snacks Market
Snacks
Asia Pacific Tortilla Market
Snacks
Grass-Fed Jerkies Market
Snacks
South America Protein Bar Market
Snacks
Organic Snacks Market