
 United Arab Emirates Energy Bar Market | 2026-2036
United Arab Emirates Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Energy Bar Market Analytics
Date paste and chicory root fiber is repositioning traditional glucose syrups in energy bar formulations across the Emirates. Quest Nutrition leverages its protein-science heritage to anchor premium shelf positioning in Dubai's health food channels. Barebells competes through Swedish-formulated taste profiles calibrated for Gulf palates. Nestlé SA extends its confectionery logistics infrastructure to dominate ambient distribution across UAE retail estates.
An energy bar is a shelf-stable, nutrient-dense food product typically comprising protein isolates, binding syrups, and structural inclusions, manufactured through cold-press extrusion or baked slab-and-cut processes, designed to deliver rapid macronutrient replenishment for active consumers. Protein bars command the largest volume share as gym memberships surge across Abu Dhabi and Dubai, while low-sugar variants represent the fastest-expanding margin pool as MOHAP guidelines tighten added-sugar thresholds. Online retail channels are capturing disproportionate growth velocity among on-the-go professionals seeking subscription-based replenishment models.
MOHAP enforces nutritional labeling standards and health claim validations for all functional food products sold in the Emirates, compelling reformulation investments from imported and domestic brands alike. ESMA's food safety management system certification requirements shape manufacturing partner selection for market entrants. FSSAI-equivalent import documentation from Indian and European suppliers adds compliance layering at UAE customs checkpoints. Stakeholders must monitor evolving sugar-tax discussions and halal certification harmonization across GCC markets to anticipate product registration timelines and reformulation cycles.
Market Dynamics
MOHAP's tightening nutritional labeling mandates are forcing reformulation cycles across UAE energy bar portfolios, compressing product development timelines while elevating compliance costs for both domestic manufacturers and import-dependent brands.
Growth Catalysts
- Protein-fortified formulations:Gym membership expansion across Dubai and Abu Dhabi is pulling demand for high-protein formats, with fitness enthusiasts now representing the fastest-growing buyer segment in the Emirates.
- MOHAP labeling harmonization:Updated food labeling requirements for nutritional claims are standardizing product transparency, creating competitive differentiation for early-compliant brands in health food retail channels.
- Date paste substitution:Local date processing infrastructure is displacing imported glucose syrups, reducing input costs while aligning formulations with regional ingredient preferences and halal certification pathways.
Market Restraints
- Import documentation layering:FSSAI-equivalent certification requirements from Indian and European suppliers add friction at UAE customs checkpoints, extending lead times for cross-border replenishment.
- Sugar threshold compression:MOHAP guidelines tightening added-sugar thresholds are constraining formulation flexibility, particularly for confectionery-heritage brands reliant on traditional sweetening systems.
- Retail estate concentration:Category visibility anchors in Dubai's premium supermarket chains, creating geographic demand asymmetry that disadvantages distribution build-out in Northern Emirates retail corridors.
Strategic Opportunities
- Subscription replenishment models:Online retail channels are capturing disproportionate growth velocity among on-the-go professionals, enabling direct-to-consumer margin retention bypassing traditional retail slotting fees.
- Chicory root fiber integration:Prebiotic fiber positioning opens functional claims differentiation in digestive health, a white space adjacent to established protein and energy positioning.
- GCC halal harmonization:Anticipated certification standardization across Gulf markets would streamline multi-country product registration, reducing duplicate testing costs for UAE-based manufacturers.
Industry Challenges
- Reformulation talent scarcity:Food technologists skilled in sugar-reduction and protein-stability optimization command premium compensation, constraining mid-tier brand R&D bandwidth.
- Cold-chain ambient tension:Shelf-stable bar formats require specialized packaging investment to maintain texture integrity through UAE summer temperature excursions, elevating unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Energy Bar Market |
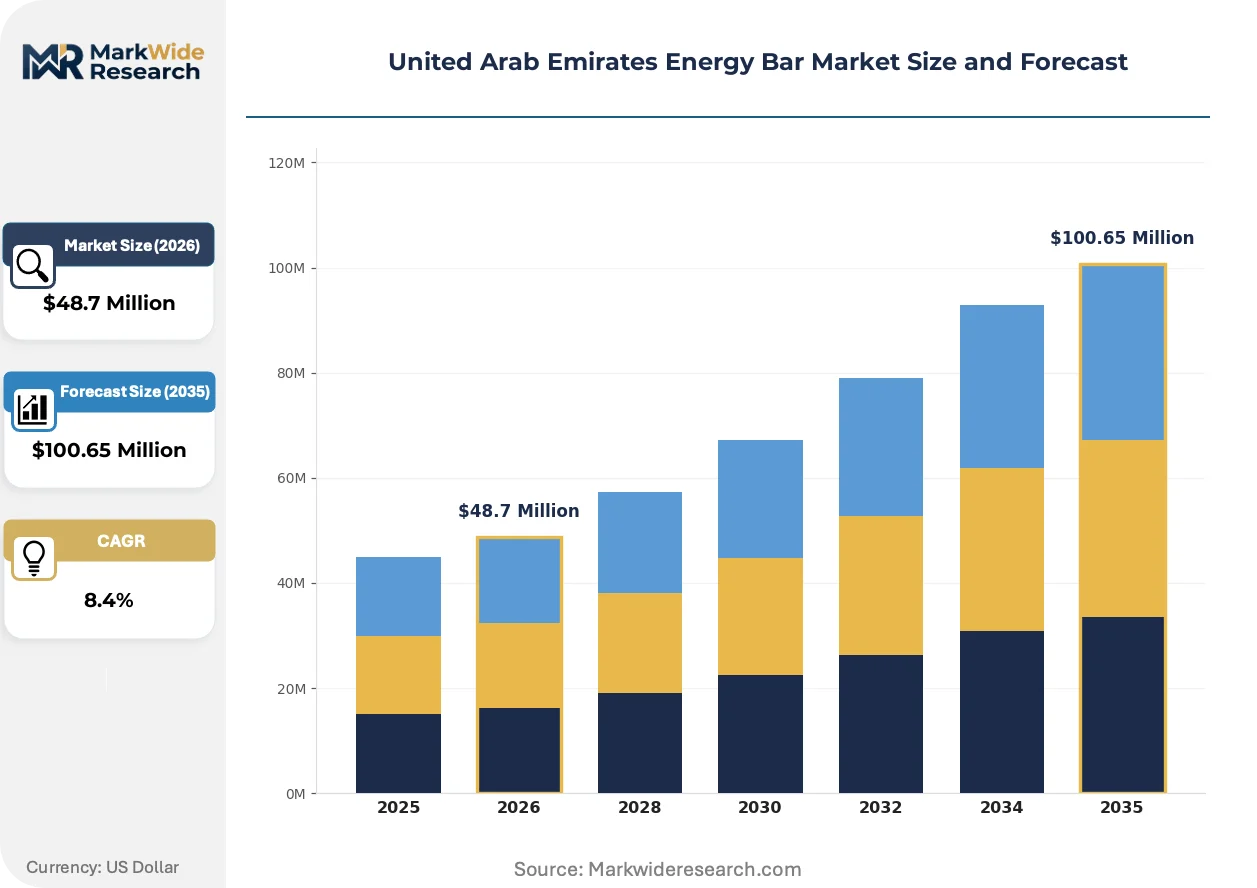
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacement Bars, Snack Bars, Low-Sugar Bars Ingredient Type: Nut-Based, Fruit-Based, Grain-Based, Vegan Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Customer Type: Health-Conscious Consumers, Athletes, On-the-Go Professionals, Students |
| Companies Covered | Clif Bar & Company, Natural Balance Foods, Rise Bar, Barebells, Nutrition Inc. (Pureprotein), General Mills Inc., Quest Nutrition, Nestlé SA, BioNutritional Research Group, Inc (Power Crunch), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Energy Bar Market Evolving Landscape
Ingredient sourcing and formulation architecture are undergoing systematic transformation across UAE energy bar manufacturing, driven by regulatory pressure, local supply maturation, and shifting consumer preference hierarchies.
Date paste is consolidating its position as the primary binding and sweetening substrate in Emirates-manufactured energy bars, displacing maltitol and corn syrup derivatives in reformulation pipelines. Domestic date processors in Al Ain and Liwa are scaling paste standardization to food-grade specifications, enabling local brands to anchor halal-provenance claims while reducing import dependency. This consolidation is compressing cost structures for mid-market producers and creating formulation divergence between UAE-origin and European-imported portfolios.
MOHAP's updated nutritional labeling requirements for health claims validation are reshaping product development workflows across functional food categories in the Emirates. The regulation mandates substantiation dossiers for protein content, fiber, and energy claims, compelling brands to invest in analytical testing partnerships. Low-sugar variants face the steepest compliance burden, as sugar-reduction claims trigger enhanced scrutiny and extended registration timelines at the federal level.
Fitness-oriented consumers are rotating purchasing behavior toward subscription-based replenishment through e-commerce platforms, disintermediating traditional health food store discovery. This channel shift concentrates buyer data with platform operators, eroding brand-direct relationship economics. The pattern is most pronounced among Dubai-based professionals aged 25-40, where convenience prioritization overrides price sensitivity in repeat purchase decisions.
United Arab Emirates Energy Bar Market Segmentation
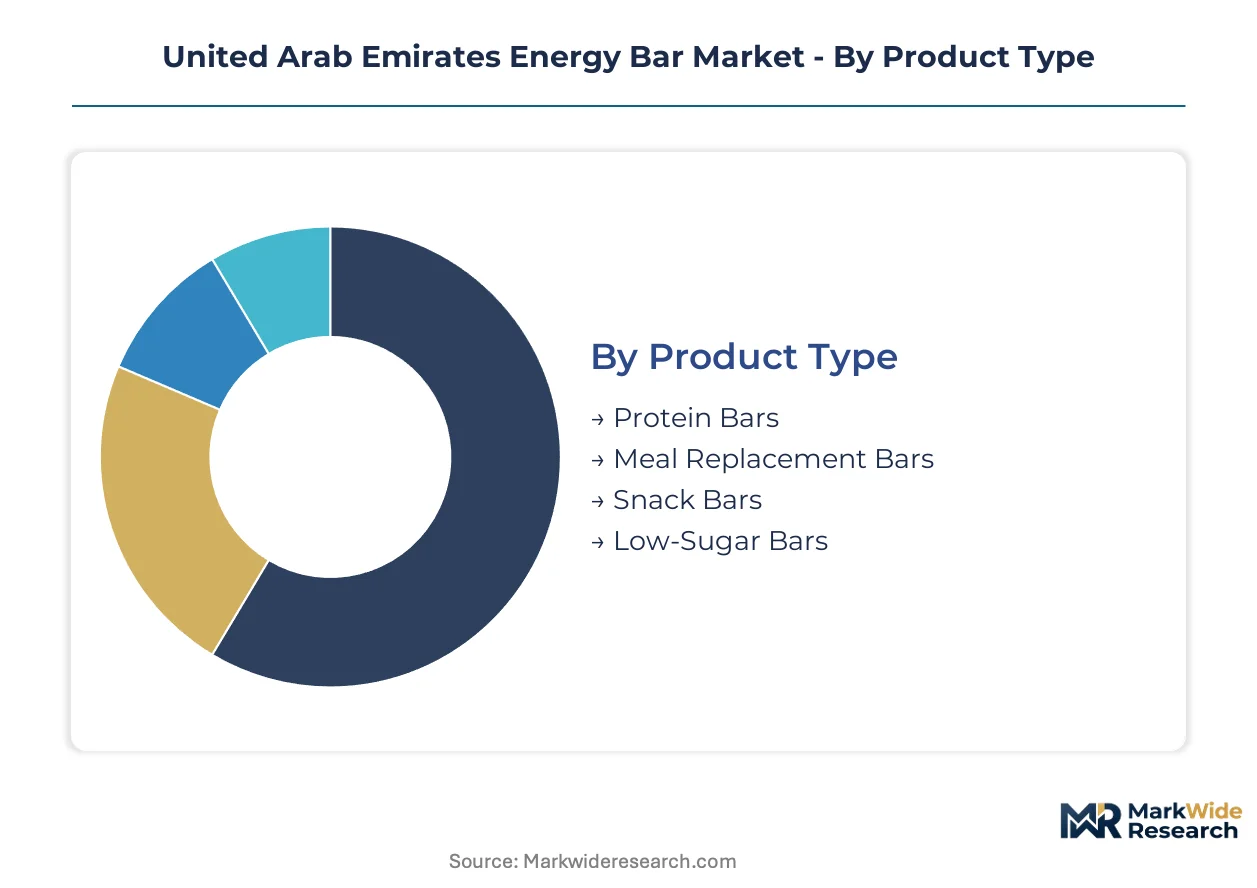
Segmentation in the UAE energy bar market reveals how regulatory requirements, distribution infrastructure, and consumer lifestyle patterns create distinct commercial battlegrounds. Each dimension carries unique certification burdens and margin profiles that shape manufacturer prioritization.
Product Type:
MOHAP's health claim validation requirements apply differentially across product formats, with protein content declarations triggering the most extensive substantiation dossiers.
- Protein Bars:Formulations delivering 15-25g protein per serving through whey isolate or plant-based concentrates dominate gym-adjacent retail in Dubai Marina and Al Quoz fitness clusters. Demand concentrates among bodybuilding enthusiasts and CrossFit practitioners seeking post-workout macronutrient replenishment.
- Meal Replacement Bars:Calorie-dense formats fortified with micronutrient blends target time-constrained professionals in Dubai International Financial Centre and Abu Dhabi Global Market corridors. These products face heightened scrutiny under MOHAP's complete nutrition labeling mandates.
- Snack Bars:Lower-protein convenience formats position for impulse purchase occasions in petrol station retail and office vending channels.
- Low-Sugar Bars:Reformulated products using date paste and chicory root fiber displace maltitol-sweetened legacy formats as sugar threshold guidelines tighten.
Protein Bars sit at the top of the volume ranking, with Low-Sugar Bars climbing the fastest.
Ingredient Type:
Halal certification pathways and import documentation requirements vary sharply by ingredient sourcing geography, creating cost tier differentiation across formulation architectures.
- Nut-Based:Almond and cashew-dominant formulations leverage UAE re-export infrastructure from Iranian and Turkish supply corridors. These products command premium shelf positioning in Emirates Hills and Palm Jumeirah retail estates.
- Fruit-Based:Date paste and dried fruit inclusions anchor regional provenance claims while satisfying local palate preferences for natural sweetness profiles.
- Grain-Based:Oat and quinoa structural matrices target sustained-release energy positioning for endurance athletes training in Al Qudra cycling circuits.
- Vegan:Plant-protein isolates from pea and rice sources require enhanced allergen labeling under ESMA food safety protocols.
Nut-Based formats capture the highest margin tier, while Vegan alternatives show the steepest expansion trajectory among younger demographics.
Distribution Channel:
Channel selection determines exposure to ambient temperature stress and slotting fee structures, with summer logistics capabilities becoming a competitive differentiator.
- Online Retail:Subscription models and same-day delivery platforms concentrate buyer data with Noon and Amazon.ae operators, enabling direct replenishment for Dubai professionals aged 25-40. Cold-chain packaging investments are minimal given ambient-stable bar formats.
- Supermarkets:Union Coop, Lulu, and Carrefour hypermarkets anchor category visibility through premium placement fees in Dubai's retail corridors.
- Convenience Stores:ADNOC distribution and Emirates petrol station retail capture impulse purchase occasions along Sheikh Zayed Road transit corridors.
- Health Food Stores:Nutrition Zone and specialized fitness retail in JLT and Business Bay clusters curate premium imported portfolios with enhanced MOHAP documentation.
Supermarkets maintain volume leadership, though Online Retail is gaining share fastest among repeat purchase cohorts.
Customer Type:
Purchase frequency and price sensitivity diverge markedly across occupational and lifestyle segments, driving portfolio breadth requirements for national distribution.
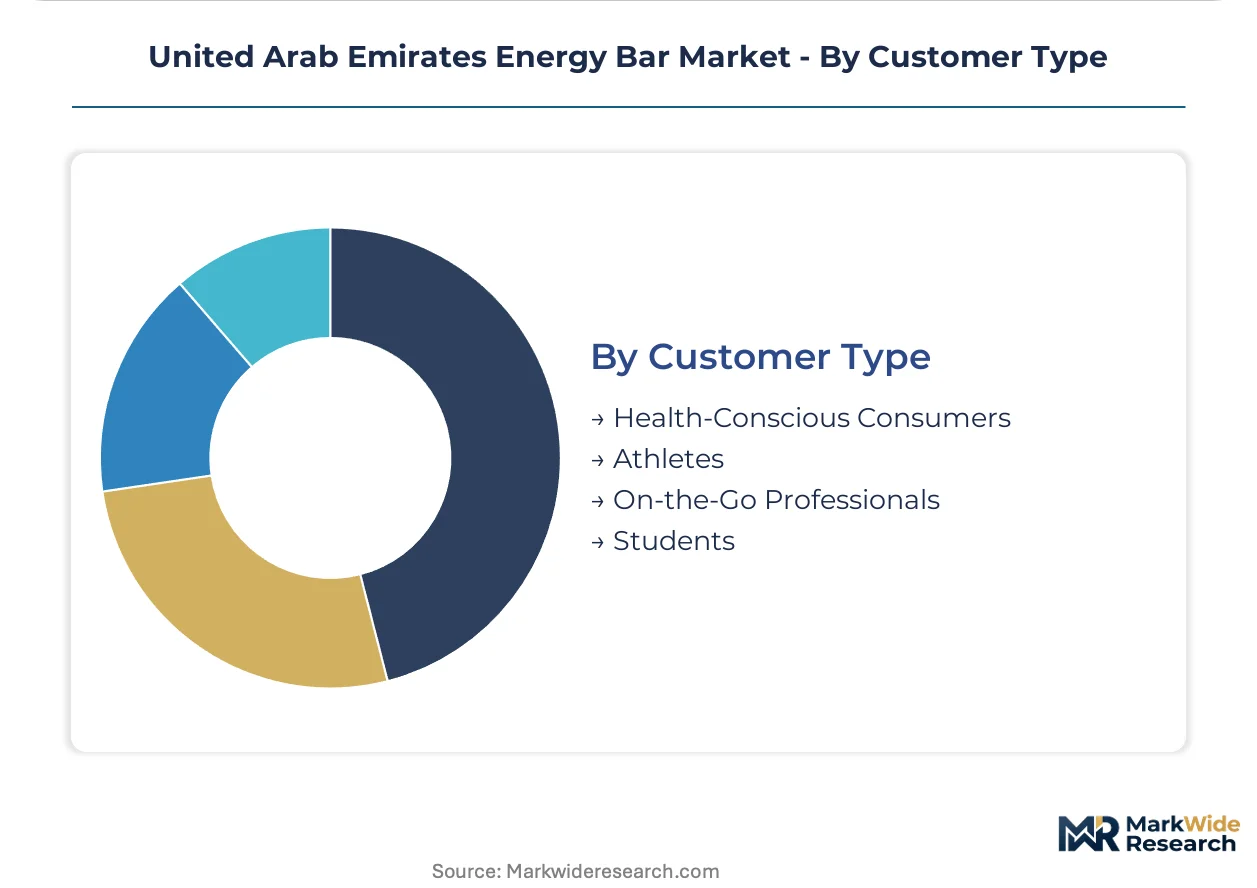
- Health-Conscious Consumers:Ingredient label scrutiny and clean-label preferences concentrate among expatriate populations in Dubai's wellness-oriented communities. These buyers drive demand for organic certification and non-GMO positioning.
- Athletes:Competitive and recreational sports practitioners prioritize protein density and amino acid completeness, with purchasing concentrated around training facility proximate retail.
- On-the-Go Professionals:Convenience prioritization overrides price sensitivity in this segment, with subscription replenishment models capturing loyalty through automated delivery scheduling.
- Students:Price-conscious purchasing in university-adjacent retail in Sharjah and Al Ain drives demand for economy-tier formats and multi-pack value positioning.
Health-Conscious Consumers anchor the premium tier by volume, with On-the-Go Professionals expanding most quickly through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's retail corridors anchor energy bar demand concentration across the Emirates, with health food stores and premium supermarket chains driving category visibility. Abu Dhabi's fitness infrastructure expansion and Sharjah's student demographics create distinct sub-regional consumption patterns. Northern Emirates distribution build-out remains underdeveloped relative to the southern commercial axis.
Dubai
Gym membership expansion in Dubai Marina and Al Quoz fitness clusters pulls demand for high-protein formats. MOHAP's updated nutritional labeling requirements standardize product transparency for brands entering health food retail channels. JLT and Business Bay nutrition zones curate premium imported portfolios with enhanced federal documentation.
Abu Dhabi
CrossFit practitioners and bodybuilding enthusiasts in the capital prioritize post-workout macronutrient replenishment through whey isolate formulations. ESMA food safety management system certification shapes manufacturing partner selection for market entrants targeting institutional channels. Yas Island and Al Maryah Island retail estates concentrate premium positioning for meal replacement bars targeting financial district professionals.
Sharjah
University-adjacent retail corridors drive price-conscious purchasing among student demographics seeking economy-tier formats and multi-pack value positioning. FSSAI-equivalent import documentation from Indian suppliers adds compliance layering at UAE customs checkpoints for brands penetrating this segment. University City and Muwaileh commercial zones anchor distribution for convenience-oriented snack bar formats.
Northern Emirates
Geographic demand asymmetry disadvantages distribution build-out in Ajman, Umm Al Quwain, and Ras Al Khaimah retail corridors relative to Dubai's premium supermarket concentration. ADNOC petrol station distribution captures impulse purchase occasions along Sheikh Zayed Road transit corridors extending northward. Local date processing infrastructure in Ras Al Khaimah is scaling paste standardization to reduce import dependency for regional manufacturers.
United Arab Emirates Energy Bar Market Competitive Landscape
Global majors compete with regional champions across formulation architecture and distribution reach in the Emirates. The vendor base segments into confectionery conglomerates with ambient logistics infrastructure, protein-science specialists with gym-channel heritage, and regional date-processing integrators leveraging local supply maturation. Three strategic archetypes dominate: European taste-profile optimizers, North American protein-density leaders, and Gulf-based halal-provenance brands. Competitive intensity concentrates on subscription-based replenishment models and summer temperature-resilient packaging investments.
Within the protein-science specialist tier, Quest Nutrition and Barebells exemplify contrasting geographic positioning strategies. Quest Nutrition leverages its California heritage to anchor premium shelf positioning in Dubai's health food channels. Barebells occupies a position as a Swedish-formulated taste-profile optimizer calibrated for Gulf palates. Nestlé SA represents the conglomerate archetype, extending ambient distribution infrastructure across UAE retail estates. These three anchors illustrate how formulation heritage and logistics capabilities determine channel access in a compliance-intensive regulatory environment.
| Leading Market Players |
|---|
| Clif Bar & Company |
| Natural Balance Foods |
| Rise Bar |
| Barebells |
| Nutrition Inc. (Pureprotein) |
| General Mills Inc. |
| Quest Nutrition |
| Nestlé SA |
| BioNutritional Research Group, Inc (Power Crunch) |
| Others |
Value Network & Pricing Analysis
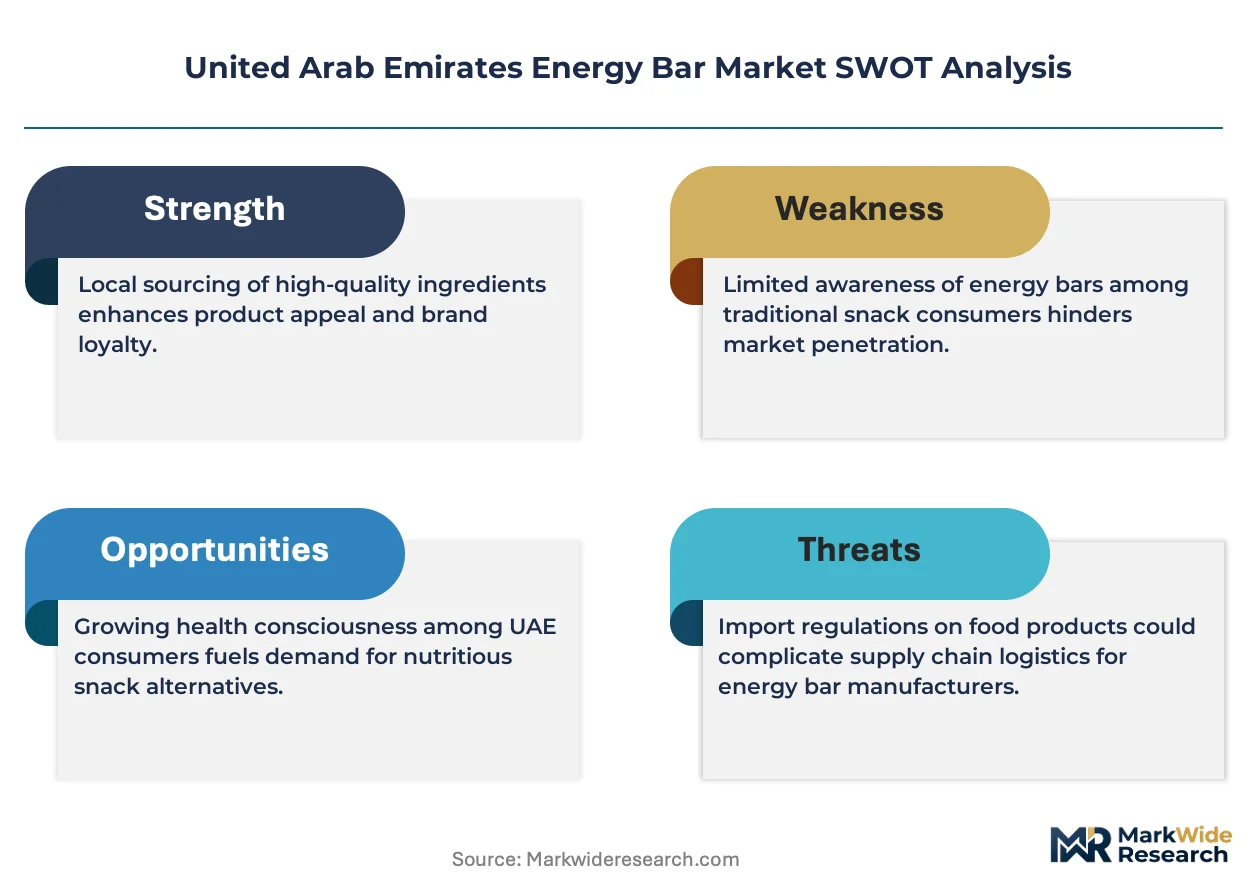
Date paste substitution for imported glucose syrups is compressing input costs for Emirates-based manufacturers while redrawing competitive boundaries between local and European-imported portfolios. This ingredient transition simultaneously erodes the cost advantage of legacy maltitol formulations and concentrates margin pressure on import-dependent brands facing FSSAI-equivalent documentation burdens.
Pricing Analysis
Input-cost pass-through from date paste localization is reshaping price architecture across protein bar tiers. Three-tier pricing structure across premium, standard, and economy levels separates gym-channel imports from supermarket domestic brands and student-segment value packs. Price differentiation hinges on halal certification grade and MOHAP compliance documentation depth. Pricing pressure stems from sugar-threshold reformulation mandates compressing legacy confectionery margins. Students in Sharjah university corridors exhibit highest price sensitivity; on-the-go professionals in Dubai Marina show least.
Supply Chain Analysis
Single-source vulnerability sits with Indian whey isolate suppliers subject to FSSAI-equivalent export documentation delays at UAE customs. Geographic supply concentration centers on India for protein concentrates, Sweden for taste-optimized formulations, and domestic Al Ain date processors for binding substrates. Raw material dependencies rest on whey isolates, chicory root fiber, and food-grade date paste. Supply chain risk manifests as regulatory restriction through MOHAP's tightening health claim validation timelines. Distribution runs through Nestlé's ambient logistics infrastructure anchoring supermarket and convenience penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE energy bar market functions as a geographic-arbitrage play where domestic date processing infrastructure undercuts European import cost structures by eliminating glucose syrup tariffs and halal certification redundancy.
For Market Incumbents: To counter Barebells' taste-profile optimization and Quest Nutrition's protein-science positioning, anchor shelf stability through backward integration into Ras Al Khaimah date paste production. Deepen MOHAP compliance dossiers ahead of sugar-tax discussions to accelerate registration timelines relative to import competitors. For New Entrants and Emerging Players: Subscription platform operators represent the most penetrable channel partner type for bypassing Union Coop and Carrefour slotting fee structures. Target Northern Emirates ADNOC petrol station retail for impulse-format buildout. Lead with chicory root fiber prebiotic positioning to exploit digestive health white space adjacent to saturated protein claims. For Investors and Strategic Acquirers: Valuations sit cheapest among regional date-processing integrators lacking branded distribution reach. Long-term viability over the mid-term projection horizon favors manufacturers with captive supply of halal-certified binding substrates. Watch GCC halal harmonization progress as the signal for multi-country registration cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Date Paste Production | Captive supply from Al Ain processors eliminates import tariff exposure and accelerates halal provenance claims. |
| MOHAP Pre-Compliance Investment | Early dossier preparation for sugar-reduction claims compresses federal registration timelines relative to reactive competitors. |
| Subscription Platform Partnership | Noon and Amazon.ae operator relationships bypass traditional retail slotting fees while concentrating buyer data for retention. |
| Chicory Root Fiber Formulation | Prebiotic positioning opens functional claims differentiation in digestive health adjacent to protein-saturated positioning. |
| Northern Emirates Distribution Buildout | ADNOC petrol station penetration captures impulse occasions along Sheikh Zayed Road transit corridors beyond Dubai retail concentration. |
Research Methodology
Bottom-up gym-channel and supermarket modeling reconciled against top-down date processor and import tracking forms the analytical core of this study. Primary interviews with MOHAP regulatory affairs officers, Union Coop category buyers, Al Ain date processing plant managers, and Dubai fitness retail operators combined with secondary validation from ESMA certification databases, UAE customs import records, and MOHAP food labeling directives. Triangulation between consumption endpoint data and supply-side production capacity ensures segmentation integrity across protein bar, meal replacement, and low-sugar format tiers.
Input-output matrix framing connects date paste production volumes, whey isolate import flows, and gym membership expansion rates to consumption forecasts across the projection horizon. Segmentation dimensions modeled include product type, ingredient sourcing geography, distribution channel temperature resilience, and customer lifestyle cohort. CAGRs derive from slope analysis of historical consumption patterns adjusted for regulatory inflection points. Forecast inputs incorporate MOHAP compliance timeline probabilities and GCC halal harmonization scenario weights.
Revisions become necessary when MOHAP sugar-tax implementation accelerates, GCC halal certification standardization stalls, or Northern Emirates retail infrastructure investment exceeds baseline assumptions. Forecasts reflect documented assumptions about date paste cost trajectories and import documentation friction persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Sweet Potato Chips Market
Snacks
Super Low Calorie Snacks Market
Snacks
India Energy Bar Market
Snacks
RTE Popcorn Market
Snacks
Europe Frozen Snacks Market
Snacks
Snack Bar Market
Snacks
Global Rice Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
North America Baked Savory Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
South America Protein Bar Market
Snacks
Dairy Protein Crisps Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Protein Bars Market
Snacks
North America Snack Bar Market
Snacks
Specialty Snacks Market