
 Fruit Jerky Market | 2026-2036
Fruit Jerky Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Jerky Market Analytics
Southeast Asian processing capacity is rewriting competitive dynamics for fruit jerky supply chains. Conagra Brands leverages its North American retail network to sustain volume leadership in mass-market distribution. Chef's Cut Real Jerky Co. competes through protein-forward positioning that bridges meat and fruit snack categories. Solely anchors its growth in ingredient-minimal formulations with transparent supply chains.
Fruit jerky consists of thin-sliced or pureed fruit that undergoes controlled dehydration at temperatures between 125°F and 160°F to achieve moisture levels below 20%, yielding a shelf-stable, chewable snack with concentrated natural sugars and preserved fiber content. Apple and mango variants dominate current production volumes due to favorable sugar-acid profiles and year-round raw material availability, while pineapple and strawberry segments command premium positioning through limited-season sourcing and higher perceived exotic value. Fitness enthusiasts represent the fastest-growing end-user channel as macro-tracking applications elevate demand for portable, whole-food carbohydrate sources with transparent nutritional labeling.
The FDA governs fruit jerky under dried fruit processing standards with specific moisture and sulfite labeling requirements, while USDA organic certification shapes premium tier market access and pricing power. EU REACH and packaging waste directives are forcing reformulation of multi-pack boxes and single-serve pouches toward recyclable or compostable substrates. Stakeholders must monitor evolving front-of-package labeling rules across multiple jurisdictions to anticipate reformulation costs and retail listing requirements.
Market Dynamics
Dehydration technology advancement and EU packaging waste mandates are compressing production economics while fragmenting competitive positioning between artisanal craft producers and industrial scale operators.
Growth Catalysts
- EU Green Deal packaging mandates:Single-use plastic bans across member states are forcing substrate innovation toward compostable films that premium brands exploit for shelf differentiation.
- Fitness-tracking application integration:Macro-logging software users seek whole-food carbohydrate sources with scannable nutritional transparency, elevating fruit jerky in gym-adjacent retail.
- Southeast Asian processing expansion:Thailand and Vietnam dehydration facilities now supply year-round mango and pineapple feedstock with shorter lead times than seasonal Latin American sources.
Market Restraints
- Input cost volatility:Organic apple concentrate prices fluctuate with Washington State and Poland harvest yields, compressing margin stability for clean-label formulators.
- Supply concentration risk:Over 60% of industrial dehydration equipment originates from Italian and German manufacturers, creating procurement bottlenecks during capacity expansion cycles.
- Technical limitation:Sulfite-free preservation methods shorten shelf life below 12 months, restricting distribution reach for additive-averse brands.
Strategic Opportunities
- German organic retail penetration:REWE and Edeka expansion of private-label fruit jerky creates white space for co-manufacturing partnerships with transparent supply chains.
- USDA organic certification arbitrage:Premium tier pricing power from organic seal adoption remains underexploited by Southeast Asian exporters serving North American natural channels.
- Solar-thermal dehydration convergence:Renewable-powered drying infrastructure in Spain and Portugal enables carbon-neutral production claims that command retail slotting fees.
Industry Challenges
- Food safety certification timelines:BRCGS and SQF audits require 8-14 month implementation cycles that delay new facility commissioning.
- Moisture calibration expertise scarcity:Precision control of 15-20% final moisture content demands skilled technicians that craft producers struggle to recruit.
- Legacy ERP integration friction:Batch-tracking software for organic chain-of-custody documentation conflicts with existing inventory management systems at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Jerky Market |
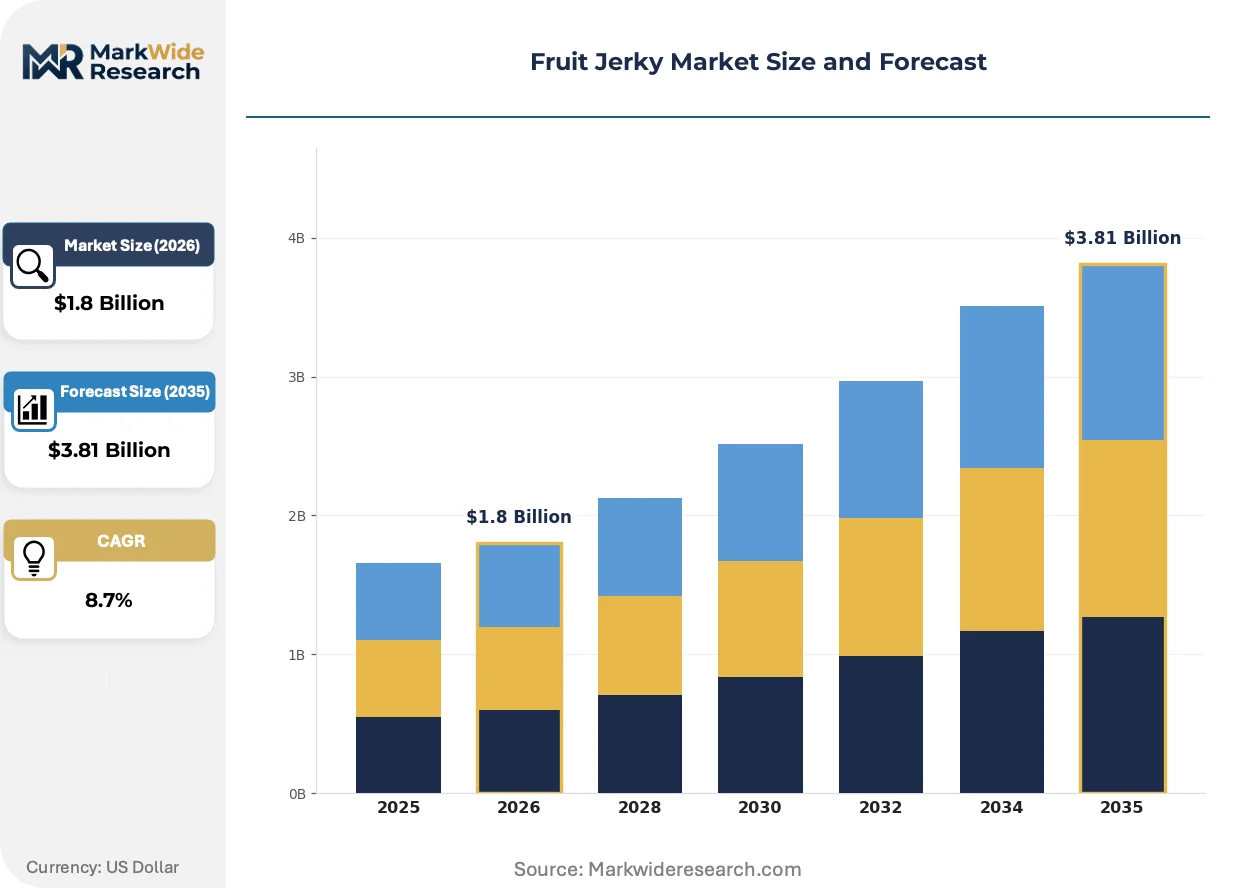
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple, Mango, Pineapple, Strawberry End User: Retail Consumers, Fitness Enthusiasts, Health Food Stores, Bulk Buyers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Farmers Markets Packaging Type: Single-Serve Pouches, Multi-Pack Boxes, Bulk Bags, Resealable Bags |
| Companies Covered | Conagra Brands, Chef's Cut Real Jerky Co., Solely, Premium Brand Holdings, Bridgford Foods Corporation, Jack Link's, Archer Provisions, Tillamook Country Smoker, Old Trapper Beef Jerky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Jerky Market Evolving Landscape
Sensor-driven process control and front-of-package labeling mandates are reconfiguring how manufacturers validate quality claims and communicate nutritional density to health-conscious buyers.
Near-infrared spectroscopy is digitizing real-time moisture monitoring during dehydration cycles. Mid-scale processors in California and Catalonia deploy these systems to reduce batch rejection rates. The technology is digitizing quality assurance documentation that retailers now require for clean-label listings.
EU front-of-package Nutri-Score mandates are compressing formulation flexibility for products with concentrated natural sugars. Manufacturers reformulate with fiber fortification and portion-size reduction to achieve favorable color ratings. German and French retail buyers now screen new listings against algorithmic nutritional profiles before shelf-space allocation.
Direct-to-gym distribution models are displacing traditional wholesale club penetration for protein-positioned fruit jerky variants. Boutique fitness chains in London, Sydney, and Toronto install refrigerated grab-and-go fixtures that bypass conventional grocery slotting negotiations. This channel pivot concentrates volume with vertical-format retail operators rather than horizontal supermarket distributors.
Fruit Jerky Market Segmentation
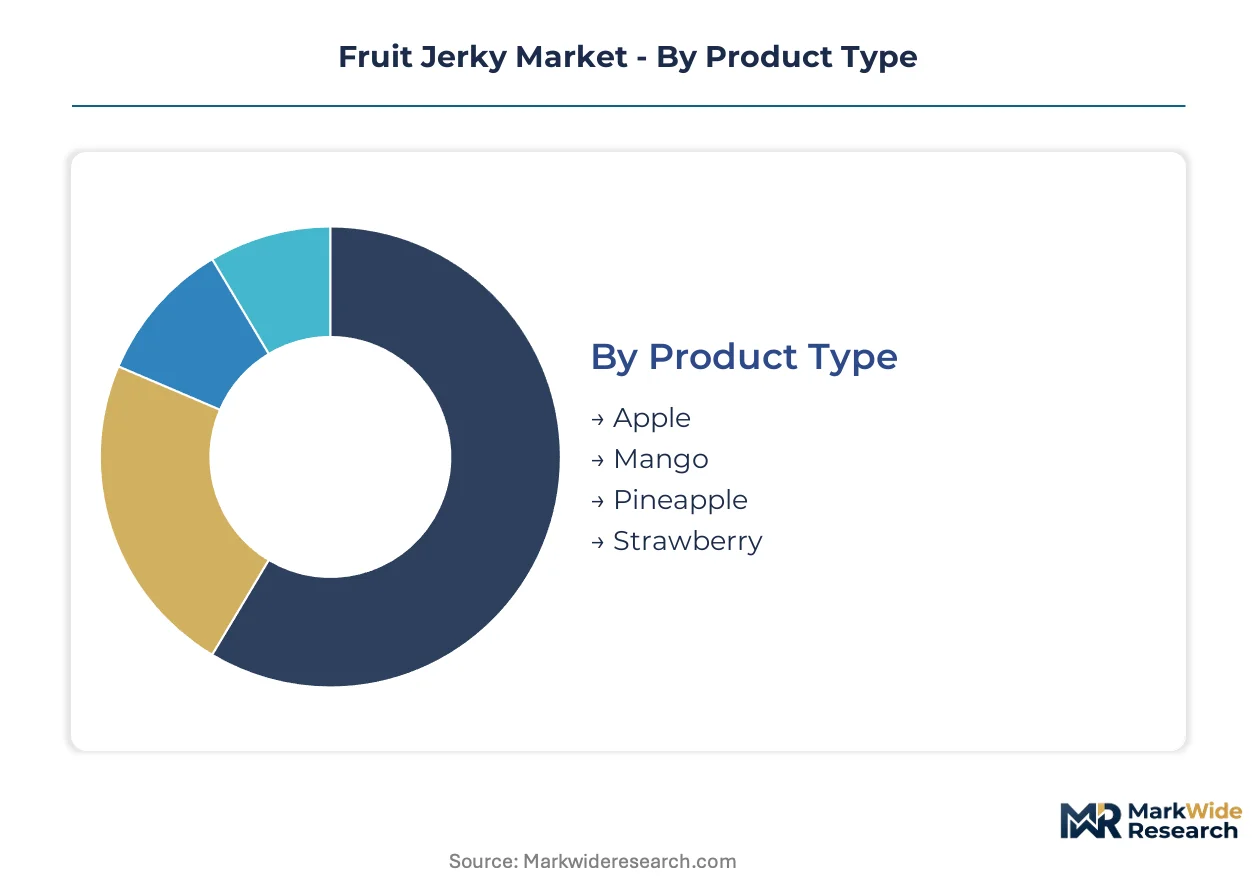
Fruit jerky manufacturers segment offerings across four dimensions that determine margin structure and channel access. Product type drives raw material sourcing strategy, while end-user targeting shapes formulation intensity and packaging format.
Product Type:
Cost tier differentiation separates commodity feedstocks from premium-positioned variants with constrained harvest windows.
- Apple:Washington State and Polish orchards supply year-round concentrate with stable brix levels. Retail consumers in German organic channels absorb volume, though concentrate price volatility compresses margin predictability for clean-label processors.
- Mango:Thailand and Vietnam dehydration facilities now process Alphonso and Kent varieties with shorter lead times than Latin American seasonal sources. Southeast Asian processing expansion is rewriting competitive dynamics for this segment.
- Pineapple:Costa Rican and Philippine supply chains serve limited-season positioning with higher perceived exotic value.
- Strawberry:California and Mexican seasonal sourcing commands premium tier placement through concentrated flavor intensity.
Apple commands the established base. The steepest expansion runs through Mango.
End User:
Application intensity varies from casual snacking to performance nutrition with divergent labeling and formulation requirements.
- Fitness Enthusiasts:Macro-tracking application users seek portable whole-food carbohydrate sources with scannable nutritional transparency. Gym-adjacent retail in London, Sydney, and Toronto displaces traditional wholesale club penetration for this channel.
- Health Food Stores:REWE and Edeka expansion of private-label SKUs creates white space for co-manufacturing partnerships with transparent supply chains.
- Retail Consumers:Mass-market distribution through Conagra Brands' North American network sustains volume leadership.
- Bulk Buyers:Foodservice and institutional procurement concentrates in co-packing arrangements with moisture-calibrated shelf stability.
Fitness Enthusiasts anchor premium pricing power. The fastest volume gains concentrate through Health Food Stores.
Distribution Channel:
Customer type determines fulfillment infrastructure requirements from cold-chain compliance to direct-to-gym logistics.
- Online Retailers:Subscription models and pantry-loading behavior concentrate in Amazon and Thrive Market with front-of-package labeling transparency requirements.
- Supermarkets:REWE, Edeka, and Kroger slotting negotiations demand BRCGS and SQF certification with 8-14 month implementation timelines.
- Specialty Stores:Independent natural grocers in California and Catalonia deploy near-infrared spectroscopy documentation for clean-label listings.
- Farmers Markets:Direct producer-to-consumer channels bypass conventional distribution margin extraction with sulfite-free preservation constraints.
Supermarkets command the established base. The steepest expansion trajectory runs through Online Retailers.
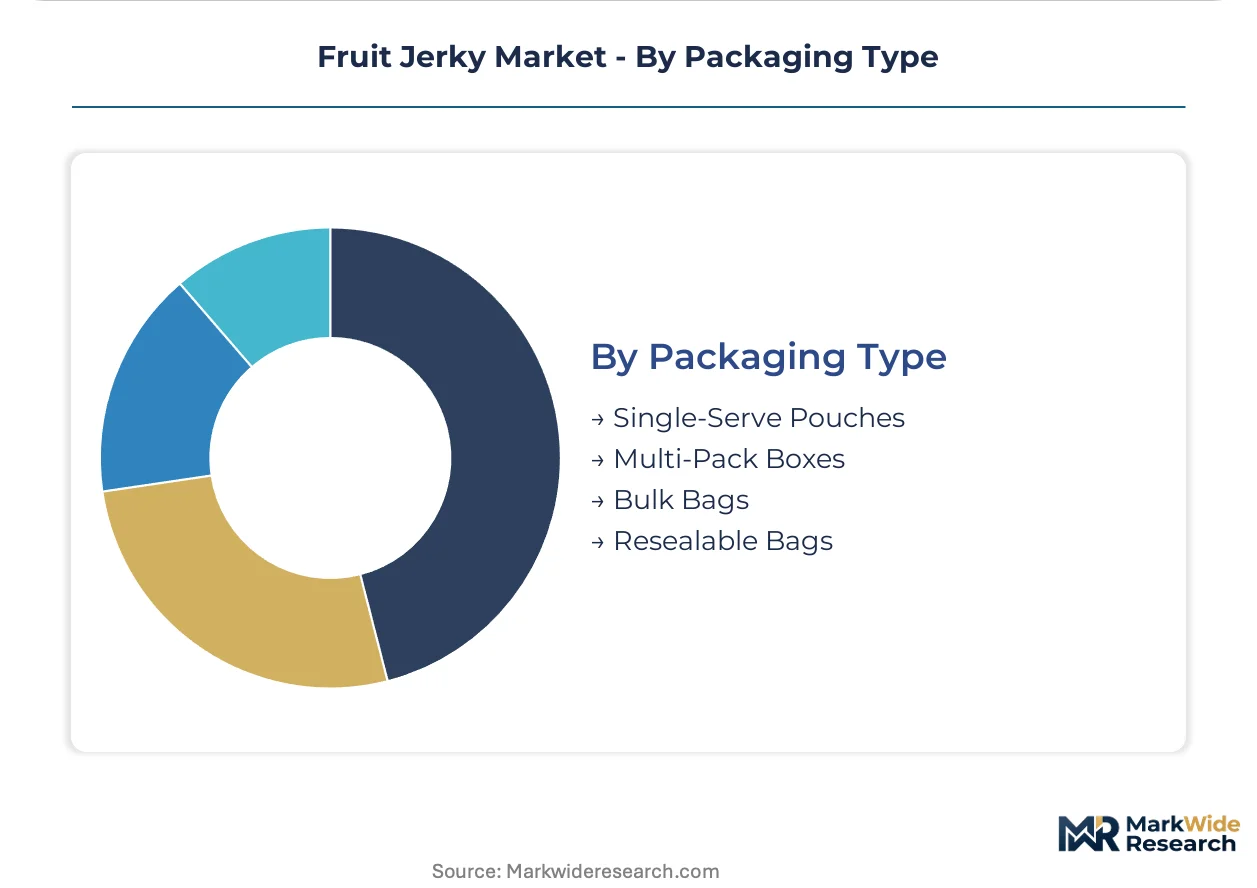
Packaging Type:
Volume scale and sustainability compliance separate single-unit convenience from institutional formats.
- Single-Serve Pouches:EU Green Deal single-use plastic bans force substrate innovation toward compostable films that premium brands exploit for shelf differentiation.
- Multi-Pack Boxes:EU REACH and packaging waste directives are forcing reformulation toward recyclable or compostable substrates.
- Bulk Bags:Foodservice and institutional buyers prioritize moisture-barrier performance over retail presentation.
- Resealable Bags:Zip-lock and press-seal formats target family-size consumption with extended shelf-life requirements.
Single-Serve Pouches anchor premium tier placement. The fastest volume gains concentrate through Multi-Pack Boxes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dehydration capacity clusters in specific countries with favorable fruit-growing climates and processing infrastructure. Manufacturers locate near raw material sources to minimize transport losses of moisture-sensitive feedstocks. Regulatory frameworks on both sides of the Atlantic shape investment decisions for new facility commissioning.
United States
Fitness-tracking application users drive demand for portable whole-food carbohydrate sources with transparent labeling. FDA dried fruit processing standards govern moisture content and sulfite disclosure requirements. California processors deploy near-infrared spectroscopy systems to reduce batch rejection rates for clean-label retail listings.
Germany
REWE and Edeka expansion of private-label fruit jerky SKUs creates co-manufacturing opportunities for transparent supply chains. EU Green Deal packaging mandates force substrate innovation toward compostable films. Bavarian organic retail infrastructure supports premium dried-fruit product placement through dedicated shelf-space allocation.
Thailand
Alphonso and Kent mango varieties supply year-round feedstock with shorter lead times than Latin American seasonal sources. Thai national food safety regulators enforce GMP certification for export-oriented dehydration facilities. Bangkok-adjacent processing zones now compete directly with Vietnamese facilities for North American natural channel contracts.
Spain
Solar-thermal dehydration infrastructure enables carbon-neutral production claims that command retail slotting fees. EU REACH directives force reformulation of multi-pack boxes toward recyclable substrates. Catalonian mid-scale processors integrate batch-tracking software for organic chain-of-custody documentation required by German buyers.
Vietnam
Pineapple dehydration facilities process Costa Rican and Philippine supply chains for limited-season premium positioning. Vietnamese Ministry of Industry and Trade export promotion programs support facility expansion for North American natural channel access. Ho Chi Minh City industrial zones attract investment from brands seeking shorter lead times than Thai competitors.
Fruit Jerky Market Competitive Landscape
Legacy packaged food conglomerates and ingredient-minimal specialists split the market between mass-market volume and premium-tier positioning. Consolidation pressure operates at the mass-market tier while fragmentation persists among craft producers with regional sourcing stories. Two strategic archetypes dominate: diversified CPG portfolios leveraging retail network density, and clean-label purists competing through supply chain transparency. Capacity expansion and substrate innovation for EU packaging compliance represent the dominant competitive moves.
Within the diversified CPG tier, Conagra Brands leverages North American retail network density to sustain volume leadership in mass-market distribution. Chef's Cut Real Jerky Co. and Solely occupy contrasting positions on the protein-forward versus ingredient-minimal spectrum. These three companies exemplify how strategic archetype selection determines channel access and margin structure in a market bifurcating between convenience-store penetration and natural-grocery premiumization.
| Leading Market Players |
|---|
| Conagra Brands |
| Chef's Cut Real Jerky Co. |
| Solely |
| Premium Brand Holdings |
| Bridgford Foods Corporation |
| Jack Link's |
| Archer Provisions |
| Tillamook Country Smoker |
| Old Trapper Beef Jerky |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container rates from Bangkok and Ho Chi Minh City to Long Beach compress margin structures for Southeast Asian processors while amplifying price differentiation between EU-compliant organic tiers and conventional mass-market offerings. Washington State apple concentrate volatility feeds directly into clean-label processor margins, forcing tier separation between sulfite-free premium positioning and additive-tolerant commodity supply.
Pricing Analysis
EU Green Deal packaging mandates dictate the pricing tier structure by forcing substrate innovation costs onto premium-positioned brands. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified variants from conventional clean-label and mass-market commodity offerings. Price differentiation hinges on certification grade and geographic delivery cost, with organic seal adoption commanding retail slotting premiums. Cost compression in the standard tier is intensifying because Washington State and Polish apple concentrate harvest volatility squeezes mid-scale processors without captive orchards. Bulk buyers and foodservice procurement show highest price sensitivity, while fitness enthusiasts and German organic retail consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Organic apple concentrate from Washington State and Polish orchards, Alphonso and Kent mango varieties from Thailand and Vietnam, and Costa Rican pineapple feedstock anchor upstream material flows. Raw material dependencies center on seasonal harvest timing, dehydration equipment from Italian and German manufacturers, and compostable film substrates for EU compliance. Single-source vulnerability concentrates in industrial dehydration equipment procurement, where over 60% of capacity expansion hardware originates from European suppliers. Distribution runs through supermarket slotting negotiations with BRCGS certification requirements, direct-to-gym vertical channels bypassing conventional wholesale, and online subscription models with front-of-package transparency demands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as fitness-tracking application integration and EU packaging compliance create divergent capability requirements that favor specialized players over consolidated portfolios. Macro-logging software users and German organic retail expansion generate niche demand pockets resistant to mass-market absorption.
For Market Incumbents: Insulate premium positioning through backward integration into Washington State and Polish organic orchards to neutralize concentrate price volatility threatening clean-label margins. Capture co-manufacturing partnerships with REWE and Edeka private-label expansion to secure volume buffers against direct-to-gym channel displacement. Certification investment in BRCGS and SQF audits locks out mid-scale craft competitors facing 8-14 month implementation timelines. For New Entrants and Emerging Players: Pursue solar-thermal dehydration infrastructure in Spain and Portugal to anchor carbon-neutral production claims that command retail slotting fees unavailable to conventional processors. Target German organic retail penetration as the most penetrable geography, where Bavarian shelf-space allocation practices favor transparent supply chain documentation. Deploy direct-to-gym distribution models in London, Sydney, and Toronto to bypass supermarket slotting negotiations entirely. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified CPG parent companies seeking to divest non-core snack assets amid portfolio rationalization pressures. Mid-scale processors with established organic chain-of-custody documentation and near-infrared spectroscopy quality systems present viable acquisition archetypes for premium-tier rollup strategies. Signal to watch: REWE and Edeka private-label SKU expansion rates as inflection indicator for co-manufacturing partnership availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Orchards | Captive Washington State and Polish apple supply neutralizes concentrate price volatility for clean-label processors. |
| Solar-Thermal Dehydration Infrastructure | Spain and Portugal facilities enable carbon-neutral claims commanding premium retail slotting fees. |
| Direct-to-Gym Distribution Expansion | Boutique fitness chains in London, Sydney, and Toronto bypass conventional grocery slotting negotiations. |
| Compostable Film Substrate Adoption | EU Green Deal compliance creates shelf differentiation for premium brands against plastic-dependent competitors. |
| Near-Infrared Spectroscopy Deployment | Real-time moisture monitoring reduces batch rejection rates required for clean-label retail listings. |
Research Methodology
Desk research of trade customs records, Nielsen retail audit data, and EU regulatory filings preceded structured interviews with dehydration facility operators, organic certification auditors, supermarket category buyers, and fitness chain procurement managers. Primary fieldwork with California and Catalonian mid-scale processors validated secondary data on near-infrared spectroscopy adoption rates. Bottom-up volume triangulation across product type and end-user segments converged with top-down market sizing from trade flow analysis.
Assumptions held fixed include EU Green Deal packaging mandate implementation timelines and FDA sulfite labeling requirements, while organic certification adoption rates and direct-to-gym channel penetration were varied across sensitivity scenarios. Segmentation modeling incorporated product type, end-user application intensity, distribution channel format, and packaging sustainability tier. CAGRs derived from regression analysis against historical volume patterns with adjustment for Southeast Asian processing capacity expansion. Industry-specific inputs included Washington State apple harvest yield correlations and German organic retail shelf-space allocation trends.
Macroeconomic conditions sit as an overlay; deviation in trans-Pacific freight rates, organic input commodity indices, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding dehydration technology diffusion and fitness application user growth. Cross-checking against customs export data from Thai and Vietnamese national trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Vegetable Chips Market
Snacks
US Potato Chips Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
China Snack Bar Market
Snacks
Granola Bars Market
Snacks
Salty Puffed Snacks Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Snack Subscription Market
Snacks
Organic Snack Food Market
Snacks
Corn Chips Market
Snacks
Low Sodium Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Organic Chips Market
Snacks
Low Fat Granola Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Nuts and Seeds (Savory Snacks) Market