
 United States Popcorn Market | 2026-2036
United States Popcorn Market Size, Share, and Industry Trends Forecast 2026-2036
United States Popcorn Market Outlook
Single-serve microwave pouch bundles paired with streaming service subscriptions is rebalancing how households stock pantry items. Conagra Brands leverages its Orville Redenbacher portfolio to sustain dominance in microwave segments across mass retail. PepsiCo competes through Frito-Lay's shelf-stable popcorn lines that anchor convenience store placements. Quinn Foods differentiates with organic, non-GMO ingredient transparency that occupies the natural channel premium tier.
Popcorn comprises Zea mays everta kernels that expand to twenty to forty times original size when heated under pressure to approximately 180°C, yielding a low-calorie, high-fiber snack substrate for flavor coating. The product serves commercial foodservice and retail channels as a scalable, margin-friendly alternative to confectionery. Caramel and kettle corn flavor profiles lead household repeat purchases, while bag packaging dominates volume due to material efficiency and shelf visibility. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models reshape replenishment behavior.
The FDA enforces Nutrition Facts labeling and allergen declarations for packaged popcorn, while USDA organic certification governs premium tier eligibility. State-level cottage food laws in Texas and California additionally shape small-batch producer market access. Stakeholders must monitor how FDA sodium reduction guidance and evolving state packaging waste regulations will reshape formulation and material choices.
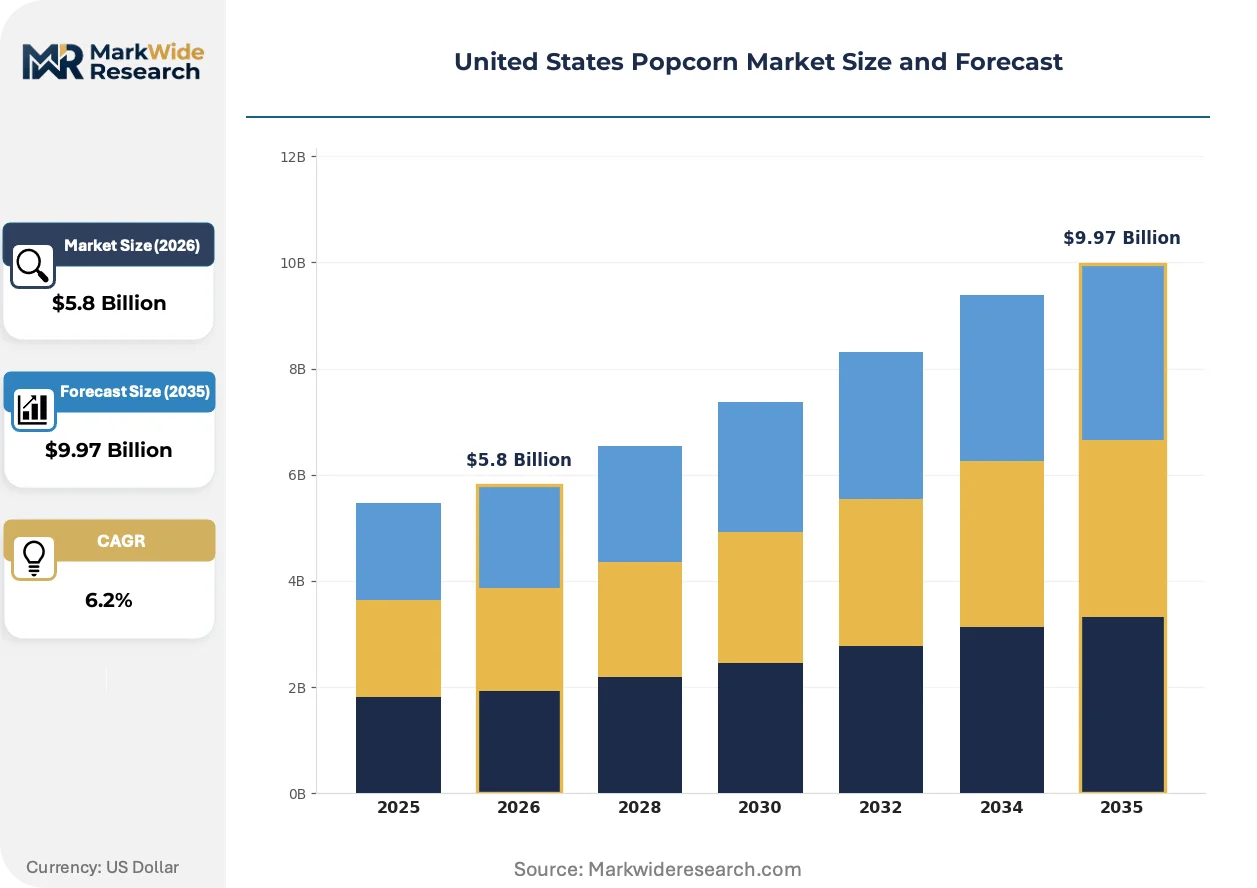
Market Dynamics
The US popcorn market is experiencing structural compression from streaming service bundling, which is displacing theater-centric consumption patterns and forcing manufacturers to rebalance channel allocation between multiplex concessions and direct-to-home fulfillment.
Growth Catalysts
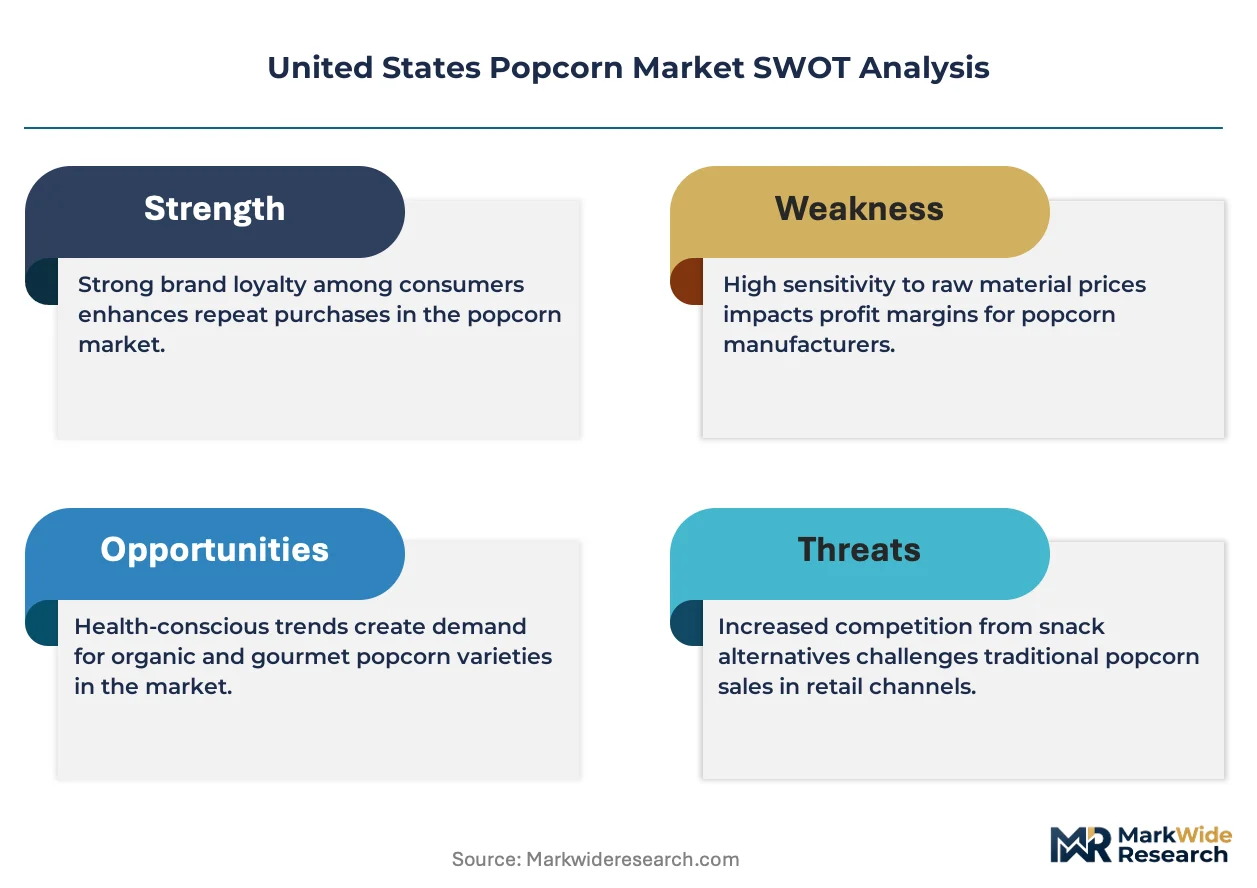
- USDA Organic Certification:Premium tier eligibility under this framework is expanding shelf space allocation in natural retail channels and commanding price premiums that subsidize conventional line margins.
- Texas Multiplex Density:Theater chain expansion across Dallas-Fort Worth and Houston corridors is anchoring bulk kernel procurement contracts and stabilizing commodity price exposure for processors.
- Microwave Pouch Innovation:Susceptor film technology is reducing unpopped kernel rates below 4% and extending product tolerance to humidity variation during transit.
Market Restraints
- Midwest Drought Exposure:Nebraska and Iowa kernel sourcing concentration creates yield volatility risk that processors hedge through forward contracting at 12-18 month horizons.
- FDA Sodium Reduction Guidance:Draft targets for savory snack categories are forcing reformulation timelines that compress R&D bandwidth and accelerate ingredient substitution costs.
- Confectionery Substitution:Chocolate-coated alternatives and savory puffed snacks are capturing impulse purchase occasions at convenience retail, eroding grab-and-go popcorn velocity.
Strategic Opportunities
- California Specialty Retail:Los Angeles and San Francisco boutique grocers are incubating small-batch heirloom varietals that command 3-4x commodity pricing and build brand equity for upstream acquisition.
- Direct-to-Consumer Subscriptions:Replenishment algorithms tied to streaming viewership data are enabling predictive inventory positioning and reducing customer acquisition costs versus traditional retail slotting.
- State Cottage Food Law Liberalization:Texas and California home-kitchen exemptions are lowering barrier-to-entry for artisan producers who subsequently graduate to co-packer relationships and regional distribution.
Industry Challenges
- Flavor Chemist Talent Scarcity:Clean-label mandates are outstripping supply of formulation specialists capable of delivering shelf-stable taste profiles without artificial additives or excessive sodium.
- Compostable Packaging Certification:ASTM D6400 and BPI verification timelines for bag films are extending 14-18 months, delaying sustainability claims and risking state-level extended producer responsibility penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Popcorn Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Cheese, Caramel, Kettle Corn Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops End User: Household, Cinema, Snack Bars, Restaurants Packaging Type: Bag, Cup, Tub, Box |
| Companies Covered | Conagra Brands, PepsiCo, The Hershey Company, Our Home, Grupo Bimbo, Weaver Popcorn, American Pop Corn Company, Quinn Foods, Eagle Family Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Popcorn Market Strategic Shifts
Flavor coating technology and packaging substrate evolution are converging to redefine product differentiation, while regulatory pressure on sodium and material waste is compressing formulation flexibility and accelerating compliance investment cycles.
Air-popped expansion systems utilizing radiant heat transfer are expanding into commercial foodservice installations, replacing oil-based kettle methods in stadium and theater environments. Aramark and Compass Group concession divisions are piloting these units across Texas and California venues to reduce ventilation infrastructure requirements and simplify cleaning protocols. This thermal approach is expanding into segments previously dominated by fried alternatives, compressing the addressable market for traditional oil-popped equipment.
FDA updated Nutrition Facts labeling requirements for packaged foods are mandating added sugar disclosure and revising serving size definitions to reflect actual consumption patterns. Popcorn manufacturers must reformulate caramel and kettle corn varieties or accept degraded nutritional panel positioning that risks retail delisting. Premium organic lines are responding fastest, leveraging existing ingredient transparency protocols to maintain shelf placement during the transition window.
Household replenishment behavior is fragmenting across pantry-stocking and impulse channels, with streaming bundle subscribers consolidating purchases into scheduled delivery windows while convenience retail captures unplanned snacking occasions. Mass retailers are responding with hybrid fulfillment models that merge subscription pricing with in-store pickup options. This bifurcation is most visible in California, where same-day delivery density supports pantry consolidation while Texas highway retail maintains high-margin single-serve velocity.
United States Popcorn Market Segmentation
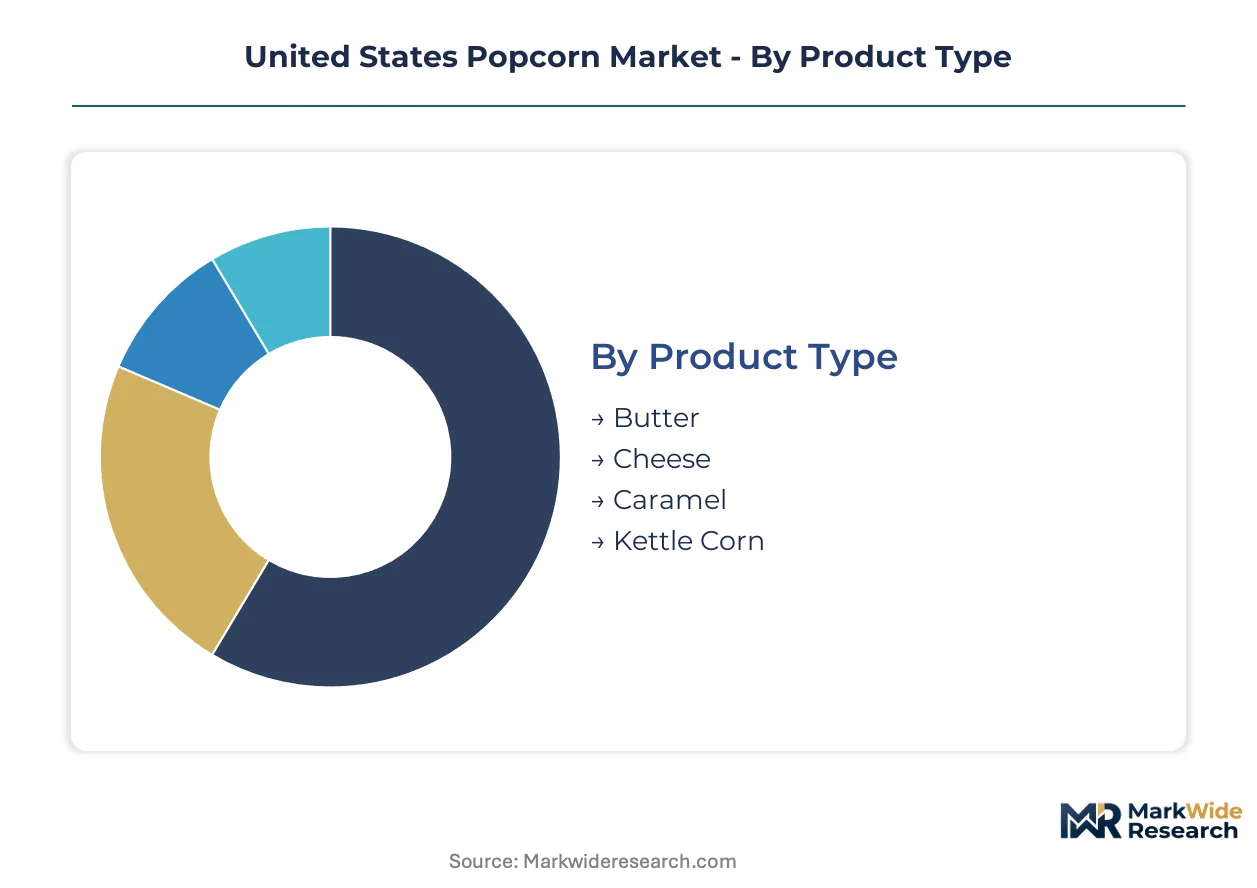
Popcorn segmentation in the United States reflects divergent consumption rituals across theatrical, home entertainment, and foodservice occasions. Manufacturers calibrate formulation density, salt load, and packaging format to match channel-specific margin structures and replenishment cadences.
Product Type:
Standardization dominates commodity tiers while flavor complexity escalates toward premium positioning.
- Butter:Salt and butter oil coating applied to expanded kernels yields the baseline flavor profile for multiplex concessions and microwave retail. Texas theater chains anchor volume procurement for this segment, though sodium reduction guidance from FDA is compressing reformulation timelines for legacy recipes.
- Caramel:Sugar syrup coating creates a shelf-stable confectionery hybrid that commands price premiums in gift and seasonal channels. California specialty retail incubates small-batch artisan caramel varieties that subsequently graduate to regional distribution through co-packer relationships.
- Cheese:Powdered cheese seasoning delivers savory intensity for convenience store impulse placement. Demand concentrates in single-serve formats for highway retail velocity across the Southwest corridor.
- Kettle Corn:Batch-cooked sugar and salt coating produces irregular kernel texture prized in fair and festival contexts. Seasonal production patterns create capacity utilization challenges for dedicated equipment operators.
Most installed capacity flows through Butter. Expansion is steepest in Caramel.
Distribution Channel:
Channel selection determines packaging format, pricing architecture, and promotional cadence for brand portfolios.
- Supermarkets:Mass retail shelf space allocation favors multi-count microwave pouch bundles and family-size ready-to-eat bags. Slotting fee structures and promotional calendar density compress net margins for emerging brands attempting national distribution.
- Online Retailers:Direct-to-consumer subscription models leverage streaming viewership data for predictive replenishment algorithms. This channel is gaining share fastest as pantry consolidation behavior accelerates among suburban households.
- Convenience Stores:Single-serve impulse placement requires shelf-stable packaging and high-visibility point-of-sale displays. Grab-and-go velocity faces erosion from chocolate-coated alternatives and savory puffed snacks.
- Specialty Shops:Curated assortment of heirloom varietals and organic-certified lines targets premium household segments. Los Angeles and San Francisco boutique grocers incubate regional brands prior to broader retail expansion.
Volume concentrates in Supermarkets. Margin expansion is most pronounced in Specialty Shops.
End User:
User context dictates kernel specification, popping method, and flavor intensity calibration.
- Household:At-home consumption spans microwave pouch preparation and ready-to-eat bag opening, with streaming bundle subscriptions reshaping pantry stocking behavior toward scheduled delivery windows.
- Cinema:Theater concession operations require bulk kernel procurement contracts and oil-based popping systems optimized for throughput during peak attendance windows.
- Snack Bars:Limited-service foodservice locations prioritize equipment footprint reduction and labor minimization through pre-popped bag or cup formats.
- Restaurants:Full-service establishments incorporate popcorn as bar snack or amuse-bouche, demanding portion-controlled presentation and flavor differentiation from retail equivalents.
Kernel volume flows predominantly to Cinema. Application innovation is accelerating fastest in Restaurants.
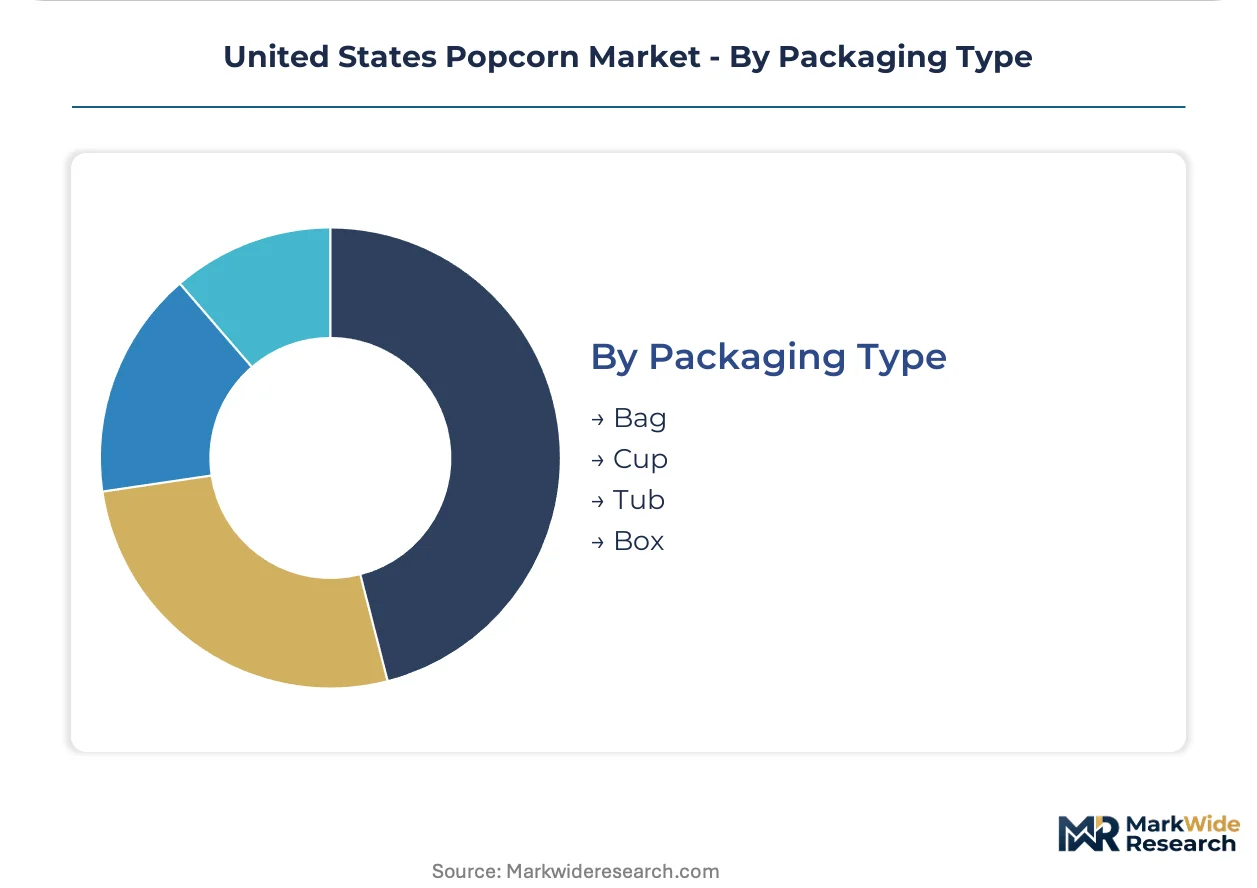
Packaging Type:
Material selection balances shelf visibility, moisture protection, and waste regulation compliance.
- Bag:Flexible film construction dominates retail volume through material efficiency and vertical shelf orientation. ASTM D6400 and BPI certification timelines for compostable alternatives are extending sustainability claim availability.
- Cup:Rigid paperboard format serves immediate consumption occasions in theater and stadium environments where hand-held portability is paramount.
- Tub:Large-format rigid packaging enables sharing occasions and refills in concession contexts, though storage footprint limits retail penetration.
- Box:Corrugated or paperboard secondary packaging supports gift sets and multi-unit retail bundles, particularly in seasonal caramel and kettle corn assortments.
Production throughput centers on Bag. Regulatory pressure is intensifying most acutely for this format.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Popcorn cultivation and processing scaled commercially in the American Midwest during the early twentieth century, with Nebraska and Iowa establishing the kernel supply foundation that still anchors national production. Theater concession culture then concentrated demand in coastal metropolitan corridors.
California
Los Angeles and San Francisco boutique grocers incubate small-batch heirloom varietals that command premium pricing multiples over commodity kernels. FDA sodium reduction guidance pressures reformulation timelines for caramel and kettle corn varieties distributed through these channels. Specialty retail density in the Bay Area supports organic certification premiums that subsidize conventional line margins.
Texas
Dallas-Fort Worth and Houston multiplex expansion anchors bulk kernel procurement contracts for theater concession operators. State cottage food law liberalization lowers barrier-to-entry for artisan producers who graduate to co-packer relationships. Highway retail across the Southwest corridor maintains high-margin single-serve velocity for cheese-flavored impulse formats.
Nebraska
Kernel sourcing concentration creates yield volatility exposure that processors hedge through forward contracting at extended horizons. USDA crop insurance programs and drought relief frameworks shape planting decisions for Zea mays everta cultivation. Processing facilities in the Platte River valley supply national microwave and ready-to-eat bag manufacturers.
Iowa
Historic popcorn breeding programs established varietal libraries that seed companies license for trait development. EPA water quality regulations govern runoff management from intensive row-crop production systems. Cedar Rapids and Des Moines corridor elevators handle export-bound kernel shipments to international markets.
Illinois
Chicago metropolitan distribution hubs coordinate rail and trucking logistics for Midwest kernel aggregation. Illinois Department of Agriculture grading standards influence quality premiums paid to growers across neighboring states. Foodservice equipment manufacturers in the region supply air-popped expansion systems to stadium and theater concession operators.
United States Popcorn Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and channel positioning, with organic and natural-tier specialists commanding price multiples that subsidize conventional microwave and ready-to-eat portfolios. The vendor base clusters around three strategic archetypes: diversified packaged food conglomerates with microwave heritage brands, salty snack specialists leveraging convenience store distribution density, and clean-label insurgents occupying natural channel shelf space. Competitive moves concentrate on portfolio diversification into heirloom and specialty varietals, plus geographic expansion through direct-to-consumer subscription fulfillment infrastructure.
Within the diversified conglomerate tier, Conagra Brands and PepsiCo exemplify scale-driven positioning across mass retail and foodservice channels. Quinn Foods occupies the premium-tier vector with organic, non-GMO ingredient transparency protocols. These three anchors illustrate how competitive positioning splits across commodity volume, convenience velocity, and natural-channel premium extraction strategies.
| Leading Market Players |
|---|
| Conagra Brands |
| PepsiCo |
| The Hershey Company |
| Our Home |
| Grupo Bimbo |
| Weaver Popcorn |
| American Pop Corn Company |
| Quinn Foods |
| Eagle Family Foods |
| Others |
Value Chain & Pricing Dynamics
Organic-non-GMO tier separation from conventional microwave lines manifests in both shelf price multiples and kernel sourcing protocols, with USDA certification gating access to natural channel placement that commands margin structures unavailable to commodity processors. This bifurcation concentrates procurement leverage among handlers with certified acreage relationships while forcing conventional brands into volume-driven promotional calendars that erode net realized prices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with USDA organic certification and heirloom varietal status driving tier placement alongside brand heritage and channel positioning. Price differentiation reflects ingredient transparency grade and packaging sustainability credentials rather than kernel quality alone. Cost compression in conventional microwave tiers is intensifying because of slotting fee escalation at mass retail. Household subscribers to streaming bundle replenishment services exhibit lowest price sensitivity, while convenience store impulse buyers demonstrate highest elasticity.
Supply Chain Analysis
USDA organic certification and FDA facility registration requirements gate upstream supplier eligibility, compressing the qualified handler base for premium tier manufacturers. Kernel supply concentrates in Nebraska and Iowa cultivation corridors, with processing capacity anchored in the Platte River valley and Cedar Rapids corridor. The chain draws from hybrid seed development programs, agricultural chemical inputs, and flexible film packaging substrates. Single-source vulnerability runs through drought-exposed Midwest acreage concentration. Distribution runs through Chicago metropolitan rail-truck intermodal hubs coordinating national fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States popcorn market functions as a stable compounder, with streaming-integrated household replenishment behavior generating predictable revenue basins that smooth cyclical theatrical exposure.
For Market Incumbents: Acquire direct-to-consumer subscription infrastructure to capture streaming-viewership data for predictive replenishment algorithms. Secure forward contracting positions on Nebraska and Iowa kernel harvests at 18-month horizons to stabilize commodity input exposure. FDA sodium reduction guidance threatens legacy butter flavor formulations; accelerate clean-label R&D recruitment to defend shelf placement during nutritional panel transitions. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route for artisan producers graduating from Texas and California cottage food law exemptions. White-space concentration sits in heirloom varietal development for Los Angeles and San Francisco specialty retail incubation. Target co-packer relationship graduation pathways rather than owned manufacturing capacity deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with clean-label insurgents possessing established natural channel shelf placement and organic certification infrastructure already amortized. Five-to-ten-year viability favors brands with streaming data integration capabilities and compostable packaging certification timelines completed. Monitor FDA final sodium reduction rule publication as inflection signal for reformulation cost exposure among legacy savory flavor portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Streaming viewership data integration enables predictive inventory positioning ahead of theatrical release windows. |
| Heirloom Varietal Development Program | California specialty retail incubation commands 3-4x commodity pricing multiples for differentiated kernel genetics. |
| Compostable Packaging Certification | ASTM D6400 and BPI verification defends against California extended producer responsibility penalty exposure. |
| Backward Integration into Kernel Sourcing | Nebraska and Iowa forward contracting stabilizes input cost volatility for microwave pouch manufacturing. |
| Clean-Label Flavor R&D Investment | FDA sodium reduction compliance preserves retail shelf placement for legacy butter and cheese product lines. |
Study Parameters
Bottom-up household consumption modeling reconciled against top-down kernel production tracking forms the analytical core of this study. Primary interviews with brand managers at diversified packaged food conglomerates, category buyers at mass retail and specialty grocers, supply planners at kernel processing facilities, and channel sales heads at convenience store distributors generated demand-side intelligence. Secondary validation drew from USDA crop production reports, FDA food facility registration databases, Nielsen retail audit data, and state-level cottage food law regulatory filings. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of multiplex attendance patterns, microwave pouch shipment data, and streaming subscription growth rates established baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, distribution channel, end-user occasion, and packaging format dimensions, with kernel grade tier and organic certification status as additional industry-specific variables. CAGRs were derived from regression-adjusted trend extrapolation incorporating regulatory compliance cost schedules and channel shift elasticity parameters. Forecast inputs included drought probability indices for Midwest growing regions and FDA guidance finalization timelines.
The model assumes a particular technology adoption path; alternative pathways for air-popped expansion systems displacing oil-based kettle methods in theater and stadium environments would alter the outlook for equipment manufacturers and flavor coating formulations. Forecasts reflect assumptions regarding streaming bundle persistence, sodium reduction rule stringency, and compostable packaging cost parity achievement. A model refresh is warranted upon material change in FDA final rule publication or extended producer responsibility implementation schedules in California and Texas.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Snacks Food Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Snack Food Packaging Market
Snacks
UAE Cereal Bar Market
Snacks
China Snack Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
North America Extruded Snack Food Market
Snacks
Low Calorie Snack Foods Market
Snacks
Seaweed Snacks Market
Snacks
Mushroom Based Jerky Market
Snacks
Low Calorie Biscuits Market
Snacks
North America Baked Chips Market
Snacks
Edible Flakes Market
Snacks
Nutritional Bar Market
Snacks
Nachos Market