
 China Snack Bar Market | 2026-2036
China Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
China Snack Bar Market Outlook
Subscription-based replenishment services is hardening as a core revenue layer for snack bar brands seeking recurring consumer lock-in. Mars Incorporated leverages its established logistics network to sustain direct-to-home delivery cadences in tier-one cities. Nestlé SA anchors its portfolio through specialized nutrition positioning that competes with local functional food entrants. Mondelez International differentiates via portion-controlled formats that dominate convenience store shelf space.
A snack bar denotes a shelf-stable, individually wrapped confection or cereal-based food item typically comprising grains, proteins, sweeteners, and binding agents, formed through extrusion or cold-pressing and baked or enrobed to achieve a moisture content below 10 percent for ambient stability. Granola bars remain the volume foundation while protein bars capture the fastest expansion as gym culture penetrates China's middle-class consumers. Online retail channels increasingly control margin pools through live-streaming commerce and algorithmic personalization that reorders purchase patterns away from traditional supermarkets.
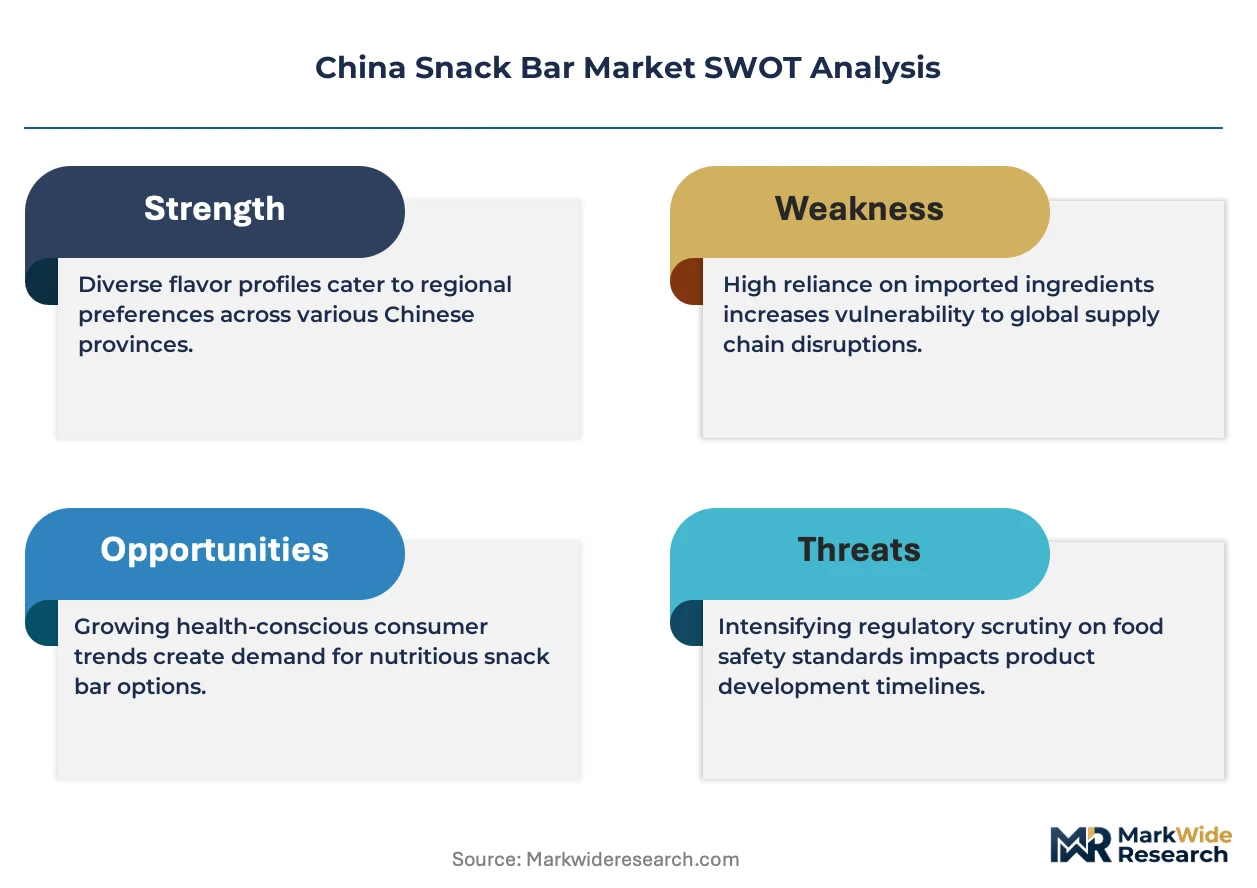
SAMR enforces GB standards for food labeling and additive limits that dictate permissible health claims on snack bar packaging. The National Health Commission's dietary guidelines and CSRC disclosure requirements for listed food companies jointly shape how brands communicate nutritional value and invest in reformulation. Stakeholders must monitor whether China's evolving functional food classification rules will create separate compliance pathways for protein-fortified versus conventional cereal bars.
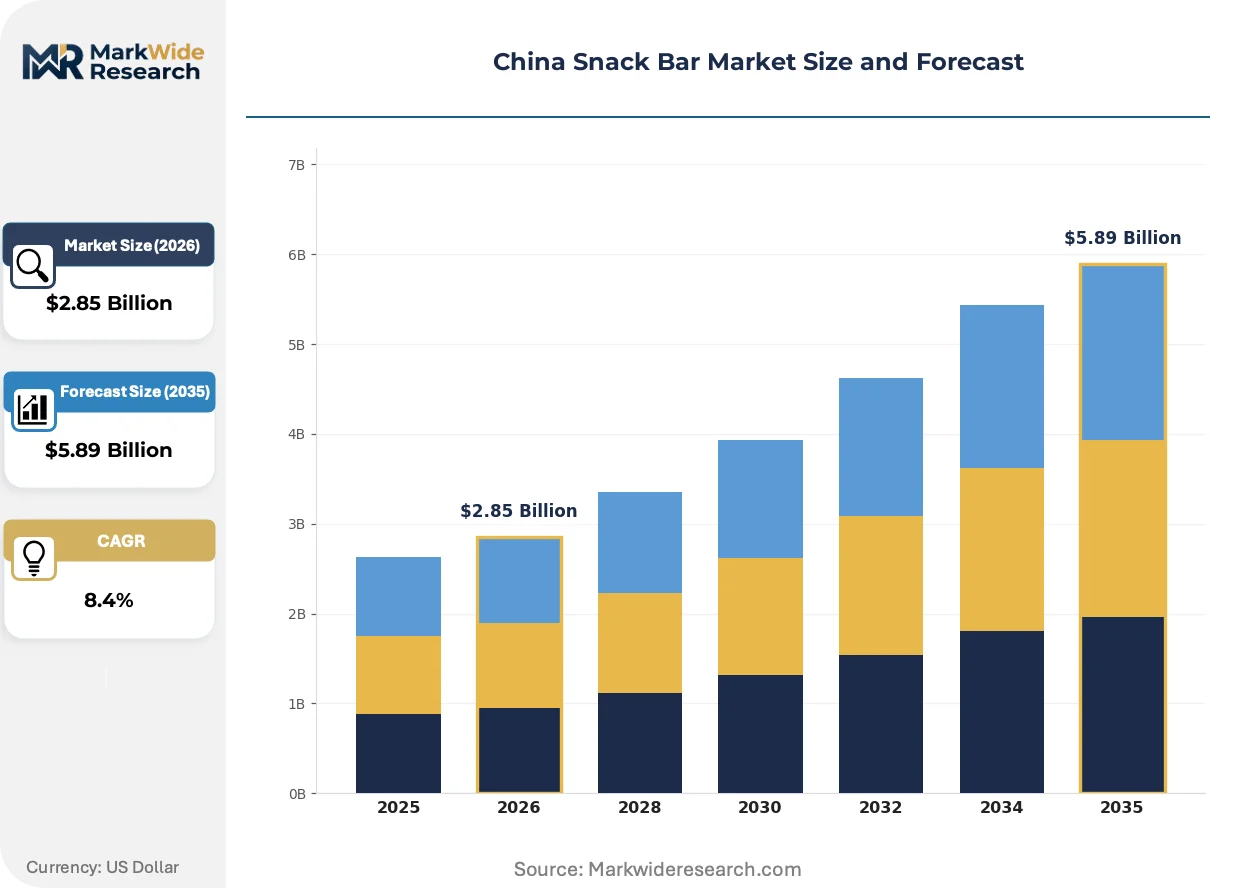
Market Dynamics
China's snack bar market is being fundamentally reshaped by SAMR's evolving GB standards for functional food classification, which are compressing formulation flexibility while forcing brands to choose between protein-fortified and conventional cereal pathways before 2030.
Growth Catalysts
- Front-of-pack labeling mandates:SAMR's sugar-reduction disclosure rules are accelerating reformulation investments among domestic manufacturers seeking health-premium positioning in first-tier cities.
- Gym culture penetration:Middle-class consumers in Shanghai and Beijing are adopting protein bars as meal replacements, creating pull-through demand for specialized nutrition formats.
- Live-streaming commerce infrastructure:Algorithmic personalization on Douyin and Xiaohongshu is reordering purchase patterns away from traditional supermarkets toward direct brand-consumer relationships.
Market Restraints
- Whey protein import dependency:Domestic brands face input cost volatility tied to Australian and New Zealand dairy supply chains subject to trade friction.
- GB additive limit strictures:SAMR's tightening enforcement on binding agents and shelf-life extenders constrains clean-label formulation options.
- Fresh food substitution:Unmanned fresh convenience stores and breakfast delivery apps in urban centers compete directly for the same morning consumption occasion.
Strategic Opportunities
- Lower-tier city whitespace:Chengdu, Hangzhou, and Wuhan exhibit protein bar penetration gaps of 40-60 percent versus Shanghai benchmarks.
- Dual carbon alignment:Brands achieving MEE carbon footprint verification can access preferential placement in state-owned retail channels.
- Subscription replenishment models:Direct-to-home delivery cadences leveraging existing logistics networks lock in recurring revenue from time-constrained professionals.
Industry Challenges
- Functional food classification ambiguity:Brands face 12-18 month SAMR approval timelines when protein content triggers specialized nutrition pathway requirements.
- Cold-chain integration costs:Enrobed and fresh-format bars require refrigerated last-mile capabilities that strain margin structures in ambient-dominant distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Snack Bar Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Fruit Bars, Nut Bars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Customer Type: Health Conscious Consumers, Busy Professionals, Students, Athletes Packaging Type: Single Serve, Multi-Pack, Resealable Bags, Bulk Packaging |
| Companies Covered | Beijing Happy Energy Health Technology Co. Ltd, Mars Incorporated, General Mills Inc., PepsiCo Inc., Nestlé SA, Otsuka Holdings Co. Ltd, Mondelez International Inc., Guangdong Wingoo Anime Foods Corporation Ltd, Yili Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Snack Bar Market Strategic Shifts
Reformulation science and channel disintermediation are converging to compress traditional competitive advantages in China's snack bar sector, with regulatory compliance emerging as the primary differentiation axis.
Extrusion-cold pressing hybrid technology is unifying texture and protein density targets that previously required separate production lines. Tier-one city manufacturers are adopting these systems at 15-20 percent annual replacement rates. The technology is unifying granola and protein bar production economics, eroding the cost gap between conventional and functional formats.
SAMR's draft GB standards for prebiotic and probiotic health claims are tightening permissible on-pack messaging for gut-health positioned bars. Domestic brands must submit clinical substantiation dossiers before 2026 enforcement windows. Protein-fortified segments face the steepest compliance burden as functional classification thresholds descend.
Young professionals in Beijing and Shanghai are fragmenting their snack bar procurement across three distinct channels: convenience stores for immediate consumption, subscription services for home stockpiling, and live-streaming flash sales for trial of novel flavors. This channel fragmentation forces brands to maintain pricing discipline across divergent margin structures while preventing arbitrage between direct and retail pricing tiers.
China Snack Bar Market Segmentation
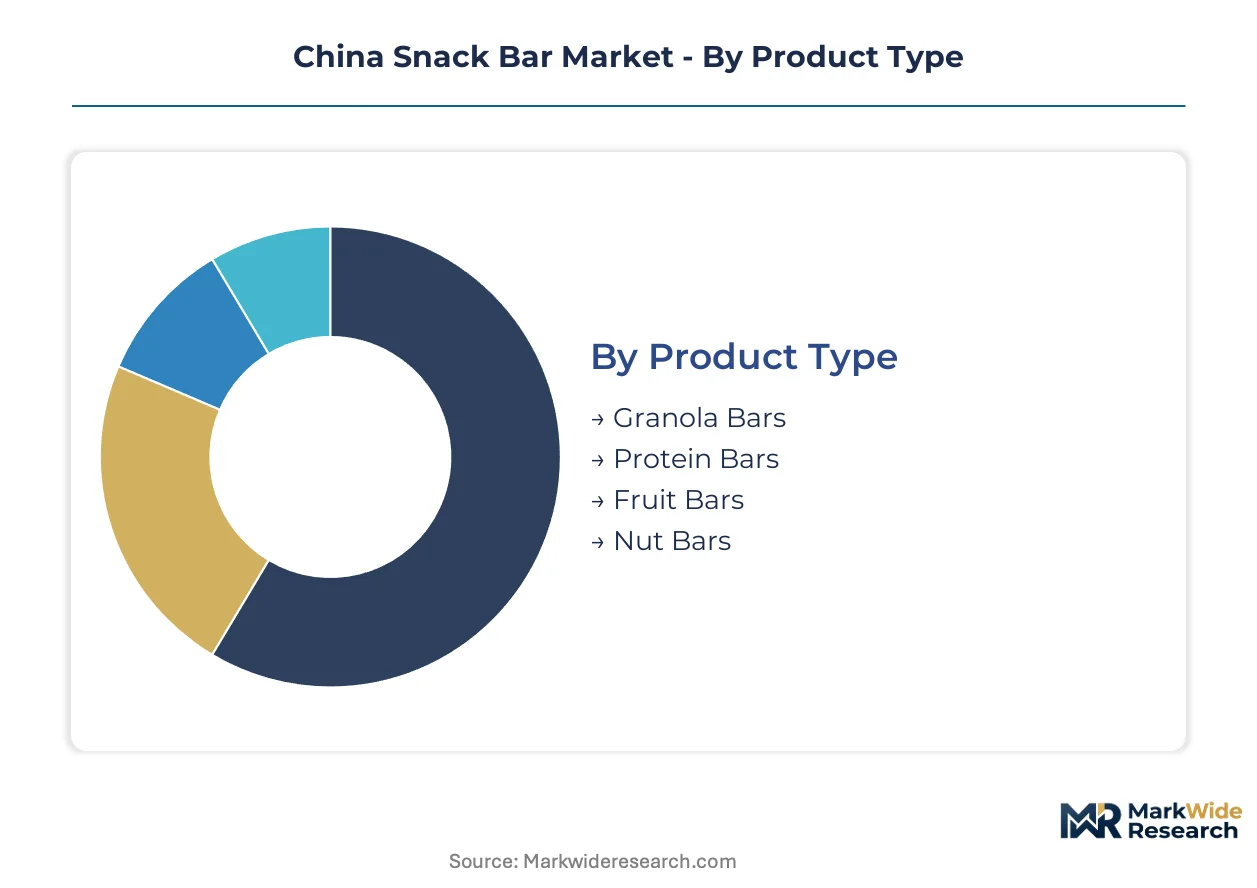
Segmentation in China's snack bar market reveals how urban consumption habits fragment across convenience priorities, nutritional positioning, and procurement channels. SAMR's functional food classification rules create divergent compliance burdens that reshape competitive economics within each segment cluster.
Product Type:
Price elasticity and protein density requirements drive buyer selection more than flavor preferences in tier-one cities.
- Granola Bars:Oat-based formulations with honey or syrup binding dominate ambient shelf-stable production. Shanghai and Beijing supermarkets move these as breakfast replacements for time-constrained commuters facing SAMR's sugar-reduction disclosure mandates.
- Protein Bars:Whey or plant-isolate fortification above 15 grams per serving triggers specialized nutrition pathway approval timelines. Gym culture penetration in Beijing creates concentrated demand for meal-replacement formats that bypass fresh breakfast delivery competition.
- Fruit Bars:Date or dried-fruit binding with minimal processing appeals to clean-label seekers. Hangzhou and Chengdu show penetration gaps versus coastal benchmarks.
- Nut Bars:Almond or cashew-dominant recipes carry higher input costs tied to import dependency. Resealable formats gain traction in office pantry channels.
Granola bars lead on scale; protein bars lead on momentum.
Distribution Channel:
Margin structure and replenishment cadence determine channel viability more than reach alone.
- Supermarkets:Hypermarket chains in Shanghai and Beijing dedicate premium shelf space to front-of-pack labeled products. Slotting fees compress margins for domestic entrants lacking Mars or Nestlé scale.
- Convenience Stores:7-Eleven and FamilyMart outlets capture immediate consumption occasions with single-serve formats. Urban professionals purchase these as breakfast replacements during morning commutes.
- Online Retail:Douyin live-streaming and Xiaohongshu algorithmic personalization reorder purchase patterns toward direct brand relationships. Subscription replenishment models harden recurring revenue for protein bar specialists.
- Health Food Stores:Specialized nutrition positioning commands premium pricing in Beijing and Shanghai boutique channels. SAMR functional food claims face stricter scrutiny here than in mass retail.
Online retail gains share fastest; convenience stores retain the highest purchase frequency.
Customer Type:
Occasion specificity and nutritional literacy separate addressable clusters more than demographics alone.
- Health Conscious Consumers:Front-of-pack label readers prioritize GB-compliant sugar disclosures and clean binding agents. These buyers fragment procurement across health food stores and subscription services.
- Busy Professionals:Time-constrained Shanghai office workers adopt snack bars as breakfast replacements when fresh delivery apps fail. Convenience store proximity drives format selection toward single-serve packaging.
- Students:Price sensitivity concentrates demand in multi-pack formats through campus e-commerce channels. Protein bar adoption lags professional cohorts due to budget constraints.
- Athletes:Specialized nutrition requirements trigger SAMR's functional food classification pathway. Gym-affiliated distribution in Beijing and Shenzhen builds brand loyalty through trainer recommendations.
Busy professionals anchor volume; athletes deliver the steepest expansion trajectory.
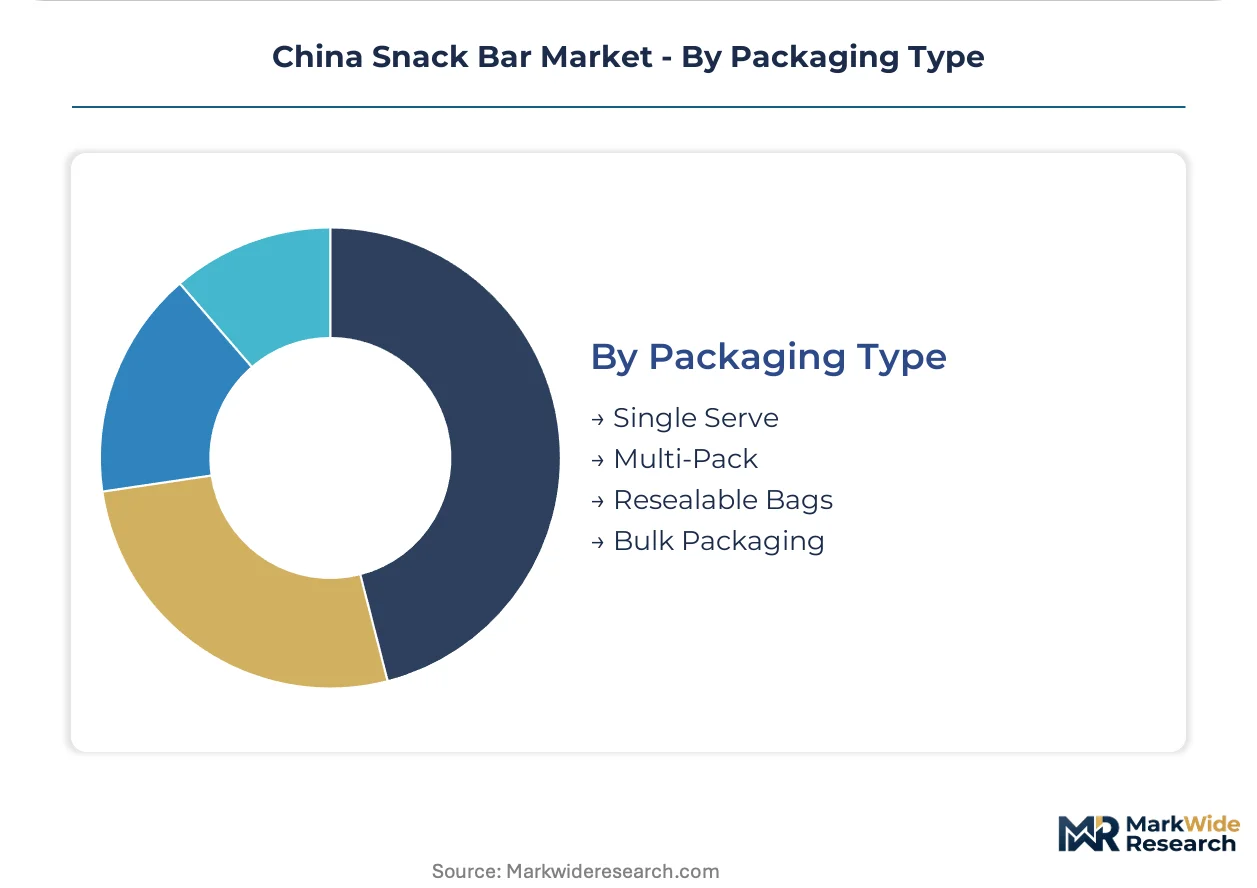
Packaging Type:
Shelf-life requirements and consumption occasion dictate format economics more than branding considerations.
- Single Serve:Individual wrapping meets convenience store and gym vending specifications. Moisture barriers below 10 percent achieve ambient stability without refrigeration.
- Multi-Pack:Four-to-six count boxes optimize household stockpiling for subscription replenishment services. E-commerce channels favor these for shipping efficiency.
- Resealable Bags:Zip-lock formats suit office pantry sharing occasions in Beijing tech corridors. Granola and nut bar categories dominate this packaging.
- Bulk Packaging:Institutional formats for corporate catering or airline service face stricter SAMR additive scrutiny. Limited penetration outside hospitality channels.
Single serve leads on ubiquity; multi-pack climbs fastest through e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's snack bar penetration exceeds India's by roughly threefold, yet both markets face parallel regulatory pressure on sugar content and functional food classification. The analysis examines sub-regional concentration across China's major economic clusters.
Yangtze River Delta
Shanghai's white-collar workforce consumes protein bars as breakfast substitutes at rates unmatched elsewhere. SAMR's front-of-pack labeling mandates accelerate reformulation among local manufacturers. Hangzhou's e-commerce logistics hubs enable same-day subscription replenishment for premium functional formats.
Pearl River Delta
Shenzhen's gym density drives specialized nutrition demand from tech sector employees. Guangdong Wingoo Anime Foods anchors production capacity for fruit-bar exports. Dongguan's contract manufacturing clusters serve both domestic brands and multinational co-packing agreements.
Beijing-Tianjin-Hebei
Capital region consumers exhibit highest nutritional literacy and willingness-to-pay for clean-label positioning. National Health Commission guidelines on sugar reduction receive strictest retail enforcement here. Tianjin's port infrastructure facilitates whey protein imports from Australia and New Zealand.
Sichuan-Chongqing
Chengdu exhibits protein bar penetration gaps of approximately fifty percent versus Shanghai benchmarks. Local taste preferences favor spicy and numbing flavor innovations in granola segments. Chongqing's rising disposable incomes attract brand expansion beyond coastal saturation.
Shandong Peninsula
Qingdao and Yantai host oat processing facilities supplying granola bar manufacturers nationwide. Shandong's agricultural base reduces grain input costs versus import-dependent competitors. Local brands leverage proximity to raw materials for price-competitive multi-pack formats.
China Snack Bar Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG conglomerates commanding shelf space in tier-one retail while domestic players dominate e-commerce velocity. Market structure tilts toward consolidation in protein-fortified categories where SAMR approval timelines create barriers. Three archetypes prevail: global nutrition giants with established GB compliance infrastructure, regional oat and grain processors with backward integration into agricultural supply, and agile direct-to-consumer startups leveraging live-streaming commerce. Competitive moves center on subscription model deployment and cold-chain capacity expansion for fresh-format bars.
Among multinational nutrition conglomerates, Mars Incorporated, Nestlé SA, and Mondelez International occupy positions exemplifying divergent strategic postures. Mars leverages logistics scale for replenishment cadence in first-tier cities. Nestlé anchors specialized nutrition positioning that competes with local functional food entrants. Mondelez exemplifies portion-controlled format dominance in convenience store channels. Domestic listed entities including Yili Group and Beijing Happy Energy Health Technology represent state-adjacent players navigating dual carbon alignment for preferential retail placement. Guangdong Wingoo Anime Foods and Otsuka Holdings illustrate regional specialization archetypes with distinct geographic anchoring.
| Leading Market Players |
|---|
| Beijing Happy Energy Health Technology Co. Ltd |
| Mars Incorporated |
| General Mills Inc. |
| PepsiCo Inc. |
| Nestlé SA |
| Otsuka Holdings Co. Ltd |
| Mondelez International Inc. |
| Guangdong Wingoo Anime Foods Corporation Ltd |
| Yili Group |
| Others |
Value Chain & Pricing Dynamics
Whey protein concentrate from New Zealand and Australian dairy cooperatives flows through Tianjin port into three pricing tiers: premium functional bars with SAMR specialized nutrition approval, standard granola formats with front-of-pack labeling compliance, and economy multi-packs for lower-tier city expansion. This input cost pathway explains why domestic brands face margin compression when trade friction disrupts ocean freight schedules while multinational players absorb volatility through forward contracts.
Pricing Analysis
Capacity additions in Shandong oat processing facilities are reshaping price floors for granola bar manufacturers seeking to undercut import-dependent competitors. Three-tier pricing structure across premium functional, standard clean-label, and economy bulk formats separates brands by SAMR compliance investment and protein density certification. Price differentiation hinges on GB standard adherence and cold-chain delivery capability. Cost compression in the standard tier intensifies because domestic oat suppliers expand milling capacity faster than demand absorbs volume. Students and price-sensitive consumers in campus channels exhibit highest price sensitivity; athletes and busy professionals in Beijing show lowest elasticity due to meal-replacement necessity.
Supply Chain Analysis
Returns of expired or damaged inventory from convenience store chains feed into animal feed or industrial processing streams rather than refurbishment given ambient shelf-life constraints. Geographic supply concentration centers on Shandong for oat and grain inputs, New Zealand and Australia for whey protein isolates, and Guangdong for fruit binding agents and packaging materials. Raw material dependencies include imported dairy proteins, domestic oat flakes, and Southeast Asian date paste. Single-source vulnerability runs through Australian whey suppliers exposed to bilateral trade policy shifts. Distribution runs through tier-one city logistics hubs for subscription replenishment, with ambient-stable formats bypassing cold-chain requirements that strain fresh-format competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's snack bar market offers margin expansion through reformulation cost-downs as extrusion-cold pressing hybrid technology unifies production economics, and through premium-tier shifts as protein-fortified segments capture health-conscious professionals willing to absorb SAMR compliance premiums.
For Market Incumbents: Anchor shelf space dominance in 7-Eleven and FamilyMart channels through exclusive single-serve format agreements that block challenger brand access. Deepen backward integration into Shandong oat supply to neutralize input cost volatility from import-dependent competitors. Defend against direct-to-consumer startups by accelerating subscription replenishment cadences leveraging existing Mars and Nestlé logistics networks. For New Entrants and Emerging Players: SAMR's draft GB standards for prebiotic health claims in China opens a window for gut-health positioned bars with clinical substantiation dossiers before enforcement windows tighten. Target Chengdu and Wuhan protein bar whitespace where penetration gaps versus Shanghai benchmarks exceed forty percent. Pursue live-streaming commerce partnerships on Douyin as the primary go-to-market angle to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR functional food classification timelines stretch 12-18 months and capital reserves determine survival. Long-term viability favors brands with dual carbon alignment credentials accessing state-owned retail preferential placement. Acquisition target archetype: regional oat processors with backward integration into agricultural supply and dormant brand assets awaiting e-commerce activation. Monitor MEE carbon footprint verification adoption rates as inflection indicator for state channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Replenishment Launch | Direct-to-home cadences lock recurring revenue from Shanghai time-constrained professionals. |
| Dual Carbon Certification Pursuit | MEE verification unlocks preferential placement in state-owned retail channels. |
| Extrusion-Cold Pressing Technology Adoption | Hybrid systems unify granola and protein bar production economics for margin recovery. |
| Lower-Tier City Distribution Expansion | Chengdu and Wuhan whitespace offers forty to sixty percent penetration gaps versus coastal benchmarks. |
| GB Standard Pre-Compliance Investment | Early clinical substantiation for prebiotic claims secures positioning before SAMR enforcement windows. |
Study Parameters
Bottom-up consumption occasion modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with brand managers at multinational CPG conglomerates, category buyers at FamilyMart and 7-Eleven, supply planners at Shandong oat processors, and regulatory affairs specialists navigating SAMR functional food pathways combined with secondary validation from customs import records, National Health Commission dietary guideline publications, and CSRC disclosure filings for listed food companies. Triangulation between demand-side procurement patterns and supply-side production data ensures segment-level accuracy.
Input-output matrices map protein density requirements, binding agent specifications, and packaging format economics across the projection horizon. Segmentation dimensions modeled include product type granularity, distribution channel margin structures, customer occasion specificity, and regional regulatory enforcement intensity. CAGRs derive from trend extrapolation of live-streaming commerce penetration and gym culture adoption curves. Industry-specific forecast inputs incorporate SAMR approval timeline distributions and whey protein import tariff exposure scenarios.
Revisions become necessary when bilateral trade friction disrupts Australian and New Zealand dairy supply chains or when SAMR accelerates functional food classification enforcement ahead of draft GB standard timelines. Practitioners should monitor MEE carbon footprint verification adoption rates and front-of-pack labeling compliance deadlines for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
No-Fat Peanut Butter Market
Snacks
Extruded Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
North America Snack Food Market
Snacks
Europe Snack Pellets Market
Snacks
Savoury Biscuits Market
Snacks
Fat Free Snacks Market
Snacks
South America Cereal Bar Market
Snacks
Marshmallow Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
Forti Flakes Market
Snacks
Low Fat Granola Market
Snacks
Low Calorie Dip Market
Snacks
North America Baked Chips Market