
 Parenteral Feeding Devices Market | 2026-2036
Parenteral Feeding Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Parenteral Feeding Devices Market Analytics
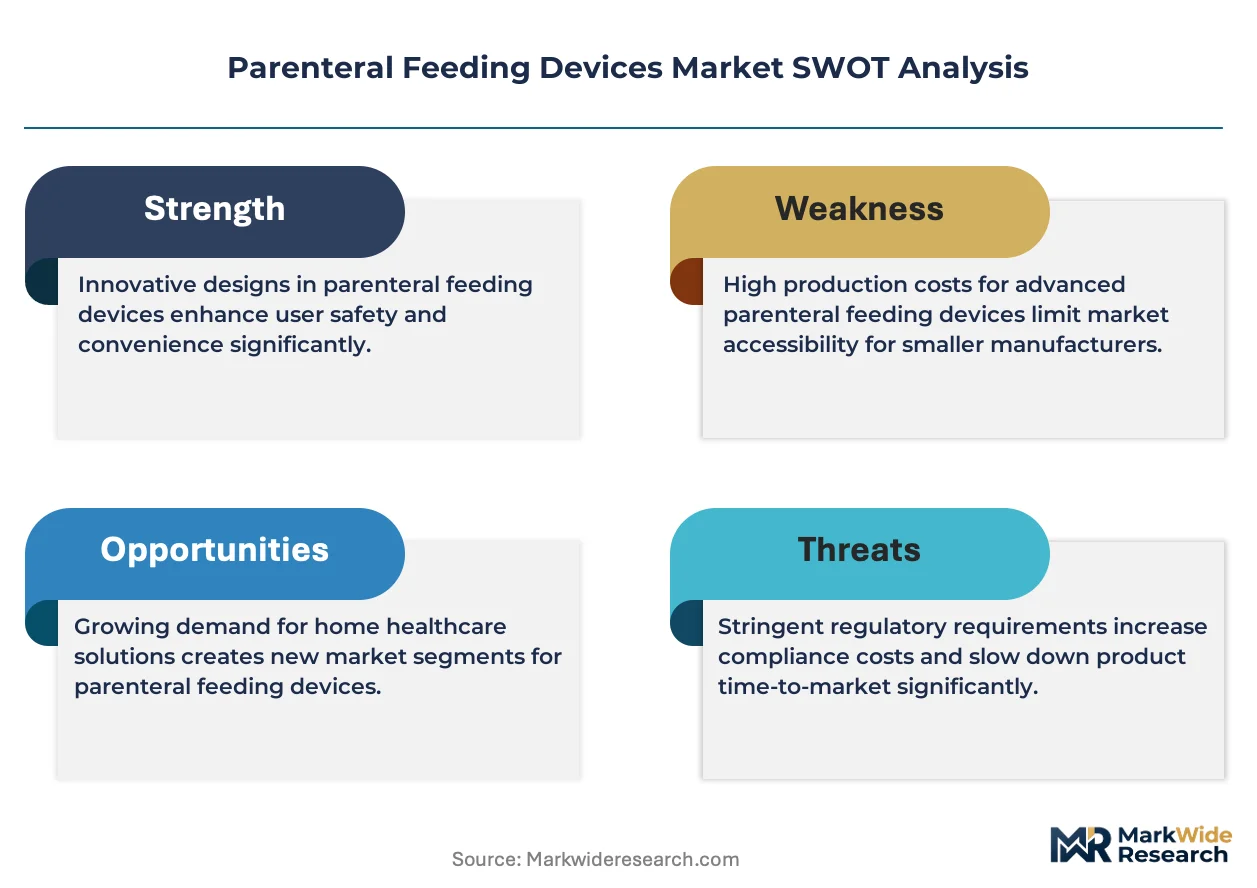
A critical shortage of specialized infusion nurses is unwinding capacity constraints across acute and post-acute settings. Fresenius Kabi AG leverages its vertical integration in parenteral nutrition formulations to maintain supply continuity for device-adjacent therapies. Baxter International Inc. anchors its position through deep partnerships with hospital group purchasing organizations. B. Braun Melsungen AG differentiates via proprietary needle-free connector technologies that reduce bloodstream infection risk.
Parenteral feeding devices are sterile apparatus engineered to deliver nutrient solutions directly into the venous bloodstream, typically incorporating peristaltic or volumetric pumping mechanisms with flow accuracy within plus or minus five percent. These systems serve patients whose gastrointestinal tracts cannot absorb adequate nutrition due to surgery, malignancy, or functional impairment. Infusion pumps command the largest value share due to electronic precision dosing and alarm integration, while gravity-based systems retain volume in resource-limited environments. Home care represents the fastest-expanding end user channel as payors push reimbursement toward outpatient models. Cancer therapy applications generate premium pricing for devices compatible with concurrent chemotherapy infusion protocols.
The FDA regulates these devices under 21 CFR 880.5725 with substantial equivalence requirements for new pump submissions, while the EU MDR imposes stricter clinical evidence thresholds for Class IIa and IIb infusion systems. ISO 60601-2-24 governs electrical safety and essential performance for infusion pumps, creating harmonized testing burdens for multinational manufacturers. Stakeholders must monitor reimbursement parity between institutional and home-based parenteral nutrition as this determines device procurement volumes and service model economics.
Market Dynamics
The FDA's updated infusion pump guidance is compressing product development timelines while payors accelerate hospital-to-home discharge protocols, creating simultaneous pressure on device precision requirements and ambulatory system durability.
Growth Catalysts
- Home care reimbursement expansion:CMS and private payors in the United States are extending coverage for outpatient parenteral nutrition, pulling device procurement into home settings.
- ISO 60601-2-24 harmonization:Electrical safety standardization across North America and Europe reduces redundant testing burdens for pump manufacturers entering multiple jurisdictions.
- Aging demographics:Japan, Italy, and Germany exhibit rising prevalence of gastrointestinal malignancies requiring long-term venous feeding support.
Market Restraints
- Specialized infusion nurse scarcity:Acute and post-acute facilities in the United States face unwinding capacity constraints due to critical workforce shortages.
- EU MDR clinical evidence thresholds:Stricter requirements for Class IIa and IIb infusion systems extend certification timelines and elevate documentation costs.
- Gravity-based system persistence:Resource-limited environments in South Asia and sub-Saharan Africa retain lower-margin alternatives that cap premium pump penetration.
Strategic Opportunities
- Needle-free connector adoption:Proprietary technologies reducing bloodstream infection risk command pricing premiums in oncology and immunocompromised patient segments.
- Concurrent chemotherapy compatibility:Cancer therapy applications generate device specifications that support dual-infusion protocols with premium positioning.
- India's hospital infrastructure buildout:Government health expenditure expansion under Ayushman Bharat creates procurement channels for mid-tier electronic pumps.
Industry Challenges
- Alarm integration complexity:FDA 21 CFR 880.5725 substantial equivalence requirements for new pump submissions demand extensive software validation documentation.
- Legacy system interoperability:Hospital electronic health record integration requires proprietary middleware development that fragments vendor ecosystems.
- Peristaltic mechanism calibration:Flow accuracy within plus or minus five percent necessitates precision manufacturing that concentrates supply among specialized component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parenteral Feeding Devices Market |
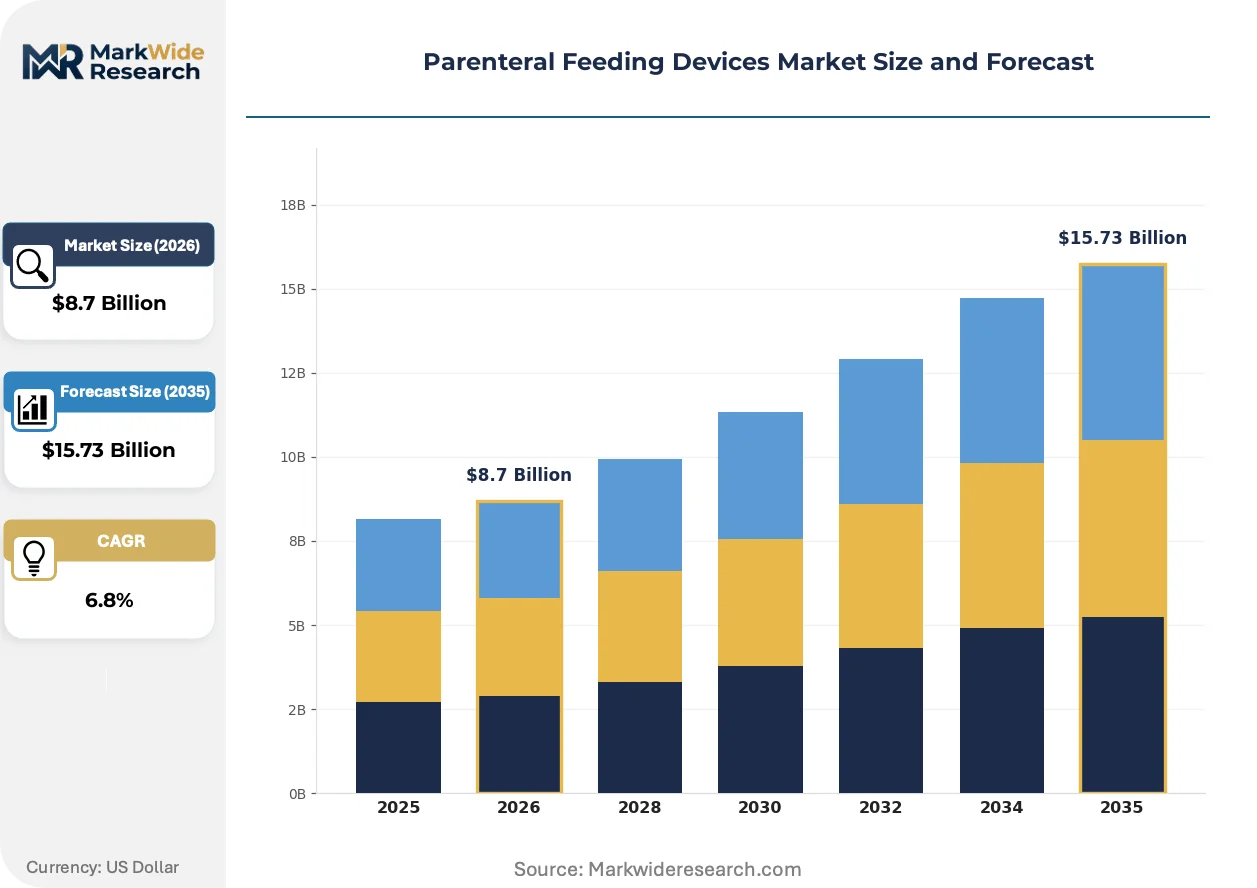
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Catheters, IV Sets, Safety Needles Technology: Electronic, Mechanical, Gravity, Hybrid End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Application: Cancer Therapy, Gastrointestinal Disorders, Nutritional Support, Surgery Recovery |
| Companies Covered | Fresenius Kabi AG, Baxter International Inc., B. Braun Melsungen AG, Pfizer Inc., Otsuka Pharmaceutical Co., Ltd., ICU Medical, Inc., Vifor Pharma Management Ltd., AbbVie Inc., Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parenteral Feeding Devices Market Evolving Landscape
Smart connectivity and closed-loop dosing algorithms are actively restructuring how parenteral feeding systems integrate with broader patient monitoring infrastructure, shifting competitive advantage toward software-capable device platforms.
Closed-loop glucose-responsive insulin co-infusion is decomposing traditional siloed pump architectures. Intensive care units in tertiary hospitals across Germany and the Netherlands are piloting these systems for hyperglycemic parenteral nutrition patients. The technology is decomposing standalone infusion pump categories into integrated metabolic management platforms that compress vendor margins on single-function devices.
EU MDR Article 10 post-market clinical follow-up requirements now mandate systematic device performance surveillance across European Economic Area member states. Manufacturers must maintain updated technical documentation and periodic safety update reports throughout product lifecycles. Class IIb infusion systems face the steepest compliance burden, with notified bodies in Germany and Ireland extending review queues that delay market entry.
Hospital group purchasing organizations are consolidating vendor panels and unbundling after-sales service from capital equipment contracts. Acute care networks in the United States now negotiate multi-year pump fleet management agreements separate from device acquisition. This restructuring concentrates procurement leverage among three dominant GPOs while fragmenting service revenue across third-party clinical engineering firms.
Parenteral Feeding Devices Market Segmentation
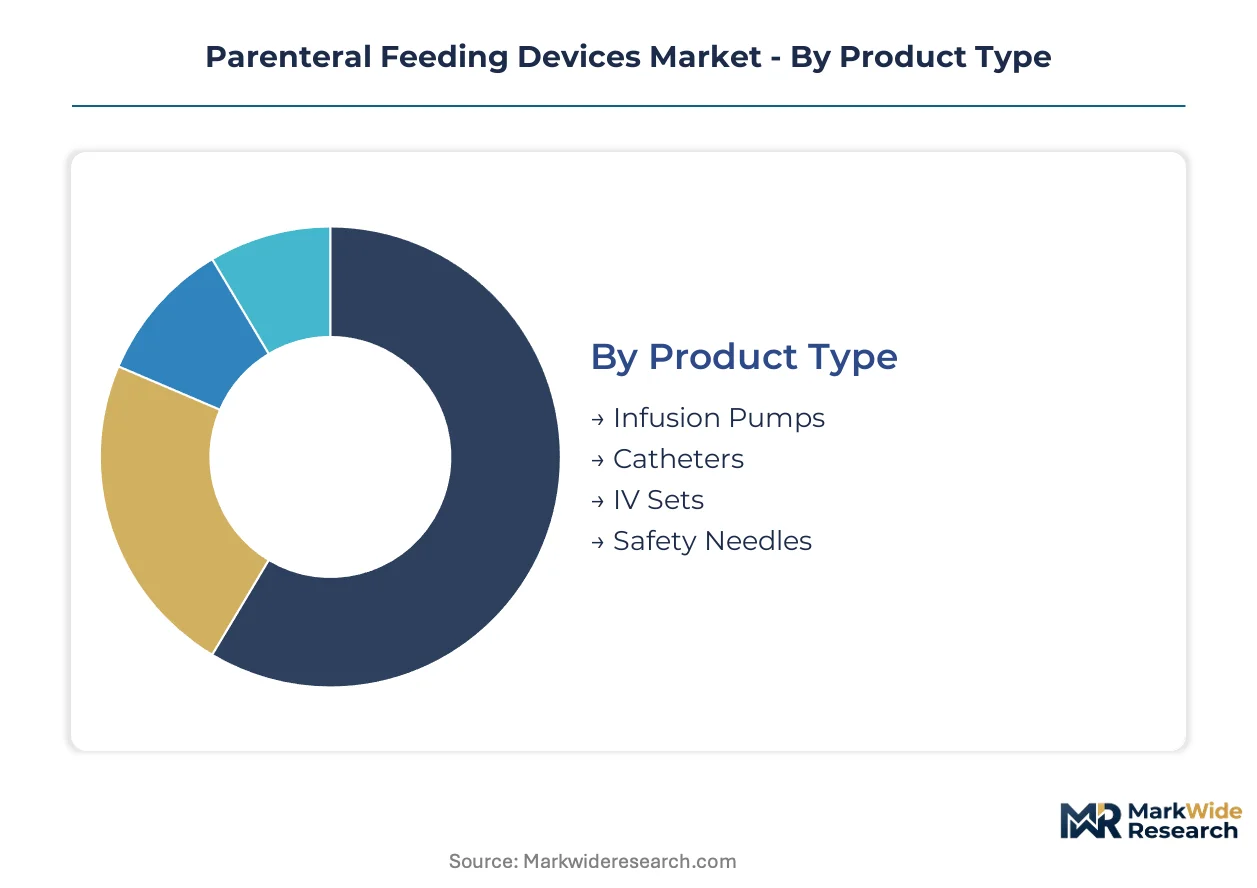
Parenteral feeding devices fragment across four critical dimensions where substitution threats and reimbursement dynamics reshape competitive boundaries. Understanding these segment boundaries reveals where electronic precision commands premium positioning versus where gravity-based alternatives retain cost-driven volume.
Product Type:
Gravity-based systems exert persistent substitution pressure on electronic pumps in resource-constrained procurement environments, compressing margins for mid-tier electronic offerings.
- Infusion Pumps:Electronic peristaltic or volumetric mechanisms deliver flow accuracy within plus or minus five percent with integrated alarm systems. Demand concentrates in United States hospital networks transitioning patients to home settings under CMS reimbursement expansion, where precision dosing justifies capital expenditure despite higher acquisition cost.
- Catheters:Central venous access devices engineered for extended dwell times include peripherally inserted central catheters and tunneled cuffed catheters. Oncology centers in Germany and Japan absorb premium-priced antimicrobial-coated variants as bloodstream infection reduction becomes a measurable quality metric.
- IV Sets:Sterile tubing assemblies with drip chambers and roller clamps for solution administration.
- Safety Needles:Engineered sharps injury prevention devices with retractable or shielded mechanisms.
Infusion pumps retain volume leadership; catheters hold the steepest expansion curve as long-term vascular access protocols proliferate.
Technology:
Cost tier stratification separates electronic precision platforms from mechanical alternatives, with hybrid architectures emerging to bridge reimbursement gaps.
- Electronic:Microprocessor-controlled systems with programmable flow rates, occlusion detection, and wireless connectivity for electronic health record integration. United States acute care networks under group purchasing organization contracts standardize on these platforms despite higher per-unit cost.
- Mechanical:Spring-loaded or elastomeric reservoir systems requiring no electrical power. Home care settings in Italy and Spain adopt these for ambulatory patients where simplicity reduces training burden and device failure risk.
- Gravity:Drip-rate dependent systems without active pumping mechanisms. South Asian and sub-Saharan African facilities retain these where capital constraints override precision requirements.
- Hybrid:Battery-backed electronic systems with gravity failover modes for power interruption resilience.
Electronic systems capture the premium tier; hybrid configurations are expanding most quickly as reliability engineering addresses home care liability concerns.
End User:
Customer type migration from institutional to ambulatory settings reconfigures device specifications toward durability and patient-operability.
- Hospitals:Tertiary acute care facilities requiring fleet-standardized pumps with centralized asset management and biomedical engineering support. United States health systems consolidate procurement through dominant group purchasing organizations that unbundle service contracts from capital acquisition.
- Home Care:Patient-directed administration settings where device portability, alarm simplicity, and caregiver training protocols determine adoption. CMS reimbursement expansion for outpatient parenteral nutrition accelerates procurement shift into this channel.
- Clinics:Outpatient infusion centers with intermediate throughput requirements.
- Long-term Care Facilities:Skilled nursing environments with limited on-site clinical engineering support.
Hospitals retain installed base dominance; home care gains share fastest as payor reimbursement structures reorient toward outpatient models.
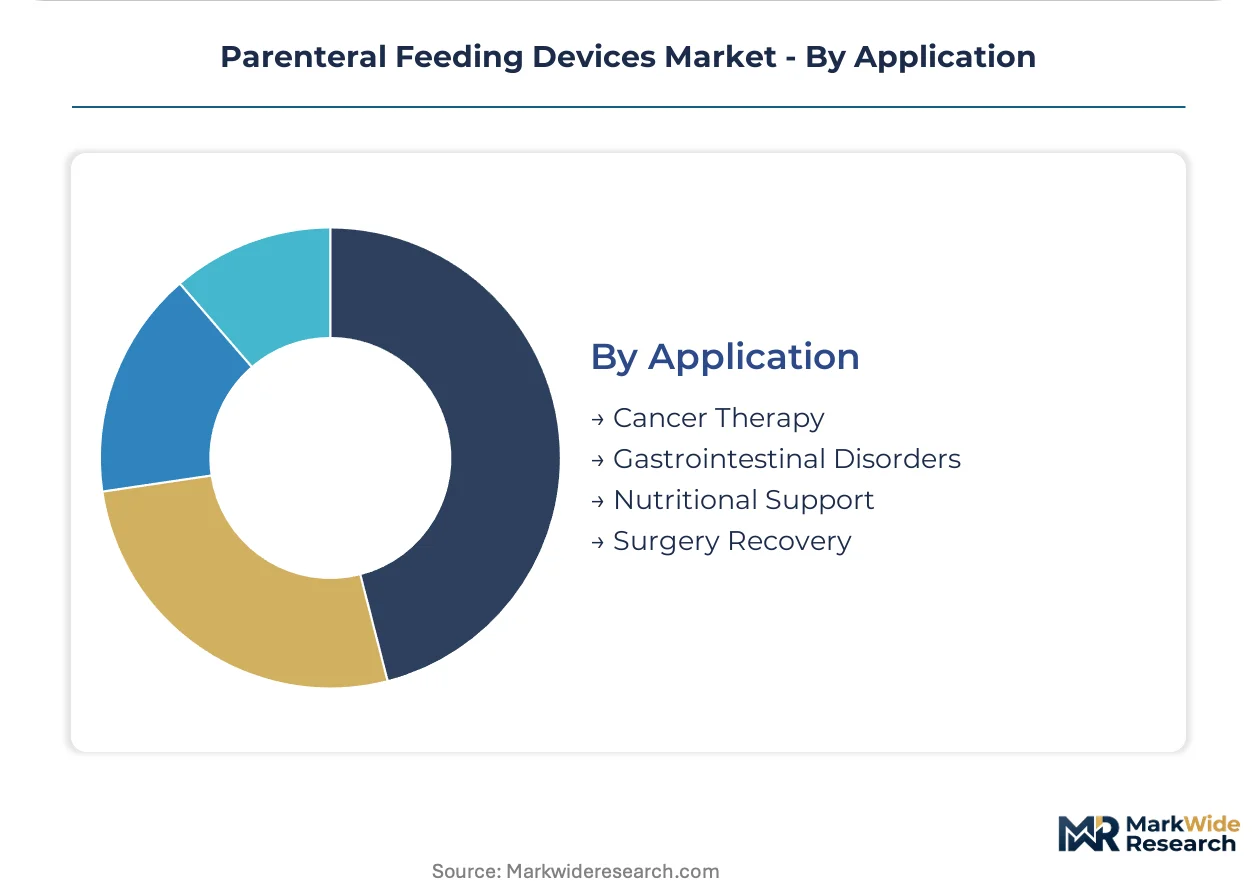
Application:
Clinical indication severity stratifies device performance requirements, with oncology applications commanding the most stringent concurrent-infusion specifications.
- Cancer Therapy:Devices supporting simultaneous parenteral nutrition and chemotherapy infusion with compatible flow rates and material compatibility. Tertiary oncology centers in the Netherlands and Switzerland pilot closed-loop glucose-responsive systems for hyperglycemic patients.
- Gastrointestinal Disorders:Long-term nutritional support for Crohn's disease, short bowel syndrome, and intestinal failure. Home-based patients in Japan with aging-related GI malignancies drive demand for portable, low-maintenance systems.
- Nutritional Support:General malnutrition and metabolic stabilization protocols.
- Surgery Recovery:Post-operative bowel rest and anastomotic healing support.
Cancer therapy commands premium pricing; gastrointestinal disorders show the steepest expansion trajectory as chronic disease prevalence rises in aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement volume tilts toward Germany and Japan. CMS reimbursement expansion for outpatient parenteral nutrition creates premium capture opportunities unmatched in European capitated systems. Japanese demand for portable home care devices accelerates faster than regulatory harmonization permits in neighboring Asian markets.
United States
Aging demographics and chronic disease prevalence sustain hospital-to-home transitions that pull device procurement into ambulatory channels. FDA's updated infusion pump guidance under 21 CFR 880.5725 compresses product development timelines while demanding extensive software validation. Hospital group purchasing organizations in the Midwest and Southeast consolidate vendor panels, unbundling service contracts from capital equipment agreements.
Germany
Tertiary oncology centers in Bavaria and North Rhine-Westphalia pilot closed-loop glucose-responsive systems for hyperglycemic parenteral nutrition patients. EU MDR Article 10 post-market clinical follow-up requirements mandate systematic device performance surveillance, with notified bodies extending review queues that delay market entry. The medical technology cluster around Tuttlingen anchors precision manufacturing for peristaltic pump mechanisms.
Japan
Rising prevalence of gastrointestinal malignancies among aging populations drives demand for long-term venous feeding support in home settings. METI standards harmonization with ISO 60601-2-24 reduces redundant testing burdens for manufacturers entering multiple jurisdictions. The Kansai region around Osaka hosts concentrated procurement for portable, low-maintenance ambulatory systems.
India
Government health expenditure expansion under Ayushman Bharat creates procurement channels for mid-tier electronic pumps in secondary hospitals. CDSCO medical device regulations impose registration requirements that extend market entry timelines for foreign manufacturers. Maharashtra and Karnataka absorb the steepest volume growth as private hospital infrastructure buildout accelerates.
Switzerland
Tertiary care networks in Zurich and Geneva command premium positioning for devices compatible with concurrent chemotherapy infusion protocols. Swissmedic maintains alignment with EU MDR requirements while offering streamlined review pathways for innovative pump architectures. The Basel pharmaceutical corridor drives demand for closed-loop metabolic management platforms integrating parenteral nutrition with insulin co-infusion.
Parenteral Feeding Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where precision engineering specialists coexist with scale-driven manufacturers. The vendor base concentrates among diversified medical technology conglomerates with captive nutrition formulation capabilities and specialized infusion device pure-plays. Three archetypes dominate: vertically integrated pharmaceutical-device hybrids, precision pump engineering specialists, and safety-focused connector innovators. Competitive dynamics center on group purchasing organization contract consolidation and proprietary needle-free technologies that command infection-risk premiums.
Within the pharmaceutical-device hybrid tier, Fresenius Kabi AG and Baxter International Inc. occupy positions that leverage in-house parenteral nutrition formulations to maintain supply continuity for device-adjacent therapies. B. Braun Melsungen AG exemplifies the safety-engineering archetype through proprietary connector technologies. These three Germany and United States-based entities anchor the premium tier, with their geographic origins reflecting historical concentration of infusion therapy innovation.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Pfizer Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| ICU Medical, Inc. |
| Vifor Pharma Management Ltd. |
| AbbVie Inc. |
| Cardinal Health, Inc. |
| Others |
Value Network & Pricing Analysis
Peristaltic pump mechanism manufacturing concentrates among German and Swiss precision engineering clusters, where scale economies in micromachined components set price floors that mid-tier electronic pump assemblers cannot match without sacrificing flow accuracy tolerances.
Pricing Analysis
The customization-premium spread separates configured-to-order infusion pumps with hospital-specific software integrations from standard catalog units. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR 880.5725 certification grade and ISO 60601-2-24 electrical safety tier. Cost compression in gravity-based alternatives is intensifying because South Asian procurement authorities prioritize capital expenditure minimization over precision dosing. Home care settings exhibit the sharpest price sensitivity due to CMS reimbursement rate constraints, while tertiary oncology centers in Switzerland and the Netherlands absorb premium positioning for closed-loop glucose-responsive systems.
Supply Chain Analysis
Strategic stockpile preferences dominate parenteral feeding device procurement as hospital group purchasing organizations negotiate multi-year fleet management agreements that buffer against peristaltic mechanism supply volatility. Component sourcing draws from Germany for precision pump motors, Switzerland for medical-grade polymers, and Malaysia for sterile tubing extrusion. Single-source vulnerability concentrates in elastomeric pump reservoir membranes where FDA master file documentation creates switching costs. Distribution runs through consolidated GPO contracts in the United States and direct hospital procurement networks in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity-based feeding systems and mechanical elastomeric pumps constitute the primary substitution threat that electronic pump incumbents must neutralize through reliability engineering and total cost-of-ownership repositioning.
For Market Incumbents: Compound service revenue attachment by unbundling clinical engineering support from capital equipment contracts, mirroring the restructuring acute care networks now demand. Deepen backward integration into parenteral nutrition formulation supply to defend against pharmaceutical-device hybrid competitors. Prioritize software validation documentation investment to compress FDA 21 CFR 880.5725 substantial equivalence review timelines.
For New Entrants and Emerging Players: Anchor in India's Ayushman Bharat hospital infrastructure buildout where CDSCO registration requirements create defensible moats against established multinationals. Target mid-tier electronic pump procurement in Maharashtra and Karnataka secondary hospitals where price-performance gaps persist. Pursue needle-free connector technology licensing as the go-to-market angle, leveraging proprietary bloodstream infection reduction claims.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors safety-engineering pure-plays with proprietary connector portfolios over diversified conglomerates facing GPO contract consolidation pressure. Long-term viability hinges on software-capable platform architectures that integrate with electronic health record systems. The inflection signal to monitor is EU MDR notified body queue lengths in Germany and Ireland, which foreshadow market entry delays for Class IIb infusion systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed review timelines under updated 21 CFR 880.5725 guidance capture CMS reimbursement expansion windows. |
| CE Marking Pathway Investment | EU MDR Article 10 clinical evidence preparation defends against notified body queue extensions in Germany. |
| Hospital System Partnership | GPO contract consolidation in Midwest and Southeast United States concentrates procurement leverage among three dominant organizations. |
| Software Companion Development | Electronic health record integration middleware addresses legacy system interoperability fragmentation. |
| Reimbursement Strategy Alignment | CMS outpatient parenteral nutrition coverage expansion pulls device procurement into home care channels. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital GPO contract filings preceded structured interviews with biomedical engineering directors, GPO contracts managers, and home care reimbursement specialists. Primary fieldwork with infusion pump manufacturers and parenteral nutrition formulation suppliers combined with secondary validation against ISO 60601-2-24 certification records and CMS Medicare claims data. Bottom-up segmentation modeling and top-down macroeconomic adjustment produced convergent estimates.
Variance decomposition across product type, technology tier, end user channel, and application indication shaped the analytical framework over the projection horizon. CAGRs emerged from logistic adoption curves applied to home care transition rates and oncology center infrastructure buildout. Modeled inputs included peristaltic mechanism manufacturing capacity utilization, EU MDR notified body review queue dynamics, and CMS reimbursement parity adjustments between institutional and outpatient settings.
Material uncertainties — regulatory harmonization delays, infusion nurse workforce shortages, and gravity-based system substitution in emerging markets — sit outside the modeled envelope. Forecasts reflect assumptions about GPO contract consolidation velocity and software validation burden trajectories. Revision becomes warranted when FDA infusion pump guidance enforcement intensity or EU MDR post-market clinical follow-up compliance costs cross thresholds that alter manufacturer entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Medical Connector Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market