
 Organ Care Products Market | 2026-2036
Organ Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Care Products Market Analysis
Multi-source procurement of perfusion circuits and disposable cannulae is consolidating around technology-integrated suppliers with captive manufacturing capabilities. TransMedics Inc. dominates the normothermic machine perfusion segment with vertically integrated console production. Paragonix Technologies differentiates through specialized cold storage transport devices with embedded temperature telemetry. XVIVO Perfusion AB anchors the European market with hypothermic perfusion platforms and organ preservation research.
Organ care products comprise medical devices, biologic solutions, and integrated systems engineered to maintain organ viability outside the human body through temperature-controlled perfusion with oxygenated, nutrient-enriched fluids; these systems typically regulate pH, electrolyte balance, and metabolic waste clearance during transport lasting up to twelve hours. Their primary purpose is to extend preservation duration, enable functional assessment, and reduce ischemia-reperfusion injury prior to transplantation surgery. Organ perfusion systems capture the dominant value share as hospitals convert from static cold storage to active metabolite-support platforms. Preservation solutions generate recurring revenue streams through single-use chemical formulations optimized by organ type. Application demand clusters in kidney transplantation due to higher procedure volumes, while heart and lung perfusion commands premium pricing tied to shorter acceptable ischemic windows.
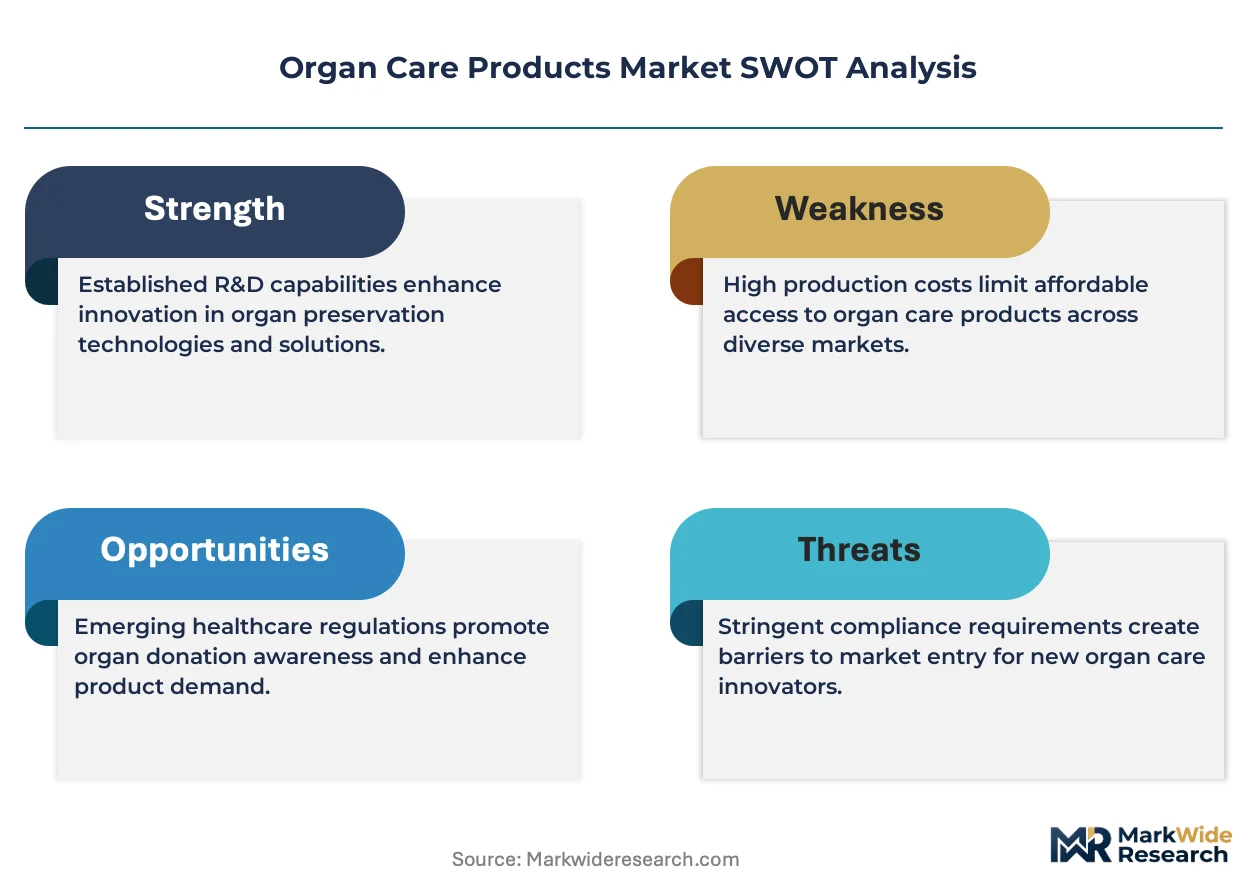
FDA breakthrough device designation pathways compress premarket review timelines for novel perfusion technologies, while EMA medical device regulation mandates clinical performance data for Class III active implantable systems. ISO 14155 governs clinical investigation standards across jurisdictions, creating compliance cost barriers for emerging entrants. Stakeholders must monitor evolving reimbursement codes for ex-vivo organ perfusion as payer evidence requirements tighten alongside technology diffusion into standard transplant protocols.
Market Dynamics
Transplant centers are abandoning static cold storage for active metabolite-support platforms, compressing procurement cycles around integrated perfusion console suppliers with captive disposable manufacturing.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's expedited premarket review pathway accelerates commercialization timelines for novel normothermic perfusion technologies, reducing regulatory friction for platform innovators.
- University Hospital Protocol Standardization:German academic medical centers are driving clinical evidence generation for ex-vivo organ assessment, creating reference implementations that diffuse across European transplant networks.
- Hypothermic-to-Normothermic Platform Migration:Active perfusion systems with embedded metabolic monitoring are displacing passive preservation, extending viable ischemic windows for marginal donor organs.
Market Restraints
- Single-Use Disposable Cost Concentration:Perfusion circuits and organ-specific cannulae represent 60-70% of lifetime system costs, creating procurement budget pressure for mid-volume transplant programs.
- Supplier Concentration Risk:Console manufacturing concentrates among three vertically integrated producers with proprietary disposable lock-in, limiting second-source options for hospital supply chains.
- Clinical Validation Burden:EMA Medical Device Regulation mandates extended clinical performance datasets for Class III active implantable systems, extending time-to-revenue for European market entry.
Strategic Opportunities
- Extended Criteria Donor Expansion:Machine perfusion enables utilization of steatotic livers and donation-after-circulatory-death hearts previously discarded, expanding addressable donor pools by 15-20%.
- India Transplant Infrastructure Buildout:The country's national organ allocation network expansion creates first-mover positioning for perfusion platform vendors as liver and kidney transplantation volumes scale.
- Reimbursement Code Development:Emerging CPT Category III codes for ex-vivo organ perfusion signal prospective payment coverage, reducing hospital capital risk for platform adoption.
Industry Challenges
- Perfusionist Workforce Scarcity:Specialized training requirements for normothermic system operation outpace certified clinician supply, constraining deployment velocity at expanding transplant centers.
- Legacy Cold Storage Integration:Hybrid procurement environments require parallel inventory management for both static preservation and active perfusion protocols, complicating supply chain operations.
- Cross-Platform Data Interoperability:Proprietary metabolic monitoring formats impede multi-center outcome aggregation, slowing real-world evidence generation for payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Care Products Market |
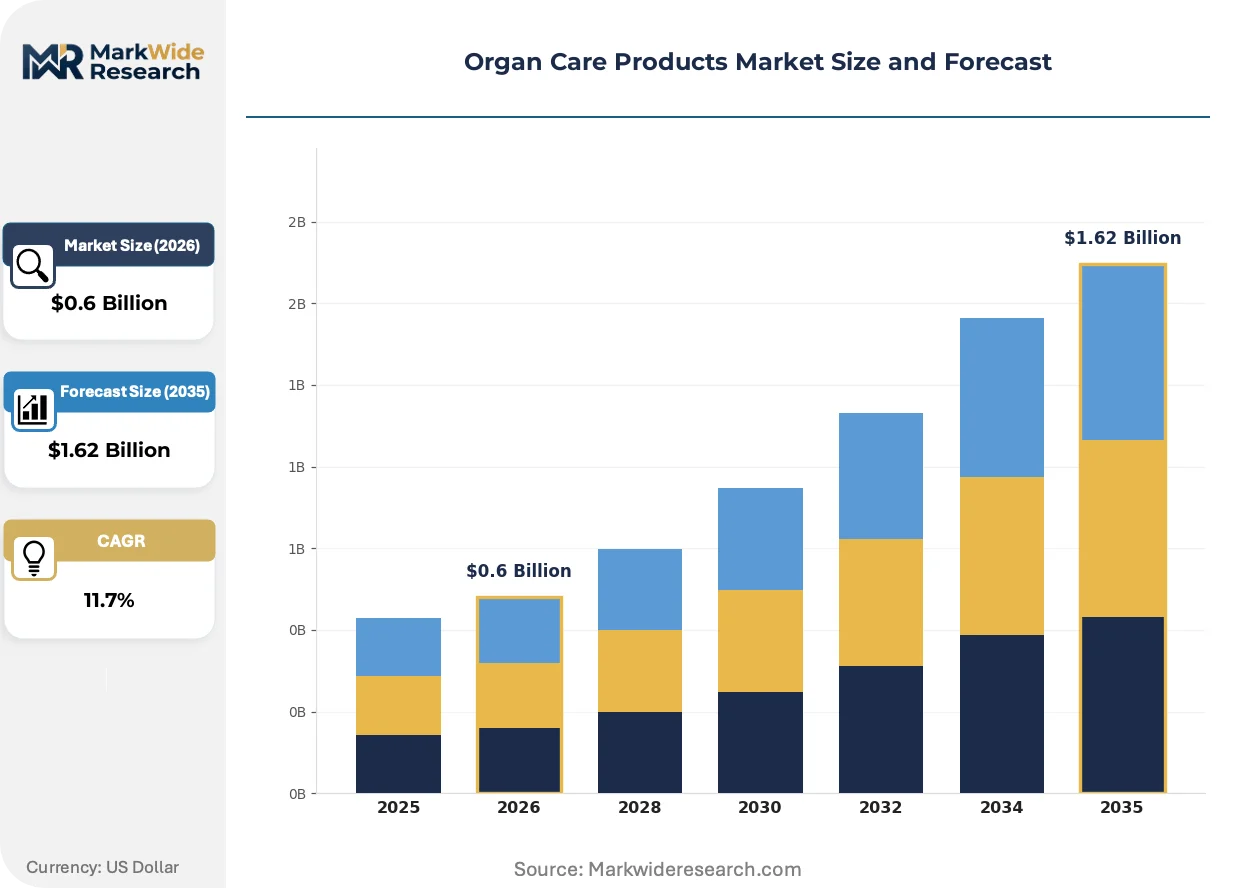
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.62 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
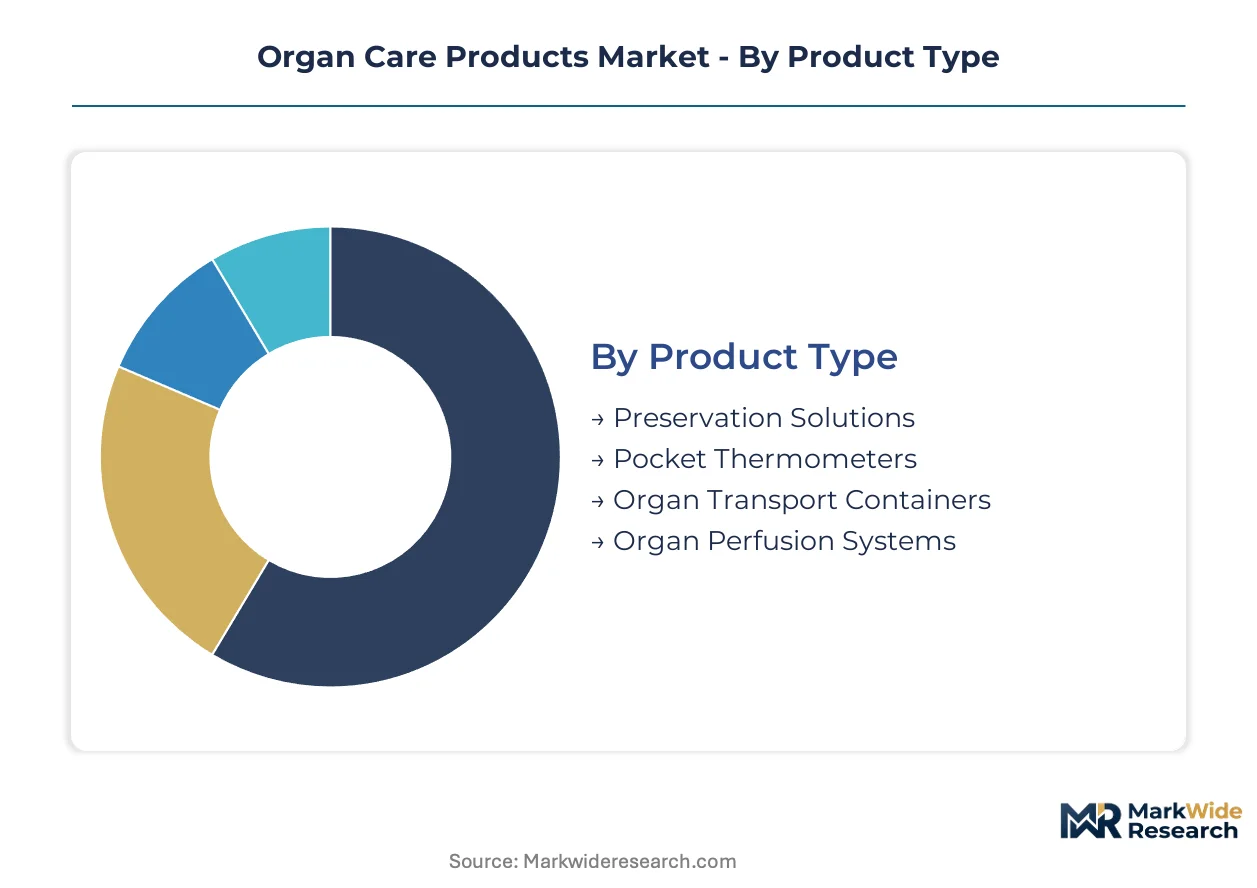
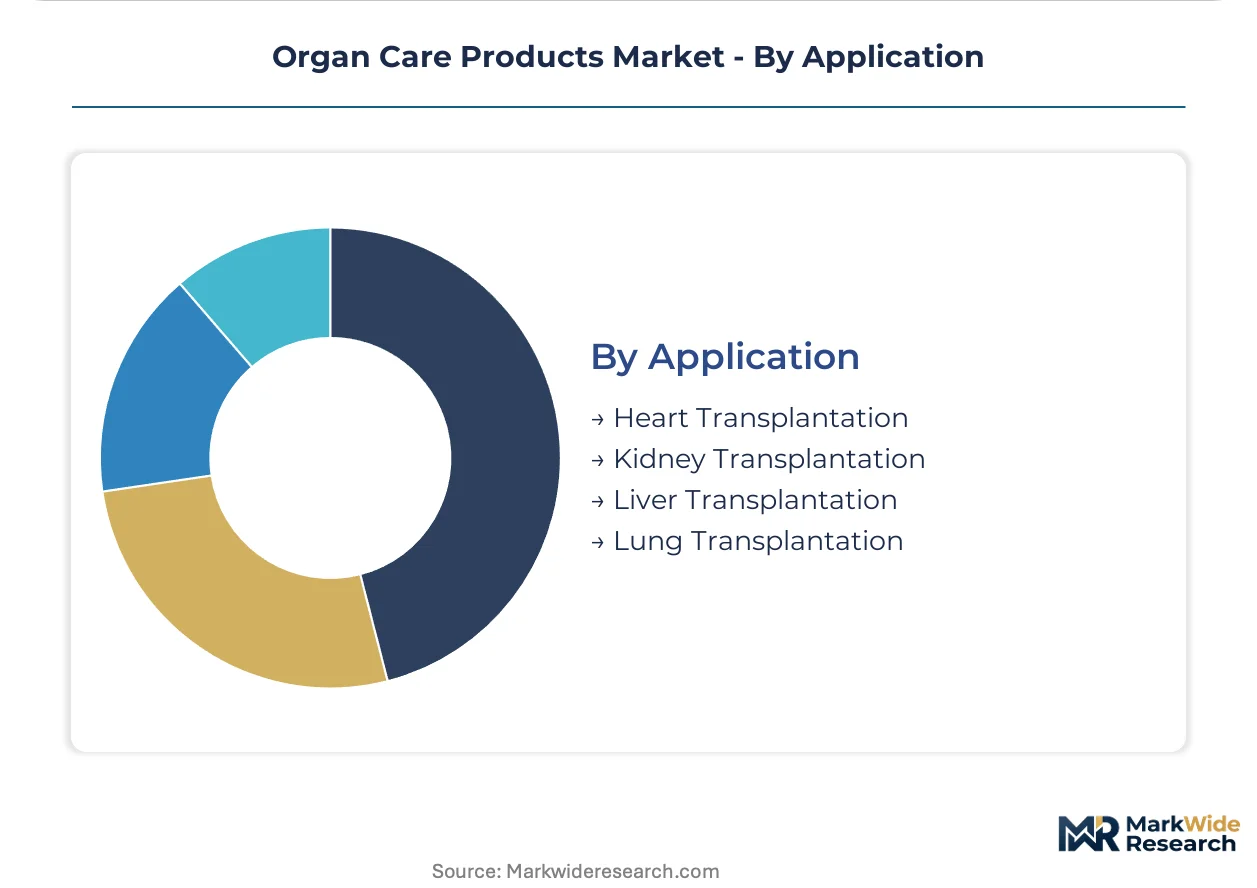
| Segmentation | Product Type: Preservation Solutions, Pocket Thermometers, Organ Transport Containers, Organ Perfusion Systems End User: Hospitals, Organ Transplant Centers, Research Laboratories, Tissue Banks Technology: Cold Storage, Active Cooling, Hypothermic Machine Perfusion, Rewarming Techniques Application: Heart Transplantation, Kidney Transplantation, Liver Transplantation, Lung Transplantation |
| Companies Covered | TransMedics Inc., Paragonix Technologies, XVIVO Perfusion AB, Organ Recovery Systems, OrganOx Limited, Bridge to Life Ltd., Preservation Solutions Inc., Dr. Franz Köhler Chemie GmbH, Essential Pharmaceuticals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Care Products Market Emerging Trajectories
Machine learning analytics are embedding into perfusion consoles, shifting clinical decision-making from empirical time thresholds to real-time organ function prediction. This intelligence layer is redefining competitive differentiation beyond hardware reliability.
Hypothermic oxygenated perfusion is converging with normothermic regional perfusion protocols, creating hybrid temperature management strategies for extended organ transport. European transplant networks are piloting these blended approaches for inter-country organ exchange. The structural consequence is compressing the historical binary between cold static and warm active preservation, forcing vendors to support multi-modal platform architectures.
EMA Medical Device Regulation Article 117 clinical evaluation requirements are tightening evidentiary standards for organ perfusion systems marketed in Europe. Manufacturers must now submit post-market surveillance data demonstrating sustained graft survival outcomes. High-complexity heart-lung platforms face the steepest compliance cost escalation, favoring established players with dedicated regulatory affairs infrastructure.
Hospital procurement committees are unbundling capital equipment from disposable supply agreements, separating console acquisition decisions from multi-year cannulae contracts. This disintermediation exposes standalone disposable pricing to competitive tender pressure. The shift is most pronounced in United States academic medical centers with centralized value analysis committees.
Organ Care Products Market Segmentation
Organ care product purchasing decisions diverge sharply by clinical setting and procedure complexity. Transplant centers prioritize perfusion platforms with embedded metabolic monitoring, while tissue banks optimize around cost-per-unit preservation chemistry. Understanding these buyer archetypes reveals where technology premiums command sustainable pricing power.
Product Type:
Hospital procurement committees weight capital equipment differently than consumable reagents based on reimbursement pathway certainty.
- Preservation Solutions:Single-use chemical formulations—Custodiol, UW solution, and histidine-tryptophan-ketoglutarate—dominate cold static protocols. German university hospitals drive protocol standardization for liver and kidney preservation, creating reference formulations that diffuse across European transplant networks.
- Organ Perfusion Systems:Active metabolite-support platforms integrate console hardware with disposable circuits, cannulae, and real-time monitoring modules. FDA breakthrough device designation pathways compress commercial timelines for normothermic platforms as US transplant centers abandon static cold storage.
- Pocket Thermometers:Handheld temperature verification devices supplement transport quality assurance. These low-cost instruments see concentrated demand from mid-volume transplant programs with hybrid procurement environments.
- Organ Transport Containers:Passive insulated vessels with phase-change cooling elements serve backup and short-haul logistics. Tissue banks in India favor these for cost-sensitive kidney preservation during national organ allocation network expansion.
Organ perfusion systems lead volumes today; preservation solutions are gaining share fastest through recurring revenue expansion.
End User:
Institutional scale and procedure specialization determine technology sophistication thresholds across buyer categories.
- Organ Transplant Centers:High-volume academic medical centers with dedicated perfusionist staff drive normothermic platform adoption. These facilities capture premium pricing for heart-lung systems with embedded machine learning analytics.
- Hospitals:General medical centers with occasional transplant activity favor hypothermic perfusion for cost containment. Their procurement committees unbundle capital equipment from disposable agreements, exposing cannulae pricing to competitive tender pressure.
- Research Laboratories:Ex-vivo organ assessment protocols generate demand for modular perfusion platforms with customizable flow parameters. EMA Medical Device Regulation Article 117 clinical evaluation requirements tighten evidentiary standards for systems used in European research settings.
- Tissue Banks:Inventory management priorities concentrate procurement around preservation solutions and passive transport containers. These buyers exhibit extreme price sensitivity on per-unit chemistry costs.
Organ transplant centers command the steepest technology premiums; research laboratories are climbing the fastest as ex-vivo assessment protocols proliferate.
Technology:
Temperature management philosophy—passive versus active, hypothermic versus normothermic—structures competitive differentiation and regulatory pathway complexity.
- Hypothermic Machine Perfusion:Active cold perfusion with oxygenated solutions extends viable ischemic windows for marginal donor organs. XVIVO Perfusion AB anchors European market positioning with specialized platforms and organ preservation research infrastructure.
- Cold Storage:Static ice-based preservation remains embedded in emergency protocols and resource-constrained settings. Legacy integration requirements complicate supply chain operations for hybrid procurement environments.
- Active Cooling:Portable refrigeration systems with precise temperature telemetry support inter-hospital organ exchange. European transplant networks pilot these for inter-country logistics.
- Rewarming Techniques:Controlled temperature elevation protocols bridge hypothermic preservation to implantation readiness. These methods concentrate in heart transplantation where shorter acceptable ischemic windows command premium system pricing.
Cold storage retains installed base dominance; hypothermic machine perfusion is expanding most quickly through marginal donor utilization.
Application:
Organ-specific ischemic tolerance thresholds and procedure volumes create divergent technology requirements and pricing architectures.
- Kidney Transplantation:Higher procedure volumes and longer acceptable cold ischemia times sustain diverse preservation modality adoption. India transplant infrastructure buildout concentrates initial perfusion platform deployment in this segment.
- Heart Transplantation:Narrow ischemic windows and functional assessment complexity drive normothermic system premiums. Machine perfusion enables utilization of donation-after-circulatory-death hearts previously discarded.
- Lung Transplantation:Ex-vivo lung perfusion protocols require specialized ventilation and perfusion circuits. EMA Class III active implantable system regulations impose extended clinical validation burdens.
- Liver Transplantation:Steatotic liver utilization expansion creates demand for perfusion platforms with metabolic monitoring. Extended criteria donor protocols in US academic centers validate machine perfusion for previously discarded organs.
Kidney transplantation leads procedure volumes; heart transplantation commands the steepest technology premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor European protocol development for ex-vivo organ assessment, driving reference implementations that diffuse across transplant networks. United States academic medical centers dominate normothermic platform adoption through FDA breakthrough device pathways. India's national organ allocation expansion creates infrastructure buildout demand for perfusion technologies.
United States
FDA breakthrough device designation accelerates commercial timelines for novel perfusion platforms as transplant centers abandon static cold storage. The agency's expedited premarket review pathway reduces regulatory friction for console innovators. Boston and Houston academic medical centers lead heart-lung system deployment with embedded machine learning analytics.
Germany
University hospitals in Heidelberg and Berlin drive clinical evidence generation for ex-vivo organ assessment protocols. EMA Medical Device Regulation mandates extended clinical performance datasets for Class III active implantable systems. Baden-Württemberg's medical technology cluster concentrates hypothermic perfusion research infrastructure.
India
National organ allocation network expansion creates first-mover positioning for perfusion vendors as liver and kidney transplantation volumes scale. CDSCO medical device registration pathways are streamlining for active perfusion consoles. Tamil Nadu and Maharashtra transplant hubs pilot machine perfusion for extended criteria donor utilization.
United Kingdom
NHS specialized commissioning frameworks are developing reimbursement codes for ex-vivo organ perfusion procedures. MHRA post-Brexit regulatory alignment maintains CE marking recognition for European-approved systems. London transplant centers coordinate multi-center outcome aggregation for real-world evidence generation.
Japan
PMDA regenerative medicine product pathways accommodate perfusion platforms as combination device-biologic systems. METI healthcare technology assessment programs evaluate cost-effectiveness of active preservation versus static cold storage. Kanto region university hospitals anchor Asia-Pacific clinical validation networks for normothermic systems.
Organ Care Products Market Vendor Landscape
Global majors compete with regional champions across regulatory pathway sophistication and disposable manufacturing scale. The vendor base concentrates around three vertically integrated console producers with proprietary cannulae lock-in, limiting second-source procurement options. Specialists in hypothermic platforms and cold storage transport devices occupy distinct positioning tiers. Dominant competitive moves include strategic partnerships with university hospitals for clinical evidence generation and geographic expansion into India's transplant infrastructure buildout.
Among US-based platform innovators, TransMedics Inc. and Paragonix Technologies exemplify divergent technology archetypes—normothermic machine perfusion versus specialized cold storage with embedded telemetry. XVIVO Perfusion AB anchors European market positioning through its Swedish research infrastructure. These three represent the consolidated core around which mid-volume transplant programs negotiate procurement.
| Leading Market Players |
|---|
| TransMedics Inc. |
| Paragonix Technologies |
| XVIVO Perfusion AB |
| Organ Recovery Systems |
| OrganOx Limited |
| Bridge to Life Ltd. |
| Preservation Solutions Inc. |
| Dr. Franz Köhler Chemie GmbH |
| Essential Pharmaceuticals LLC |
| Others |
Supply Flow & Price Mechanics
Medical-grade polymer resin indices cascade through perfusion circuit manufacturing into three-tier pricing structures across premium, standard, and economy levels, with console-integrated disposable bundles commanding premiums against standalone procurement.
Pricing Analysis
Input-cost pass-through from specialized biocompatible materials and single-use circuit assemblies drives margin compression at mid-volume transplant programs. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough device certification status and embedded metabolic monitoring capabilities. Price erosion runs through standard-tier hypothermic platforms as hospital value analysis committees unbundle capital equipment from disposable agreements. Tissue banks exhibit extreme price sensitivity on per-unit preservation chemistry, while academic medical centers absorb premium normothermic system pricing.
Supply Chain Analysis
Cross-border freight costs for temperature-controlled organ transport containers concentrate procurement decisions around regional manufacturing footprints in the United States, Germany, and Sweden. Console production draws from medical-grade silicone supply chains and precision pump component ecosystems anchored in Baden-Württemberg and New England manufacturing clusters. Single-source vulnerability pervades proprietary cannulae lock-in from vertically integrated platform vendors. Distribution runs through GPO contracts and direct hospital system agreements with limited secondary sourcing options.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organ care products constitute a late-cycle quality story as transplant centers abandon static cold storage for active metabolite-support platforms with embedded functional assessment capabilities.
For Market Incumbents: Acquire disposable circuit manufacturing capabilities to defend against procurement committee unbundling pressures. Consolidate regulatory affairs infrastructure for EMA Medical Device Regulation Article 117 compliance cost absorption. Expand perfusionist training program partnerships to constrain deployment velocity for emerging normothermic competitors. For New Entrants and Emerging Players: Launch via research laboratory modular platform channels to bypass entrenched hospital GPO contracts. Target India's transplant infrastructure buildout as liver and kidney volumes scale under national organ allocation network expansion. Develop CPT Category III reimbursement code evidence packages to reduce hospital capital risk for platform adoption. For Investors and Strategic Acquirers: Asymmetric upside sits with hypothermic-to-normothermic platform migration specialists with captive European research infrastructure. Long-term viability over the next decade hinges on real-world evidence generation capabilities for payer negotiation leverage. Monitor FDA breakthrough device designation velocity as inflection indicator for commercial timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures exclusive perfusion console placement through multi-year cannulae supply agreements with academic medical centers. |
| CE Marking Pathway | Accelerates European market entry under EMA Medical Device Regulation for Class III active implantable systems. |
| Software Companion Development | Embeds machine learning analytics into perfusion consoles for real-time organ function prediction capabilities. |
| Reimbursement Strategy | Generates clinical evidence packages for emerging CPT Category III codes covering ex-vivo organ perfusion procedures. |
| Geographic Expansion | Establishes first-mover positioning in India's Tamil Nadu and Maharashtra transplant hubs during infrastructure buildout. |
Methodological Framework
Multiple input streams — transplant surgeon interviews, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers — were reconciled against FDA 510(k) filings, EMA submission databases, CMS Medicare reimbursement data, and hospital procurement records. Bottom-up unit economics from console and disposable sales combined with top-down transplant procedure volume estimates across the analysis window.
Historical adoption curves for normothermic versus hypothermic platforms were cross-referenced against expert panel inputs on protocol standardization timelines. Segmentation modeling incorporated product type, end-user institution scale, temperature management technology, and organ-specific application dimensions. CAGRs were derived from procedure volume trajectories and technology substitution elasticity assumptions for marginal donor organ utilization expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement code development delays and perfusionist workforce scarcity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Medical Products Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Global Clinical Trial Consumables Market