
 Cytotoxicity Assays Market | 2026-2036
Cytotoxicity Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Cytotoxicity Assays Market Analysis
Biopharmaceutical manufacturing is repositioning cytotoxicity assays from late-stage confirmatory tools to front-line screening instruments in early drug development. Thermo Fisher Scientific leverages its automated platform portfolio to capture workflow integration demand across large-molecule pipelines. Danaher Corporation sustains competitive density through fluorescence and imaging system specialization that reduces assay variability. Merck KGaA anchors European supply relationships with colorimetric reagent manufacturing scale that serves contract research organizations.
Cytotoxicity assays measure cellular metabolic activity, membrane integrity, or DNA content to quantify compound-induced cell death, typically employing tetrazolium salts, resazurin dyes, or luciferin-luciferase chemiluminescence systems with detection thresholds below nanomolar ranges. Their primary commercial purpose is to filter therapeutic candidates before in vivo studies, reducing downstream attrition costs in pharmaceutical development. ATP assays and fluorescence assays lead current revenue contribution due to sensitivity advantages in high-throughput environments, while imaging systems represent the fastest-expanding technology segment as spatial resolution becomes critical for complex co-culture models. Flow cytometry occupies a mature but stable position where multi-parameter analysis justifies premium pricing in immuno-oncology applications.
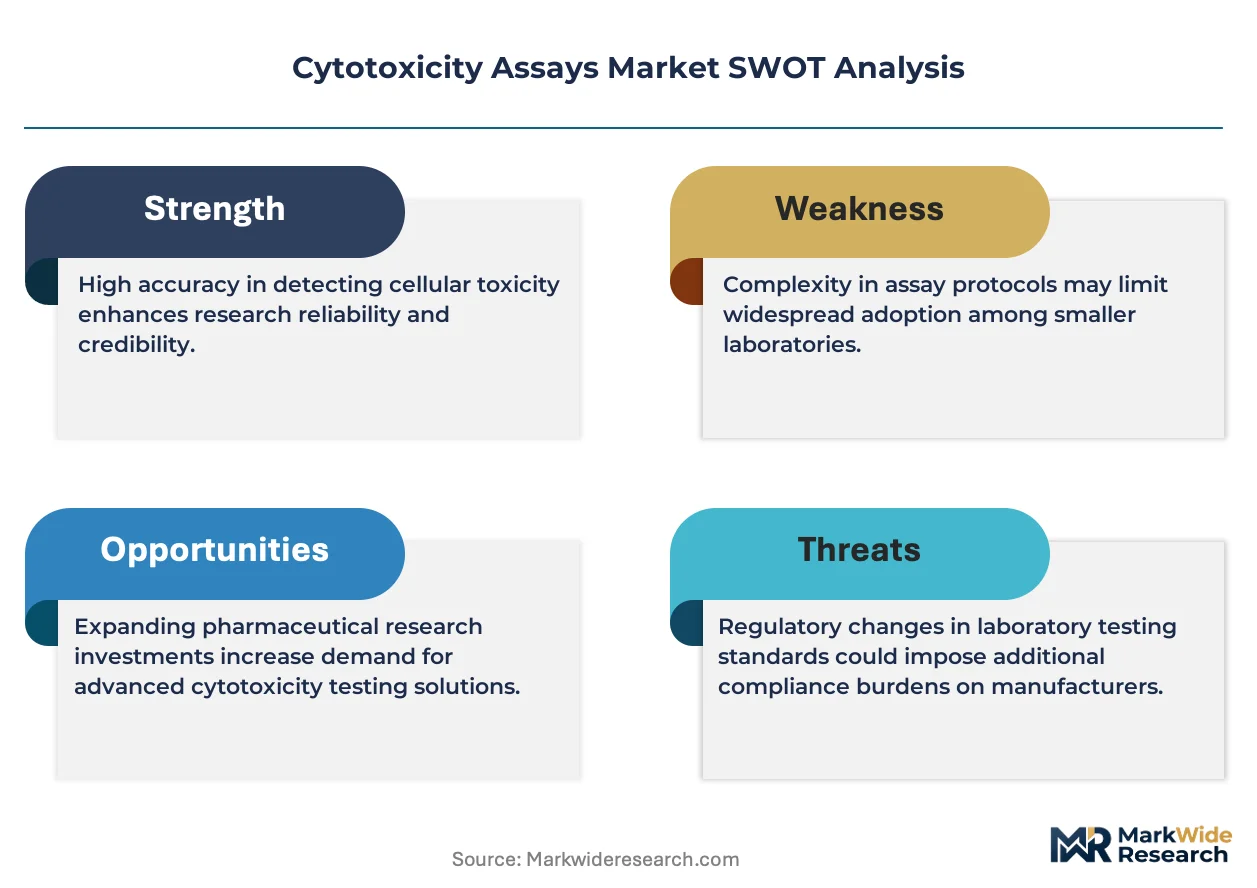
FDA guidelines on in vitro toxicology, EMA's REACH-aligned reduction mandates for animal testing, and China's NMPA acceptance of alternative methods collectively reshape validation standards and procurement criteria for assay providers. ISO 10993 biocompatibility frameworks further tighten reproducibility requirements, particularly for medical device leachate testing that now parallels pharmaceutical workflows. Stakeholders must monitor regulatory convergence between FDA and EMA on assay qualification thresholds, as divergent acceptance criteria could fragment product development strategies across development programs.
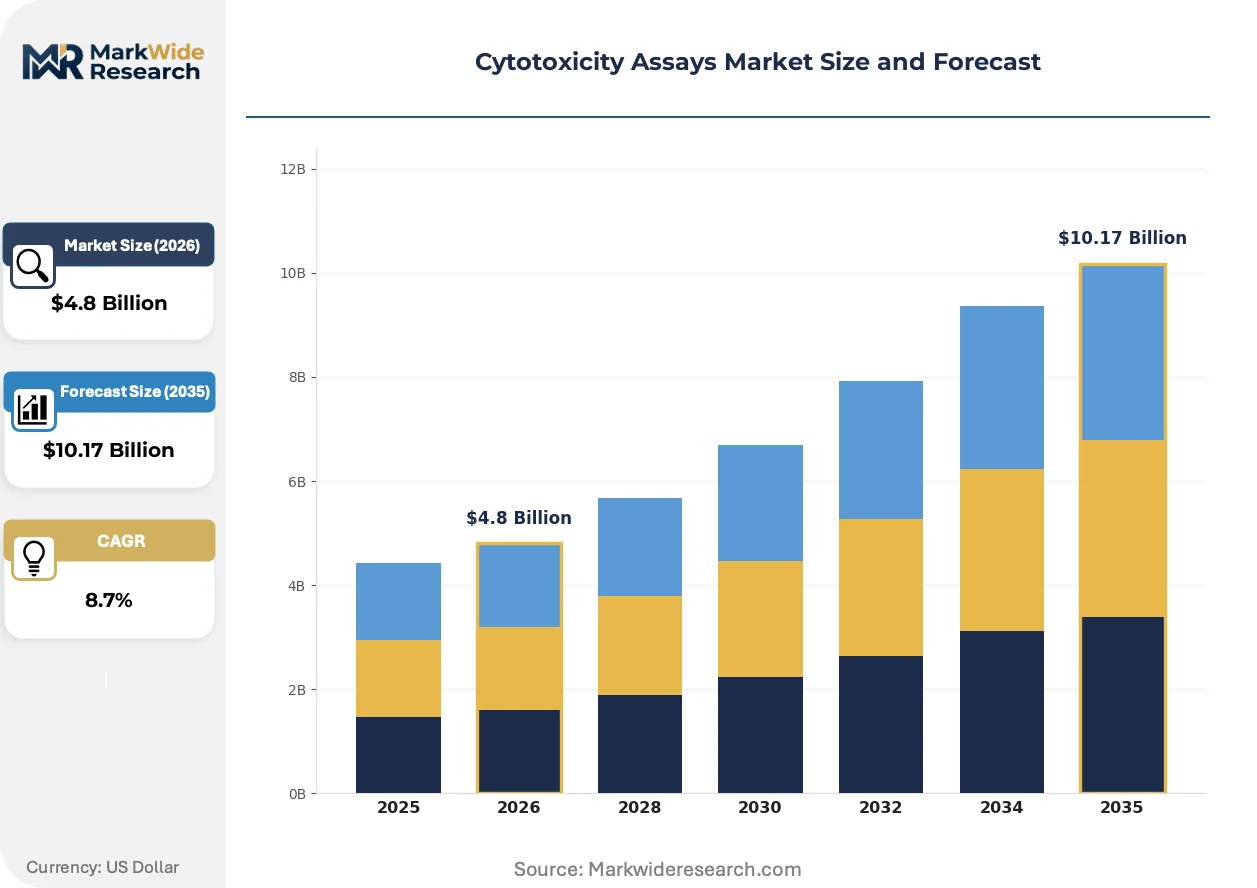
Market Dynamics
FDA and EMA alignment on in vitro toxicology validation is compressing assay qualification timelines while fragmenting procurement criteria across development programs. Biopharmaceutical sponsors now face parallel submission requirements that demand dual-track assay characterization before IND enabling studies.
Growth Catalysts
- REACH-aligned reduction mandates:EMA's animal testing reduction framework accelerates contract research organization adoption of validated in vitro alternatives for safety pharmacology screening.
- High-throughput automation:Robotics integration in compound library screening reduces per-assay labor costs below manual thresholds, enabling earlier toxicity triage in discovery pipelines.
- China NMPA acceptance:China's national medical products administration now recognizes OECD-validated alternative methods, opening domestic biopharma procurement to imported assay platforms.
Market Restraints
- Reagent supply concentration:Tetrazolium salt and luciferase reagent manufacturing clusters in Germany and Switzerland create single-source vulnerability for colorimetric and ATP assay workflows.
- ISO 10993 biocompatibility timeline:Medical device leachate testing under tightened reproducibility frameworks extends assay validation cycles by 4-6 months for contract laboratories.
- Primary cell substitution:Immortalized cell line assays face displacement by patient-derived organoid models that command 3-5x per-well cost premiums.
Strategic Opportunities
- India CDSCO pathway:India's central drugs standard control organization is drafting alternative method acceptance guidelines that would unlock domestic generic developer demand for cost-validated assays.
- 3D co-culture imaging:Spatial biology platforms integrating high-content imaging with microfluidic perfusion represent white space between standalone fluorescence readers and full organ-on-chip systems.
- Japan PMDA harmonization:Japan's pharmaceuticals and medical devices agency is aligning with ICH M3(R2) toxicology guidelines, creating regulatory tailwind for assay vendors with OECD-validated portfolios.
Industry Challenges
- Multi-parameter cytometry expertise:Flow cytometry assay development requires specialized immunophenotyping talent that concentrates in Boston, Basel, and Singapore hubs.
- Legacy LIMS integration:Automated cytotoxicity platforms face protocol reconfiguration costs when interfacing with incumbent laboratory information management systems at mid-scale pharmaceutical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytotoxicity Assays Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assay Type: Colorimetric Assays, Fluorescence Assays, ATP Assays, Microscopy Assays Application: Drug Discovery, Toxicology Testing, Cancer Research, Cell Viability Studies Technology: Flow Cytometry, Automated Platforms, High-Throughput Screening, Imaging Systems End User: Pharmaceutical Companies, Academic Institutions, Research Laboratories, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Merck KGaA, Promega Corporation, PerkinElmer, Roche, Sartorius AG, Bio-Rad Laboratories, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytotoxicity Assays Market Emerging Trajectories
Artificial intelligence is reshaping assay data interpretation while regulatory convergence pressures are standardizing validation protocols across major pharmaceutical markets.
High-content imaging systems are integrating deep learning algorithms for real-time toxicity classification. Mid-tier biopharmaceutical sponsors in Germany and Massachusetts are adopting these platforms at 18-month replacement cycles. The technology is integrating phenotypic profiling with mechanistic toxicology, compressing the gap between screening hits and pathway hypotheses.
EMA's updated guidance on in vitro methods for genotoxicity testing now mandates positive control characterization that exceeds OECD TG 487 requirements. Contract research organizations serving European sponsors must retool Ames II and micronucleus assay workflows. Immuno-oncology developers with dual US-EU filing strategies face the steepest compliance reconfiguration costs.
Consolidated purchasing through centralized procurement functions at top-20 pharmaceutical sponsors is displacing decentralized laboratory autonomy. Preferred vendor agreements now bundle reagent supply with platform service contracts, squeezing standalone assay kit manufacturers. This concentration is most visible in California and New Jersey, where three sponsors account for one-quarter of North American high-throughput screening reagent demand.
Cytotoxicity Assays Market Segmentation
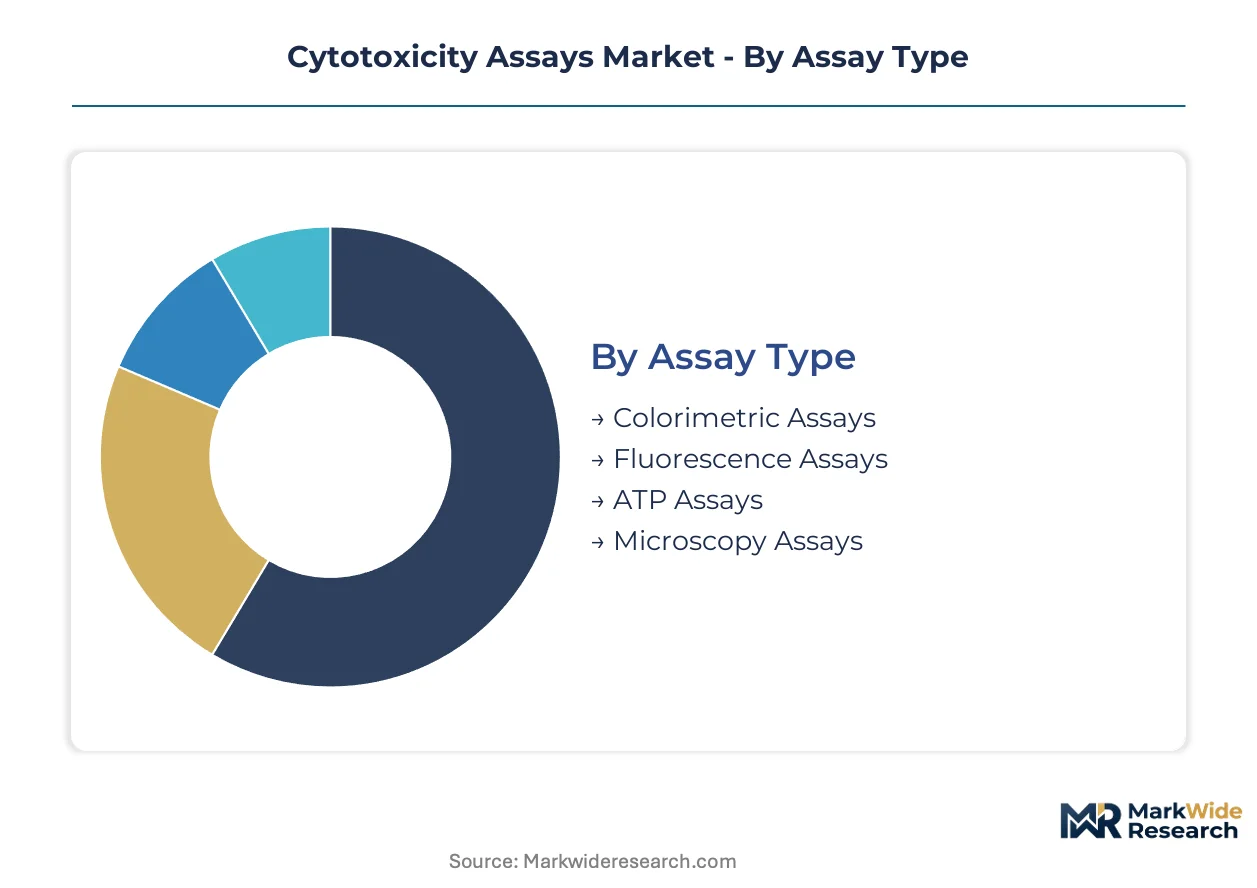
Cytotoxicity assay segmentation reflects divergent capital requirements across detection modalities and automation tiers. Pharmaceutical procurement teams weight sensitivity specifications against throughput economics when allocating budget across assay categories.
Assay Type:
Capital intensity varies sharply across detection chemistries, with luminescence infrastructure demanding the highest upfront platform investment.
- ATP Assays:Luciferin-luciferase chemiluminescence systems detect ATP depletion with sub-nanomolar sensitivity, making them indispensable for high-throughput screening at Thermo Fisher Scientific automated workstations in Massachusetts and California biotech clusters. Reagent supply concentrates in German and Swiss manufacturing hubs, creating procurement vulnerability for North American sponsors.
- Fluorescence Assays:Resazurin and calcein-AM dyes enable multiplexed endpoint detection through standard plate readers, with Danaher Corporation's imaging specialization reducing well-to-well variability below 5% in contract research organization workflows. Demand clusters in Basel and Boston immuno-oncology pipelines where multi-parameter readouts justify premium reagent costs.
- Colorimetric Assays:Tetrazolium salt reduction (MTT, XTT, WST-8) produces formazan precipitates quantified by absorbance spectroscopy; Merck KGaA's European manufacturing scale serves cost-sensitive academic laboratories.
- Microscopy Assays:Direct cell counting and morphological assessment requires trained operator intervention, limiting adoption to specialized toxicology laboratories with dedicated imaging infrastructure.
ATP assays absorb the bulk of installed capacity in high-throughput pharmaceutical environments; fluorescence assays are expanding most quickly through multiplexing advantages in complex co-culture models.
Application:
End-use economics segment sharply between revenue-generating pharmaceutical workflows and grant-funded academic research.
- Drug Discovery:Lead optimization pipelines in San Francisco and Cambridge deploy cytotoxicity screening as front-line filters before IND-enabling studies, with per-compound screening costs below $50 in automated 384-well formats. FDA in vitro toxicology guidelines compress assay validation timelines while expanding the addressable market for qualified alternatives.
- Toxicology Testing:EMA REACH-aligned mandates accelerate substitution of animal studies with validated in vitro methods, particularly for genotoxicity assessment under OECD TG 487 frameworks. Contract research organizations in Germany and the Netherlands face steepest compliance reconfiguration costs.
- Cancer Research:Immuno-oncology developers in Singapore and Basel hubs leverage cytotoxicity endpoints for CAR-T potency assessment, with patient-derived organoid models displacing immortalized lines at 3-5x cost premiums.
- Cell Viability Studies:Academic laboratories in China and India prioritize cost-per-assay minimization, driving demand for colorimetric alternatives over luminescence systems.
Drug discovery commands the largest absolute spending; toxicology testing is climbing the fastest as regulatory substitution mandates widen.
Technology:
Automation tier determines both capital deployment and labor substitution economics across installation bases.
- Automated Platforms:Integrated robotics for plate handling, reagent dispensing, and detection reduce per-assay labor to below manual thresholds, with 18-month replacement cycles visible in mid-tier German biopharmaceutical sponsors. Thermo Fisher Scientific's workflow integration captures consolidated procurement at top-20 pharmaceutical sponsors.
- High-Throughput Screening:384-well and 1536-well density formats enable single-day compound library evaluation, with three California and New Jersey sponsors accounting for disproportionate North American reagent demand through centralized purchasing functions.
- Imaging Systems:High-content platforms integrate deep learning for real-time toxicity classification, with spatial resolution critical for 3D co-culture and microfluidic perfusion models.
- Flow Cytometry:Multi-parameter immunophenotyping justifies premium pricing in immuno-oncology applications, though specialized talent concentrates in Boston, Basel, and Singapore hubs.
Automated platforms dominate current installed value; imaging systems are gaining share fastest through phenotypic profiling convergence with mechanistic toxicology.
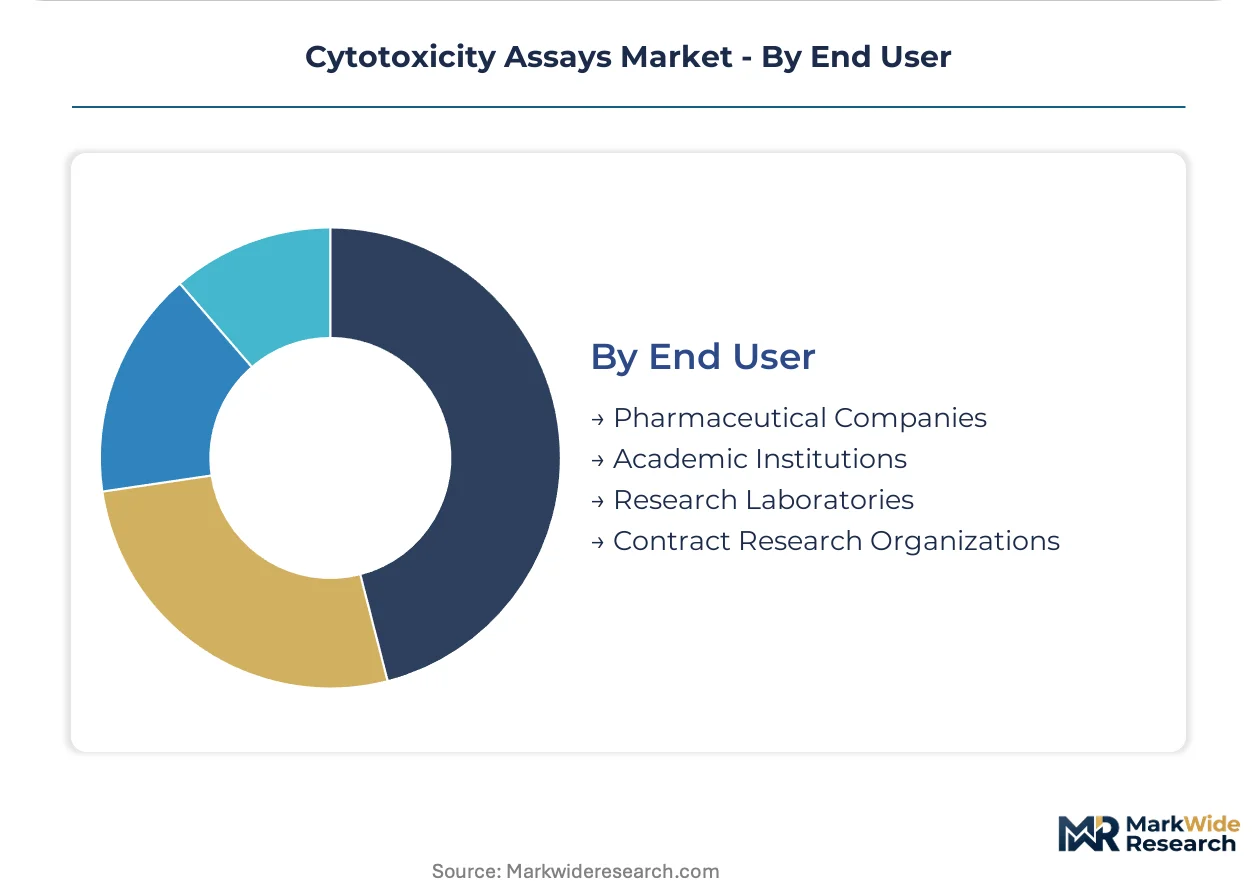
End User:
Customer procurement sophistication creates distinct service requirements across organizational scales.
- Pharmaceutical Companies:Centralized procurement functions at top-20 sponsors bundle reagent supply with platform service contracts, displacing decentralized laboratory autonomy and squeezing standalone kit manufacturers.
- Contract Research Organizations:European CROs face dual-track FDA-EMA assay characterization requirements before IND-enabling studies, fragmenting validation protocols across development programs.
- Academic Institutions:Grant-funded laboratories in China and India prioritize cost-validated colorimetric assays over luminescence systems with higher per-well economics.
- Research Laboratories:Mid-scale pharmaceutical sites encounter legacy LIMS integration costs when interfacing automated cytotoxicity platforms with incumbent information management systems.
Pharmaceutical companies concentrate the highest per-site spending; contract research organizations are expanding most quickly through regulatory-driven outsourcing of validation-intensive workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts Life Sciences Center tax incentives and California's R&D tax credits concentrate biopharmaceutical infrastructure in designated enterprise zones. These fiscal instruments accelerate facility deployment for automated assay platforms. Procurement clusters in these zones absorb disproportionate shares of high-throughput screening capacity.
United States
FDA in vitro toxicology guidelines compress assay validation timelines while expanding qualified alternative method adoption. The 21st Century Cures Act provisions accelerate pathway designations for non-animal testing submissions. San Francisco and Cambridge biotech clusters deploy cytotoxicity screening as front-line filters before IND-enabling studies.
Germany
EMA REACH-aligned reduction mandates accelerate contract research organization procurement of validated in vitro alternatives. Federal Ministry of Education and Research funding streams support toxicology infrastructure modernization. Basel-proximate Rhine-Main biopharma corridor sustains concentrated demand for fluorescence assay platforms.
China
NMPA acceptance of OECD-validated alternative methods opens domestic biopharma procurement to imported assay platforms. National Major Scientific Equipment Development Program subsidizes high-content imaging infrastructure acquisition. Shanghai and Suzhou biotech parks anchor automated cytotoxicity workflow deployment for domestic drug developers.
India
CDSCO alternative method acceptance guidelines unlock domestic generic developer demand for cost-validated assays. Department of Biotechnology grants support assay platform acquisition at contract research organizations. Hyderabad and Bengaluru biotech corridors concentrate reagent procurement for export-oriented toxicology services.
Switzerland
Swissmedic alignment with ICH M3(R2) toxicology guidelines creates regulatory tailwind for OECD-validated assay portfolios. Federal Act on Research funding instruments sustain precision medicine infrastructure investments. Basel pharmaceutical hub sustains premium reagent demand for immuno-oncology cytotoxicity applications.
Cytotoxicity Assays Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated vendors capturing consolidated procurement at top-20 pharmaceutical sponsors while standalone reagent suppliers serve cost-sensitive academic laboratories. Market structure concentrates around three strategic archetypes: diversified life science conglomerates with workflow integration capabilities, specialized detection technology vendors with fluorescence and imaging expertise, and European reagent manufacturers with colorimetric scale advantages. Competitive dynamics center on M&A activity for platform portfolio expansion and strategic partnerships for regulatory validation co-development.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify workflow integration strategies that bundle automated platforms with service contracts. Merck KGaA anchors European supply relationships through reagent manufacturing scale. These three entities represent distinct competitive positions: Thermo Fisher captures consolidated procurement through automated workstation portfolios, Danaher reduces assay variability through imaging specialization, and Merck KGaA serves contract research organizations with cost-optimized colorimetric production.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Merck KGaA |
| Promega Corporation |
| PerkinElmer |
| Roche |
| Sartorius AG |
| Bio-Rad Laboratories |
| Lonza Group |
| Others |
Supply Flow & Price Mechanics
EMA REACH-aligned reduction mandates for animal testing gate qualified supply access and premium-tier pricing power for OECD-validated assay portfolios. Biopharmaceutical sponsors in Germany and Switzerland now pay lead-time premiums for dual-source qualified reagents that satisfy both FDA and EMA submission requirements.
Pricing Analysis
Lead-time compression commands 15-25% premiums for ATP assay reagents with sub-8-week delivery windows against spot inventory discounts for standard tetrazolium salts. Pricing stratifies across premium, standard, and economy tiers based on OECD validation status and after-sales technical support bundling. Cost compression in colorimetric workflows is intensifying as Chinese manufacturers enter WST-8 substrate production. Academic laboratories in India and China exhibit highest price sensitivity, while immuno-oncology developers in Basel and Boston accept premium luminescence pricing for lot-to-lot consistency.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for luciferase and tetrazolium salt inputs across all top-20 pharmaceutical sponsors. Manufacturing concentrates in Germany, Switzerland, and China, with Swiss and German facilities anchoring high-purity reagent production and Chinese sites scaling colorimetric substrate output. Raw material dependencies center on firefly luciferase extracts, resazurin dye precursors, and specialized microplate polymers. Single-source vulnerability persists for GMP-grade luciferin amid limited qualified fermentation capacity. Distribution runs through authorized distributor networks with direct-to-laboratory fulfillment for high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cytotoxicity assays market has become a vertical-integration race where control over reagent manufacturing determines margin capture. Players are pursuing backward integration into GMP-grade substrate production to escape German-Swiss supply bottlenecks.
For Market Incumbents: To counter displacement by patient-derived organoid models, consolidate fluorescence detection IP through targeted acquisition of high-content imaging specialists and expand captive luciferase fermentation capacity in Singapore or South Korea to dilute European supply concentration risk. For New Entrants and Emerging Players: Enter via white-space 3D co-culture imaging platforms that bridge standalone plate readers and full organ-on-chip systems, targeting mid-tier German biopharmaceutical sponsors with 18-month equipment replacement cycles and regulatory validation partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: CDSCO alternative method guideline publication is the leading indicator that Indian contract research organization demand will inflect toward cost-validated assay platforms. Five-to-ten-year viability favors vendors with dual FDA-EMA qualification capabilities and reagent manufacturing scale. Acquisition targets should display OECD-validated portfolios and established distributor relationships in Hyderabad and Bengaluru.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Partnership | CDSCO guideline alignment unlocks Indian generic developer procurement contracts. |
| Backward Integration into Reagent Manufacturing | Captive luciferase production insulates margins from Swiss-German supply concentration. |
| High-Content Imaging Platform Launch | Deep learning integration addresses 3D co-culture spatial resolution requirements in Basel. |
| Long-term Service Contract Bundling | Preferred vendor agreements at top-20 sponsors displace standalone kit competitors. |
| Geographic Manufacturing Expansion | Singapore production hub reduces lead-time premiums for Asia-Pacific immuno-oncology developers. |
Methodological Framework
Multi-period observation of regulatory submission volumes, assay platform installation bases, and reagent procurement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at contract research organizations, toxicology laboratory directors, and biopharmaceutical procurement managers. Secondary validation drew from FDA in vitro toxicology guidance documents, EMA REACH implementation reports, NMPA alternative method acceptance notices, OECD TG 487 validation studies, and ISO 10993 biocompatibility framework updates. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation models.
Input-output matrices mapped detection chemistry demand to automation tier adoption, application end-use intensity, and geographic regulatory cluster alignment across the projection horizon. Segmentation dimensions spanned assay type, technology tier, end-user organization scale, and regional validation framework. CAGRs derived from regression analysis of historical platform shipment data against biopharmaceutical pipeline expansion rates. Forecast inputs incorporated EMA animal testing reduction mandate implementation timelines and NMPA OECD method recognition pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent FDA-EMA assay qualification threshold scenarios or sustained luciferase supply disruption. Deviation in CDSCO guideline finalization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Histopathology Services Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Assessment Services Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Laboratory Developed Tests Market