
 Laboratory Disposable Products Market | 2026-2036
Laboratory Disposable Products Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Disposable Products Market Outlook
Contract research organizations are collapsing the traditional buyer hierarchy in laboratory disposables, overtaking academic institutions as the largest volume purchasers. Thermo Fisher Scientific leverages its integrated supply chain to dominate North American distribution channels for pipette tips and cell culture vessels. Greiner Bio-One specializes in polymer formulation science, sustaining premium positioning in cell-based assay consumables across European life science clusters.
Laboratory disposable products encompass single-use articles manufactured from medical-grade polymers, natural rubber latex, or silicone elastomers through injection molding, extrusion, or thermoforming processes, designed to eliminate reprocessing costs and cross-contamination pathways in analytical workflows. Gloves and microcentrifuge tubes occupy the highest-volume tiers, with petri dishes capturing concentrated margin pools in cell culture applications where surface modification patents create differentiation barriers. Plastic resins command material share leadership, though biodegradable formulations are gaining fastest in European research facilities facing landfill diversion mandates under the EU Green Deal.
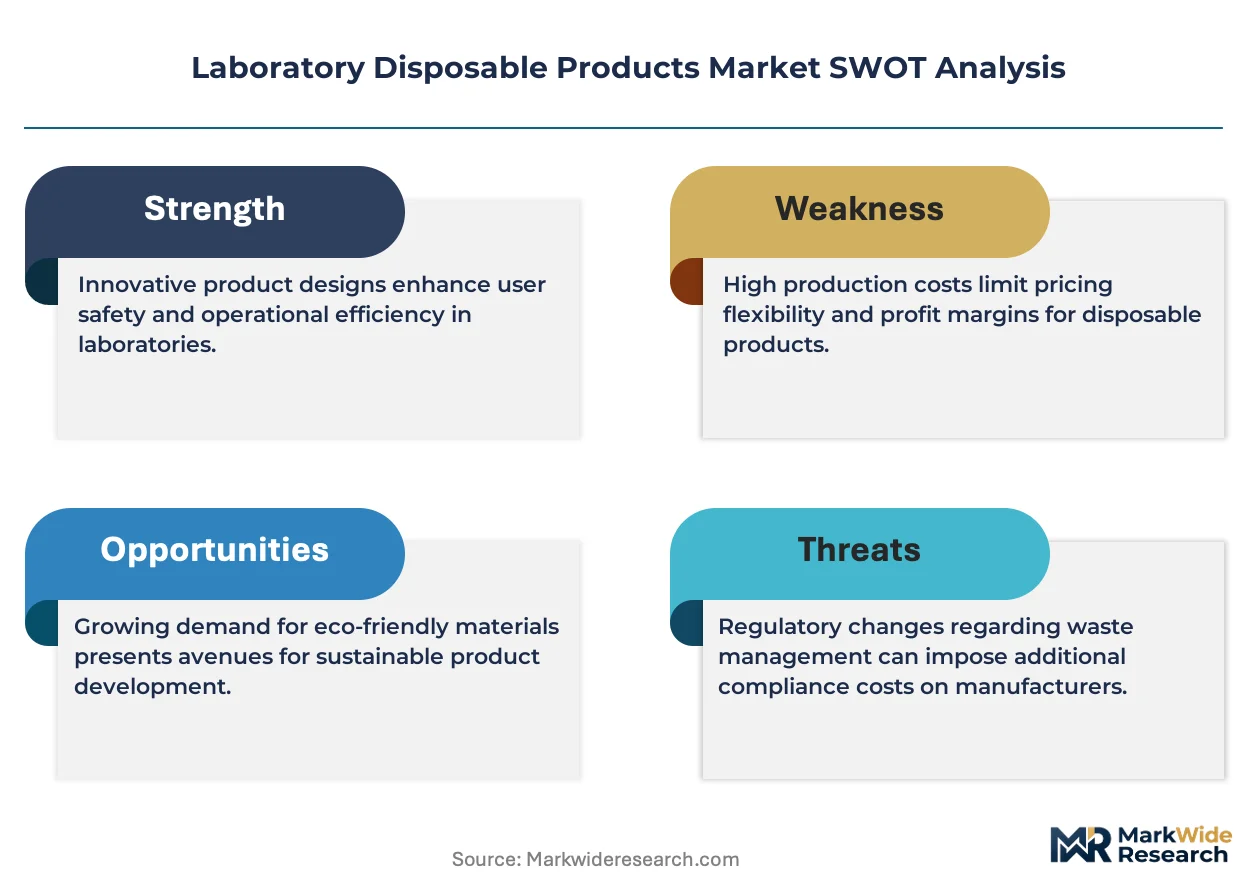
The FDA enforces sterility assurance levels and biocompatibility testing under ISO 10993 for device-bound disposables, while REACH restricts phthalate plasticizers in European-manufactured polymer labware. EMA's Good Manufacturing Practice inspections for pharmaceutical quality control labs indirectly shape vendor qualification standards for disposable suppliers serving drug development pipelines. Stakeholders must monitor evolving extended producer responsibility frameworks for plastic medical waste, as these regulations will reshape material selection criteria and supplier compliance investments without warning.
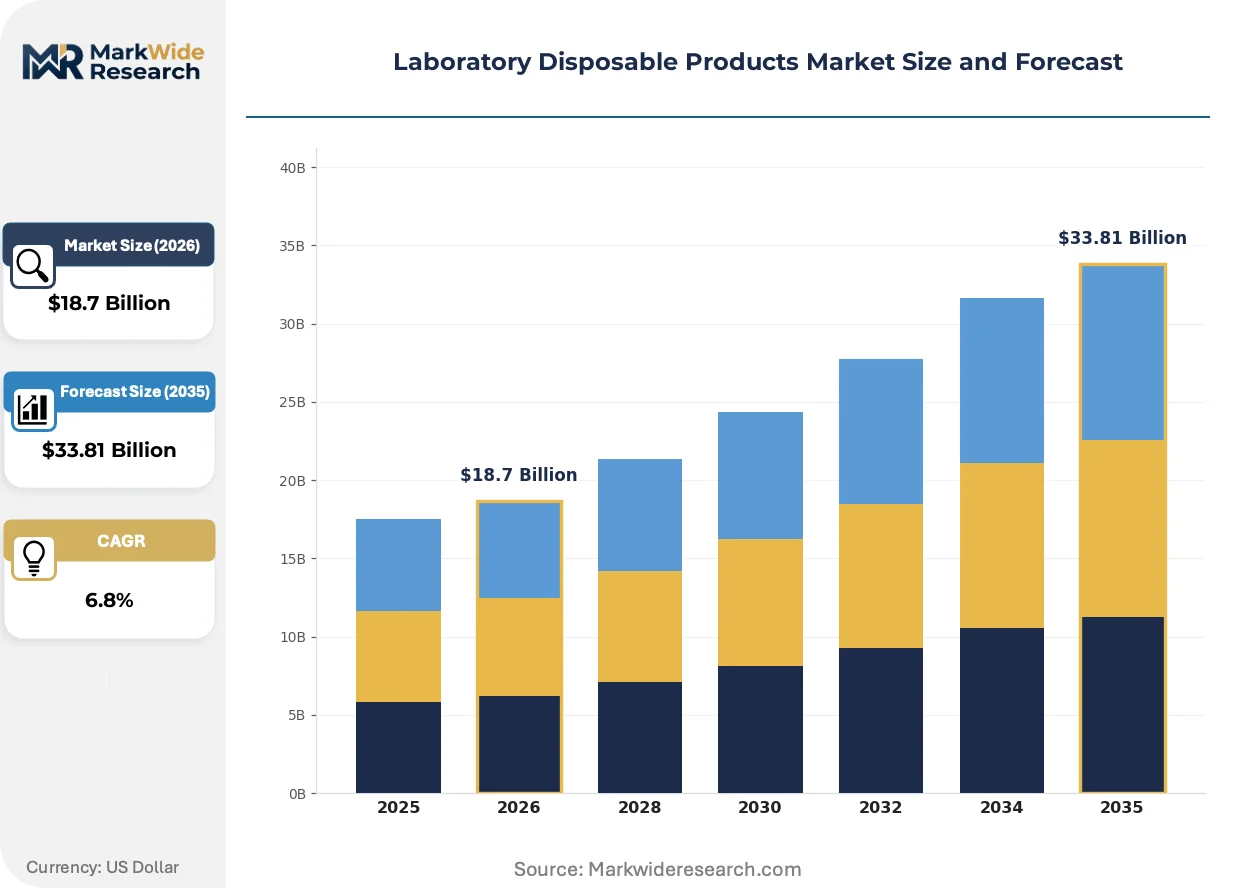
Market Dynamics
Contract research organizations now drive volume procurement of single-use consumables, collapsing the traditional academic-institution buyer hierarchy and forcing suppliers to reconfigure distribution networks around high-throughput screening workflows.
Growth Catalysts
- ISO 10993 biocompatibility mandates:The FDA's sterility assurance requirements for device-bound disposables elevate validation standards, creating captive demand for certified manufacturers.
- Cell culture surface modification patents:Proprietary polymer coatings for petri dishes and cell culture vessels command concentrated margin pools in regenerative medicine applications.
- EU Green Deal landfill diversion mandates:European research facilities accelerate procurement of biodegradable polymer formulations, reshaping material selection criteria across the continent.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene and polystyrene input prices fluctuate with petrochemical feedstock markets, compressing margins for injection-molded consumables.
- Single-source sterilization infrastructure:Gamma irradiation and ethylene oxide capacity concentrates in Germany and the United States, creating geographic supply vulnerability.
- REACH phthalate restrictions:ECHA limitations on plasticizer chemistry constrain formulation flexibility for European-manufactured polymer labware.
Strategic Opportunities
- India's pharmaceutical quality control expansion:CDSCO-aligned GMP inspections for drug development pipelines create vendor qualification demand for disposable suppliers.
- Biodegradable starch-based polymers:Thermoforming advances in polylactic acid blends enable compostable alternatives to petroleum-derived microcentrifuge tubes.
- Direct-to-lab e-procurement platforms:Digital purchasing channels bypass traditional distributor markups for mid-sized biotechnology startups.
Industry Challenges
- Sterility validation timeline compression:Accelerated FDA 510(k) review expectations strain quality assurance staffing at contract manufacturers.
- Legacy ERP integration friction:Hospital-affiliated reference laboratories face data format incompatibilities when consolidating supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Disposable Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Syringes, Petri Dishes, Microcentrifuge Tubes Material: Plastic, Biodegradable, Silicone, Latex Application: Clinical Labs, Research Facilities, Educational Institutions, Industrial Testing End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Clinical Laboratories |
| Companies Covered | Bio-Rad Laboratories, PerkinElmer, Thermo Fisher Scientific, Greiner Bio-One, Sarstedt AG, Corning Incorporated, Becton, Dickinson and Company, VWR International, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Disposable Products Market Strategic Shifts
Material science breakthroughs and procurement digitization are converging to reshape competitive positioning, with sustainability mandates and workflow automation driving parallel transformation tracks.
Plant-derived polylactic acid formulations are displacing petroleum-based polypropylene in microcentrifuge tube production. Academic medical centers in Scandinavia and Germany now specify compostable alternatives in tender documents. This substitution is compressing demand for conventional resin grades and forcing incumbent molders to retool extrusion lines.
EMA's extended producer responsibility frameworks for plastic medical waste are advancing through national implementation across EU member states. The regulations impose material traceability and end-of-life accountability on laboratory consumable suppliers. Cell culture vessel manufacturers serving pharmaceutical quality control labs face the steepest compliance investments.
Consolidated purchasing consortia among hospital-affiliated reference laboratories are aggregating demand for gloves, pipette tips, and syringes. These buying groups negotiate volume-based pricing tiers that displace traditional distributor relationships. The United States exhibits the most pronounced concentration, with multi-hospital systems centralizing procurement decisions.
Laboratory Disposable Products Market Segmentation
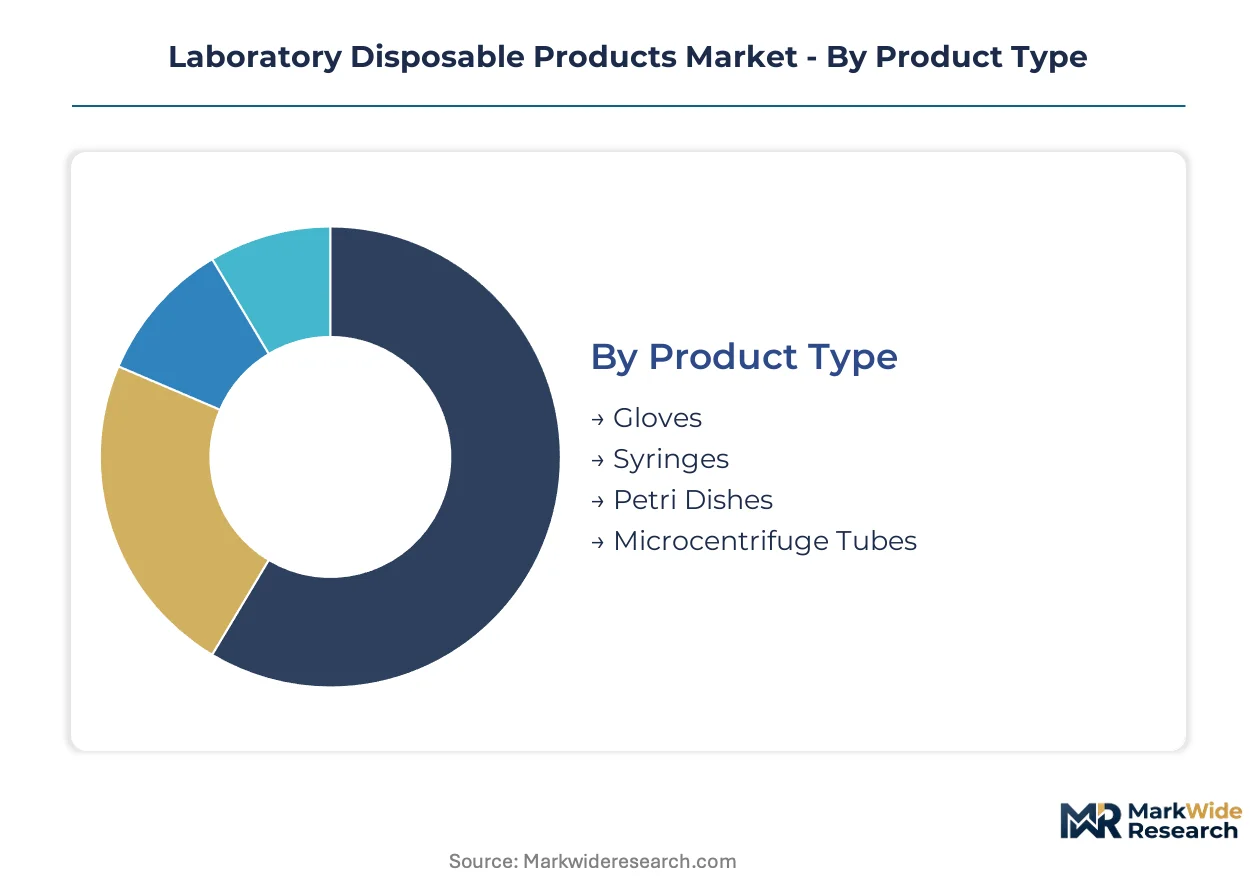
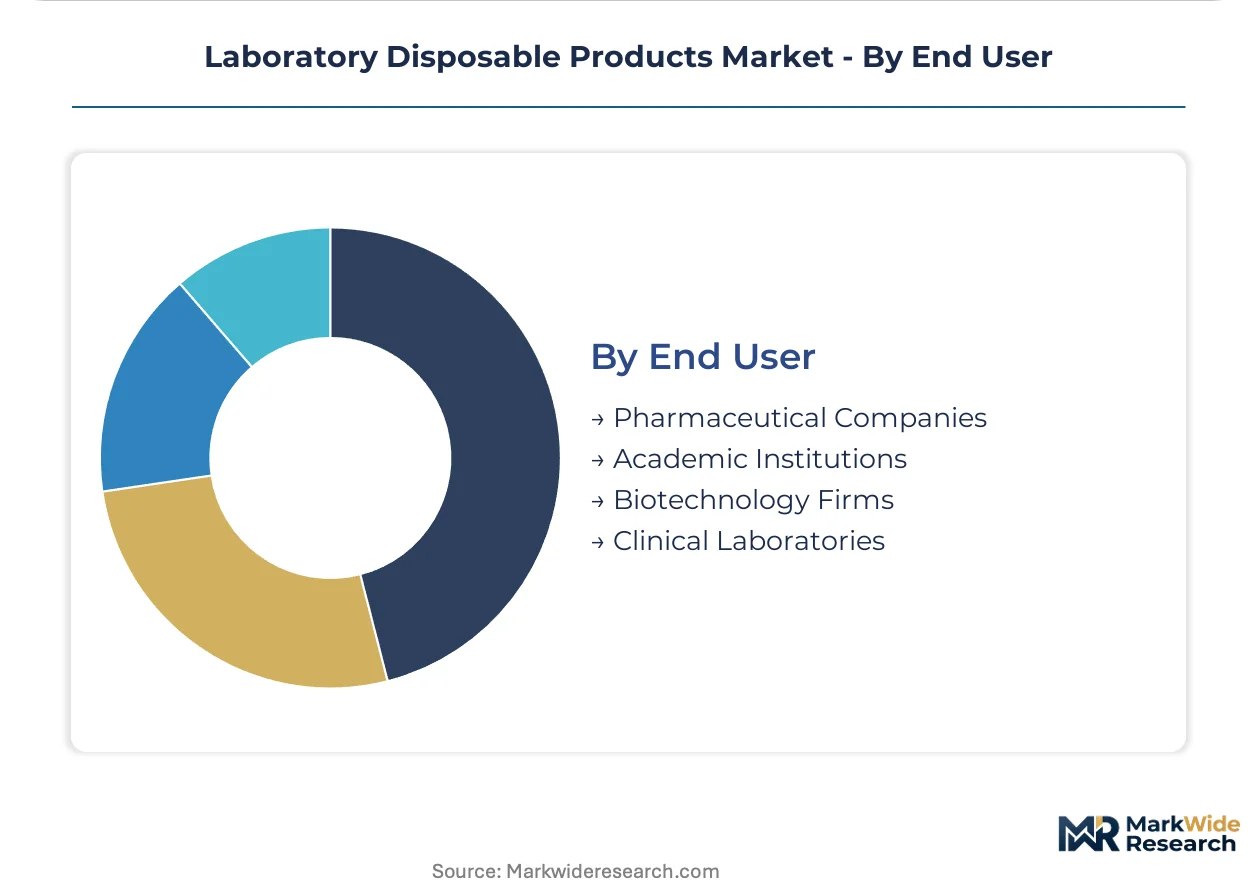
Laboratory disposable products segment across four critical dimensions that determine procurement patterns, regulatory exposure, and margin structures. Each category carries distinct compliance burdens and supply chain configurations that reshape vendor selection criteria.
Product Type:
FDA sterility assurance requirements and ISO 10993 biocompatibility mandates create tiered validation burdens across disposable categories, with device-bound articles facing the steepest certification costs.
- Gloves:Natural rubber latex and nitrile formulations dominate hospital-affiliated reference laboratories, where FDA 510(k) clearance requirements for surgical-grade variants sustain premium pricing tiers. United States procurement concentrates in multi-hospital systems negotiating volume-based contracts that displace traditional distributor relationships.
- Syringes:Medical-grade polypropylene barrels with silicone elastomer plunger tips serve pharmaceutical quality control labs under EMA Good Manufacturing Practice inspections. REACH phthalate restrictions constrain plasticizer flexibility for European-manufactured variants, compressing formulation options.
- Petri Dishes:Surface modification patents for cell culture applications create concentrated margin pools in regenerative medicine workflows.
- Microcentrifuge Tubes:Polypropylene and polylactic acid blends face accelerating substitution pressure from biodegradable alternatives in EU Green Deal jurisdictions.
Gloves handle the majority of throughput; microcentrifuge tubes are gaining share fastest on material substitution trends.
Material:
Cost tier differentiation separates commodity petroleum-derived polymers from premium biodegradable formulations, with certification-grade medical devices occupying a distinct pricing band.
- Plastic:Polypropylene and polystyrene injection-molded consumables face petrochemical feedstock price volatility that compresses margins for high-volume molders serving contract research organizations.
- Biodegradable:Polylactic acid and starch-based thermoformed alternatives command procurement preference in Scandinavian and German academic medical centers facing landfill diversion mandates.
- Silicone:Medical-grade elastomers sustain premium positioning in syringe plunger and sealing applications requiring biocompatibility validation.
- Latex:Natural rubber formulations retain cost advantages in non-sterile industrial testing environments with reduced regulatory exposure.
Plastic resins dominate absolute volume; biodegradable alternatives are expanding most quickly on regulatory procurement preferences.
Application:
Customer type concentration determines workflow automation requirements and sterility validation intensity, with pharmaceutical-facing applications demanding the most stringent vendor qualification.
- Clinical Labs:Hospital-affiliated reference laboratories drive consolidated purchasing consortia for high-throughput screening workflows across multi-site networks.
- Research Facilities:Academic medical centers in Germany and Scandinavia specify compostable alternatives in tender documentation, accelerating material substitution.
- Educational Institutions:Cost-sensitive procurement favors standard-grade plastics with reduced validation documentation.
- Industrial Testing:Quality control labs serving manufacturing supply chains prioritize lot traceability and supply security over premium specifications.
Clinical labs anchor procurement volume; research facilities are climbing fastest on sustainability mandate compliance.
End User:
Procurement authority concentration varies sharply, with consolidated pharmaceutical buyers extracting volume leverage while fragmented academic purchasers face distributor markup capture.
- Pharmaceutical Companies:CDSCO-aligned GMP inspections in India create vendor qualification demand for disposable suppliers serving expanding quality control infrastructure.
- Academic Institutions:Budget constraints and legacy ERP systems create data format incompatibilities when consolidating supplier networks across research consortia.
- Biotechnology Firms:Mid-sized startups increasingly bypass traditional distributors through direct-to-lab e-procurement platforms.
- Clinical Laboratories:Contract research organizations have overtaken academic institutions as the largest volume purchasers, collapsing traditional buyer hierarchies.
Pharmaceutical companies sustain premium pricing tolerance; biotechnology firms are shifting procurement channels fastest on digital platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research organizations concentrate procurement authority in the United States, while European sustainability mandates and Asian pharmaceutical quality control expansion reshape geographic demand patterns across the analysis window.
United States
Hospital-affiliated reference laboratories drive consolidated purchasing consortia for gloves, pipette tips, and syringes. FDA sterility assurance requirements under ISO 10993 elevate validation standards for device-bound disposables. The Boston-Cambridge biotechnology corridor anchors regenerative medicine demand for surface-modified cell culture vessels.
Germany
Academic medical centers in Baden-Württemberg and Bavaria specify compostable alternatives in tender documentation. ECHA REACH restrictions on phthalate plasticizers constrain formulation flexibility for polymer labware. The Rhine-Main cluster concentrates gamma irradiation infrastructure serving pharmaceutical quality control labs.
India
CDSCO-aligned GMP inspections for drug development pipelines create vendor qualification demand for disposable suppliers. The central government's pharmaceutical quality control expansion drives procurement of certified consumables. Hyderabad and Bangalore anchor contract research organization facility buildouts requiring high-throughput screening workflows.
China
NMPA medical device regulations harmonize with international standards for laboratory consumables serving domestic biopharma. The Yangtze River Delta manufacturing base supplies injection-molded microcentrifuge tubes to regional research facilities. Shanghai's Pudong district concentrates cell therapy development driving premium cell culture vessel demand.
Japan
METI industrial standards support precision polymer formulation for cell-based assay consumables. PMDA quality system regulations align with international harmonization initiatives for laboratory devices. The Kansai region's Osaka-Kobe biomedical cluster sustains demand for certified silicone elastomer syringe components.
Laboratory Disposable Products Market Competitive Environment
Player mix skews toward integrated life science conglomerates with captive distribution networks. Three structural tiers separate global full-line suppliers from regional molders and specialized surface-coating innovators. Dominant competitive moves include backward integration into medical-grade resin compounding and strategic partnerships with sterilization infrastructure operators.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific exemplifies integrated distribution dominance, while Greiner Bio-One occupies a specialist position in polymer formulation science. Becton, Dickinson and Company anchors the medical-device-aligned tier through syringe and safety-engineered product expertise. These three represent distinct competitive archetypes: supply chain integrators, material science specialists, and clinical workflow optimizers.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| PerkinElmer |
| Thermo Fisher Scientific |
| Greiner Bio-One |
| Sarstedt AG |
| Corning Incorporated |
| Becton, Dickinson and Company |
| VWR International |
| Agilent Technologies |
| Others |
Value Chain & Pricing Dynamics
Gamma irradiation capacity utilization rates above 85% in Germany and the United States create supply-side pricing power for sterilization-dependent consumables, compressing margin flexibility for molders without captive ethylene oxide infrastructure. This concentration forces buyers into long-term offtake commitments that embed resin price indexation clauses, linking disposable pricing to polypropylene futures volatility.
Pricing Analysis
Cost-plus contracts with polypropylene and polystyrene indexation dominate procurement between high-volume contract research organizations and injection molders. Three-tier pricing structure across certified-medical, standard-laboratory, and educational-grade levels separates FDA 510(k) cleared articles from general research consumables. Pricing pressure stems from consolidated purchasing consortia extracting volume leverage through multi-hospital system tenders. Academic institutions exhibit highest price sensitivity due to grant-funded budget constraints, while pharmaceutical quality control labs tolerate premium tiers for validated supply security.
Supply Chain Analysis
Just-in-time inventory policies at contract research organizations compress lead-time tolerance to six weeks for high-throughput screening workflows. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta supplying injection-molded microcentrifuge tubes and the Rhine-Main cluster hosting gamma irradiation infrastructure. Raw material dependencies span medical-grade polypropylene, natural rubber latex, and silicone elastomers. Single-source sterilization vulnerability in Germany and the United States creates geographic concentration risk. Distribution runs through integrated life science conglomerates with captive logistics networks serving hospital-affiliated reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterility validation services and lot-traceability software subscriptions are expanding faster than hardware procurement, positioning after-sales attach as the primary margin expansion vector. Recurring revenue from compliance documentation and automated reorder systems now exceeds one-time consumable margins for leading suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into medical-grade resin compounding and captive sterilization infrastructure acquisition. The collapse of traditional distributor relationships threatens margin capture unless direct-to-lab digital platforms are deployed. Priority investment in biodegradable polymer formulation patents protects European market access against EU Green Deal procurement mandates.
For New Entrants and Emerging Players: E-procurement platform underinvestment by mid-sized biotechnology firms creates service-layer white space for digital-native distributors. India's pharmaceutical quality control expansion offers the most penetrable geography, with CDSCO-aligned GMP inspection demand outpacing certified supplier availability. Target contract research organization facility buildouts in Hyderabad and Bangalore with direct sales teams bypassing legacy distributor markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors surface-modification patent holders over commodity molders, as cell culture vessel differentiation sustains pricing power through regenerative medicine application growth. Five-to-ten year viability concentrates in biodegradable formulation specialists and sterilization infrastructure operators. The inflection signal to monitor is EU member state implementation velocity for extended producer responsibility frameworks, which will force material substitution investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Patent Portfolio | EU Green Deal landfill diversion mandates accelerate procurement preference for compostable alternatives in German academic medical centers. |
| Captive Sterilization Infrastructure | Gamma irradiation capacity scarcity in the United States and Germany creates supply security premiums for integrated operators. |
| Direct-to-Lab E-Procurement Platform | Mid-sized biotechnology startups bypass traditional distributor markups through digital purchasing channels. |
| Surface Modification R&D Investment | Proprietary polymer coatings for cell culture vessels command concentrated margin pools in regenerative medicine workflows. |
| CDSCO-Aligned GMP Certification | India's pharmaceutical quality control expansion creates vendor qualification demand for disposable suppliers serving drug development pipelines. |
Study Parameters
Initial hypotheses were tested against primary input from laboratory procurement managers, contract research organization operations directors, biomedical engineers at hospital-affiliated reference labs, and regulatory affairs specialists at polymer labware manufacturers, then refined through secondary validation against FDA 510(k) filings, EMA Good Manufacturing Practice inspection records, EU Green Deal implementation documents, and customs trade data for medical-grade resin imports. Bottom-up demand modeling from individual facility procurement patterns was triangulated against top-down market sizing from industry association aggregates.
Variance decomposition across product type, material formulation, application workflow, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Forecast inputs incorporated sterilization infrastructure capacity utilization rates, biodegradable polymer substitution curves in EU jurisdictions, and contract research organization facility buildout pipelines.
Underlying assumptions cover sustained FDA sterility assurance enforcement, EU extended producer responsibility implementation timelines, and petrochemical feedstock price stability, with deviation risk concentrated in regulatory acceleration for plastic medical waste restrictions and single-source sterilization infrastructure disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Central Lab Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
UAE Clinical Laboratory Services Market