
 Portable Lenses Market | 2026-2036
Portable Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Lenses Market Insights
Asset-light leasing programs for professional camera gear is reconfiguring competitive dynamics by lowering capital barriers for independent creators and small studios. Canon Inc. leverages its vertical integration across glass melting to barrel assembly to sustain margin control. Sony Corporation dominates full-frame mirrorless lens development, while Sigma Corporation specializes in high-performance third-party alternatives that undercut OEM pricing.
Portable lenses are precision-engineered optical assemblies with focal lengths, aperture ranges, and multi-element designs calibrated for handheld imaging devices, typically manufactured through computer-controlled grinding, polishing, and thin-film coating processes to achieve specified modulation transfer function performance. Their primary purpose is to focus and transmit light onto digital sensors for photography and video capture. Zoom lens configurations anchor volume demand among event and travel shooters who prioritize single-body versatility. Fixed focal length designs command premium positioning among portrait specialists seeking maximum aperture speed. Weather resistant feature sets represent the fastest-growing margin pool as outdoor and adventure content production expands.
The US FCC governs electromagnetic compatibility for lenses with integrated autofocus motors and image stabilization systems. Japan's METI promotes domestic optics manufacturing through technology development subsidies and export certification frameworks. China's NMPA and GB standards regulate medical-adjacent imaging lenses that share production lines with consumer portable optics. Stakeholders must monitor how divergent national certification requirements for electromagnetic interference and environmental substance restrictions reshape sourcing strategies and factory location decisions.
Market Dynamics
Asset-light leasing programs for professional camera gear are reconfiguring competitive dynamics by lowering capital barriers for independent creators and small studios, while China's NMPA optical device standards and Japan's METI technology roadmaps simultaneously tighten performance benchmarks for interchangeable lens systems.
Growth Catalysts
- Content Creator Equipment Refresh Cycles:Independent videographers and travel influencers across North America and Asia-Pacific now replace lenses at compressed intervals, sustaining replacement demand independent of professional studio budgets.
- China's NMPA Optical Device Standards:Mandatory performance benchmarks for medical-adjacent imaging lenses that share production lines with consumer portable optics are elevating baseline quality across the manufacturing base.
- Weather-Resistant Feature Development:Adventure and outdoor content production expansion is accelerating factory investment in sealed barrel assemblies and fluorine-coated front elements.
Market Restraints
- Precision Glass Input Volatility:Specialized low-dispersion and extra-low dispersion glass blanks concentrate among Japanese and German suppliers, exposing margins to rare earth element price swings.
- Guangdong Manufacturing Cluster Concentration:Final assembly and barrel machining capacity concentrates in China's Pearl River Delta, creating single-point vulnerability to regional logistics disruptions or trade policy shifts.
- Smartphone Computational Photography Substitution:Multi-lens array smartphones with AI-enhanced image processing now satisfy casual imaging needs, compressing entry-level interchangeable lens demand.
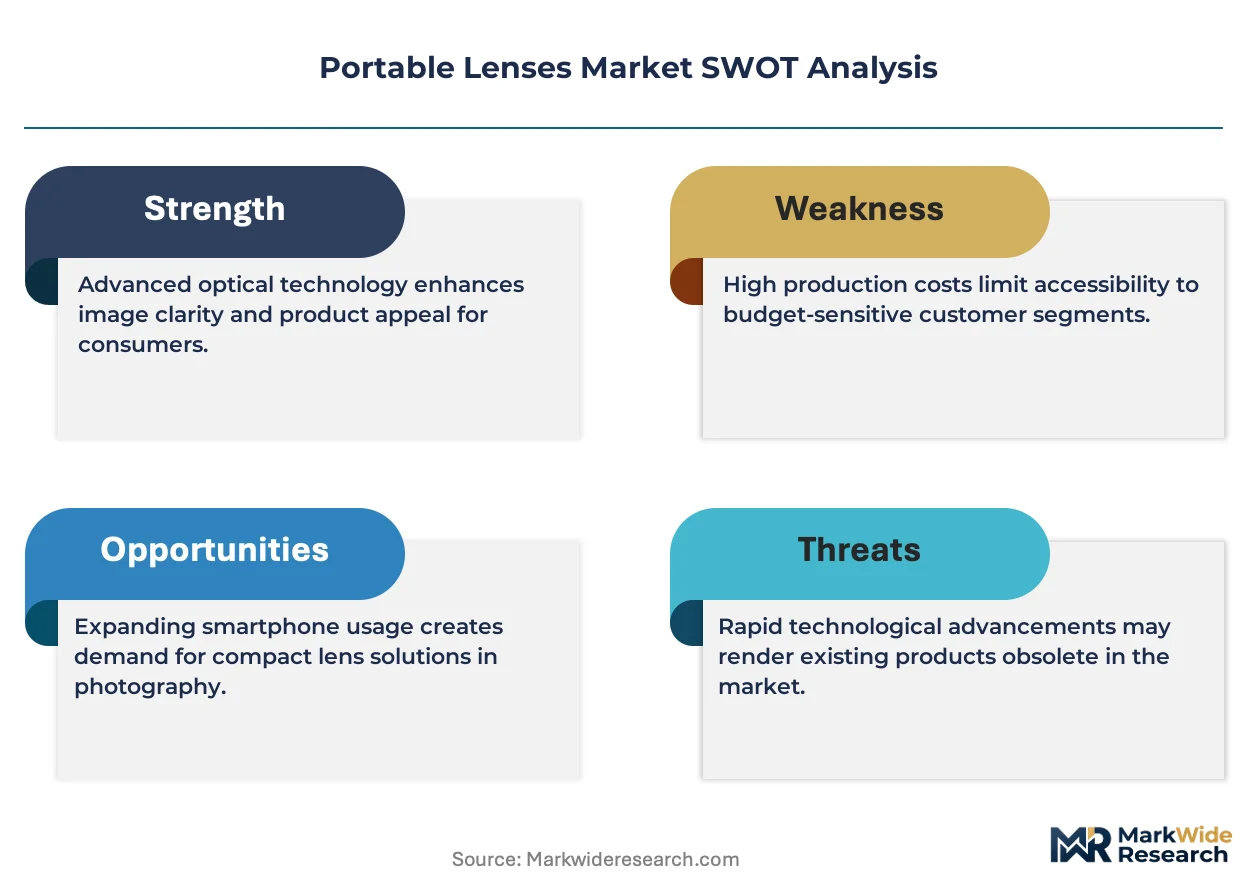
Strategic Opportunities
- India's Untapped Creator Economy:YouTube and short-form video platform expansion in tier-2 Indian cities is generating first-time interchangeable lens buyers without established brand loyalty.
- EU CSRD Supply Chain Disclosure Requirements:Mandatory sustainability reporting for optical component sourcing is creating premium positioning for manufacturers with verified conflict-free rare earth traceability.
- Computational Optics Convergence:Real-time lens aberration correction through in-camera processing is enabling simpler, lighter optical designs without sacrificing image quality endpoints.
Industry Challenges
- Thin-Film Coating Technician Shortage:Multi-layer anti-reflective deposition requires specialized vacuum chamber operators whose training pipelines have not kept pace with coating capacity expansion.
- Cross-Border Certification Timeline Compression:Simultaneous FCC electromagnetic compliance, CE marking, and NMPA registration for autofocus motor systems extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Lenses Market |
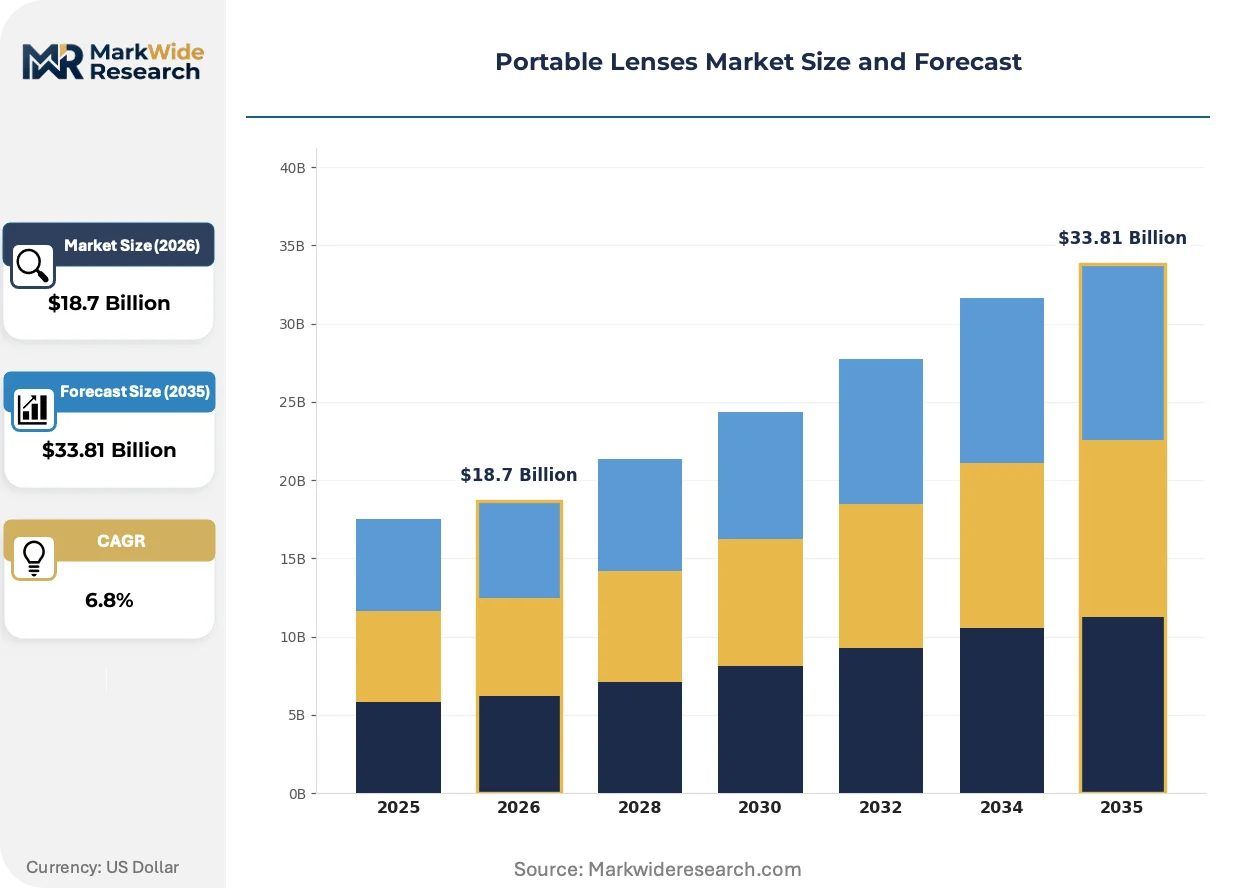
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Focal Length, Zoom Lens, Wide Angle, Telephoto End User: Photographers, Videographers, Content Creators, Cinematographers Material: Glass, Plastic, Multi-Coated, Aspherical Feature: Weather Resistant, Lightweight, High Aperture, Image Stabilization |
| Companies Covered | Canon Inc., Fujifilm Corporation, Nikon Corporation, Sony Corporation, Panasonic Corporation, Sigma Corporation, Tamron Co., Ltd., Olympus Corporation, Samyang Optics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Lenses Market Trends and Innovations
Computational image processing and cloud-based rendering workflows are dissolving the traditional boundary between optical capture and digital post-production, forcing lens designers to optimize for software-correctable aberrations rather than purely physical perfection.
Phase-detect autofocus pixel arrays embedded directly on image sensors are virtualizing the mechanical focus detection systems that previously required dedicated optical modules. Mirrorless camera body manufacturers across Japan and China are stripping out separate AF subassemblies, compressing lens-to-body communication to pure digital signaling. This virtualization is collapsing the historical differentiation between premium and mid-tier lens autofocus performance tiers.
Japan's METI technology development subsidies now explicitly tie funding eligibility to domestic optics manufacturing employment thresholds, reshaping where precision grinding and polishing operations locate. Manufacturers seeking METI support must maintain specified headcounts in Nagano and Yamanashi prefectures rather than relocating assembly to lower-cost ASEAN facilities. Full-frame mirrorless lens development programs are most affected, with several projects restructuring joint venture terms to preserve Japanese production ratios.
Subscription-based equipment access models are displacing outright ownership among freelance content creators in the United States and United Kingdom. Lens rental platforms and creator economy service bundles now bundle interchangeable optics with editing software and distribution analytics, unbundling the traditional retail channel. Event videographers and wedding photographers in Texas and Florida markets show the highest uptake rates for these all-inclusive monthly arrangements.
Portable Lenses Market Segmentation
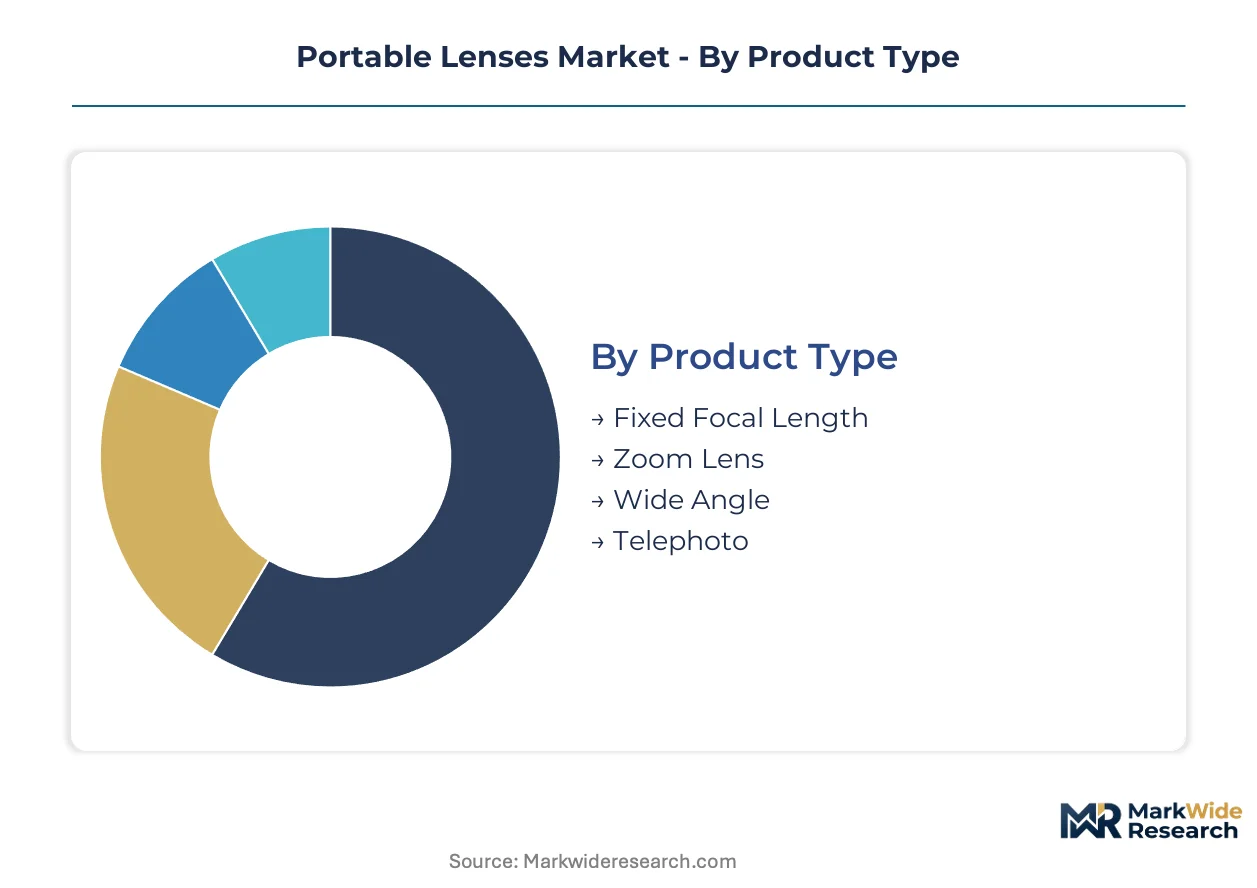
Portable lens purchasing patterns vary sharply by user sophistication and shooting context. Replacement cycles compress from five years for hobbyists to eighteen months for professional content creators chasing platform algorithm preferences. Manufacturers calibrate warranty terms and service programs around these divergent refresh velocities.
Product Type:
Zoom configurations turn over fastest among event shooters needing single-body versatility, while fixed focal length designs persist longest with portrait specialists who amortize premium glass over decade-long ownership horizons.
- Zoom Lens:Variable focal length assemblies with motorized or manual zoom rings enable rapid reframing without lens swaps. Travel and wedding shooters in Florida and Texas markets drive replacement demand as wear accumulates on zoom cams and barrel tracks.
- Fixed Focal Length:Prime lens designs with single focal length and typically wider maximum apertures serve portrait and low-light specialists. Owners in Japan's Nagano precision optics corridor retain these assets longest due to superior build quality and repair infrastructure.
- Wide Angle:Short focal length designs below 35mm equivalent for landscape and architecture capture.
- Telephoto:Long focal length assemblies for wildlife and sports photography with extended reach.
Zoom lenses dominate installed base volume. Fixed focal length designs are where expansion concentrates among creators seeking shallow depth-of-field aesthetics.
End User:
Capital intensity separates these segments, with independent creators spending discretionary income while cinematographers deploy production company equipment budgets.
- Content Creators:YouTube and short-form platform producers refresh gear fastest to maintain competitive image quality. India's tier-2 cities generate first-time interchangeable lens buyers without established brand loyalty as platform monetization expands.
- Cinematographers:Narrative and commercial film professionals deploy cinema-optimized glass with standardized gear rings and consistent color rendering. METI technology development subsidies in Japan support domestic employment thresholds for precision grinding operations serving this tier.
- Photographers:Still image specialists across wedding, portrait, and documentary disciplines.
- Videographers:Event and corporate video producers prioritizing autofocus speed and stabilization.
Content creators represent the steepest expansion trajectory. Cinematographers anchor premium pricing tiers through volume commitments and rental channel relationships.
Material:
Cost structure and optical performance diverge most sharply here, with raw material sourcing constraints shaping manufacturing geography.
- Glass:Conventional crown and flint glass elements ground and polished to precise curvature specifications. Japanese and German suppliers concentrate specialized low-dispersion blank production, exposing margins to rare earth element volatility.
- Multi-Coated:Vacuum-deposited anti-reflective layers reduce flare and ghosting in challenging light. Thin-film coating technician shortages in China's Guangdong cluster constrain capacity expansion despite climbing demand.
- Plastic:Molded polymer aspheres for cost-sensitive consumer optics.
- Aspherical:Precision-molded or ground elements correcting spherical aberration without multiple glass pieces.
Glass elements dominate professional installed base. Multi-coated configurations are where factory investment concentrates as resolution standards escalate.
Feature:
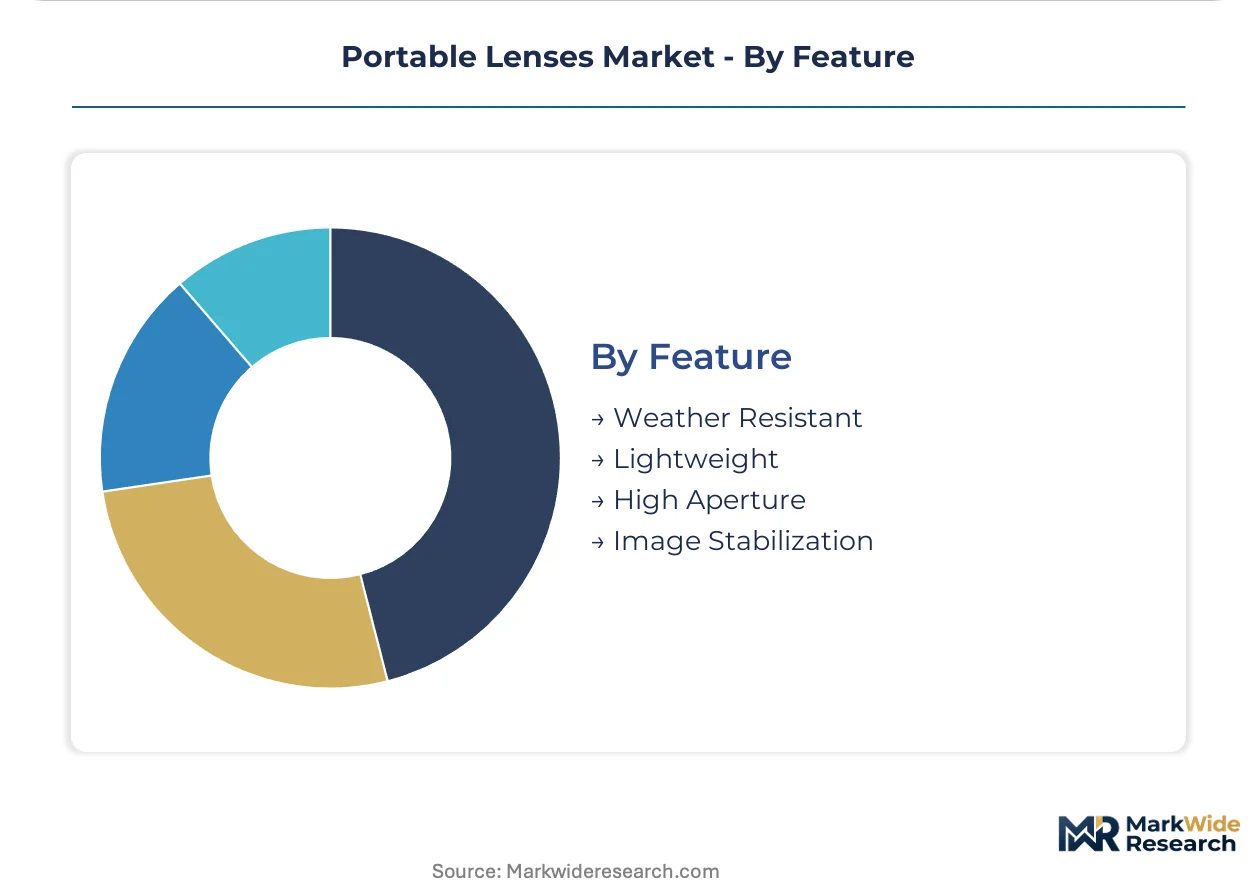
Margin capture varies dramatically by feature complexity, with sealed mechanical assemblies commanding substantial premiums over optical-only specifications.
- Weather Resistant:Sealed barrel assemblies with gaskets and fluorine-coated front elements protect against moisture and dust. Adventure content production expansion across North American national parks and Himalayan trekking routes accelerates factory investment in environmental sealing capacity.
- Image Stabilization:Gyroscopic sensors and voice coil motors counteract hand shake and body movement. FCC electromagnetic compliance requirements for integrated motor systems extend US product launch timelines by certification complexity.
- Lightweight:Composite barrel materials and optical designs minimizing element count for travel and hiking applications.
- High Aperture:Maximum f-stop values below f/2.0 enabling shallow depth-of-field and low-light capture.
Weather resistant features dominate margin expansion. Image stabilization is where technology differentiation concentrates as phase-detect autofocus virtualizes mechanical focus systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI technology development subsidies tie funding eligibility to domestic optics manufacturing employment thresholds, reshaping where precision grinding operations locate. China's NMPA optical device standards elevate baseline quality across shared medical-consumer production lines. India's tier-2 cities generate first-time interchangeable lens buyers as platform monetization expands.
United States
Independent videographers and travel influencers across Texas and Florida drive compressed equipment refresh cycles. The US FCC governs electromagnetic compatibility for lenses with integrated autofocus motors and image stabilization systems. Greater Los Angeles anchors post-production workflows that influence lens specification priorities for content creators.
China
Guangdong's Pearl River Delta concentrates final assembly and barrel machining capacity for global supply. The NMPA and GB standards regulate medical-adjacent imaging lenses sharing production lines with consumer portable optics. Shenzhen's manufacturing cluster faces thin-film coating technician shortages despite climbing demand for multi-layer anti-reflective deposition.
Japan
METI technology roadmaps tighten performance benchmarks for interchangeable lens systems while mandating domestic employment ratios. Nagano and Yamanashi prefectures host precision grinding operations serving full-frame mirrorless development programs. Canon Inc. leverages vertical integration across glass melting to barrel assembly to sustain margin control.
Germany
Specialized low-dispersion and extra-low dispersion glass blank production concentrates among suppliers exposing margins to rare earth element volatility. The EU CSRD supply chain disclosure requirements create premium positioning for manufacturers with verified conflict-free rare earth traceability. Bavaria's precision engineering corridor supports optical component sourcing verification systems.
India
YouTube and short-form video platform expansion in tier-2 cities generates first-time interchangeable lens buyers without established brand loyalty. The country's national electronics regulator oversees import certification frameworks for imaging equipment. Maharashtra's Mumbai-Pune corridor hosts emerging creator economy service bundles bundling optics with editing software.
Portable Lenses Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated optical specialists and full-frame mirrorless platform leaders. Three strategic archetypes dominate: captive glass-to-barrel integrators, sensor-body ecosystem architects, and high-performance third-party alternatives. Competitive moves concentrate on backward integration into rare earth glass supply and computational optics convergence partnerships.
Among Japanese precision optics specialists, Canon Inc., Sony Corporation, and Sigma Corporation exemplify divergent competitive positions. Canon Inc. represents the vertically integrated archetype with captive control from glass melting through final assembly. Sony Corporation anchors the full-frame mirrorless ecosystem architect tier, while Sigma Corporation occupies the high-performance third-party alternative position that undercuts OEM pricing structures.
| Leading Market Players |
|---|
| Canon Inc. |
| Fujifilm Corporation |
| Nikon Corporation |
| Sony Corporation |
| Panasonic Corporation |
| Sigma Corporation |
| Tamron Co., Ltd. |
| Olympus Corporation |
| Samyang Optics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Guangdong's Pearl River Delta manufacturing cluster concentrates barrel machining and final assembly capacity, concentrating pricing power among vertically integrated Japanese specialists who control glass melting through finished lens production. Canon Inc. and Sony Corporation leverage captive supply chains to maintain margin premiums while third-party alternatives from Sigma Corporation and Tamron Co., Ltd. compress mid-tier pricing through outsourced component sourcing.
Pricing Analysis
Certification level (FCC electromagnetic compliance, CE marking, NMPA registration) creates the primary spread between premium and standard tiers, with autofocus motor systems extending launch timelines and amortization costs. Weather-resistant sealing and multi-layer anti-reflective coatings command additional premiums. Pricing pressure stems from smartphone computational photography substitution eroding entry-level interchangeable lens demand. Content creators in India's tier-2 cities exhibit highest price sensitivity, while cinematographers deploying production budgets show lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentrates among precision optics specialists in Japan's Nagano and Yamanashi prefectures and China's Guangdong cluster, with Foxconn and Luxshare ICT holding significant electronics assembly capacity. Specialized low-dispersion glass blanks draw from Japanese and German suppliers, tethering margins to rare earth element volatility. Single-source vulnerability concentrates in Guangdong logistics corridors. Distribution runs through creator economy service bundles and rental platforms displacing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as content creator equipment refresh cycles compress and platform algorithm preferences fragment demand across specialized focal length and feature combinations.
For Market Incumbents: Insulate premium positioning through backward integration into rare earth glass supply and METI-compliant domestic employment thresholds in Nagano precision operations. Secure thin-film coating technician pipelines against capacity constraints. Defend against third-party undercutting via exclusive computational optics convergence partnerships with mirrorless body manufacturers. For New Entrants and Emerging Players: India's tier-2 creator economy represents the most penetrable entry point for first-time interchangeable lens buyers without established brand loyalty. Weather-resistant feature development for Himalayan and North American adventure content production offers white-space margin capture. Bundle optics with editing software and platform analytics in subscription arrangements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive glass-to-barrel control and METI subsidy eligibility. Long-term viability hinges on computational optics convergence capabilities and rare earth supply traceability. Monitor NMPA certification timeline compression and FCC electromagnetic compliance bottlenecks as inflection indicators for factory location restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Integration | Backward integration into low-dispersion glass blank production reduces exposure to Japanese and German supplier concentration. |
| Computational Optics Partnership | Real-time aberration correction alliances with Sony and Canon mirrorless platforms enable simplified optical designs. |
| Creator Economy Subscription Bundles | Texas and Florida event videographers show highest uptake for all-inclusive monthly equipment access arrangements. |
| Weather-Resistant Capacity Expansion | Sealed barrel assembly investment targets adventure content production across North American national parks. |
| India Tier-2 Distribution Buildout | Mumbai-Pune corridor service bundles capture first-time interchangeable lens buyers without brand loyalty. |
Research Methodology
Desk research of customs trade records, SEC 10-K optical segment disclosures, and METI technology roadmap publications preceded structured interviews with precision grinding operations managers, thin-film coating technicians, content creator equipment purchasers, and cinematography rental house procurement leads. Primary fieldwork across Japan's Nagano corridor and China's Guangdong cluster validated capacity and cost assumptions. Bottom-up lens shipment estimates triangulated against top-down imaging equipment market sizing.
Assumptions held fixed include current NMPA and FCC certification timelines, METI domestic employment subsidy thresholds, and rare earth element supply concentration. Variables included content creator refresh cycle compression rates, smartphone substitution elasticity, and computational optics adoption curves across the projection horizon. Segmentation modeled product type, end user sophistication, material grade, and feature complexity. CAGRs derived from installed base turnover velocity and premium mix shift trajectories.
Practitioners should monitor rare earth element price volatility, NMPA regulatory timeline changes, and METI subsidy restructuring for early signals of factory location and margin pressure shifts. Quarterly review of Guangdong logistics disruption indicators and thin-film coating technician pipeline expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Objective Lens Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Diode Laser Module Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Digital Cinema Lens Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Fogless Mirror Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Microchannel Plates Market
Optical Components
Optical Encoder Market