
 Photomask Pellicle Market | 2026-2036
Photomask Pellicle Market Size, Share, and Industry Trends Forecast 2026-2036
Photomask Pellicle Market Insights
Fluoropolymer film is pivoting toward thinner, higher-transmission formulations as extreme ultraviolet lithography nodes advance below seven nanometers. Mitsui Chemicals leverages captive polymer synthesis to secure supply continuity for pellicle membrane substrates. Shin-Etsu Chemical Co., Ltd. anchors its position through integrated quartz and silicon material streams that feed pellicle frame production. S&S Tech specializes in precision tensioning equipment that controls membrane flatness during assembly.
A photomask pellicle is a thin, transparent membrane mounted on a frame that seals the patterned surface of a photomask from airborne particles during semiconductor lithography, typically constructed from fluoropolymer films with thicknesses below one micrometer to maximize optical transmission at wavelengths of thirteen point five nanometers or one hundred ninety-three nanometers. Its primary purpose is to eliminate defect-causing particle contamination on the mask surface without degrading image fidelity during projection printing. Transparent pellicles dominate volume shipments for logic and memory device production where optical clarity at EUV wavelengths determines yield, while anti-reflective variants command margin premiums in flat panel display lithography where ghosting suppression matters. Foundry end users represent the fastest-growing demand pool as TSMC, Samsung, and Intel expand captive mask sets for three-nanometer and two-nanometer process ramps.
Japan's METI coordinates domestic pellicle supply security through its semiconductor material strategy, while EPA fluoropolymer emission rules in the United States constrain feedstock chemistry options for membrane manufacturers. The EU REACH framework restricts per- and polyfluoroalkyl substance use in coatings, forcing reformulation of protective pellicle layers for European-bound equipment. Stakeholders must monitor material qualification timelines for next-generation EUV pellicles as node transitions outpace standard certification cycles.
Market Dynamics
The transition to sub-seven-nanometer EUV lithography nodes is compressing pellicle qualification timelines while simultaneously tightening transmission and durability specifications beyond current fluoropolymer capabilities.
Growth Catalysts
- Advanced node lithography:Semiconductor foundries in Taiwan's Hsinchu Science Park cluster are expanding captive mask sets for three-nanometer production ramps, directly lifting pellicle procurement volumes.
- Japan's METI semiconductor material strategy:Domestic supply security coordination is accelerating qualification of locally-produced pellicle substrates for export-bound equipment.
- EUV wavelength transmission requirements:Thinner fluoropolymer membrane formulations below one micrometer are enabling yield-critical optical clarity at thirteen point five nanometers.
Market Restraints
- Feedstock chemistry constraints:EPA fluoropolymer emission rules in the United States are limiting synthesis pathways for high-purity membrane polymers.
- Per- and polyfluoroalkyl substance restrictions:EU REACH framework reforms are forcing protective coating reformulations for European-bound pellicle shipments.
- Quartz and silicon material concentration:Integrated supply streams for pellicle frame production remain concentrated among Japanese chemical conglomerates.
Strategic Opportunities
- Anti-reflective variant expansion:Flat panel display lithography applications command margin premiums where ghosting suppression determines specification compliance.
- Precision tensioning equipment:Membrane flatness control systems represent an adjacent equipment category for specialized machinery suppliers.
- South Korean foundry buildouts:Samsung's EUV capacity expansion creates incremental demand for qualified pellicle suppliers outside incumbent supply relationships.
Industry Challenges
- Material qualification timeline compression:Node transition cycles now outpace standard EUV pellicle certification protocols, creating supply readiness gaps.
- Fluoropolymer synthesis expertise scarcity:Captive polymer production capabilities remain limited to a handful of chemical manufacturers with decades of process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photomask Pellicle Market |
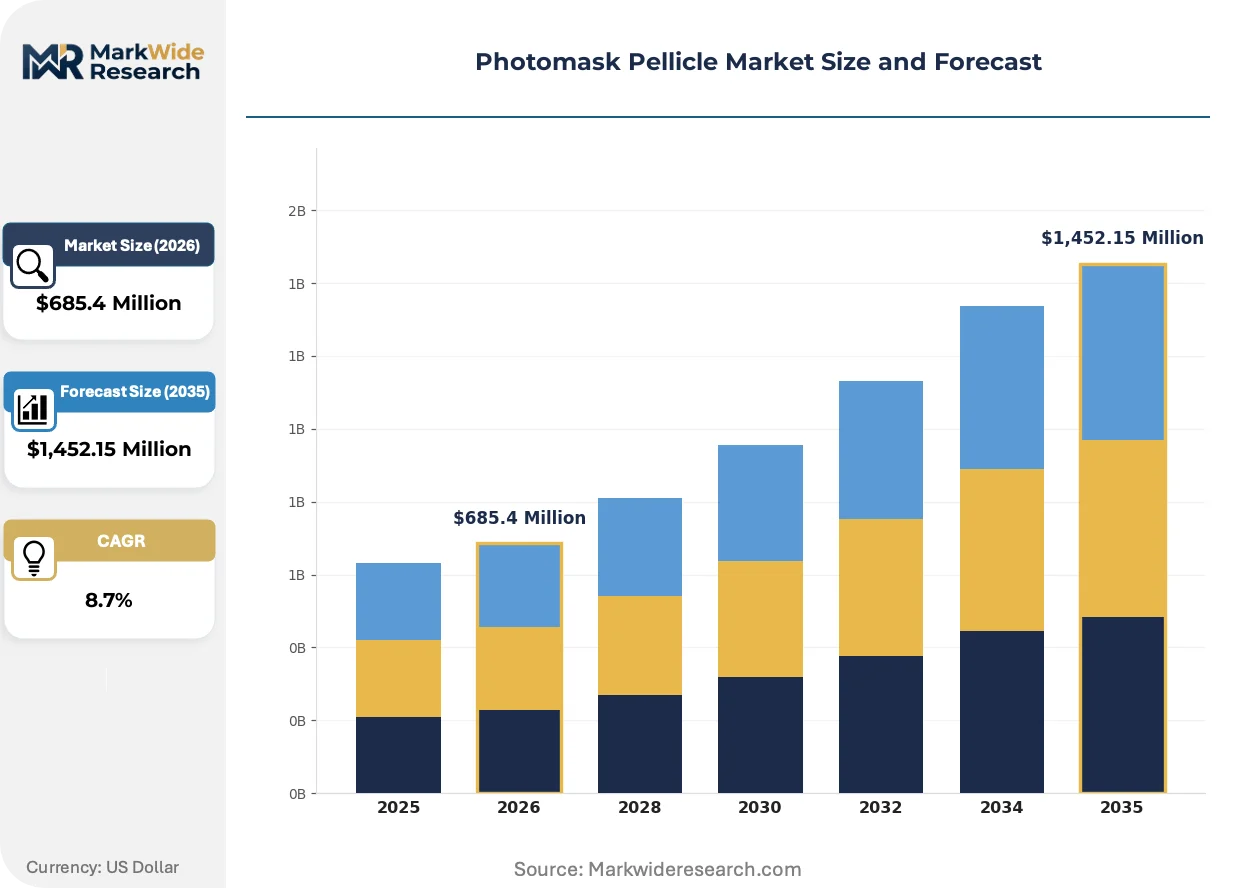
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Non-Transparent, Anti-Reflective, Protective Application: Semiconductors, Flat Panel Displays, Microelectronics, Others Material: Polycarbonate, Quartz, Silicon, Protective Coating End User: Foundries, Integrated Device Manufacturers, Research Institutions, Equipment Manufacturers |
| Companies Covered | Mitsui Chemicals, Shin-Etsu Chemical Co., Ltd., FINE SEMITECH, Micro Lithography Inc., S&S Tech, INKO Industrial, NEPCO, Canatu, Toppan Photomasks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photomask Pellicle Market Trends and Innovations
EUV lithography advancement is fragmenting traditional pellicle supply relationships as transmission specifications tighten and qualification burdens shift downstream to foundry operators.
Multi-layer fluoropolymer membrane architectures are decentralizing the incumbent single-material supplier model for EUV-grade pellicles. Memory device manufacturers in South Korea are piloting these structures for two-nanometer process development. The technology is decentralizing procurement authority from chemical substrate suppliers toward foundry-led co-development partnerships.
EPA fluoropolymer emission regulations are constraining synthesis facility expansions in the United States. Membrane manufacturers are relocating pilot production to jurisdictions with less restrictive perfluorinated compound oversight. European equipment OEMs are accelerating qualification of Japanese-sourced substrates to preempt supply discontinuity risks.
Foundry operators are consolidating pellicle specification authority under direct material science teams rather than delegating to mask shop intermediaries. TSMC and Intel are establishing captive qualification labs for next-generation membrane testing. Taiwan's Hsinchu corridor hosts the densest concentration of these vertically integrated evaluation capabilities.
Photomask Pellicle Market Segmentation
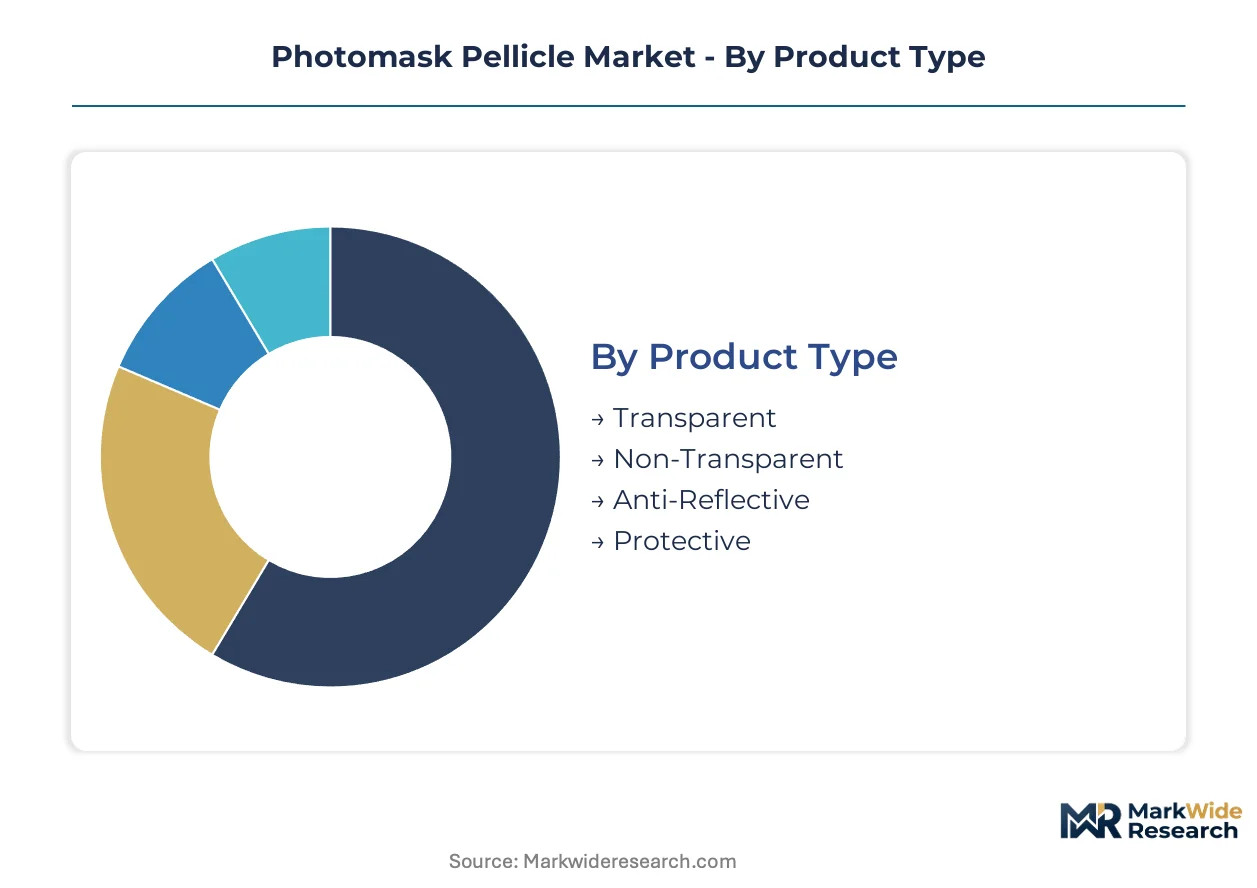
Photomask pellicle segmentation reveals how material science specialization and lithography wavelength requirements fragment procurement strategies across semiconductor manufacturing tiers. Each category reflects distinct technical trade-offs between optical transmission, mechanical durability, and chemical compliance.
Product Type:
Standardization dominates transparent pellicle specifications for high-volume logic production, while anti-reflective variants demand customized layer engineering for display applications.
- Transparent:Fluoropolymer membranes below one micrometer thickness maximize transmission at thirteen point five nanometer EUV wavelengths. Foundries in Taiwan's Hsinchu Science Park cluster specify these for three-nanometer process ramps where yield-critical clarity determines procurement.
- Anti-Reflective:Multi-layer dielectric coatings suppress ghosting artifacts in flat panel display lithography. Korean display manufacturers pay margin premiums for customized spectral performance across generation-eight substrate sizes.
- Non-Transparent:Opaque frame-sealing membranes protect mask edges from particle ingress during handling.
- Protective:Sacrificial surface layers extend pellicle service life in high-throughput scanner environments.
Leading the category by volume: Transparent. Growing fastest: Anti-Reflective.
Application:
Volume concentration tilts toward memory and logic semiconductor fabrication, while flat panel display lithography creates specialized specification pockets.
- Semiconductors:EUV lithography at sub-seven-nanometer nodes requires membrane flatness tolerances below fifty nanometers. Samsung and Intel captive mask sets drive qualification urgency for next-generation fluoropolymer formulations.
- Flat Panel Displays:Large-area lithography systems use anti-reflective pellicles to suppress moiré patterns across generation-eight and generation-ten substrate formats.
- Microelectronics:Specialty analog and power device manufacturers specify protective variants for extended scanner duty cycles.
- Others:Photonics and MEMS fabrication represent fragmented demand with customized frame geometries.
Semiconductors anchor volume procurement. Flat Panel Displays expand most quickly as OLED capacity builds accelerate.
Material:
Supply concentration in fluoropolymer synthesis creates tiered access to membrane substrate quality.
- Polycarbonate:Legacy deep-ultraviolet pellicles at one hundred ninety-three nanometers retain niche demand in mature node maintenance. Japanese chemical conglomerates control captive polymer production for high-purity grades.
- Quartz:Pellicle frame substrates require ultra-low thermal expansion coefficients. Shin-Etsu Chemical anchors supply through integrated ingot pulling and precision machining operations.
- Silicon:Silicon-based membrane research targets EUV durability beyond fluoropolymer limits.
- Protective Coating:Perfluorinated surface treatments face EU REACH reformulation pressure for European-bound equipment.
Quartz frames dominate structural material volume. Polycarbonate retains widest installed base.
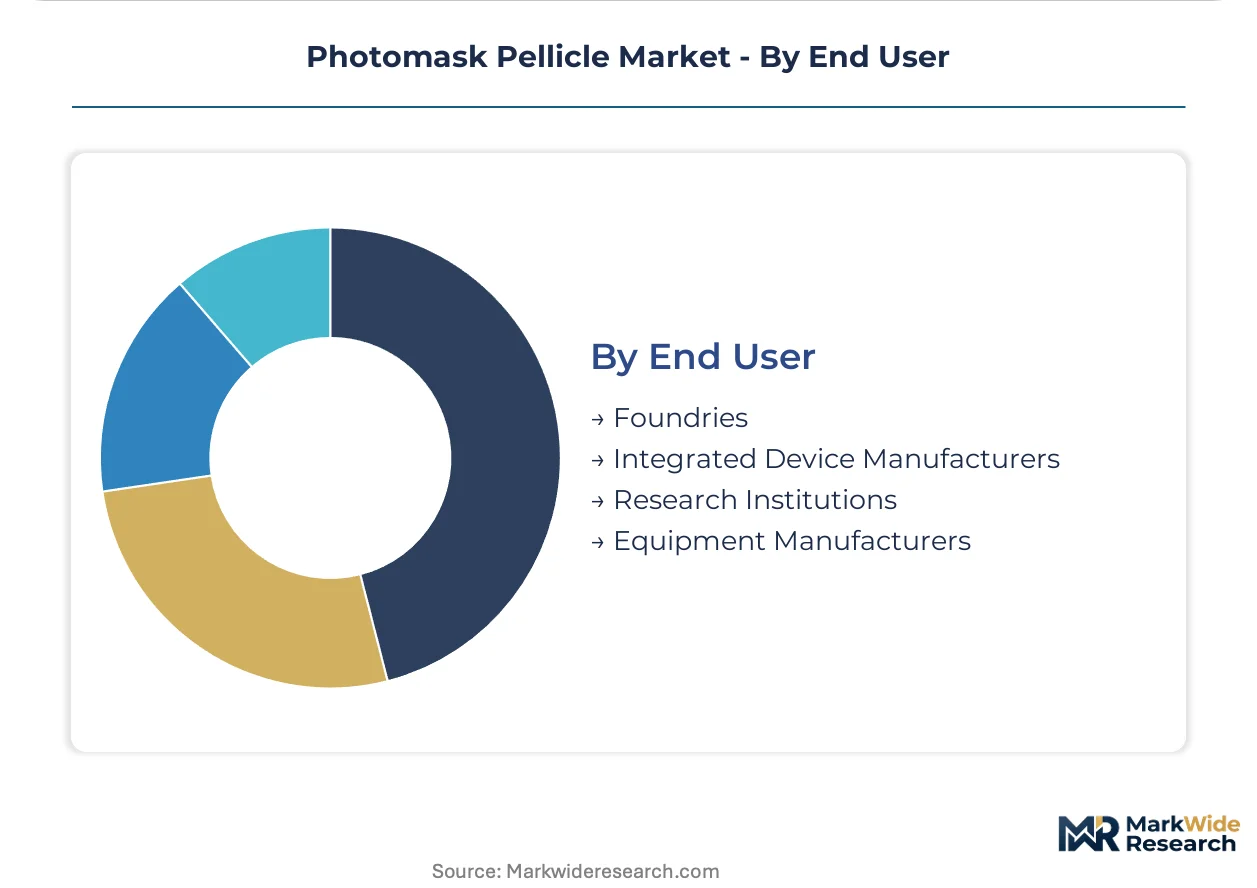
End User:
Procurement authority is shifting from mask shop intermediaries toward foundry-led material science teams.
- Foundries:TSMC and Samsung now specify pellicle transmission requirements directly rather than delegating to mask vendors. Captive qualification labs in Taiwan's Hsinchu corridor compress certification timelines for two-nanometer development.
- Integrated Device Manufacturers:Intel's internal mask operations maintain parallel qualification tracks for advanced node ramp security.
- Research Institutions:Imec and academic consortia pilot multi-layer membrane architectures outside incumbent supplier relationships.
- Equipment Manufacturers:ASML and Nikon specify pellicle compatibility envelopes for scanner warranty coverage.
Foundries command the steepest expansion trajectory. Integrated Device Manufacturers retain highest specification authority per wafer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan functions as the dominant tax-incentive zone concentrating photomask pellicle demand. Advanced foundry operations there generate procurement volumes that shape supplier qualification priorities worldwide.
United States
Intel's captive mask operations in Oregon and Arizona drive specification authority for EUV-grade pellicles. EPA fluoropolymer emission rules constrain domestic synthesis facility expansions, forcing membrane manufacturers to relocate pilot production offshore. The Pacific Northwest corridor hosts scanner warranty qualification labs that validate pellicle compatibility for ASML equipment.
Japan
METI's semiconductor material strategy accelerates qualification of locally-produced pellicle substrates for export-bound equipment. Domestic chemical conglomerates maintain integrated supply streams feeding pellicle frame production. The Kanto region around Tokyo anchors precision tensioning equipment manufacturing that controls membrane flatness during assembly.
South Korea
Samsung's EUV capacity expansion in Gyeonggi Province creates incremental demand for qualified pellicle suppliers outside incumbent supply relationships. Memory device manufacturers there pilot multi-layer fluoropolymer membrane architectures for two-nanometer process development. The Busan-Ulsan corridor concentrates flat panel display lithography where anti-reflective variants command margin premiums.
Taiwan
TSMC's three-nanometer production ramps in Hsinchu Science Park directly lift pellicle procurement volumes for advanced node lithography. Foundry operators there consolidate specification authority under direct material science teams rather than delegating to mask shop intermediaries. The Hsinchu corridor hosts the densest concentration of vertically integrated qualification capabilities for next-generation membrane testing.
Germany
European equipment OEMs in Saxony accelerate qualification of Japanese-sourced substrates to preempt supply discontinuity risks. EU REACH framework reforms force protective coating reformulations for European-bound pellicle shipments. The Dresden semiconductor cluster drives demand for transparent pellicles where yield-critical clarity determines procurement specifications.
Photomask Pellicle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around integrated chemical conglomerates with captive polymer synthesis capabilities and specialized precision equipment fabricators. Three archetypes dominate: fluoropolymer substrate suppliers with decades of process development, quartz and silicon material integrators feeding frame production, and membrane tensioning system specialists. Competitive moves center on backward integration into polymer production and geographic relocation of synthesis facilities to jurisdictions with less restrictive perfluorinated compound oversight.
Among Japanese chemical conglomerates, Mitsui Chemicals and Shin-Etsu Chemical Co., Ltd. occupy positions representing integrated material supply archetypes. Mitsui exemplifies captive polymer synthesis capabilities that secure supply continuity for pellicle membrane substrates. Shin-Etsu anchors its competitive position through upstream control over quartz and silicon material streams. S&S Tech sits within the precision equipment tier, representing specialists in membrane flatness control systems that determine assembly yield.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Shin-Etsu Chemical Co., Ltd. |
| FINE SEMITECH |
| Micro Lithography Inc. |
| S&S Tech |
| INKO Industrial |
| NEPCO |
| Canatu |
| Toppan Photomasks |
| Others |
Pricing and Supply Chain Analysis
Fluoropolymer membrane substrate costs cascade through pellicle pricing tiers based on synthesis purity grades and captive polymer production capabilities. Japanese chemical conglomerates with integrated supply streams command premium positioning for EUV-grade specifications, while spot-market polycarbonate pellicles trade at compressed margins for mature node maintenance.
Pricing Analysis
Short lead-time premiums separate qualified suppliers from spot-market alternatives in pellicle procurement. Contract-based long-term offtake agreements dominate foundry procurement, with price differentiation driven by EUV transmission certification tier and volume scale commitments. Pricing pressure stems from EPA fluoropolymer emission constraints limiting domestic synthesis expansion in the United States. Memory device manufacturers exhibit highest price sensitivity due to cyclical capacity investment timing, while logic foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand for EUV-grade pellicles, bypassing traditional mask shop intermediaries. Supply concentrates in Japan, Taiwan, and South Korea, with raw material dependencies on high-purity fluoropolymer resins, quartz ingots, and precision tensioning equipment. Single-source vulnerability runs through Japanese chemical conglomerates controlling captive polymer synthesis. Distribution runs through vertically integrated qualification labs in Taiwan's Hsinchu corridor where foundry-led specification authority is consolidating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into fluoropolymer synthesis separates viable competitors from margin-compressed assemblers. Players are pursuing upstream control over membrane substrate production to secure supply continuity and specification authority.
For Market Incumbents: Extend captive polymer production capabilities to preempt feedstock chemistry constraints from EPA emission rules. Deepen foundry co-development partnerships in Taiwan's Hsinchu corridor to lock in qualification timelines for two-nanometer node ramps. Threat substitution from silicon-based membrane research demands accelerated R&D investment to maintain fluoropolymer relevance. For New Entrants and Emerging Players: Equipment manufacturers represent the most penetrable channel partner type for precision tensioning system specialists seeking pellicle assembly market entry. Target South Korean memory foundries piloting multi-layer membrane architectures outside incumbent supply relationships. White-space exists in anti-reflective variant customization for generation-ten flat panel display formats where spectral performance engineering commands margin premiums. For Investors and Strategic Acquirers: Foundry establishment of captive qualification labs is the leading indicator that procurement authority is permanently shifting downstream from chemical suppliers. Long-term viability favors targets with demonstrated EUV transmission certification and foundry-direct relationships over mask shop-dependent intermediaries. Watch for METI policy acceleration signals indicating Japanese supply security prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Synthesis | Mitsui Chemicals' captive polymer production secures membrane substrate supply continuity against EPA emission constraints. |
| Foundry-Direct Qualification Partnerships | TSMC's captive labs in Hsinchu compress certification timelines and consolidate specification authority away from mask vendors. |
| Multi-Layer Membrane Architecture Development | Samsung's pilot programs in Gyeonggi Province decentralize single-material supplier models for EUV durability. |
| Geographic Relocation of Synthesis Facilities | Membrane manufacturers shift pilot production to jurisdictions with less restrictive perfluorinated compound oversight. |
| Anti-Reflective Coating Customization | Korean display manufacturers pay premiums for spectral performance engineering across generation-eight substrate sizes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this photomask pellicle market assessment. Primary interviews with fluoropolymer synthesis directors, foundry procurement leads, mask shop operations managers, and precision equipment engineers combined with secondary validation from METI policy documents, EPA emission filings, and EU REACH substance registrations. Bottom-up shipment tallies by product type and application triangulated against top-down semiconductor capital expenditure patterns.
Data-stream reconciliation across foundry capex disclosures, scanner installation records, and pellicle qualification timelines shaped the analytical framework. Segmentation dimensions modeled include product type, application, material composition, and end-user procurement authority across the projection horizon. CAGRs derived from node transition pacing, EUV adoption curves, and material qualification cycle compression. Industry-specific inputs incorporated fluoropolymer transmission specification evolution and foundry captive mask set expansion rates.
Caveats apply where EPA fluoropolymer emission rule amendments or EU REACH substance restriction expansions could materially shift the outlook. Forecasts reflect assumptions regarding node transition timelines and qualification protocol standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
ROADM WSS Component Market
Optical Components
Ring Panel Filters Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Display Optical Film Market
Optical Components
Spatial Light Modulator Market
Optical Components
CMP Polishing Machine Market
Optical Components
CVD Sic Ring Market
Optical Components
Duplication Disc Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Passive Optical Component Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Portable Lenses Market
Optical Components
Diode Laser Module Market