
 Cataract Treatment Market | 2026-2036
Cataract Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cataract Treatment Market Outlook
Premium toric and multifocal intraocular lens specifications are reorganizing competitive dynamics across the cataract treatment landscape. Alcon leverages vertical integration from lens material chemistry to surgical consumables, sustaining pricing power across the premium tier. Johnson & Johnson competes through R&D intensity in femtosecond laser platforms, while Carl Zeiss dominates optical coherence tomography-guided surgical planning systems.
Cataract treatment encompasses surgical removal of the clouded natural lens and its replacement with an artificial intraocular lens, typically involving ultrasonic phacoemulsification through a sub-3-millimeter corneal incision to restore visual acuity. Intraocular lenses command the dominant product type position due to recurring replacement cycles and premium upgrade pathways, while laser-assisted procedure types represent the fastest-growing segment as femtosecond platforms displace manual capsulorhexis in developed markets. Delivery mode concentration favors outpatient clinics and specialty eye care centers where capital equipment utilization rates and surgeon throughput maximize per-procedure economics.
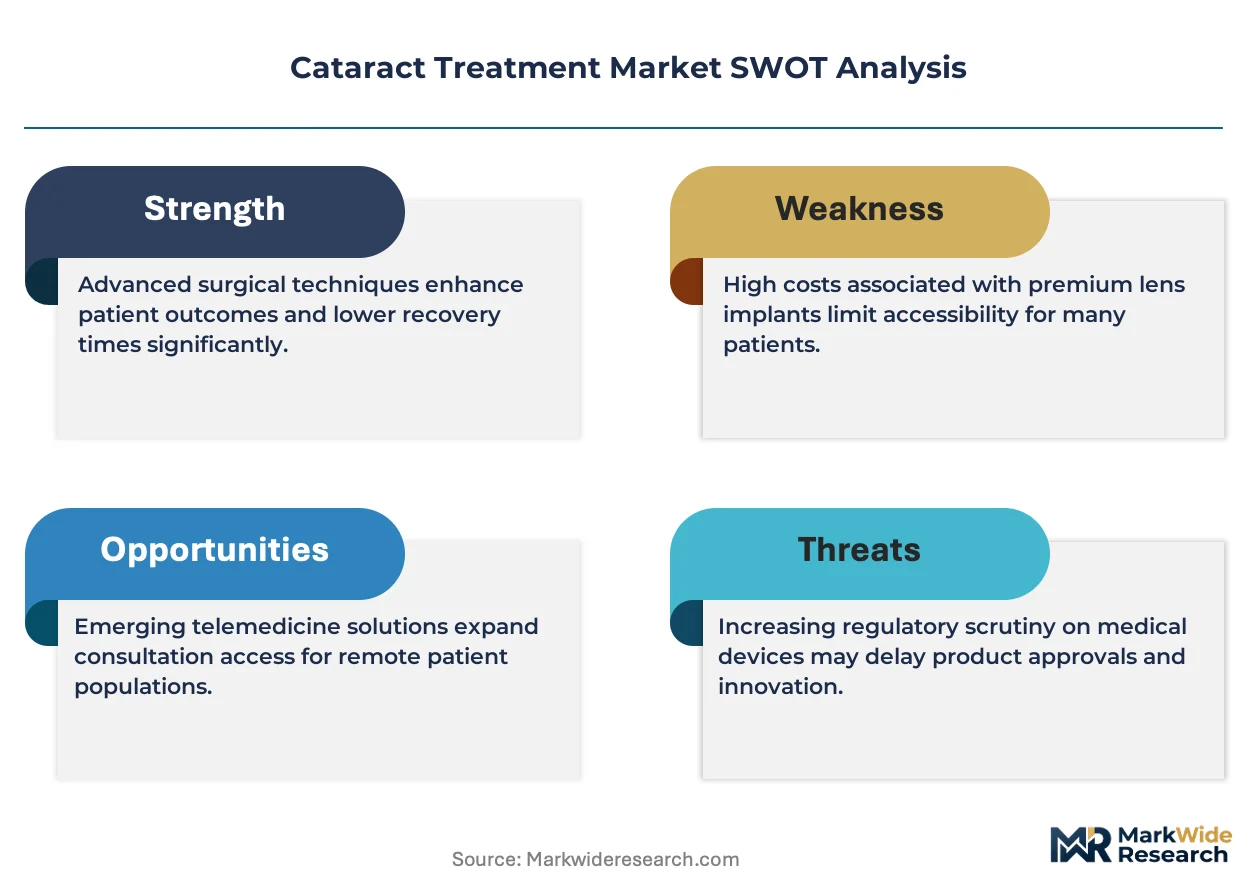
FDA premarket notification requirements for new intraocular lens designs, CE marking under the EU Medical Device Regulation, and India's CDSCO medical device rules collectively shape product development timelines and market access conditions across major geographies. The FDA's Breakthrough Devices Program and EMA's parallel scientific advice pathways are compressing development timelines for next-generation accommodating lenses. Stakeholders must monitor reimbursement parity decisions between conventional and laser-assisted procedures as these determinations will dictate capital deployment priorities for surgical platform upgrades.
Market Dynamics
The cataract treatment market is undergoing a technology transition where femtosecond laser platforms are fragmenting the traditional manual surgery value chain, creating new equipment purchase cycles and surgeon retraining requirements across hospital systems and ambulatory surgical centers.
Growth Catalysts
- India's National Programme for Control of Blindness:Government-funded screening camps and subsidized phacoemulsification procedures are expanding surgical access to rural populations previously excluded from formal eye care networks.
- Femtosecond laser-assisted cataract surgery:Precision capsulotomy and lens fragmentation capabilities are reducing ultrasonic energy requirements and improving visual outcomes in premium lens implantations.
- REACH registration requirements:EU chemical safety assessments for lens monomer materials are accelerating biocompatible polymer innovations while filtering substandard imports from European markets.
Market Restraints
- Acrylic and silicone monomer cost volatility:Petroleum-derived feedstock price fluctuations compress gross margins for intraocular lens manufacturers operating on fixed hospital contract pricing.
- Surgeon training pipeline constraints:Fellowship program bottlenecks in the United States and Western Europe limit the expansion of laser-assisted procedure volumes despite installed platform capacity.
- EU Medical Device Regulation recertification burdens:Legacy intraocular lens designs face extended conformity assessment timelines and notified body capacity shortages, delaying product line refreshes.
Strategic Opportunities
- Vietnam and Indonesia ophthalmology chains:Underpenetrated phacoemulsification markets with aging demographics and rising disposable incomes present first-mover advantages for equipment-leasing business models.
- Extended depth of focus lenses:Next-generation accommodating designs that bridge multifocal and monofocal performance gaps address presbyopia-correcting demand without dysphotopsia trade-offs.
- Telemedicine-enabled preoperative screening:AI-assisted slit-lamp image analysis via smartphone adapters is decentralizing diagnostic access to primary care settings in sub-Saharan Africa and South Asia.
Industry Challenges
- FDA Breakthrough Devices Program navigation:Expedited review pathways for novel accommodating lenses demand intensive clinical evidence generation and predicate device strategy complexity.
- Capital equipment utilization optimization:Femtosecond laser platforms require high surgical volumes to achieve per-procedure cost parity with manual techniques, pressuring smaller ambulatory centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cataract Treatment Market |
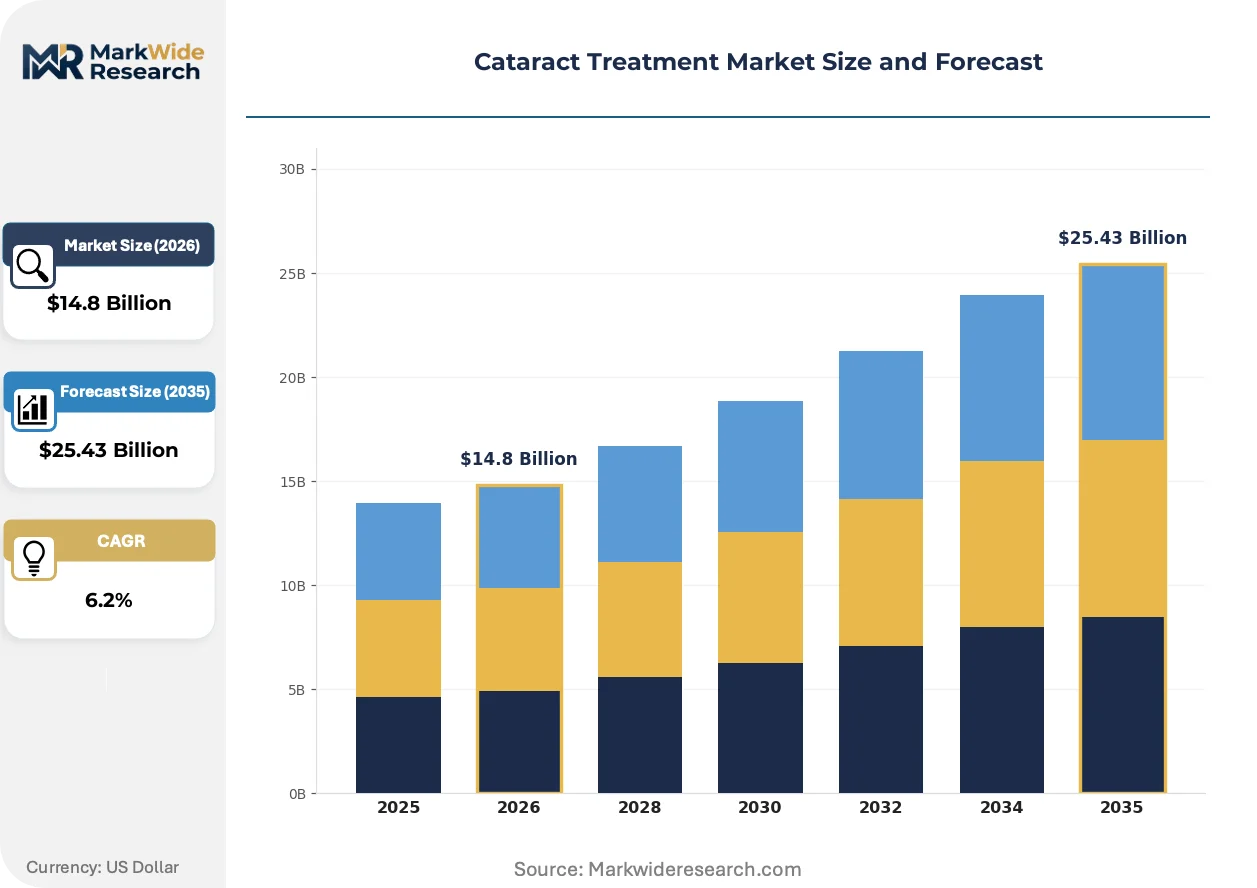
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
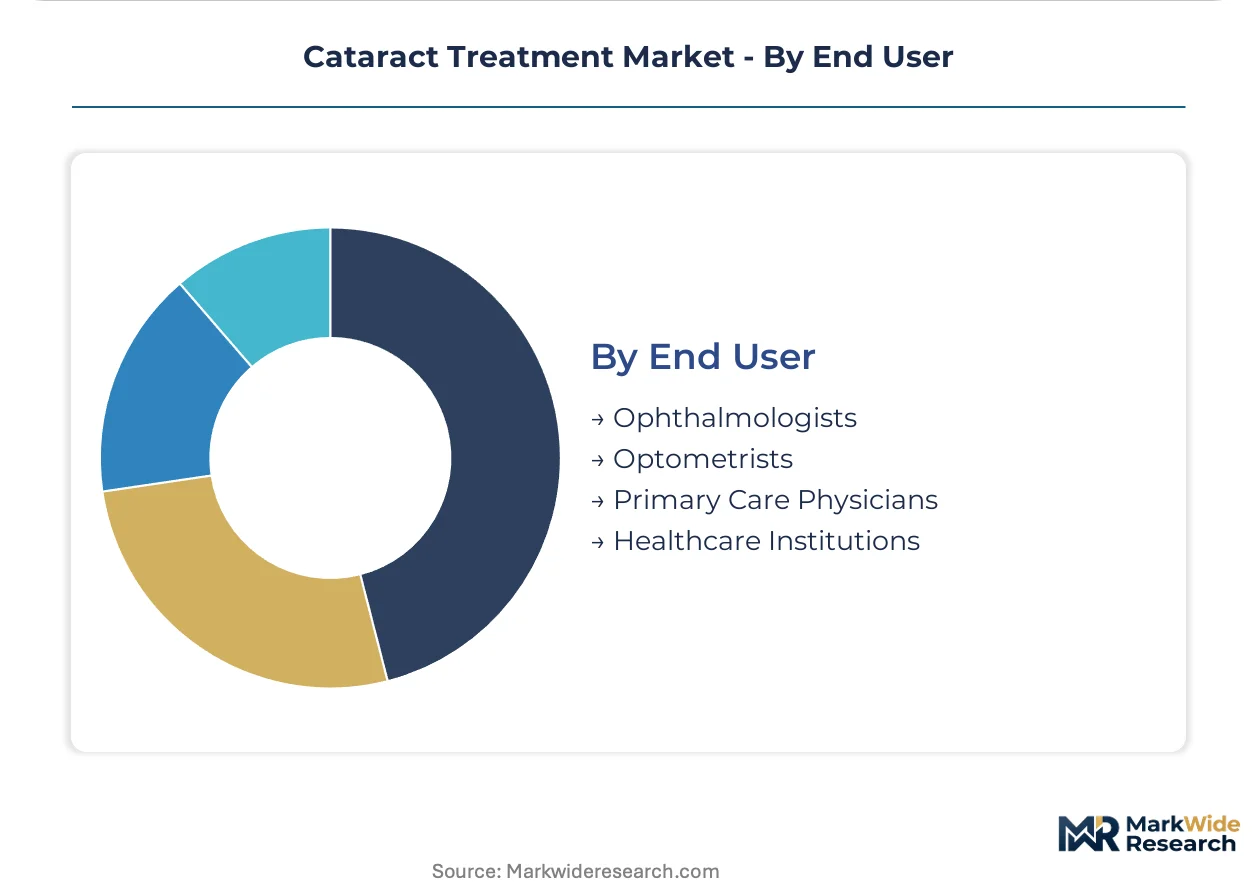
| Segmentation | Product Type: Intraocular Lenses, Cataract Surgery Equipment, Ophthalmic Devices, Surgical Instruments Delivery Mode: Hospital, Outpatient Clinic, Specialty Eye Care Center, Home Care Procedure Type: Phacoemulsification, Extracapsular Extraction, Intracapsular Extraction, Laser-Assisted End User: Ophthalmologists, Optometrists, Primary Care Physicians, Healthcare Institutions |
| Companies Covered | Alcon, Johnson & Johnson, Carl Zeiss, Bausch Health Companies, Abbott Laboratories, HOYA Corporation, STAAR Surgical, NIDEK Co. Ltd., EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cataract Treatment Market Strategic Shifts
Technology convergence between diagnostic imaging and surgical execution is compressing the traditional separation between preoperative planning and intraoperative decision-making, reshaping how ophthalmology practices organize their clinical workflows and capital deployment.
Intraoperative optical coherence tomography is decomposing the conventional reliance on surgeon visualization alone during posterior capsule management. Academic medical centers in Germany and Japan are adopting integrated OCT-guided systems at replacement cycle points, enabling real-time anatomical feedback that reduces posterior capsule rupture rates and supports trainee skill acquisition in complex cases.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III implantable devices are extending development timelines for novel intraocular lens materials. Manufacturers are responding by prioritizing incremental modifications to predicate designs over breakthrough accommodating mechanisms, concentrating R&D investment in surface modification chemistries rather than entirely new optical platforms.
Hospital procurement departments are consolidating vendor relationships through multi-year intraocular lens supply agreements that bundle premium, standard, and toric SKUs under volume-tiered pricing. This behavior is most pronounced in United States integrated delivery networks, where standardization committees are reducing approved lens vendor lists from six to two or three suppliers to simplify inventory management and capture administrative efficiency gains.
Cataract Treatment Market Segmentation
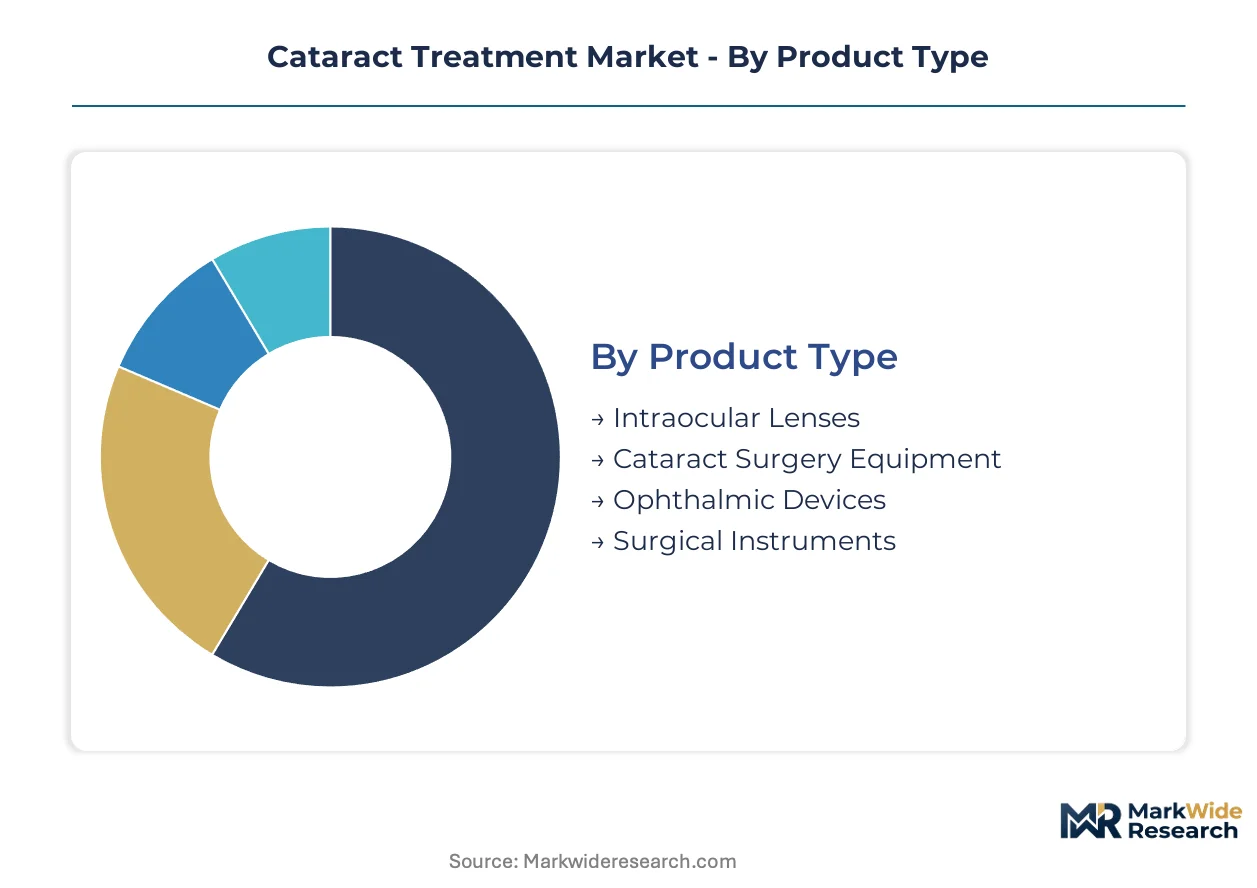
Cataract treatment segmentation reveals how technology transitions and site-of-care economics reshape procurement priorities. Product and procedure categories face divergent substitution pressures from adjacent ophthalmology modalities, while delivery mode fragmentation reflects capital intensity versus accessibility trade-offs.
Product Type:
Intraocular lenses face the strongest substitution threat from refractive surgery alternatives including corneal inlays and presbyopia-correcting drops, forcing manufacturers to defend implantable device value propositions through extended depth-of-focus innovations.
- Intraocular Lenses:Hydrophobic acrylic and silicone-optic designs with square-edge barriers dominate posterior capsule opacification prevention. India's CDSCO medical device rules and FDA 510(k) pathways govern biocompatibility certifications, with premium toric and multifocal specifications commanding hospital formulary slots through surgeon training partnerships.
- Cataract Surgery Equipment:Phacoemulsification consoles with peristaltic and venturi fluidics systems anchor capital budgets in tertiary hospitals. Germany's Klinikum clusters and Japan's academic medical centers drive replacement cycles toward integrated OCT-guided platforms that reduce ultrasonic energy delivery.
- Ophthalmic Devices:Diagnostic imaging systems including optical biometers and corneal topographers support preoperative lens power calculations.
- Surgical Instruments:Single-use phacoemulsification handpieces and reusable titanium instrument sets balance infection control against per-procedure cost targets.
Intraocular lenses anchor the volume base while laser-assisted surgical platforms gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates high-volume ambulatory centers from capital-constrained rural facilities, with equipment leasing models penetrating price-sensitive markets.
- Hospital:Tertiary ophthalmology departments in India's All India Institute of Medical Sciences network and US academic medical centers manage complex cases requiring anesthesia support. India's National Programme for Control of Blindness subsidizes rural hospital cataract camps, expanding phacoemulsification access beyond metropolitan corridors.
- Outpatient Clinic:Standalone ambulatory surgical centers in Germany's Kassenärztliche Vereinigung system and US Medicare-certified facilities optimize femtosecond laser utilization through high surgical throughput. REACH registration requirements for lens monomer materials filter supply chains toward European-manufactured consumables.
- Specialty Eye Care Center:Dedicated ophthalmology chains in Vietnam and Indonesia concentrate premium lens implantation volumes.
- Home Care:Postoperative drop regimens and remote monitoring applications support rural patient compliance.
Hospital settings concentrate the highest-acuity volume while outpatient clinics expand most quickly through efficiency-focused capital deployment.
Procedure Type:
Application-based divergence separates manual techniques optimized for dense nuclear sclerosis from laser platforms targeting premium lens outcomes.
- Phacoemulsification:Ultrasonic emulsification through sub-3-millimeter incisions remains the standard for senile cataract extraction. US fellowship-trained surgeons and India's Aravind Eye Care System surgeons demonstrate the steepest volume curves, with manual small-incision alternatives persisting in sub-Saharan Africa.
- Laser-Assisted:Femtosecond platforms perform capsulotomy and lens fragmentation with pulse durations under 500 femtoseconds. Japan's PMDA-approved systems and Germany's Carl Zeiss installations lead optical coherence tomography-guided adoption, reducing effective phacoemulsification time in hard cataract grades.
- Extracapsular Extraction:Larger-incision techniques persist where phacoemulsification capital is unavailable.
- Intracapsular Extraction:Complete lens removal with capsule sacrifice remains limited to trauma and dislocated lens indications.
Phacoemulsification anchors the volume base while laser-assisted procedures climb the fastest through premium segment penetration.
End User:
Customer type concentration reflects scope-of-practice boundaries, with surgical licensure restricting high-revenue procedures to ophthalmology specialists.
- Ophthalmologists:Medical doctors with residency and fellowship training perform incisional surgery and premium lens implantation. US Medicare reimbursement parity decisions between conventional and laser-assisted techniques directly influence their capital equipment preferences.
- Healthcare Institutions:Integrated delivery networks and India's government hospital systems standardize vendor relationships through multi-year supply agreements. Procurement committees reduce approved intraocular lens suppliers to capture administrative efficiency and volume-tiered pricing.
- Optometrists:Preoperative screening and postoperative refractive management extend their diagnostic role.
- Primary Care Physicians:Initial vision complaint triage and referral coordination in rural India and sub-Saharan Africa.
Ophthalmologists anchor the volume base while healthcare institutions gain procurement influence at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision ophthalmology equipment to Japan's academic medical centers, establishing a bilateral trade corridor in femtosecond laser platforms and diagnostic imaging systems.
United States
Medicare reimbursement parity debates and integrated delivery network consolidation are reshaping procurement patterns. FDA Breakthrough Devices Program pathways compress review timelines for novel accommodating lenses. The Cleveland Clinic and Mayo Clinic anchor premium lens implantation volumes in the Midwest.
Germany
Kassenärztliche Vereinigung reimbursement structures and Klinikum cluster procurement standardization concentrate demand. EU Medical Device Regulation recertification burdens extend conformity assessment timelines for legacy intraocular lens designs. Heidelberg and Jena host Carl Zeiss optical coherence tomography manufacturing.
India
Government-funded National Programme for Control of Blindness screening camps and Aravind Eye Care System surgical volumes expand rural access. CDSCO medical device rules govern biocompatibility certifications for imported lens materials. Madurai and Coimbatore concentrate phacoemulsification training and high-volume surgical output.
Japan
Aging demographics and PMDA-approved femtosecond laser installations accelerate technology transitions. METI industrial policy supports domestic ophthalmic equipment manufacturing. Tokyo and Osaka academic medical centers drive integrated OCT-guided platform adoption.
Vietnam
Rising disposable incomes and underpenetrated phacoemulsification markets attract equipment-leasing business models. The country's national pharmaceutical regulator oversees medical device import licensing. Ho Chi Minh City and Hanoi concentrate private ophthalmology chain expansion.
Cataract Treatment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and R&D concentration. The market structures around three tiers: integrated multinationals with backward integration into lens chemistry, laser platform specialists with femtosecond patent estates, and regional consumables suppliers with hospital contract pricing. Dominant competitive moves include multi-year supply agreement bundling and surgeon training partnership lock-ins.
Within the integrated multinational tier, Alcon and Johnson & Johnson occupy positions spanning lens materials to surgical platforms. Carl Zeiss exemplifies the precision optics archetype with diagnostic-to-surgical workflow integration. Among Asia-Pacific specialists, HOYA Corporation and NIDEK Co. Ltd. represent regional equipment and consumables concentration.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson |
| Carl Zeiss |
| Bausch Health Companies |
| Abbott Laboratories |
| HOYA Corporation |
| STAAR Surgical |
| NIDEK Co. Ltd. |
| EssilorLuxottica |
| Others |
Value Chain & Pricing Dynamics
Femtosecond laser platform adoption replacing manual phacoemulsification equipment simultaneously concentrates supply geography in Germany and Japan while widening the pricing gap between premium-tier and standard-tier surgical consumables. Acrylic monomer feedstock volatility from petroleum derivatives feeds directly into intraocular lens manufacturing cost structures, compressing margins for fixed-contract hospital suppliers.
Pricing Analysis
Prior-generation phacoemulsification consoles, current-generation femtosecond laser platforms, and next-generation OCT-guided integrated systems stratify equipment pricing across three performance tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by surgeon training certification level and volume commitment scale. Cost compression in standard hydrophobic acrylic lenses is intensifying because India's CDSCO import regulations accelerate local manufacturing substitution. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure economics pressure, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for silicone monomer shipments originating from German chemical manufacturers. Lens manufacturing concentrates in Germany, the United States, and Japan, with phacoemulsification handpiece assembly anchored in South Korea and Malaysia. Hydrophobic acrylic polymer and platinum-cured silicone elastomer feedstock draws from petrochemical complexes in Texas and Rotterdam. Single-source vulnerability in femtosecond laser crystal supply creates chokepoint exposure. Distribution runs through hospital procurement committees and GPO contract frameworks in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cataract treatment market sits at a platform-economics inflection where diagnostic-to-surgical workflow integration is consolidating vendor relationships around interoperable equipment ecosystems. Femtosecond laser and OCT system interoperability standards are reshaping procurement committee evaluation criteria toward bundled platform commitments.
For Market Incumbents: Compound defensive moats through backward integration into lens monomer chemistry and exclusive surgeon training academy partnerships. Lock in multi-year supply agreements with India's Aravind Eye Care System and US integrated delivery networks before REACH registration requirements filter substandard imports. Prioritize CE marking pathway acceleration for next-generation accommodating lens designs. For New Entrants and Emerging Players: Lead with equipment-leasing business models targeting Vietnam and Indonesia ophthalmology chains where phacoemulsification penetration remains below metropolitan India levels. Vietnam's underpenetrated private clinic segment offers the most penetrable entry point. Deploy telemedicine-enabled preoperative screening as a low-capital patient acquisition channel. For Investors and Strategic Acquirers: Capital is best deployed toward precision optics specialists with femtosecond patent estates and diagnostic-to-surgical workflow integration capabilities. Long-term viability hinges on regulatory navigation expertise across FDA Breakthrough Devices Program and EU MDR recertification pathways. Watch for reimbursement parity decisions between laser-assisted and conventional procedures as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Program Submission | Expedited review timelines compress competitive entry for novel accommodating lenses. |
| CE Marking Pathway Under EU MDR | Enhanced clinical evidence requirements extend development timelines for Class III implants. |
| Hospital System Partnership | Multi-year supply agreements with Cleveland Clinic and Mayo Clinic anchor premium volumes. |
| Software Companion Development | AI-assisted OCT-guided surgical planning differentiates integrated platform offerings. |
| Reimbursement Strategy | Medicare parity decisions dictate capital deployment for laser-assisted procedure adoption. |
Study Parameters
Cross-validation between primary interviews with ophthalmology department heads and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with cataract surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers inform demand-side dynamics. Secondary sources include CMS Medicare reimbursement databases, CDSCO medical device registration records, EMA parallel scientific advice documentation, and EU MDR notified body assessment reports. Bottom-up surgical volume modeling triangulates against top-down market size estimates.
Sensitivity analysis across premium lens penetration scenarios and laser-assisted procedure adoption curves tests forecast robustness. Segmentation dimensions span product type, procedure modality, delivery site, and end-user archetype across the modeling period. CAGRs derive from weighted average of historical procedure growth and technology substitution elasticity. Forecast inputs incorporate India's National Programme for Control of Blindness camp volumes and Japan's PMDA-approved femtosecond installation rates.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EU MDR conformity assessment timelines; material policy shifts would require re-modeling. Commodity price volatility in petroleum-derived monomers and surgeon training pipeline constraints represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Astigmatism Market
Ophthalmology
Ophthalmic Tonometers Market