
 Exophthalmos Treatment Market | 2026-2036
Exophthalmos Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Exophthalmos Treatment Market Foresight
European biopharmaceutical manufacturing capacity for biologic exophthalmos therapies is expanding as CDMOs add sterile fill-finish lines dedicated to ophthalmic indications. AbbVie Inc. leverages its immunology infrastructure to sustain development of targeted biologics for thyroid eye disease. Regeneron Pharmaceuticals, Inc. anchors its position through proprietary antibody platforms that address orbital inflammation. Novartis AG competes via established rare disease commercial networks spanning multiple continents.
Exophthalmos treatment encompasses pharmacologic, surgical, and radiologic interventions designed to reduce orbital volume, manage optic nerve compression, and restore ocular alignment and function. Biologic agents such as teprotumumab function as insulin-like growth factor-1 receptor antagonists that attenuate orbital fibroblast activation and glycosaminoglycan deposition behind the globe. Medication segments lead current revenue generation due to biologic pricing power and chronic administration requirements, while Surgery segments capture substantial margin pools from complex orbital decompression and strabismus correction procedures. Immunotherapy segments represent the fastest-growing category as IGF-1R inhibitors and B-cell modulators displace corticosteroid-first protocols in Graves' orbitopathy management.
The FDA's breakthrough therapy and orphan drug programs accelerate clinical timelines for novel exophthalmos therapeutics, while the EMA's PRIME designation pathway creates parallel European market access incentives. ISO 13485 quality management standards govern surgical instrument and orbital implant manufacturing, constraining supplier qualification and batch release protocols. Stakeholders must monitor evolving payer evidence requirements for biologic therapies versus established surgical alternatives as health technology assessment bodies tighten reimbursement criteria.
Market Dynamics
The FDA's orphan drug incentives and breakthrough therapy designations are compressing development timelines for novel exophthalmos therapeutics, while specialty clinics expand orbital care infrastructure to capture chronic patient volumes.
Growth Catalysts
- Biologic Mechanism Validation:IGF-1R inhibitor pathways now demonstrate reproducible efficacy in reducing orbital inflammation, validating investment in targeted immunotherapy platforms for thyroid eye disease management.
- Specialty Clinic Expansion:Tertiary ophthalmology centers in the United States are adding dedicated orbital units, creating concentrated referral networks that accelerate patient access to surgical and pharmacologic interventions.
- EMA PRIME Designation:European regulatory acceleration pathways reduce time-to-market for novel therapeutics, incentivizing manufacturers to prioritize rare disease indications with streamlined assessment protocols.
Market Restraints
- Biologic Manufacturing Concentration:Sterile fill-finish capacity for ophthalmic biologics concentrates among select CDMOs in Western Europe, creating supply bottlenecks during batch scaling.
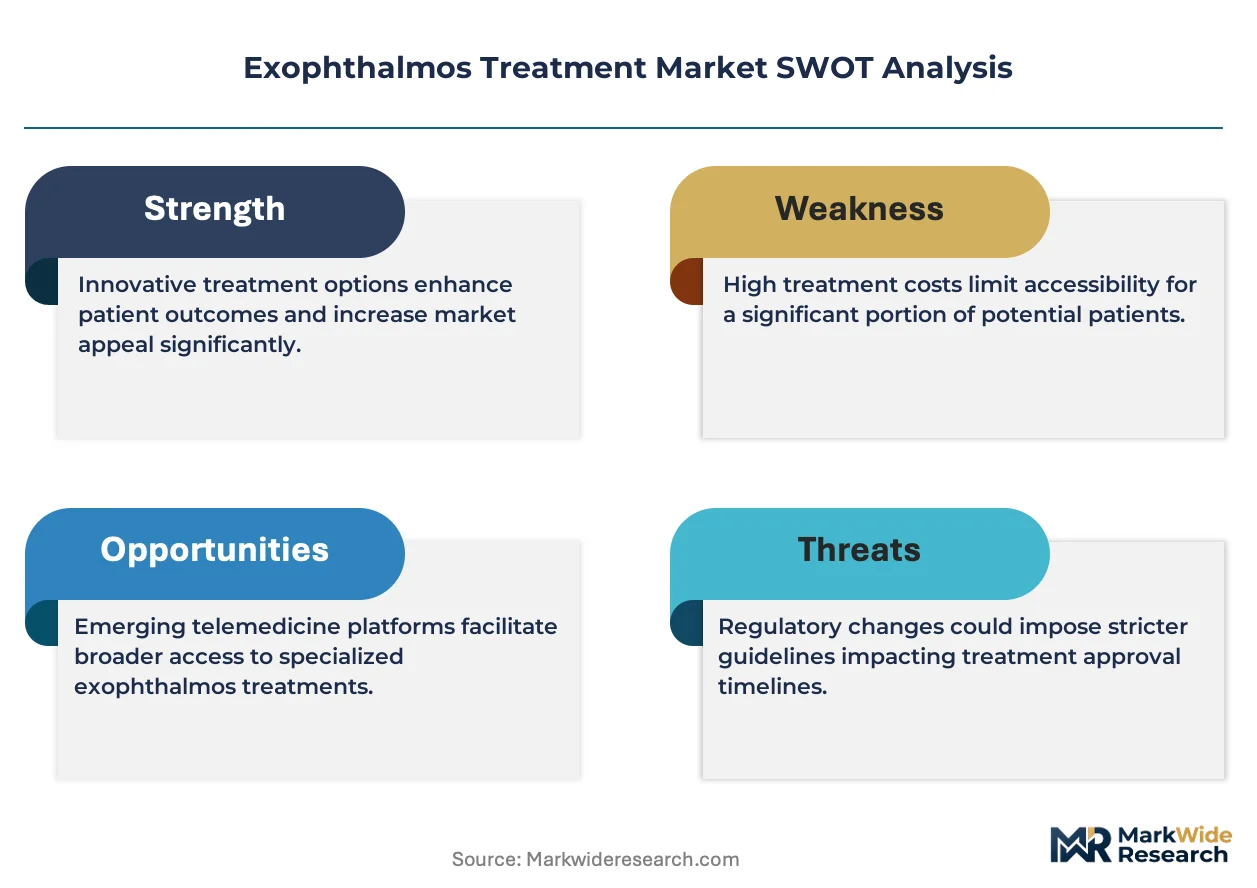
- Corticosteroid Substitution Threat:Low-cost generic corticosteroid protocols remain first-line therapy in many markets, pressuring uptake of higher-priced targeted biologics despite superior efficacy profiles.
- ISO 13485 Compliance Burden:Surgical instrument and orbital implant manufacturers face extended qualification timelines under quality management standards, constraining supplier onboarding and product release velocity.
Strategic Opportunities
- Underpenetrated Asian Markets:Graves' disease prevalence in India and China exceeds diagnosed treatment rates, presenting expansion potential for biologic therapies as healthcare access improves in tier-2 cities.
- Teleophthalmology Integration:Remote monitoring platforms enable orbital measurement tracking between clinic visits, reducing patient travel burden while maintaining disease surveillance for chronic cases.
- Health Technology Assessment Alignment:Payers in Germany and the United Kingdom are developing evidence frameworks for biologic-versus-surgical cost-effectiveness, creating pathways for premium therapy reimbursement.
Industry Challenges
- Oculoplastic Surgeon Scarcity:Complex orbital decompression and strabismus correction procedures require subspecialty training that outpaces fellowship program expansion, limiting surgical capacity growth.
- Biologic Cold Chain Integrity:Temperature-controlled distribution for monoclonal antibody therapies demands infrastructure investment that fragments last-mile delivery economics in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exophthalmos Treatment Market |
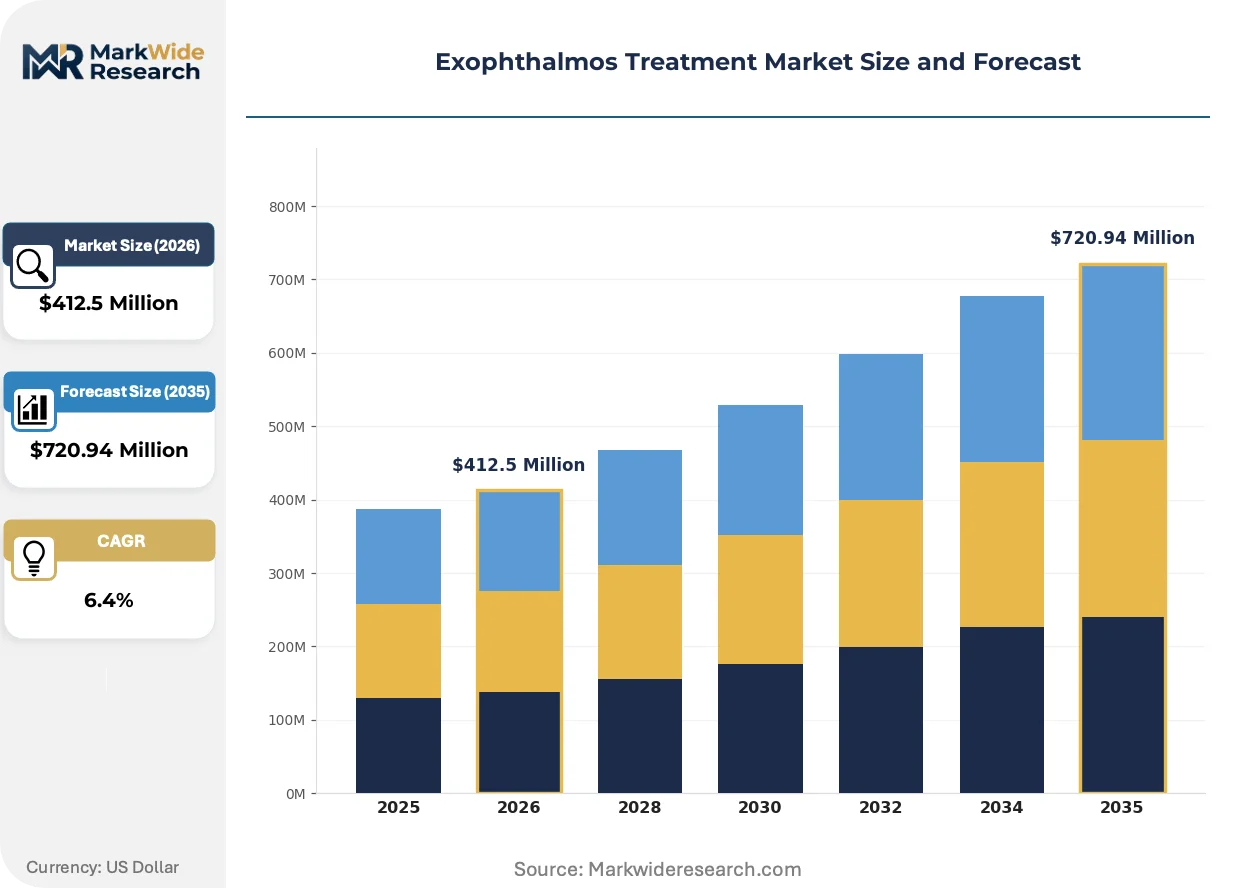
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgery, Radiation Therapy, Immunotherapy Therapy Area: Thyroid Eye Disease, Graves' Disease, Tumor Management, Ocular Hypertension End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | AbbVie Inc., Regeneron Pharmaceuticals, Inc., Novartis AG, Alcon Inc., Amgen Inc., Pfizer Inc., Bausch Health Companies Inc., Santen Pharmaceutical Co., Ltd., Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exophthalmos Treatment Market Shifts & Advancements
Orbital imaging and computational modeling are reshaping how clinicians plan interventions, while regulatory pathways evolve to accommodate personalized therapeutic approaches in rare disease indications.
Artificial intelligence-powered volumetric analysis is automating orbital fat and muscle quantification from CT and MRI scans, enabling precise surgical planning and treatment response tracking. Tertiary ophthalmology centers in the United States and Germany are deploying these tools at scale, reducing inter-observer variability in clinical trial endpoints and standardizing outcome measurement across sites. This automation is compressing the timeline from imaging to intervention decision, allowing faster patient stratification between medical and surgical management pathways.
The EMA's PRIME designation pathway creates parallel market access incentives to FDA breakthrough programs, accelerating clinical development for therapies addressing unmet needs in rare orbital diseases. Manufacturers gain enhanced scientific advice and accelerated assessment, reducing regulatory uncertainty for novel mechanism biologics. European biopharmaceutical firms are responding by prioritizing PRIME-eligible indications in Graves' orbitopathy, aligning development strategies with both US and European acceleration frameworks.
Patient advocacy networks are consolidating referral pathways to centers of excellence, concentrating demand among high-volume orbital specialists and compressing geographic access for rural populations. This concentration is displacing fragmented community-based management models that previously relied on general ophthalmology for initial diagnosis. The United Kingdom and the Netherlands exhibit this pattern most acutely, where national health system structures enable rapid network formation around established academic medical centers.
Exophthalmos Treatment Market Segmentation
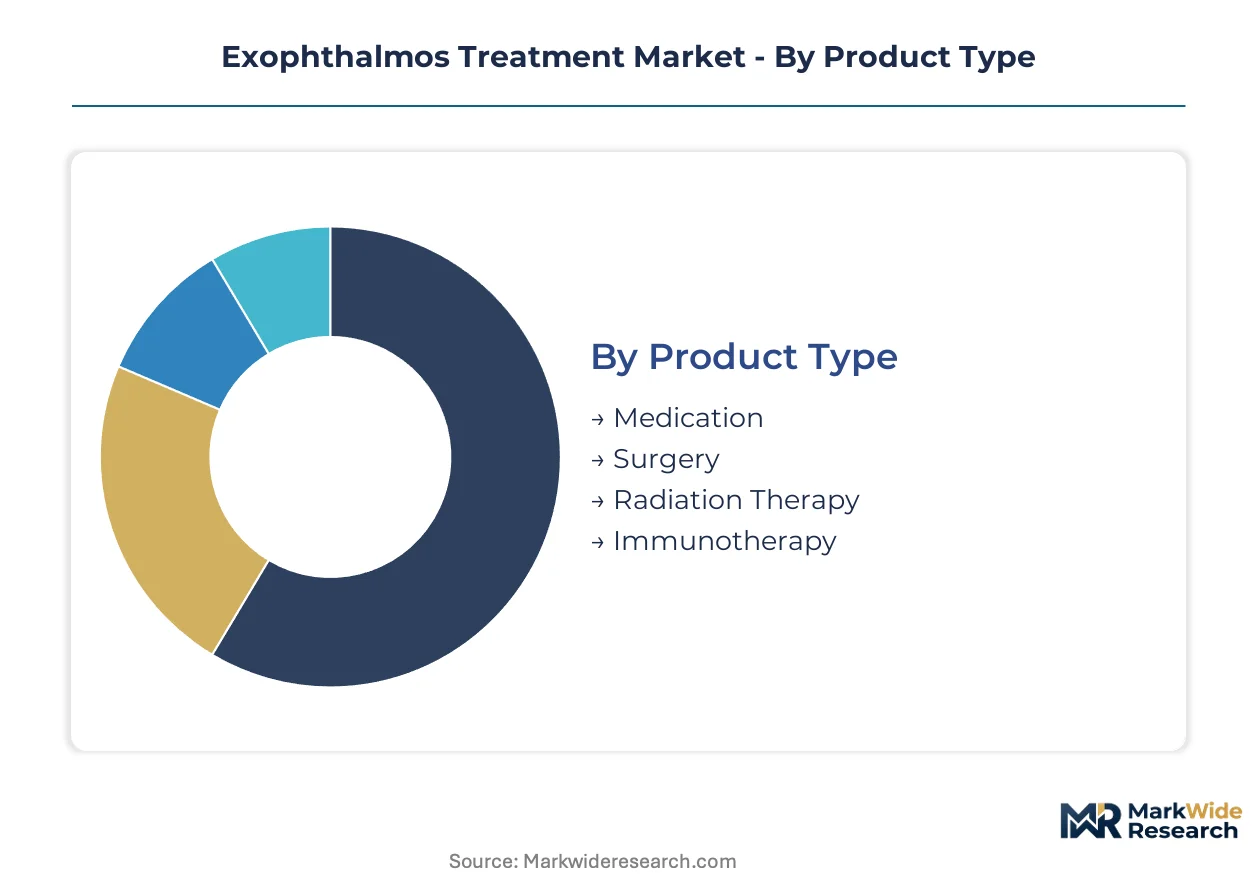
Exophthalmos treatment pathways fragment across therapeutic modalities, disease etiologies, and care settings. Each segment carries distinct regulatory burdens, reimbursement profiles, and infrastructure requirements that shape commercial strategy.
Product Type:
Medication and biologic segments require FDA BLA or EMA centralized marketing authorization with orphan drug exclusivity provisions. Surgical instruments fall under MDR Class IIa/IIb with notified body CE marking. Radiation devices need FDA 510(k) or EMA medical device regulation compliance.
- Medication:Small-molecule corticosteroids and orbital decongestants dominate first-line protocols. Demand concentrates in United States tertiary centers where prior authorization requirements favor established formularies over novel biologics.
- Surgery:Orbital decompression, strabismus correction, and eyelid repositioning procedures require specialized oculoplastic training. Germany and the Netherlands exhibit highest per-capita surgical volumes due to concentrated referral networks around academic medical centers.
- Radiation Therapy:Fractionated external beam protocols for active inflammatory phase disease. United Kingdom NHS England commissions these through specialized head-and-neck oncology networks with strict volume thresholds.
- Immunotherapy:IGF-1R inhibitors and B-cell modulators represent the fastest-expanding category. FDA breakthrough therapy designation accelerates development timelines for Graves' orbitopathy indications.
Leading the category by volume: Medication. Growing fastest: Immunotherapy.
Therapy Area:
Disease-specific protocols determine which regulatory pathways apply—autoimmune indications qualify for orphan drug incentives, while tumor management follows oncology reimbursement frameworks.
- Thyroid Eye Disease:Autoimmune orbital inflammation drives the majority of biologic therapy development. United States prevalence concentrates in women aged 40-60, with diagnostic delays common in rural markets lacking endocrinology-ophthalmology coordination.
- Graves' Disease:Systemic hyperthyroidism with orbital involvement requires multidisciplinary management. India and China present underdiagnosed populations where improving healthcare access in tier-2 cities expands addressable incidence.
- Tumor Management:Orbital lymphoma and metastatic lesions require histopathologic confirmation before therapy selection.
- Ocular Hypertension:Secondary pressure elevation from mass effect or venous congestion demands urgent intervention.
Highest treatment intensity: Thyroid Eye Disease. Steepest expansion trajectory: Graves' Disease as Asian diagnosis rates improve.
End User:
Site-of-care economics differ sharply—hospitals capture surgical margin pools while specialty clinics concentrate chronic biologic administration.
- Hospitals:Academic medical centers perform complex decompressions and manage acute optic neuropathy. United States Medicare severity-adjusted DRG payments incentivize high-volume orbital programs.
- Specialty Clinics:Dedicated oculoplastic and neuro-ophthalmology practices administer chronic biologic therapy. Netherlands and United Kingdom national health systems consolidate these into center-of-excellence networks.
- Home Care:Subcutaneous biologic self-administration emerging for stable maintenance patients.
- Research Laboratories:Academic sites conduct mechanistic studies and early-phase trials under FDA IND or EMA CTIS frameworks.
Revenue concentration: Hospitals. Patient volume growth: Specialty Clinics.
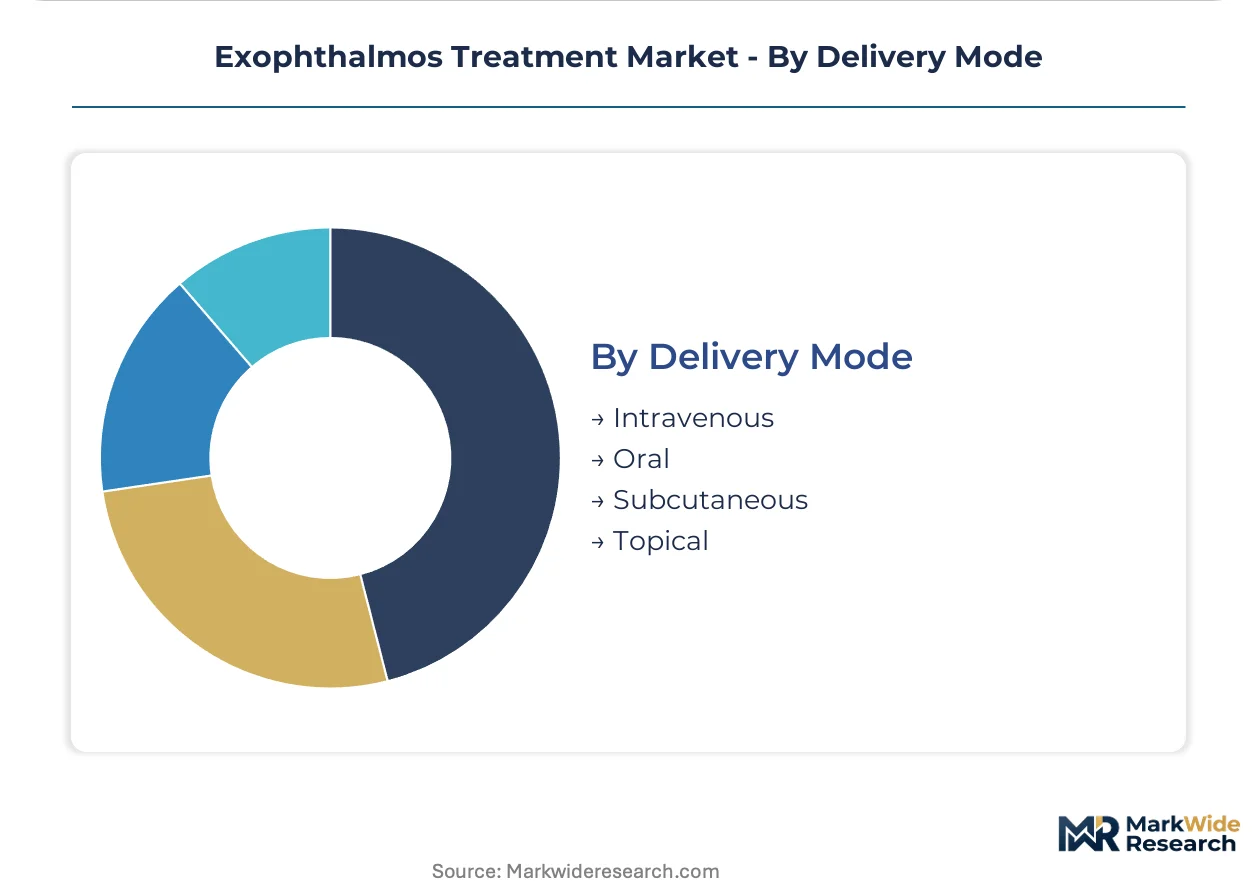
Delivery Mode:
Route selection determines cold chain requirements, pharmacy benefit versus medical benefit classification, and patient compliance profiles.
- Intravenous:Hospital or infusion center administration for teprotumumab and other monoclonal antibodies. United States site-of-service policies increasingly push these to lower-cost ambulatory settings.
- Oral:Corticosteroid tapers and immunosuppressants for maintenance therapy. Generic pricing pressure limits commercial opportunity despite high prescription volumes.
- Subcutaneous:Emerging biologic formulations targeting home administration convenience.
- Topical:Lubricants and surface anti-inflammatories for exposure keratopathy management.
Dominant by value: Intravenous. Gaining share fastest: Subcutaneous as formulation technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital biologics manufacturing clusters concentrate in Western Europe and the United States, with sterile fill-finish capacity anchoring supply chains around Basel, Boston, and Frankfurt. Tertiary ophthalmology centers drive demand concentration in metropolitan hubs across multiple continents.
United States
FDA breakthrough therapy designations compress clinical timelines for IGF-1R inhibitors targeting thyroid eye disease. Medicare severity-adjusted DRG payments incentivize high-volume orbital programs at academic medical centers. Tertiary ophthalmology centers cluster around Boston, New York, and Los Angeles, creating concentrated referral networks for complex decompressions.
Germany
EMA PRIME designation pathways accelerate assessment for rare disease biologics, reducing regulatory uncertainty for novel mechanism therapies. ISO 13485 quality standards govern surgical instrument manufacturing under MDR Class IIa/IIb frameworks. The Rhine-Main region hosts specialized CDMOs adding sterile fill-finish lines dedicated to ophthalmic indications.
United Kingdom
NHS England commissions radiation therapy through specialized head-and-neck oncology networks with strict volume thresholds. National health system structures enable rapid center-of-excellence formation around academic medical centers in London and Manchester. Patient advocacy networks consolidate referral pathways, displacing fragmented community-based management models.
India
Graves' disease prevalence exceeds diagnosed treatment rates in tier-2 cities, presenting expansion potential as healthcare access improves. CDSCO regulatory pathways govern biologic import and local manufacturing under evolving rare disease frameworks. Mumbai and Delhi-NCR concentrate endocrinology-ophthalmology coordination infrastructure for multidisciplinary orbitopathy management.
China
NMPA marketing authorization requirements for imported biologics create extended review timelines compared to Western regulators. Domestic manufacturing incentives under the PLI scheme attract CDMO investment for ophthalmic sterile fill-finish capacity. Shanghai and Beijing concentrate tertiary ophthalmology centers with dedicated orbital units for complex surgical interventions.
Exophthalmos Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue immunotherapy platforms and subcutaneous formulation convenience. The market structure reflects consolidation around immunology infrastructure holders and fragmentation among surgical instrument specialists. Three archetypes dominate: biologic platform developers leveraging antibody engineering, diversified ophthalmology portfolios spanning devices and pharmaceuticals, and rare disease commercial networks with multi-continent reach. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing sterile fill-finish slots at premium CDMOs and academic centers forming referral alliances.
Within the biologic platform tier, AbbVie Inc. and Regeneron Pharmaceuticals, Inc. exemplify immunology infrastructure leverage, while Novartis AG occupies a position reflecting established rare disease commercial networks. These three entities anchor the competitive structure through distinct strategic postures: AbbVie Inc. represents sustained development investment in targeted biologics, Regeneron Pharmaceuticals, Inc. exemplifies proprietary antibody platform deployment, and Novartis AG sits within the multi-continent rare disease commercialization archetype. Each occupies a differentiated position without direct overlap in mechanism or geographic emphasis.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Regeneron Pharmaceuticals, Inc. |
| Novartis AG |
| Alcon Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| Bausch Health Companies Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Teva Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Biologic-versus-surgical modality divergence creates distinct value capture mechanisms across the exophthalmos treatment landscape, with IGF-1R inhibitor pricing tethered to orphan drug exclusivity periods while orbital decompression procedures command bundled facility fees that reflect oculoplastic surgeon scarcity. This bifurcation manifests in supply chain configurations where sterile fill-finish capacity for monoclonal antibodies concentrates among Western European CDMOs, whereas surgical instrument sourcing fragments across ISO 13485-certified specialty manufacturers with extended qualification timelines.
Pricing Analysis
Warranty and service bundling separates chronic biologic administration models from acute surgical intervention pricing, with teprotumumab and comparable IGF-1R inhibitors incorporating patient support programs and infusion site coordination into their value proposition while orbital decompression fees bundle surgeon time, facility overhead, and implant materials without aftercare guarantees. Three-tier pricing structure across premium biologics, standard corticosteroid protocols, and economy generic immunosuppressants reflects FDA breakthrough therapy designation premiums versus commodity substitution pressure. Pricing pressure stems from Medicare site-of-service policies pushing intravenous administration toward lower-reimbursement ambulatory settings. Generic corticosteroid buyers exhibit highest price sensitivity; academic medical centers with dedicated orbital units demonstrate lowest sensitivity due to severity-adjusted DRG capture.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle chronic biologic demand, with hospital-based infusion centers and dedicated oculoplastic practices receiving temperature-controlled shipments from Basel, Frankfurt, and Boston manufacturing clusters. Sterile fill-finish capacity concentrates in Switzerland, Germany, and the United States, while orbital implant raw materials draw from medical-grade titanium suppliers in Germany and the United States plus biocompatible polymer sources in Japan. Single-source vulnerability for IGF-1R inhibitor active pharmaceutical ingredients creates supply continuity exposure. Distribution runs through cold chain logistics partners with validated last-mile capabilities for monoclonal antibody therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug incentives and ISO 13485 quality management standards erect substantial compliance cost barriers that protect incumbent positions while constraining new entrant scalability, creating a cost-of-compliance moat where certification investment separates viable competitors from marginal participants.
For Market Incumbents: Lock in sterile fill-finish capacity through long-term CDMO agreements at Basel and Frankfurt facilities before competitor expansion absorbs available slots. Prioritize backward integration into orbital implant manufacturing to capture margin pools currently fragmented among ISO 13485-certified specialty suppliers. Corticosteroid substitution threat from generic protocols demands defensive formulary access investment. For New Entrants and Emerging Players: Subcutaneous biologic formulation technology offers a technology-first wedge into the maintenance therapy segment currently dominated by intravenous infusion models. Target tier-2 cities in India where Graves' disease diagnosis rates lag prevalence and healthcare access improvement creates addressable incidence expansion. Deploy teleophthalmology-enabled remote monitoring as a go-to-market angle that reduces patient travel burden and differentiates against incumbent clinic-dependent models. For Investors and Strategic Acquirers: Re-rating potential sits with rare disease commercial networks possessing multi-continent regulatory infrastructure given EMA PRIME designation acceleration and FDA breakthrough therapy pathway convergence. Long-term viability favors platforms with both biologic development capabilities and surgical device portfolios spanning the full intervention spectrum. Watch for CDMO capacity expansion announcements as an inflection indicator for supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Capacity Lock-in | Long-term sterile fill-finish agreements at Basel and Frankfurt facilities secure supply continuity for IGF-1R inhibitors. |
| Subcutaneous Formulation Development | Self-administration convenience targets maintenance therapy patients currently tethered to infusion centers. |
| Teleophthalmology Platform Integration | Remote orbital measurement tracking reduces patient travel burden while maintaining disease surveillance. |
| Center-of-Excellence Alliance Formation | Academic medical center referral networks concentrate high-volume surgical demand and accelerate patient stratification. |
| Health Technology Assessment Alignment | Germany and United Kingdom evidence frameworks create pathways for biologic-versus-surgical cost-effectiveness reimbursement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with oculoplastic surgeons, formulary directors at United States payers, CDMO operations managers, and regulatory affairs leads at biopharmaceutical firms. FDA BLA submissions, EMA centralized marketing authorization documents, ClinicalTrials.gov entries, and ISO 13485 audit reports provided structured validation. Bottom-up patient flow modeling and top-down revenue triangulation converged on segment-level estimates.
Granularity-level modeling operated at the intersection of therapeutic modality, disease etiology, and care setting dimensions, with separate projections for medication, surgery, radiation therapy, and immunotherapy segments across thyroid eye disease, Graves' disease, tumor management, and ocular hypertension indications. Administration route, site-of-service economics, and regional regulatory cluster variations informed value calculations throughout the projection horizon. CAGRs derived from epidemiological incidence trends, diagnosis rate improvement assumptions, and therapy penetration curves specific to each geography.
Several conditions sit outside the modeled scope, including pipeline failure rates for Phase III IGF-1R inhibitors, oculoplastic fellowship program expansion trajectories, and unforeseen regulatory pathway modifications. Forecasts reflect documented assumptions regarding biologic pricing persistence, surgical capacity growth, and payer evidence requirement evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Nystagmus Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market