
 Ophthalmology Diagnostics Market | 2026-2036
Ophthalmology Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmology Diagnostics Market Outlook
China is rewriting ophthalmology diagnostics manufacturing capacity as domestic producers scale optical coherence tomography module production. Carl Zeiss Meditec AG leverages its German engineering heritage to sustain premium positioning across retinal imaging platforms. Topcon Corporation anchors Asian supply chains through its Tokyo-based precision optics manufacturing. NIDEK CO., LTD competes aggressively on refractive diagnostic systems across outpatient eye care networks.
Ophthalmology diagnostics encompasses instruments that measure ocular structure and visual function through optical, electrophysiological, or tomographic methods, with resolution thresholds often reaching micrometer-scale for retinal layer segmentation. These systems serve the primary commercial purpose of enabling early disease detection, treatment planning, and post-operative monitoring across eye care practices. Optical coherence tomography commands the dominant margin pool due to its irreplaceable role in glaucoma progression tracking and macular degeneration management. Portable devices within the delivery mode dimension represent the fastest structural expansion as point-of-care screening penetrates rural and mobile clinic settings. Cataract diagnosis applications maintain volume leadership while retinal disorder analysis captures disproportionate R&D investment from device manufacturers.
FDA premarket notification requirements for Class II ophthalmic devices establish baseline safety and efficacy thresholds that shape product development cycles for US market entrants. EMA medical device regulation and ISO 10993 biocompatibility standards collectively govern European market access and material selection for patient-contact components. Japan's PMDA enforces stringent quality management system audits that filter out lower-tier competitors from its high-value procurement landscape. Stakeholders must monitor how cloud-based diagnostic platforms navigate divergent data sovereignty requirements across FDA, EMA, and PMDA jurisdictions as remote screening expands.
Market Dynamics
AI-enabled diagnostic algorithms are compressing clinical decision timelines while forcing hardware manufacturers to recalibrate software integration architectures. Hospital procurement committees now weight algorithmic interpretability equally against optical resolution specifications.
Growth Catalysts
- Population-wide diabetic retinopathy screening mandates:National health systems in Germany and Japan now reimburse point-of-care retinal imaging. This expands addressable patient pools beyond traditional clinic settings.
- FDA breakthrough device designation pathway:Expedited review timelines for AI-diagnostic combinations accelerate commercialization cycles. Developers prioritize US market entry to capture premium pricing.
- Optical coherence tomography angiography:This non-invasive vascular imaging modality eliminates fluorescein dye risks. Outpatient networks adopt it for macular degeneration monitoring.
Market Restraints
- Indium gallium arsenide detector shortages:Near-infrared sensor supply concentrates among Japanese and German specialty foundries. OEMs face 14-18 month component lead times.
- EMA MDR clinical evidence requirements:Class IIa ophthalmic devices now demand prospective validation studies. Small manufacturers lack capital to sustain European market access.
- Smartphone-based visual acuity apps:These low-cost substitutes capture basic screening volumes in emerging markets. Dedicated hardware vendors lose price-sensitive segments.
Strategic Opportunities
- Rural India vision care gaps:Tele-ophthalmology networks lack diagnostic-grade imaging endpoints. Portable OCT units with satellite connectivity address this infrastructure deficit.
- EU AI Act high-risk system classification:Compliance mandates create consultative service revenue streams. Device vendors bundle algorithmic audit packages with hardware sales.
- Corneal biomechanical analysis convergence:Integration of Scheimpflug tomography with air-puff tonometry enables single-device glaucoma and ectasia risk stratification.
Industry Challenges
- Computational pathology talent scarcity:Retinal image annotation requires dual expertise in ophthalmology and machine learning. Academic pipelines produce fewer than 200 qualified specialists annually.
- Legacy PACS integration complexity:Hospital IT departments resist proprietary data formats from new OEMs. DICOM conformance testing extends deployment timelines by 4-6 months.
- ISO 13485 audit backlogs:Notified body capacity constraints delay quality management system certifications. Manufacturers queue 8-12 months for initial assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmology Diagnostics Market |
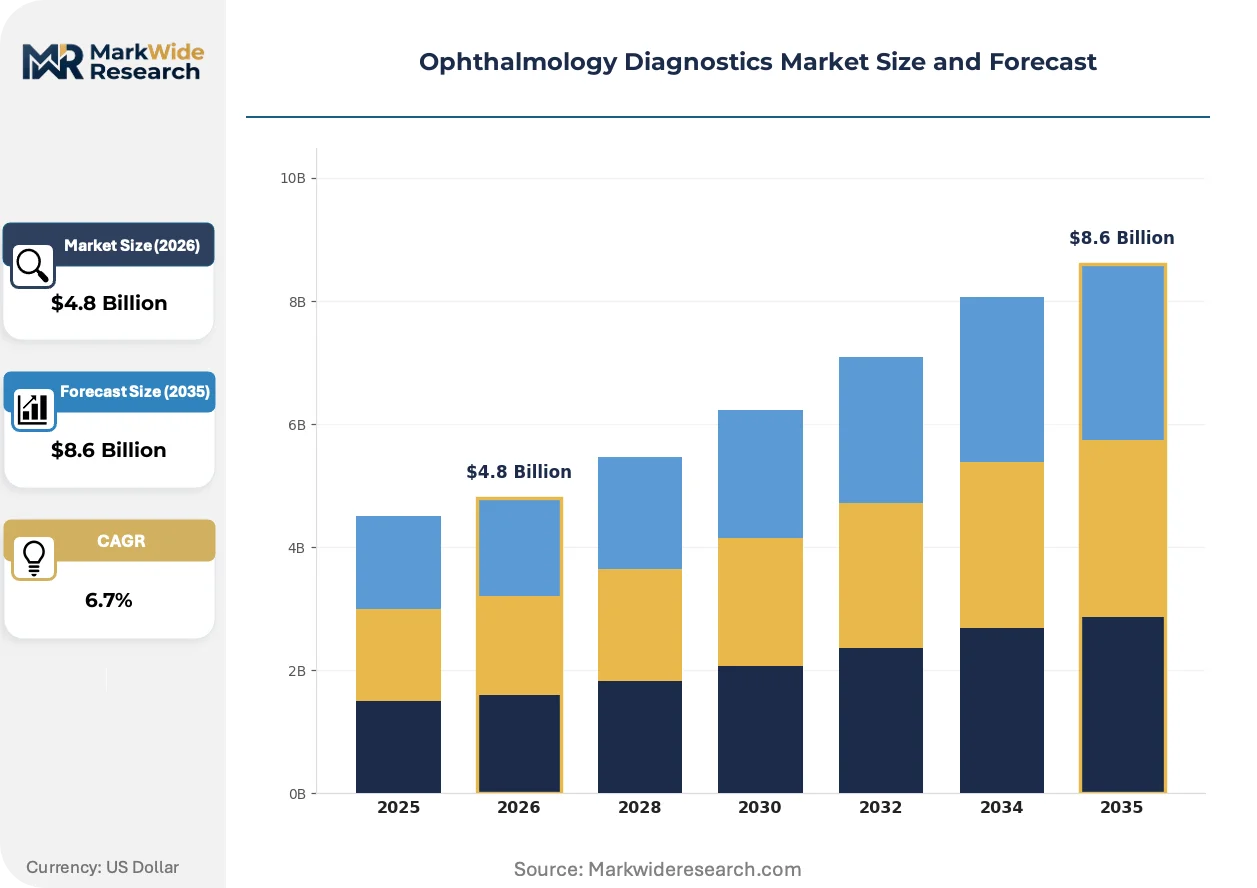
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmoscopes, Retinal Cameras, Visual Field Analyzers, Optical Coherence Tomography Application: Cataract Diagnosis, Glaucoma Screening, Retinal Disorder Analysis, Refractive Error Assessment End User: Hospitals, Clinics, Optical Centers, Research Institutions Delivery Mode: Standalone Devices, Portable Devices, Integrated Systems, Cloud-Based Solutions |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, NIDEK CO., LTD, Alcon Inc., Bausch & Lomb Incorporated, Ziemer Ophthalmic Systems AG, Canon, Haag-Streit Group, Essilor International S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmology Diagnostics Market Strategic Shifts
Spectral-domain detection architectures are supplanting time-domain systems while computational imaging techniques extract diagnostic signals from lower-cost hardware. These shifts compress equipment replacement cycles and democratize access.
Optical coherence tomography is migrating from spectral-domain to swept-source architectures across premium glaucoma practices. Academic medical centers in the United States and Japan lead this transition, completing platform refreshes within 36-month windows. Swept-source systems penetrate deeper choroidal layers, compressing the clinical utility gap between structural imaging and invasive angiography.
EMA Medical Device Regulation Annex XVI expansion now captures software-only diagnostic products previously exempt from conformity assessment. This reclassification forces standalone AI algorithm developers to establish quality management systems and clinical evidence portfolios. Retinal image analysis platforms face the steepest compliance burden as notified bodies lack standardized review templates for machine learning-based devices.
Eye care networks are unbundling capital equipment purchases from service contracts and software subscriptions. Hospital procurement teams in Germany negotiate three-year total cost of ownership agreements rather than upfront device acquisitions. This financialization trend pressures OEM margins while favoring vendors with captive financing capabilities or third-party leasing partnerships.
Ophthalmology Diagnostics Market Segmentation
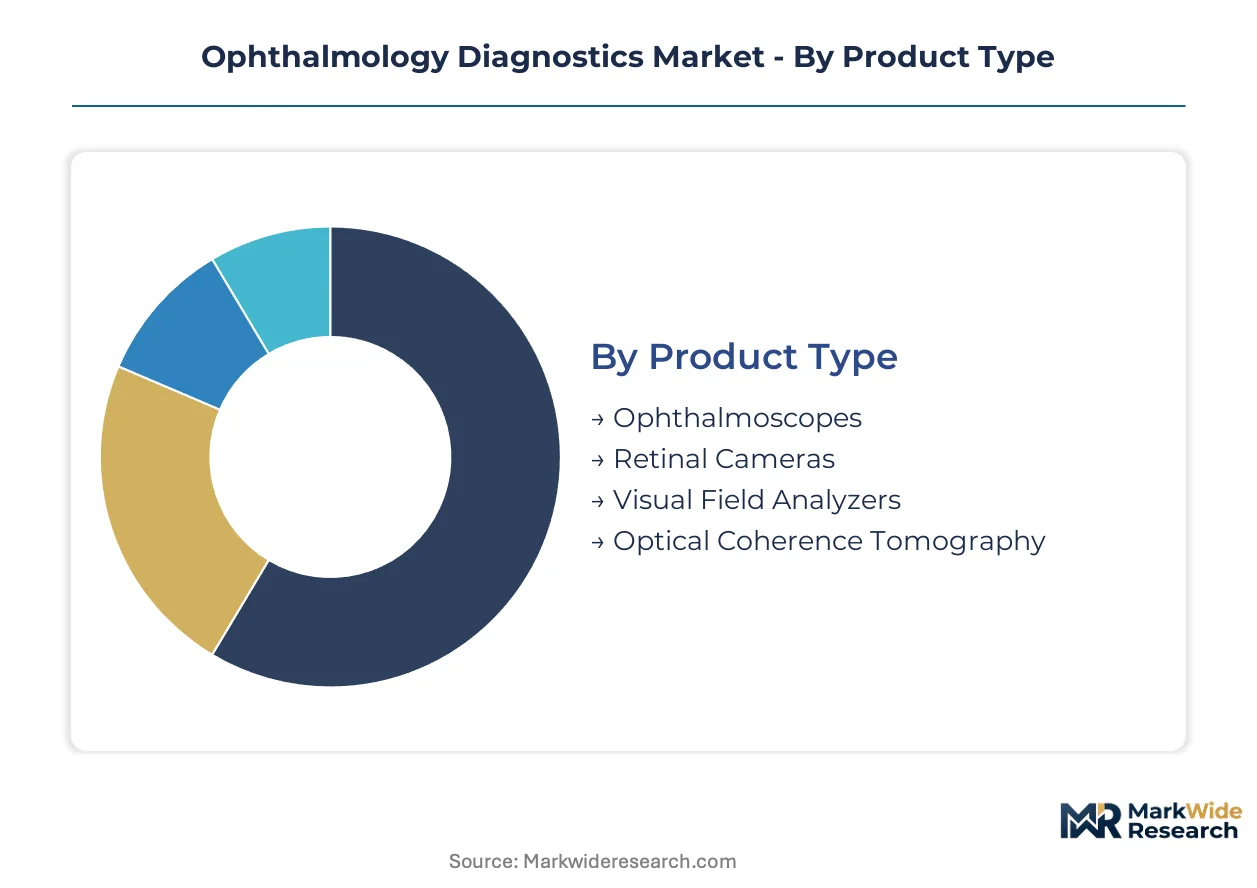
Ophthalmology diagnostics manufacturers configure product portfolios around four intersecting dimensions. Equipment replacement cycles, reimbursement pathways, and point-of-care penetration rates vary sharply across these boundaries, forcing vendors to prioritize segments with aligned capital and clinical workflows.
Product Type:
Optical coherence tomography systems turn over every 4-5 years as imaging depth and speed specifications advance, while ophthalmoscopes persist 8-12 years in primary care settings. Replacement velocity shapes service contract pricing and trade-in program design.
- Optical Coherence Tomography:Spectral-domain and swept-source architectures capture cross-sectional retinal images at micrometer resolution. Academic medical centers in the United States and Japan drive platform refreshes for choroidal visualization capabilities. Premium pricing reflects irreplaceable utility in glaucoma progression monitoring and macular degeneration management.
- Retinal Cameras:Non-mydriatic fundus photography systems enable diabetic retinopathy screening without pupil dilation. Germany and Japan now reimburse point-of-care deployment, expanding volumes beyond hospital ophthalmology departments into primary care networks.
- Visual Field Analyzers:Automated perimetry systems map functional vision loss for glaucoma staging.
- Ophthalmoscopes:Direct and indirect examination instruments remain the lowest-cost entry point for basic fundus assessment.
Optical coherence tomography dominates installed base value. Retinal cameras are where expansion concentrates.
Application:
Procedure volume and reimbursement intensity diverge across diagnostic applications, with screening mandates in specific geographies redirecting capital flows.
- Cataract Diagnosis:Biometry and corneal topography systems support surgical planning for the highest-volume ophthalmic procedure globally. Preoperative measurement precision directly determines intraocular lens selection accuracy.
- Glaucoma Screening:Tonometry, perimetry, and OCT structural assessment combine for early detection protocols. Population-wide screening programs in Japan generate sustained equipment demand across outpatient networks.
- Retinal Disorder Analysis:Age-related macular degeneration and diabetic retinopathy detection commands disproportionate R&D investment from device manufacturers.
- Refractive Error Assessment:Wavefront aberrometry and corneal mapping guide laser vision correction candidacy decisions.
Cataract diagnosis maintains procedure volume leadership. Glaucoma screening is climbing the fastest as national programs scale.
End User:
Capital availability and procurement sophistication fragment sharply across care settings, with hospital systems favoring bundled service agreements.
- Hospitals:Eye care departments within tertiary centers deploy full diagnostic suites with PACS integration requirements. Procurement committees weight algorithmic interpretability equally against optical resolution specifications.
- Clinics:Outpatient ophthalmology practices prioritize throughput-optimized platforms with streamlined technician workflows.
- Optical Centers:Retail vision care settings concentrate refractive diagnostic volumes with limited pathology assessment capabilities.
- Research Institutions:Academic medical centers access early-access prototypes and drive technology validation studies.
Hospitals anchor premium system deployment. Clinics are gaining share fastest as ambulatory surgery center networks expand.
Delivery Mode:
Capital deployment models are unbundling from traditional equipment purchase, with subscription and leasing structures penetrating specific customer tiers.
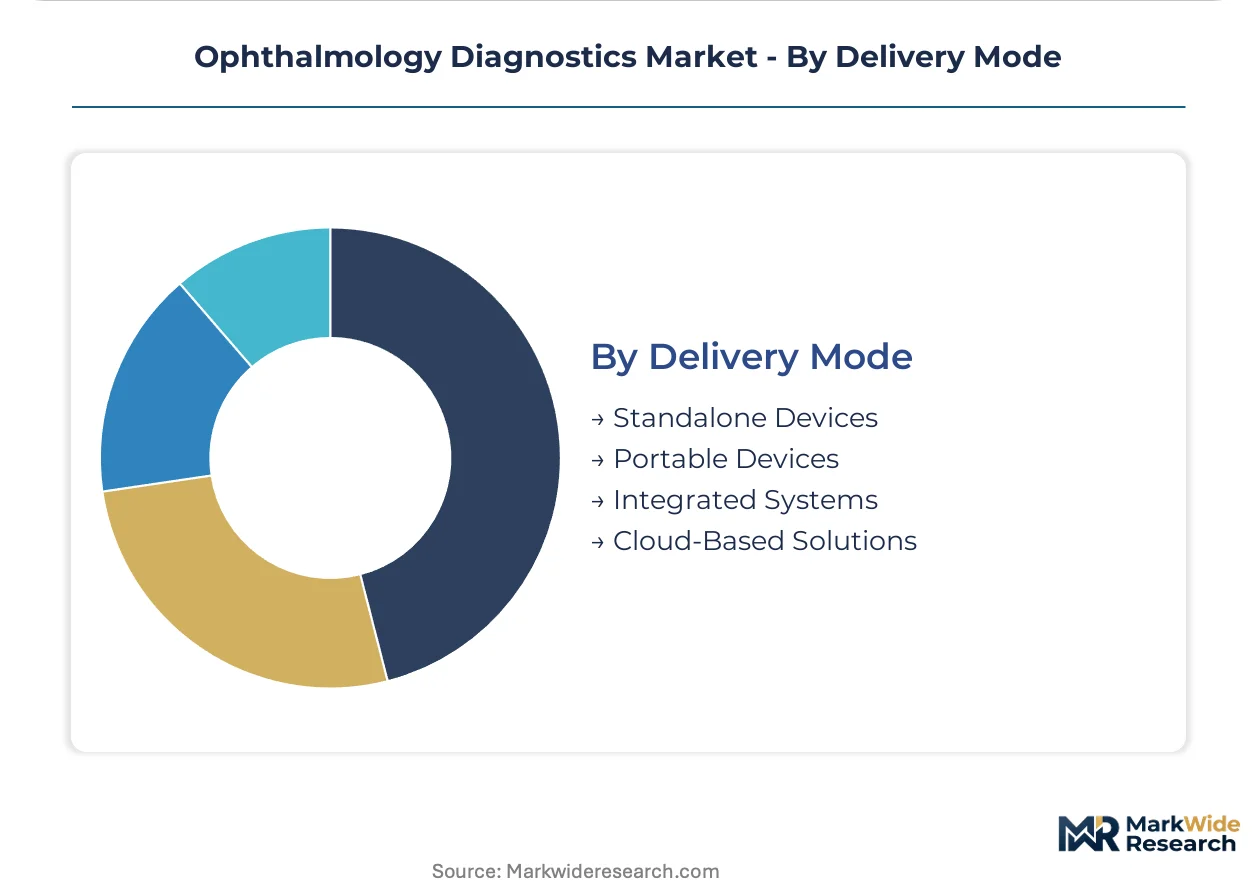
- Portable Devices:Battery-powered fundus cameras and handheld OCT units enable rural and mobile clinic screening. Tele-ophthalmology networks in India lack diagnostic-grade imaging endpoints, creating infrastructure deficit opportunities.
- Cloud-Based Solutions:AI-enabled image analysis platforms navigate divergent FDA, EMA, and PMDA data sovereignty requirements as remote screening expands.
- Standalone Devices:Self-contained diagnostic workstations persist in settings with limited IT infrastructure.
- Integrated Systems:Multi-modal platforms combine tomography, photography, and angiography in unified hardware footprints.
Standalone devices dominate legacy installed base. Portable devices are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty foundries in Japan and Germany concentrate near-infrared detector supply, creating 14-18 month lead times that constrain OEM capacity planning. Hospital procurement committees in the United States, Germany, and Japan now weight algorithmic interpretability equally against optical resolution specifications.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive swept-source OCT platform refreshes within 36-month cycles. FDA breakthrough device designation for AI-diagnostic combinations accelerates commercialization timelines and attracts premium pricing strategies. The Cleveland Clinic and Johns Hopkins anchor validation studies for computational imaging techniques.
Germany
Population-wide diabetic retinopathy screening mandates now reimburse point-of-care retinal imaging, expanding volumes beyond hospital ophthalmology departments. EMA MDR Annex XVI reclassification captures software-only diagnostic products, forcing standalone AI developers to establish quality management systems. Carl Zeiss Meditec AG leverages its Oberkochen engineering heritage across retinal imaging platforms.
Japan
PMDA enforces stringent quality management system audits that filter lower-tier competitors from high-value procurement landscapes. METI-funded glaucoma screening programs generate sustained equipment demand across outpatient networks. Topcon Corporation anchors Asian supply chains through its Tokyo-based precision optics manufacturing operations.
China
Domestic producers scale optical coherence tomography module production, rewriting regional manufacturing capacity. NMPA clearance pathways for Class II ophthalmic devices establish baseline safety thresholds that shape product development cycles. Yangtze River Delta clusters concentrate optical component fabrication for export markets.
India
Tele-ophthalmology networks lack diagnostic-grade imaging endpoints across rural vision care gaps. CDSCO regulates medical device imports while domestic manufacturers pursue PLI scheme incentives for local production. Maharashtra and Karnataka host emerging assembly operations for portable fundus camera distribution.
Ophthalmology Diagnostics Market Competitive Environment
Precision optics specialists and diversified medical technology conglomerates split the market across premium and volume tiers. The vendor base concentrates among German engineering heritage firms, Japanese precision manufacturers, and Swiss ophthalmic instrument specialists. Two strategic archetypes dominate: vertically integrated optical component producers and modular platform assemblers. Competitive moves center on algorithmic software bundling with hardware sales and three-year total cost of ownership financing structures.
Within the precision optics tier, Carl Zeiss Meditec AG and Topcon Corporation exemplify divergent geographic anchoring strategies. Ziemer Ophthalmic Systems AG occupies a position among Swiss-engineered surgical diagnostic specialists. Haag-Streit Group represents the heritage instrument manufacturer archetype with embedded clinical workflow relationships. These named entities illustrate how engineering origin and customer intimacy models stratify competitive positioning without implying specific market share claims.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| NIDEK CO., LTD |
| Alcon Inc. |
| Bausch & Lomb Incorporated |
| Ziemer Ophthalmic Systems AG |
| Canon |
| Haag-Streit Group |
| Essilor International S.A |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta optical component clusters translate manufacturing scale into asymmetric pricing power for domestic Chinese OEMs. Indium gallium arsenide detector shortages at Japanese and German specialty foundries force 14-18 month procurement queues, compressing margin buffers for hardware assemblers lacking captive supply arrangements.
Pricing Analysis
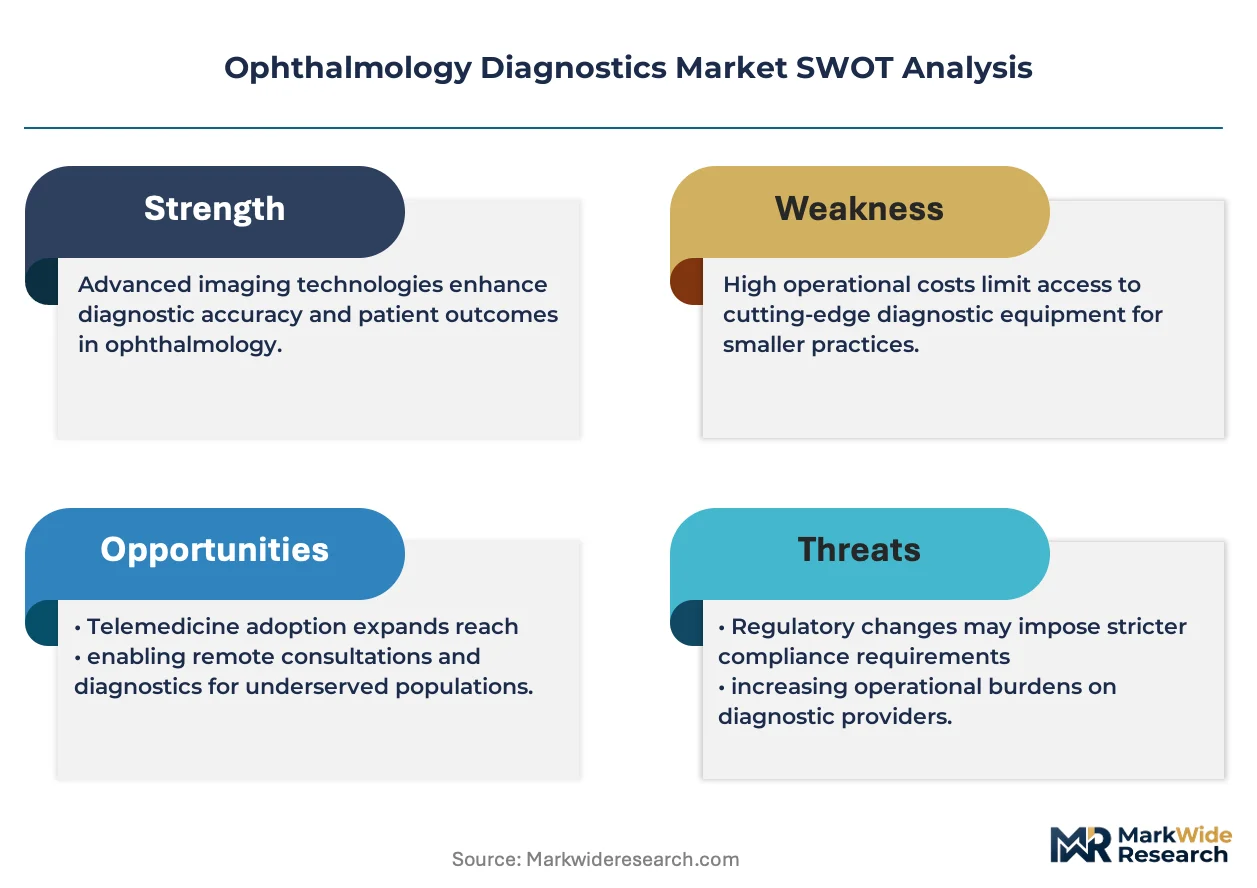
FDA premarket notification requirements dictate the pricing tier structure across ophthalmology diagnostics, separating Class II clearance holders from lower-validated competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status, after-sales service bundling, and optical resolution specifications. Cost compression in the economy tier intensifies as smartphone-based visual acuity apps capture basic screening volumes. Hospital procurement committees demonstrate lowest price sensitivity; primary care networks exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Japanese and German precision optics suppliers filter working capital constraints downstream to modular platform assemblers. Manufacturing concentration centers on Japan, Germany, and China for near-infrared sensors, spectral-domain detection modules, and optical coherence tomography subassemblies. Supply chain vulnerability rests on single-source indium gallium arsenide detector fabrication. Distribution runs through hospital procurement committees, GPO contracts, and direct OEM sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled diagnostic algorithms are compressing clinical decision timelines while forcing hardware manufacturers to recalibrate software integration architectures. FDA breakthrough device designation pathways accelerate commercialization cycles and attract premium pricing strategies.
For Market Incumbents: Pre-empt smartphone-based screening substitution by bundling algorithmic interpretability modules with spectral-domain hardware refreshes. Secure captive indium gallium arsenide supply through backward integration into Japanese detector foundries or long-term offtake agreements. Carl Zeiss Meditec and Topcon Corporation exemplify the engineering heritage defense. For New Entrants and Emerging Players: Build out portable OCT units with satellite connectivity for rural India tele-ophthalmology networks, where diagnostic-grade imaging endpoints remain absent. Target EU AI Act high-risk system compliance services as consultative revenue streams bundled with hardware sales. Prioritize CDSCO clearance pathways for Maharashtra and Karnataka assembly operations. For Investors and Strategic Acquirers: Long-term, this sits as a precision optics consolidation play because spectral-domain to swept-source architecture transitions compress equipment replacement cycles to 36-month windows. Acquisition targets include Swiss-engineered surgical diagnostic specialists with embedded clinical workflow relationships. Monitor PMDA quality management system audit backlogs as inflection signals for Japanese market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review timelines accelerate AI-diagnostic combination commercialization for US market entry. |
| EMA MDR Annex XVI Compliance | Software-only diagnostic reclassification forces standalone AI developers to establish quality management systems. |
| Hospital System Partnership | Three-year total cost of ownership agreements replace upfront device acquisitions in German procurement. |
| Software Companion Development | Algorithmic audit packages bundled with hardware sales address EU AI Act high-risk system mandates. |
| Reimbursement Strategy | Population-wide diabetic retinopathy screening mandates in Germany and Japan expand point-of-care volumes. |
Study Parameters
Operator-level perspectives from ophthalmology department heads, biomedical engineers, hospital purchasing committees, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device registration databases, PMDA approval summaries, and hospital procurement records. Bottom-up equipment shipment analysis triangulated against top-down healthcare expenditure flows across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, application, end user, and delivery mode segmentation dimensions. CAGRs derived from equipment replacement cycle velocity, reimbursement pathway expansion rates, and point-of-care penetration trajectories. Swept-source OCT platform refresh timing and AI algorithm regulatory clearance cadence served as industry-specific forecast inputs throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese optical component producers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Ophthalmic Devices Market