
 Tonometry Market | 2026-2036
Tonometry Market Size, Share, and Industry Trends Forecast 2026-2036
Tonometry Market Outlook
Ophthalmic technician training capacity is rotating toward digital tonometry platforms faster than legacy Goldmann calibration programs can replenish. Topcon Corporation leverages its optical coherence technology lineage to anchor premium hospital contracts across East Asia. Reichert Inc. competes through specialized pneumatic tonometer designs that dominate veterinary and research niches. Nidek Co. Ltd. sustains manufacturing scale in mechanical applanation segments where replacement cycles remain predictable.
Tonometry measures intraocular pressure through corneal deformation analysis, with Goldmann applanation remaining the reference standard at 3.06 mm probe diameter despite requiring topical anesthesia. The technology serves glaucoma risk stratification, treatment monitoring, and population screening programs where early detection prevents optic nerve damage. Non-contact pneumatic systems lead volume growth in ophthalmology clinics by eliminating patient contact and cross-contamination protocols. Optical coherence tonometry occupies the fastest-expanding margin pool as swept-source imaging integrates pressure mapping with retinal nerve fiber analysis. Dynamic contour devices remain concentrated in research institutions where continuous monitoring protocols justify capital intensity.
The FDA regulates tonometers as Class II medical devices under 21 CFR 886.1930, while the EU Medical Device Regulation requires notified body certification for applanation and non-contact systems entering European markets. Japan's PMDA enforces JIS T 0601 electromagnetic compatibility standards that shape product redesign cycles for Asian market access. Stakeholders must monitor how reimbursement coding for home tonometry influences capital allocation between clinic-based and patient-operated monitoring modalities.
Market Dynamics
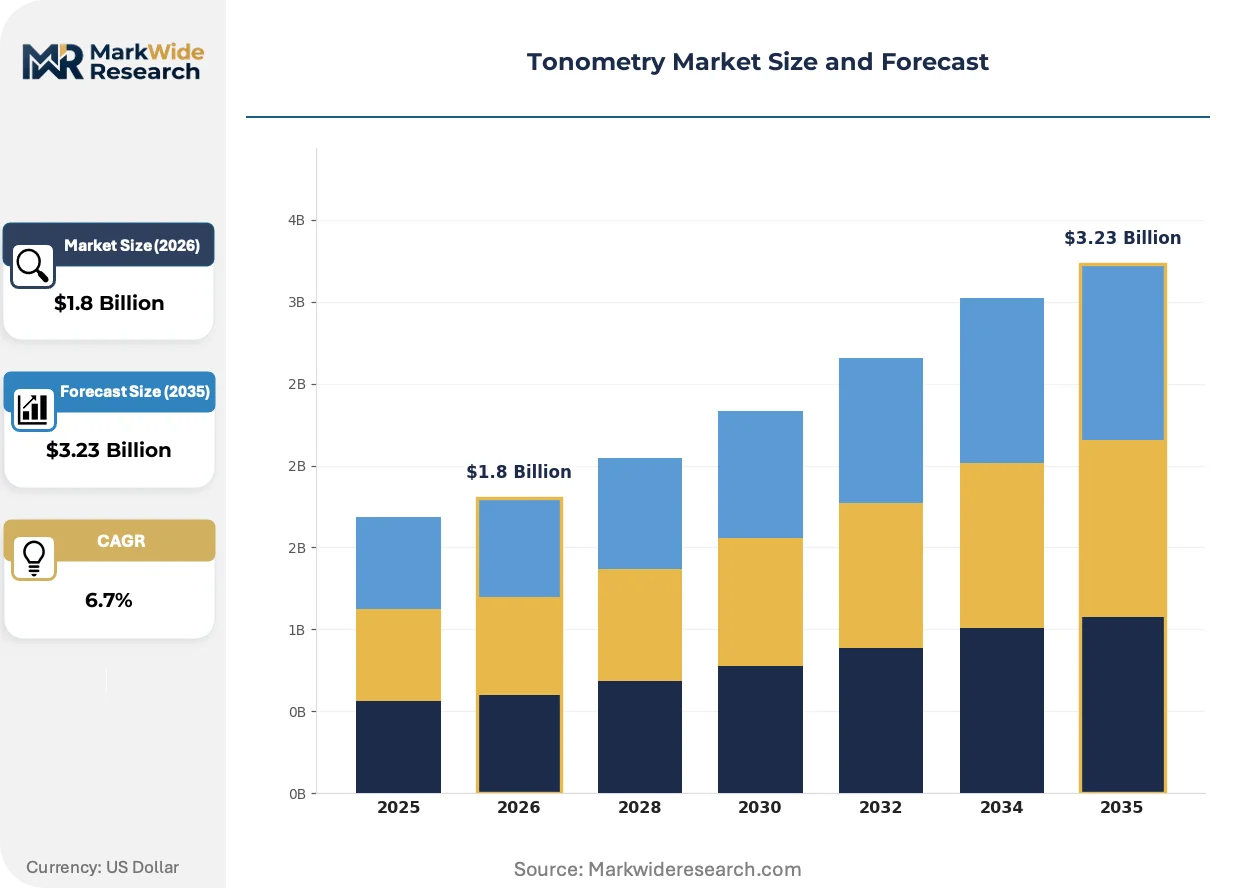
The tonometry market pivots on the FDA's streamlined Class II review pathways, which compress clearance timelines for non-contact and optical coherence devices while ophthalmology clinics accelerate replacement of legacy Goldmann systems.
Growth Catalysts
- Non-contact pneumatic adoption:Ophthalmology clinics eliminate topical anesthesia protocols and cross-contamination risks, expanding throughput in high-volume screening environments.
- Japan's PMDA electromagnetic standards:Manufacturers redesign product cycles to meet JIS T 0601 compliance, accelerating Asian market entry for swept-source imaging platforms.
- Glaucoma screening maturation:Germany's statutory health insurance funds expand reimbursement for population-based intraocular pressure monitoring, driving device procurement in ambulatory settings.
Market Restraints
- Goldmann reference standard lock-in:Clinical trials and regulatory submissions still require 3.06 mm applanation correlation, forcing dual-platform validation costs.
- Pneumatic component supply concentration:Precision air pressure sensors concentrate in East Asian contract manufacturers, exposing OEMs to logistics volatility.
- Optical coherence capital intensity:Swept-source laser sources and high-speed detectors demand upfront investment that restricts research institution adoption.
Strategic Opportunities
- Home tonometry reimbursement coding:United States Medicare Advantage plans pilot remote monitoring codes that could shift capital toward patient-operated devices.
- Veterinary ophthalmology expansion:Companion animal specialty practices in France and the United Kingdom adopt calibrated pneumatic systems for glaucoma screening in brachycephalic breeds.
- Retinal nerve fiber convergence:Optical coherence tonometry platforms integrate pressure mapping with structural imaging, consolidating diagnostic workflow in hospital ophthalmology departments.
Industry Challenges
- Digital platform technician training:Legacy Goldmann calibration expertise retires faster than community colleges and vocational programs can deploy non-contact certification curricula.
- Dual regulatory pathway synchronization:Manufacturers must align FDA 510(k) submissions with EU MDR notified body reviews, stretching compliance timelines for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tonometry Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Goldmann Applanation, Non-Contact, Tono-Pen, Dynamic Contour End User: Ophthalmology Clinics, Hospitals, Diagnostic Centers, Research Institutions Technology: Optical Coherence, Pneumatic, Mechanical, Electron Beam Application: Glaucoma Screening, Eye Pressure Monitoring, Clinical Trials, Research Studies |
| Companies Covered | Icare Finland Oy, Topcon Corporation, AMETEK Inc., Reichert Inc., Keeler Ltd., Nidek Co. Ltd., Haag-Streit Group, Accutome Inc., Tomey Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tonometry Market Strategic Shifts
Device architecture is compressing around patient-operated monitoring and integrated diagnostic platforms, with regulatory convergence and procurement centralization accelerating platform consolidation.
Portable rebound tonometers are miniaturizing spring-loaded probe mechanisms into handheld units suitable for home use. Patients with established glaucoma diagnoses in the United States and Japan acquire these devices through specialty pharmacy channels. The technology is miniaturizing clinical-grade measurement into consumer-accessible form factors that bypass traditional clinic workflows.
The EU Medical Device Regulation's Class IIa reclassification for non-contact systems tightens clinical evidence requirements for software-driven pressure algorithms. Manufacturers must generate prospective validation data that previously relied on predicate equivalence. Hospital procurement consortia in Germany and the Netherlands now demand MDR certification as a gating criterion for tender participation, filtering out legacy submissions.
Consolidated purchasing through ophthalmology group purchasing organizations concentrates device selection authority in fewer decision-makers. Independent practices in the United States affiliate with management services organizations that standardize on single-vendor platforms. California and Texas health systems negotiate enterprise pricing for multi-site tonometer fleets, displacing individualized clinic purchasing autonomy.
Tonometry Market Segmentation
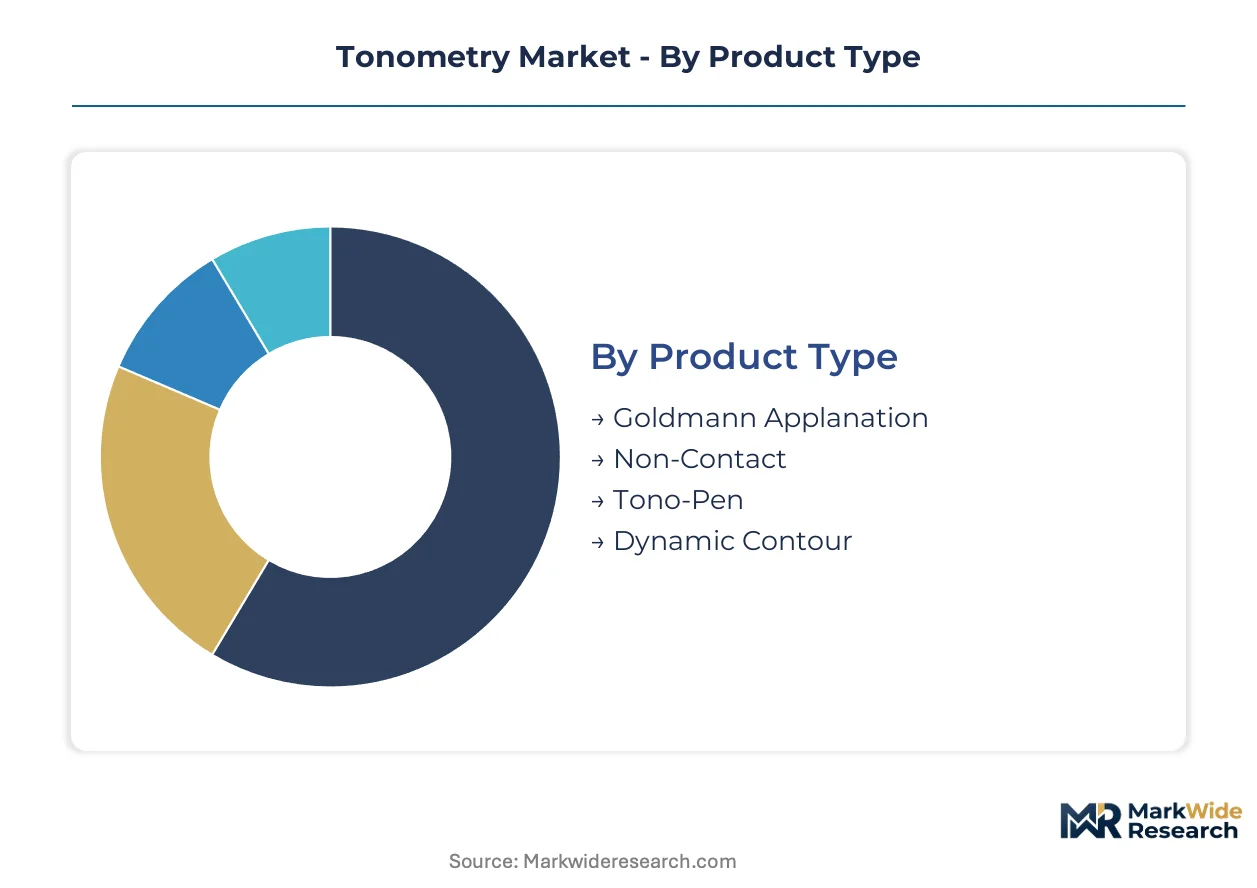
Tonometry segmentation reveals distinct procurement patterns across clinical settings. Product type determines reimbursement coding, while technology choice reflects capital availability and throughput requirements.
Product Type:
Channel distribution splits sharply between hospital systems favoring reference-standard platforms and high-volume clinics prioritizing throughput-optimized alternatives.
- Goldmann Applanation:The 3.06 mm probe diameter remains the regulatory reference standard for clinical trial correlation. Demand concentrates in academic medical centers across Germany and Japan where diagnostic protocol rigor justifies anesthesia requirements and specialized technician training.
- Non-Contact:Pneumatic air-puff systems eliminate corneal contact and cross-contamination protocols. Ophthalmology clinics in the United States deploy these for population screening programs where patient throughput drives equipment selection.
- Tono-Pen:Portable applanation devices serve bedside and emergency settings where Goldmann table mounting proves impractical.
- Dynamic Contour:Continuous pressure monitoring systems remain concentrated in research institutions where longitudinal data collection justifies capital intensity.
By volume, Non-Contact leads. By growth pace, Dynamic Contour is expanding most quickly.
End User:
Customer type shapes pricing tolerance and replacement cycle length, with procurement authority concentrating in integrated delivery networks.
- Ophthalmology Clinics:Independent and group-affiliated practices drive non-contact device procurement for routine glaucoma screening. California and Texas health systems negotiate enterprise pricing for multi-site fleets, displacing individualized purchasing autonomy.
- Hospitals:Academic medical centers maintain Goldmann platforms for resident training and clinical trial eligibility. Japan's PMDA electromagnetic standards force redesign cycles for Asian market entry.
- Diagnostic Centers:High-throughput screening facilities prioritize pneumatic systems with automated alignment.
- Research Institutions:Continuous monitoring protocols justify dynamic contour capital expenditure.
Ophthalmology Clinics command the largest installed base. Hospitals generate the highest revenue per unit.
Technology:
Technology selection tracks the trade-off between measurement precision and operational simplicity, with regulatory pathways diverging by classification.
- Optical Coherence:Swept-source imaging integrates pressure mapping with retinal nerve fiber analysis. Hospital ophthalmology departments in Germany and the Netherlands demand MDR certification as a tender gating criterion, filtering out legacy submissions.
- Pneumatic:Air-pressure deformation systems dominate veterinary and research niches through specialized calibration. Precision air pressure sensors concentrate in East Asian contract manufacturers, exposing OEMs to logistics volatility.
- Mechanical:Spring-loaded and applanation mechanisms sustain predictable replacement cycles in established markets.
- Electron Beam:Experimental modalities remain confined to research protocols.
Pneumatic systems hold volume leadership. Optical Coherence claims the steepest expansion trajectory.
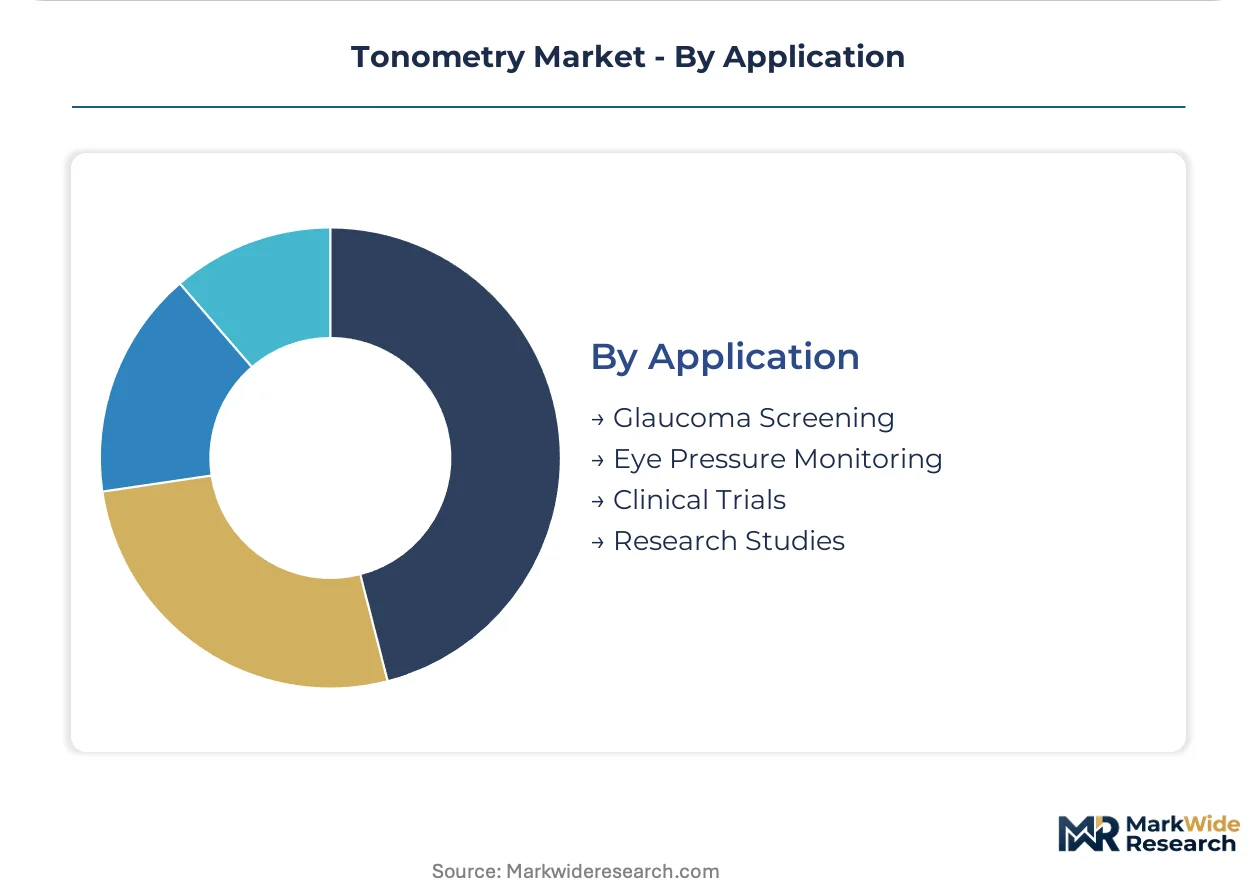
Application:
Application context determines device specification, with screening programs tolerating lower precision than treatment monitoring.
- Glaucoma Screening:Population-based detection programs in Germany's statutory health insurance system expand reimbursement for intraocular pressure monitoring, driving ambulatory device procurement.
- Eye Pressure Monitoring:Established patient management in the United States and Japan shifts toward home-based rebound tonometers acquired through specialty pharmacy channels.
- Clinical Trials:FDA submissions require Goldmann correlation data, forcing dual-platform validation costs.
- Research Studies:Continuous monitoring demands dynamic contour capabilities.
Glaucoma Screening generates the highest unit volume. Eye Pressure Monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for reference-standard Goldmann platforms while the United States drives volume through high-throughput non-contact screening networks, creating a transatlantic pricing-power asymmetry that shapes manufacturer portfolio allocation.
United States
Medicare Advantage pilots for home tonometry reimbursement are redirecting capital toward patient-operated devices. The FDA's streamlined Class II review pathways compress clearance timelines for optical coherence systems. California and Texas health systems negotiate enterprise pricing for multi-site tonometer fleets, displacing clinic-level purchasing autonomy.
Germany
Statutory health insurance funds expand reimbursement for population-based intraocular pressure monitoring, driving ambulatory procurement. The EU Medical Device Regulation's Class IIa reclassification tightens clinical evidence requirements for software-driven algorithms. Hospital procurement consortia in the Netherlands and Germany demand MDR certification as a tender gating criterion.
Japan
PMDA enforcement of JIS T 0601 electromagnetic compatibility standards forces product redesign cycles for Asian market access. The country's aging demographic accelerates glaucoma screening program maturation. Tokyo and Osaka academic medical centers maintain Goldmann platforms for resident training and clinical trial eligibility.
United Kingdom
Companion animal specialty practices adopt calibrated pneumatic systems for glaucoma screening in brachycephalic breeds. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for device certification. London and Southeast England ophthalmology group purchasing organizations concentrate device selection authority in fewer decision-makers.
France
Veterinary ophthalmology expansion in metropolitan Paris and Lyon drives niche pneumatic tonometer demand. ANSM clinical evidence requirements for Class IIa devices filter legacy submissions from tender participation. The country's statutory screening programs for diabetic retinopathy create adjacent demand for integrated pressure-mapping platforms.
Tonometry Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with optical coherence specialists commanding premium hospital contracts while pneumatic manufacturers dominate high-volume screening segments. The market structure consolidates around three tiers: integrated optical conglomerates with coherence technology lineage, specialized pneumatic designers serving veterinary and research niches, and mechanical applanation specialists sustaining predictable replacement cycles. Dominant competitive moves include strategic partnerships for electromagnetic compliance redesign and portfolio diversification into home monitoring modalities.
Within the integrated optical tier, Topcon Corporation and Nidek Co. Ltd. represent the archetype of diversified ophthalmic equipment manufacturers leveraging manufacturing scale across multiple diagnostic modalities. Reichert Inc. occupies a distinct position among pneumatic specialists, exemplifying how focused engineering capabilities can anchor defensible positions in veterinary and research sub-markets. These three companies collectively illustrate the segmentation between premium hospital contracts and high-throughput clinic procurement.
| Leading Market Players |
|---|
| Icare Finland Oy |
| Topcon Corporation |
| AMETEK Inc. |
| Reichert Inc. |
| Keeler Ltd. |
| Nidek Co. Ltd. |
| Haag-Streit Group |
| Accutome Inc. |
| Tomey Corporation |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale in swept-source laser assemblies anchors price floors for optical coherence platforms while constraining margin expansion for mid-tier pneumatic manufacturers. East Asian component concentration forces OEMs to absorb logistics volatility or redesign for dual-sourcing, compressing working capital flexibility across the supply base.
Pricing Analysis
The customization-premium spread between configured-to-order optical coherence systems and standard non-contact devices runs three-to-one in hospital procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—MDR-certified platforms command fifteen to twenty percent premiums over legacy CE-marked inventory. Price differentiation stems from electromagnetic compliance redesign costs and after-sales service bundling. Margins are tightening due to precision sensor supply constraints. Diagnostic centers exhibit highest price sensitivity; academic medical centers show lowest.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time procurement for pneumatic components and strategic stockpiling for swept-source laser sources. Manufacturing concentrates in Japan, South Korea, and Taiwan. Production draws from precision air pressure sensors, high-speed photodetectors, and applanation probe alloys. Single-source vulnerability in East Asian contract manufacturers exposes OEMs to logistics disruption. Distribution runs through ophthalmology group purchasing organizations and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for legacy Goldmann calibration creates bottleneck conditions while digital platform training capacity lags replacement demand. This capability gap concentrates margin capture among incumbents with established training infrastructure.
For Market Incumbents: Consolidate around electromagnetic compliance redesign partnerships with Japanese component suppliers to lock in PMDA pathway access. Deepen backward integration into swept-source laser sourcing to offset East Asian logistics exposure. Defend against pneumatic specialists encroaching on veterinary screening segments through calibrated companion-animal platform extensions. For New Entrants and Emerging Players: Differentiate on home-monitoring reimbursement coding expertise to capture Medicare Advantage pilot expansion. Target the United States patient-operated device segment where regulatory clarity remains nascent and incumbent positioning is weakest. Pursue specialty pharmacy channel partnerships as primary go-to-market mechanism. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pneumatic specialists with veterinary niche dominance and optical coherence platforms with hospital contract concentration. Long-term viability rests on integration capabilities spanning pressure mapping and retinal nerve fiber analysis. Acquisition targets should demonstrate JIS T 0601 compliance completion or MDR certification progress. Watch home tonometry reimbursement code finalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Hospital procurement consortia in Germany and the Netherlands mandate certification as tender prerequisite. |
| Hospital System Partnership | California and Texas health systems negotiate enterprise pricing for multi-site tonometer fleet standardization. |
| Software Companion Development | Integrated pressure mapping with retinal nerve fiber analysis consolidates diagnostic workflow in ophthalmology departments. |
| Reimbursement Strategy | Medicare Advantage pilots for remote monitoring codes redirect capital toward patient-operated modalities. |
| Strategic Partnership | Electromagnetic compliance redesign collaborations with Japanese suppliers accelerate PMDA market access. |
Study Parameters
A spread of perspectives from ophthalmology clinic administrators, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs directors converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, PMDA approval databases, EU MDR notified body certifications, and hospital procurement contract records. Bottom-up installed base estimates and top-down expenditure flows were triangulated for cross-verification.
Segmentation dimensions modeled include product type, end user category, technology platform, and application context across the analysis window. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of screening program expansion rates. Forecast inputs incorporated PMDA electromagnetic standard enforcement timelines and Medicare reimbursement coding development status.
The analysis sits within stated boundaries; outcomes outside sustained statutory insurance reimbursement for population screening or accelerated FDA clearance pathway stability would require recalibration. Forecasts reflect documented assumptions regarding technician training capacity expansion and component supply normalization. Revision becomes warranted when home tonometry reimbursement code density crosses adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Vision Care Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market